
 Asia Health Check-Ups Market | 2026-2036
Asia Health Check-Ups Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Health Check-Ups Market Analytics
Preventive care revenue is reshaping margin pools away from episodic diagnostic testing across Asia. Sonic Healthcare Limited leverages its extensive laboratory network to sustain geographic dominance in Australia and Southeast Asia. Quest Diagnostics Incorporated anchors its position through technology leadership in automated pathology workflows. LalPathLabs.com competes aggressively on brand strength and channel control within India's fragmented diagnostic landscape.
Asia health check-ups encompass scheduled clinical assessments measuring physiological parameters through blood chemistry panels, imaging modalities, and biomarker quantification to detect subclinical conditions before symptom onset. These services combine phlebotomy, radiology, and physician consultation to reduce downstream treatment costs and mortality risk. Preventive care and diagnostic testing represent the core revenue pillars, with wellness screening gaining traction among corporate purchasers seeking to lower insurance premiums. Chronic disease monitoring is accelerating fastest as diabetes and cardiovascular conditions proliferate across aging populations in China, Japan, and South Korea.
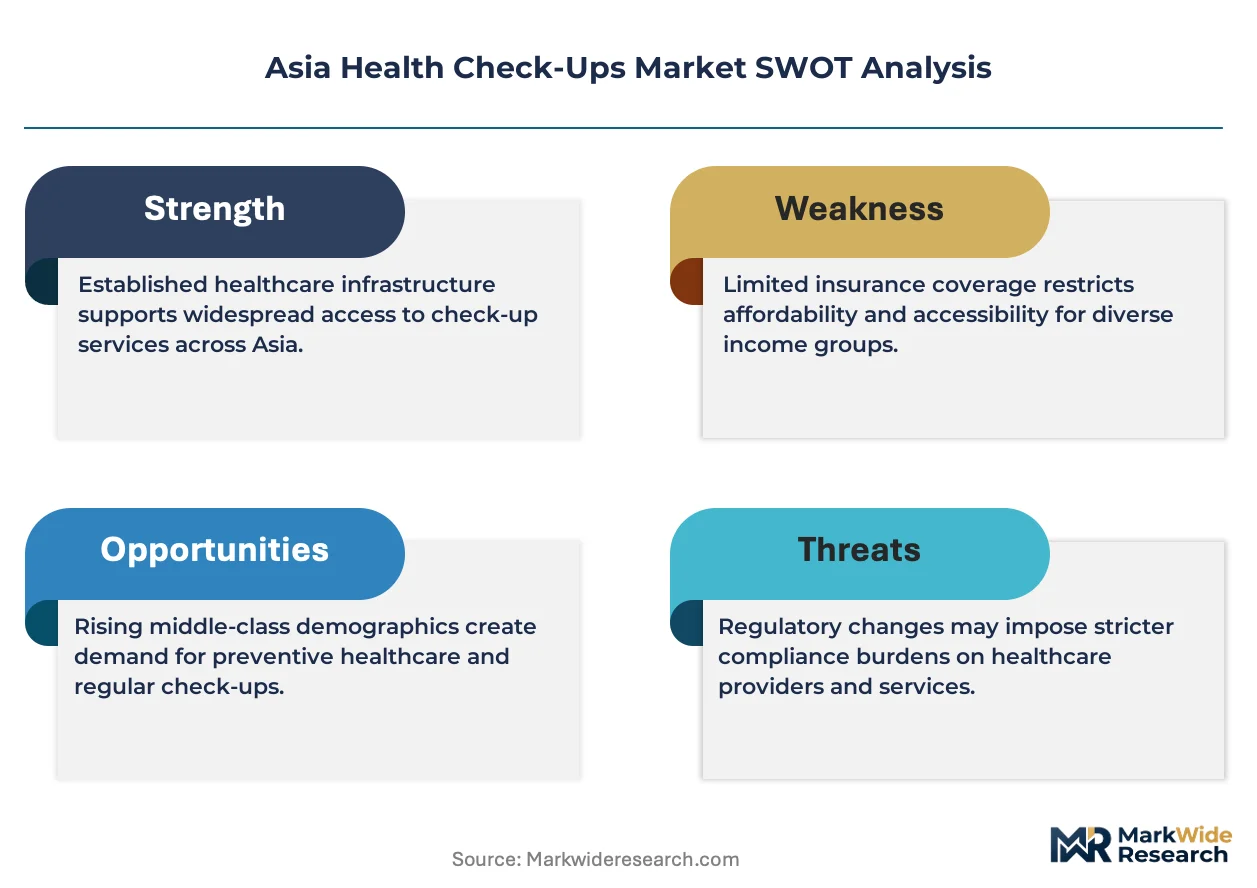
Japan's PMDA regulates in-vitro diagnostic devices used in health check-ups, while India's CDSCO governs medical device standards for screening equipment; both agencies elevate compliance costs but barrier entry for accredited providers. China's NMPA and SAMR enforce quality certification for diagnostic laboratories, directly shaping market access in the region's largest volume pool. Stakeholders must monitor regulatory convergence on data privacy for telemedicine-delivered consultations and wearable-generated biomarker streams.
Market Dynamics
Preventive health economics are restructuring Asia's diagnostic service landscape. Corporate wellness mandates and aging demographics in East Asia are compressing reimbursement cycles while elevating volume throughput requirements for accredited laboratory networks.
Growth Catalysts
- Japan's METI preventive health technology guidelines:These standards accelerate digital health platform adoption among domestic insurers. Screening providers gain preferred network status through compliance certification.
- Corporate wellness program expansion:Multinational employers across Singapore and Hong Kong are bundling annual health assessments into core benefits packages. This institutionalizes recurring revenue streams for service operators.
- Chronic disease monitoring protocols:Diabetes and cardiovascular screening regimens in South Korea's national health insurance system generate sustained demand for biomarker quantification services.
Market Restraints
- Input cost volatility in imaging equipment:MRI and CT scanner components face supply concentration in specialized semiconductor foundries. Equipment leasing costs fluctuate with import duty adjustments.
- Laboratory accreditation friction:China's NMPA quality certification requirements impose multi-year compliance timelines on new market entrants. This limits capacity expansion velocity in tier-one cities.
- Substitution by wearable biomarker devices:Consumer-grade continuous glucose monitors and blood pressure trackers reduce frequency of clinical phlebotomy visits among younger demographics.
Strategic Opportunities
- Telemedicine-integrated screening in Southeast Asia:Indonesia and Vietnam present underpenetrated demand for remote consultation follow-ups after initial health assessments. Digital infrastructure gaps are narrowing.
- India's PLI scheme for healthcare infrastructure:Domestic manufacturing incentives for diagnostic equipment reduce import dependency. Local production of screening devices lowers capital deployment barriers for regional chains.
- AI-augmented radiology workflows:Machine learning integration with PACS systems compresses image interpretation turnaround. This enables same-day report delivery that differentiates premium service tiers.
Industry Challenges
- Specialized phlebotomy workforce scarcity:Venipuncture certification programs in the Philippines and Thailand cannot match demand growth. Labor shortages constrain peak-hour throughput capacity.
- Legacy HIS integration complexity:Hospital information systems in mature markets like Japan use proprietary data formats. Interoperability gaps fragment patient record continuity across screening networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Health Check-Ups Market |
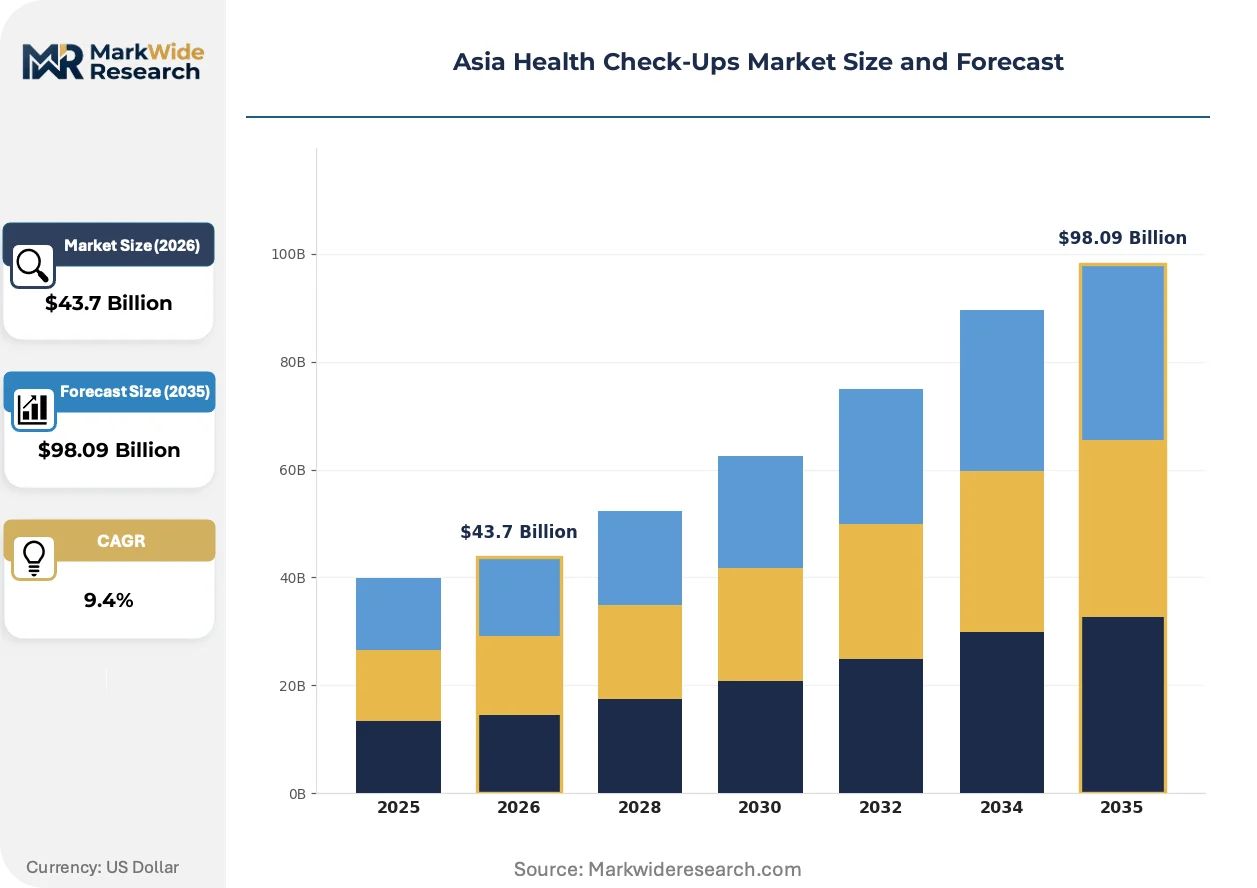
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $98.09 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Care, Diagnostic Testing, Wellness Screening, Chronic Disease Monitoring End User: Individuals, Corporations, Hospitals, Clinics Technology: Telemedicine, Wearable Devices, Lab Tests, Health Apps Delivery Mode: In-Clinic, Home Care, Mobile Units, Virtual Consultations |
| Companies Covered | Eurofins Scientific, SYNLAB International GmbH, UNILABS, OPKO Health, Inc., Sonic Healthcare Limited, Laboratory Corporation of America Holdings, Quest Diagnostics Incorporated, LalPathLabs.com, Metropolis Healthcare Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Health Check-Ups Market Evolving Landscape
Diagnostic service delivery is fragmenting across physical and virtual touchpoints. Technology convergence, regulatory digitization, and employer purchasing centralization are compressing traditional channel economics.
Artificial intelligence-assisted pathology is migrating from experimental deployment to standard-of-care protocols in high-volume screening centers. South Korean hospital networks are adopting these tools for cervical cytology and chest X-ray triage. The technology is migrating from premium urban facilities toward provincial diagnostic chains, compressing specialist labor cost structures while elevating detection sensitivity benchmarks.
China's SAMR and NMPA are harmonizing cross-border data governance rules for telemedicine-delivered consultations. This regulatory convergence enables mainland laboratories to issue reports reviewed by Hong Kong-licensed physicians. Diagnostic providers with dual-jurisdiction accreditation capture corporate wellness contracts requiring international standard documentation.
Employer procurement centralization is consolidating vendor relationships among Asia-Pacific headquarters functions. Regional benefits managers in Singapore and Shanghai are negotiating multi-country screening contracts with single-source providers. This purchasing pattern is most visible in financial services and technology sectors where talent retention metrics tie directly to wellness program participation rates.
Asia Health Check-Ups Market Segmentation
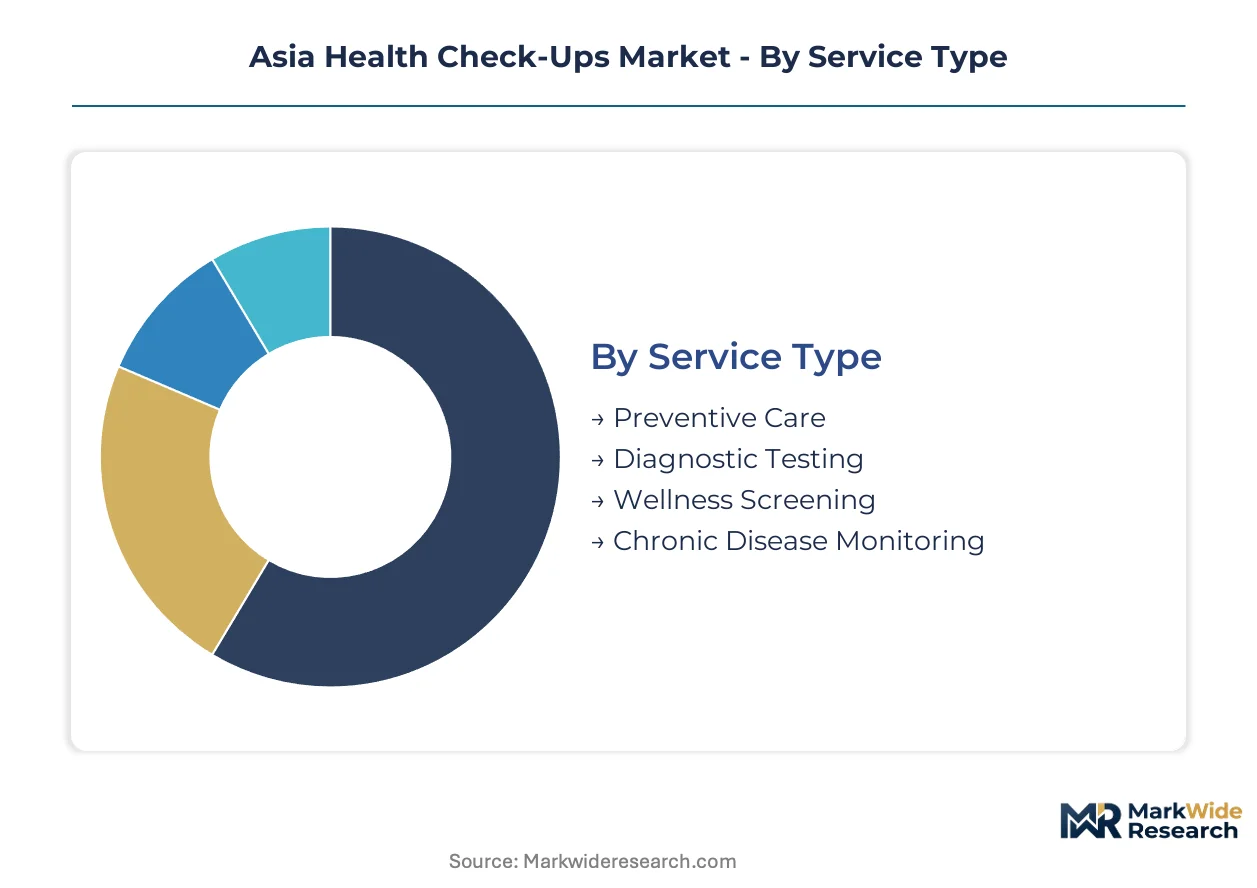
Service configuration in Asia's health check-up market determines reimbursement pathways, capital intensity, and customer acquisition economics. Segmentation reveals how preventive care economics are compressing traditional diagnostic margins while opening new volume pools across corporate and virtual channels.
Service Type:
Mature revenue streams anchor the base while emerging protocols reshape growth trajectories across the region.
- Preventive Care:Scheduled assessments combining phlebotomy, imaging, and physician consultation to intercept subclinical conditions. China's tier-one cities concentrate demand as aging demographics and employer wellness mandates converge in Shanghai, Beijing, and Shenzhen.
- Diagnostic Testing:Episodic laboratory panels and radiology services triggered by symptom presentation or physician referral. India's fragmented diagnostic landscape drives price competition, with CDSCO-accredited laboratories commanding premium positioning in metro corridors.
- Wellness Screening:Lifestyle-focused assessments targeting metabolic and cardiovascular risk factors.
- Chronic Disease Monitoring:Protocol-driven biomarker tracking for diabetes and cardiovascular conditions.
Preventive care handles the majority of throughput; chronic disease monitoring is gaining share fastest as national insurance systems in South Korea and Japan expand coverage.
End User:
Customer type determines pricing power, contract duration, and service bundling complexity across the value chain.
- Corporations:Multinational employers in Singapore and Hong Kong institutionalize annual health assessments as core benefits. Procurement centralization at Asia-Pacific headquarters functions compresses vendor relationships toward single-source regional contracts.
- Individuals:Out-of-pocket purchasers seeking discrete screening packages or comprehensive health profiles. Japan's METI preventive health guidelines elevate quality expectations and compliance costs for direct-to-consumer positioning.
- Hospitals:Integrated health systems capturing referral flows and captive diagnostic volume.
- Clinics:Independent and chain-affiliated facilities serving neighborhood catchment areas.
Corporations lock in the longest contract cycles; individuals deliver the highest margin per encounter but fragment across price tiers.
Technology:
Technology stack selection separates capital-light digital entrants from infrastructure-heavy incumbents competing on throughput.
- Lab Tests:Blood chemistry panels, histopathology, and molecular diagnostics requiring phlebotomy infrastructure and NMPA-certified equipment. Sonic Healthcare Limited sustains dominance through geographic density of collection centers across Australia and Southeast Asia.
- Telemedicine:Remote consultation platforms enabling report delivery and physician follow-up without physical facility requirements. China's SAMR and NMPA harmonization of cross-border data rules permits mainland laboratories to leverage Hong Kong-licensed physicians for international standard documentation.
- Wearable Devices:Consumer-grade continuous monitoring for glucose, blood pressure, and activity metrics.
- Health Apps:Software interfaces for appointment scheduling, result access, and lifestyle coaching.
Lab tests absorb the largest capital deployment; telemedicine is climbing the fastest as digital infrastructure gaps narrow in Indonesia and Vietnam.
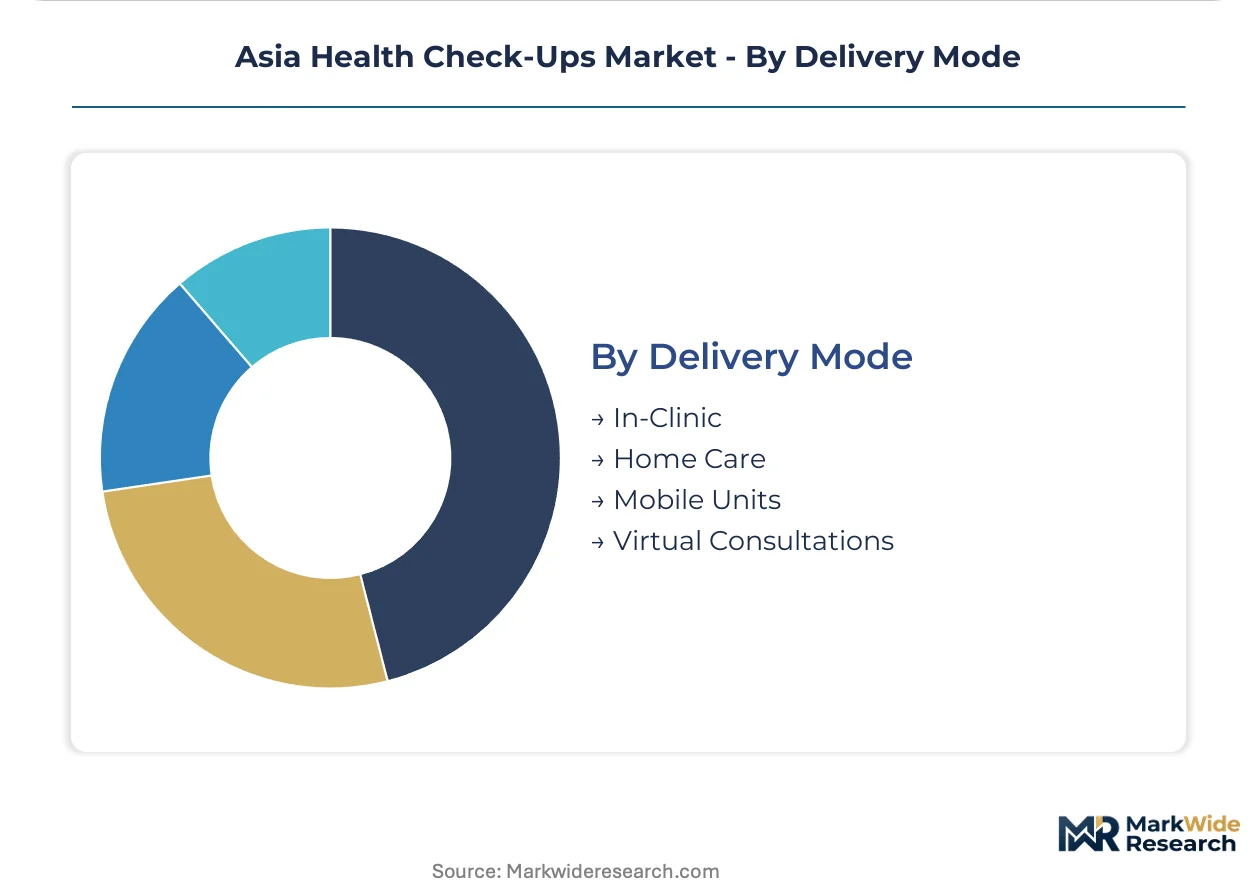
Delivery Mode:
Physical versus virtual touchpoint strategy shapes customer acquisition costs and service differentiation in contested urban markets.
- In-Clinic:Fixed-site facilities with full imaging and laboratory capabilities. China's NMPA quality certification requirements impose multi-year compliance timelines that constrain new entrant velocity in tier-one cities, entrenching incumbent networks.
- Mobile Units:Deployable screening vehicles bringing phlebotomy and basic imaging to corporate campuses and underserved districts. India's PLI scheme for healthcare infrastructure reduces equipment import dependency, lowering capital barriers for regional chain expansion.
- Home Care:Nurse-deployed sample collection and portable diagnostic services.
- Virtual Consultations:AI-triaged symptom assessment and remote physician interaction without physical presence.
In-Clinic retains the highest average revenue per encounter; mobile units are expanding most quickly as employers prioritize on-site convenience and workforce participation rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments across Asia's health check-up landscape. India's out-of-pocket purchasers drive fierce competition on package pricing, while Japan's corporate buyers prioritize compliance certification over cost. China's tier-one cities exhibit mixed elasticity, with premium segments absorbing price premiums for same-day reporting.
China
Shanghai, Beijing, and Shenzhen concentrate demand as aging demographics collide with employer wellness mandates. NMPA quality certification requirements impose multi-year compliance timelines that entrench incumbent laboratory networks. The Yangtze River Delta anchors the highest throughput screening centers, where AI-augmented radiology workflows compress report delivery to same-day service.
Japan
Corporate wellness program expansion institutionalizes annual health assessments as core employee benefits. METI preventive health technology guidelines accelerate digital health platform adoption among domestic insurers. The Kanto region around Tokyo hosts the densest concentration of accredited screening facilities, where PMDA-regulated in-vitro diagnostic devices elevate quality benchmarks.
India
Fragmented diagnostic landscapes in Mumbai, Delhi, and Bangalore drive price competition on routine panel pricing. CDSCO medical device standards for screening equipment create compliance costs that favor accredited regional chains. The PLI scheme for healthcare infrastructure reduces import dependency on diagnostic equipment, lowering capital barriers for domestic manufacturing.
South Korea
National health insurance system coverage for diabetes and cardiovascular screening regimens generates sustained biomarker quantification demand. MFDS regulatory frameworks govern medical device deployment in preventive care settings. The Seoul Capital Area concentrates the highest per-capita screening frequency as chronic disease monitoring protocols expand reimbursement eligibility.
Singapore
Multinational employer procurement centralization at Asia-Pacific headquarters functions compresses vendor relationships toward single-source regional contracts. The country's national pharmaceutical regulator enforces quality standards that align with international documentation requirements. The city-state's financial services and technology sectors tie talent retention metrics directly to wellness program participation rates.
Asia Health Check-Ups Market Competitive Landscape
Capability concentration sits with accredited laboratory networks possessing multi-jurisdiction quality certifications; scale advantage sits with geographic footprint density across tier-one urban corridors. Market structure exhibits tiered consolidation, with pan-Asian chains commanding corporate contracts while independent facilities fragment individual purchaser segments. Three archetypes dominate: technology-integrated platforms, compliance-certified regional networks, and price-competitive metro specialists. M&A activity targets laboratory network density; strategic partnerships bridge telemedicine platforms with physical collection infrastructure.
Among laboratory network operators, Sonic Healthcare Limited exemplifies geographic dominance through collection center density across Australia and Southeast Asia. Quest Diagnostics Incorporated occupies a position representing technology leadership in automated pathology workflows. LalPathLabs.com sits within the tier of brand-intensive competitors navigating India's fragmented diagnostic landscape through channel control and metro corridor penetration.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SYNLAB International GmbH |
| UNILABS |
| OPKO Health, Inc. |
| Sonic Healthcare Limited |
| Laboratory Corporation of America Holdings |
| Quest Diagnostics Incorporated |
| LalPathLabs.com |
| Metropolis Healthcare Ltd. |
| Others |
Value Network & Pricing Analysis
Specialized semiconductor foundries in Taiwan and South Korea concentrate production of MRI and CT scanner components, anchoring margin pools in equipment leasing tiers where import duty fluctuations pass through to diagnostic service pricing. This upstream concentration elevates capital deployment barriers for screening networks while compressing reimbursement cycles for episodic testing.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value for imaging equipment lessors, with three-tier pricing structure across premium, standard, and economy levels separating NMPA-certified laboratories from uncertified competitors. Price differentiation rests on accreditation grade and geographic delivery cost, with corporate wellness purchasers in Singapore and Hong Kong exhibiting lowest sensitivity while India's out-of-pocket individual buyers drive fierce routine panel competition. Cost compression in economy-tier screening packages is intensifying because of CDSCO compliance cost spreading across lower volumes.
Supply Chain Analysis
Supplier-financing facilities from Japanese equipment manufacturers extend payment terms for diagnostic chains, easing working capital pressure on NMPA certification timelines. Geographic supply concentrates in Japan, Germany, and the United States for high-field MRI magnets, contrast agents, and automated pathology workstations. Raw material dependencies span rare earth elements for magnet fabrication, iodinated contrast media, and specialized reagents for biomarker quantification. Single-source vulnerability in semiconductor foundry capacity for gradient amplifier chips threatens equipment delivery schedules. Distribution runs through manufacturer-direct sales for tier-one cities and regional distributor networks for provincial expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia's health check-up market functions as a service-attach opportunity where chronic disease monitoring protocols and corporate wellness program subscriptions expand faster than hardware depreciation cycles. Recurring revenue from biomarker tracking regimens now exceeds one-time diagnostic panel economics.
For Market Incumbents: Build accreditation moats through dual-jurisdiction NMPA and SAMR quality certifications that lock in corporate wellness contracts requiring international standard documentation. Sonic Healthcare Limited exemplifies geographic density defense across Australia and Southeast Asia collection centers. Capacity addition in China's tier-one cities faces multi-year compliance timelines that entrench first-mover networks. Channel control through hospital information system integration fragments patient record continuity for competitors. For New Entrants and Emerging Players: Build out telemedicine-integrated screening platforms in Indonesia and Vietnam where digital infrastructure gaps are narrowing fastest. White-space targets include remote consultation follow-ups after initial health assessments and mobile unit deployment for corporate campus convenience. The most penetrable segment sits in mid-sized employers seeking single-source regional contracts without incumbent switching costs. Go-to-market leverage rests on AI-augmented radiology workflows promising same-day report delivery differentiation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional laboratory chains possessing metro corridor density but lacking multi-country accreditation. Long-term viability favors platforms integrating physical collection infrastructure with virtual consultation capabilities over pure equipment lessors. Acquisition target archetypes include CDSCO-accredited Indian diagnostic networks and Southeast Asian mobile screening operators. Watch for NMPA harmonization with Hong Kong data governance rules as inflection indicator for cross-border service scalability.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Radiology Workflow Deployment | Machine learning integration with PACS systems compresses image interpretation turnaround for same-day premium service tiers. |
| Dual-Jurisdiction Accreditation Investment | NMPA and SAMR quality certification plus Hong Kong physician licensing unlocks corporate wellness contract eligibility. |
| Mobile Screening Unit Fleet Expansion | Deployable phlebotomy and basic imaging vehicles capture employer on-site convenience mandates across tier-two cities. |
| Telemedicine Platform Integration | Remote consultation follow-ups after initial assessments penetrate underpenetrated demand in Indonesia and Vietnam. |
| Chronic Disease Monitoring Protocol Development | Biomarker tracking regimens for diabetes and cardiovascular conditions align with South Korean national insurance reimbursement expansion. |
Research Methodology
The analysis maps preventive care, diagnostic testing, wellness screening, and chronic disease monitoring segments, each validated through hospital procurement managers, GPO contracts managers, biomedical engineers, and corporate benefits directors. Primary interviews with laboratory network operators and secondary validation through NMPA filings, CDSCO medical device registrations, hospital procurement databases, and METI preventive health guideline documents anchor the foundation. Bottom-up volume modeling and top-down macroeconomic triangulation reconcile segment-level outputs.
Assumptions held fixed include regulatory certification timelines, corporate wellness program penetration rates, and chronic disease prevalence trajectories; variables stress-tested span import duty adjustments, semiconductor foundry capacity constraints, and telemedicine reimbursement policy shifts. The analytical framework operates across the analysis window with segmentation dimensions covering service type, end user, technology stack, and delivery mode. CAGRs derive from historical throughput growth rates applied to projected accreditation expansion and employer procurement centralization patterns. Forecast inputs incorporate AI adoption curves in radiology workflows and PLI scheme equipment localization timelines.
Stress conditions across tariff exposure, phlebotomy workforce scarcity, and wearable substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory convergence and technology adoption thresholds. Macroeconomic contraction, regulatory fragmentation, or disruptive biomarker monitoring breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Tongue Scraper Market
Personal Health
Hair Restoration Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Sleep Mask Market
Personal Health
Patient Health Management Market
Personal Health
Skin Tag Remover Market
Personal Health
Maternity and Personal Care Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
Biohacking Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Workplace Wellness Market
Personal Health
Feminine Hygiene Market
Personal Health
Disposable Underwear Market
Personal Health
OTC Health Products Market
Personal Health
Global OTC Hair Loss Treatment Market