
 Earwax Removal Products Market | 2026-2036
Earwax Removal Products Market Size, Share, and Industry Trends Forecast 2026-2036
Earwax Removal Products Market Intelligence
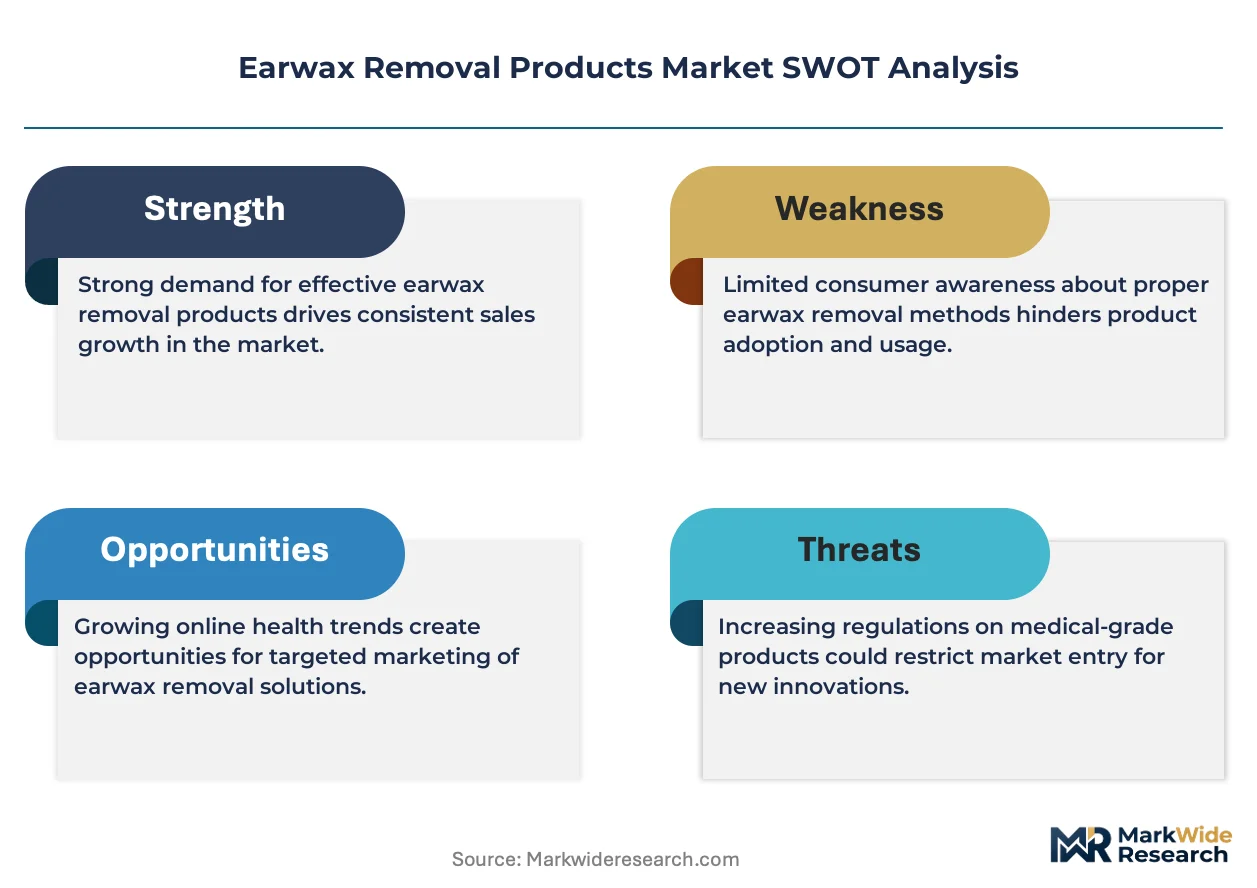
The gap between premium automated devices and commodity cotton swabs is repositioning how manufacturers allocate R&D budgets. Johnson & Johnson leverages its consumer health infrastructure to sustain shelf presence across drugstore chains. NeilMed Pharmaceuticals anchors its position through specialized irrigation technology. Eosera Inc differentiates via biotechnology-driven formulations targeting sensitive ear canal conditions.
Earwax removal products encompass devices, formulations, and implements designed to dissolve, flush, or mechanically extract cerumen from the external auditory canal, typically operating at body-safe temperatures and pH-balanced chemistries to prevent tympanic membrane irritation. These products serve both clinical otology workflows and direct-to-consumer home hygiene routines. Ear drops and water-based solutions capture the largest volume pools due to repeat purchase frequency, while automated devices represent the fastest-expanding margin segment as consumers trade up from manual tools. Online retail channels are restructuring distribution economics by disintermediating traditional pharmacy networks.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern device safety claims and biocompatibility testing for ear irrigation systems and electronic removal tools. The EPA regulates antimicrobial additives in essential oil formulations, constraining preservative choices for manufacturers targeting the United States. Stakeholders must monitor how harmonization between FDA and EMA otologic device standards reshapes product development roadmaps and market access timelines.
Market Dynamics
The migration from manual cotton swabs to powered irrigation systems and biotech-formulated drops is restructuring manufacturer R&D allocation and retail shelf economics across pharmacy and e-commerce channels.
Growth Catalysts
- Aging residential populations:Home care adoption accelerates among seniors managing self-administered ear hygiene without clinical visits. Germany and Japan lead this demographic transition.
- FDA 510(k) pathway maturation:Clearance frameworks for otologic devices now provide predictable timelines for irrigation system commercialization, attracting venture investment into automated tools.
- Biotechnology formulation advances:Enzyme-based cerumenolytics are replacing mineral oil and hydrogen peroxide solutions, commanding premium pricing in sensitive canal segments.
Market Restraints
- Raw material concentration:Medical-grade silicone for ear bulb syringes concentrates among East Asian compounders, exposing manufacturers to input volatility and logistics friction.
- CE marking under EU MDR:Biocompatibility testing requirements for electronic removal tools have extended certification timelines by 8-14 months, freezing product launches.
- Substitute availability:Low-cost mineral oil and warm water home remedies continue capturing price-sensitive consumers, compressing volume for formulated drops.
Strategic Opportunities
- Direct-to-consumer telehealth bundling:Virtual ENT consultations paired with prescribed irrigation devices create subscription revenue streams in the United States.
- EPA antimicrobial additive waivers:Essential oil preservative pathways for cerumenolytics are opening under revised environmental toxicity thresholds.
- India pharmacy modernization:Organized retail chains in Mumbai and Bangalore are establishing dedicated otologic care sections, displacing unorganized chemist counters.
Industry Challenges
- Audiologist training bottlenecks:Proper irrigation technique certification for retail pharmacy staff remains uneven, elevating liability exposure for device manufacturers.
- Legacy cotton swab infrastructure:Existing supply chains optimized for commodity swabs resist retooling for automated systems, creating working capital strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earwax Removal Products Market |
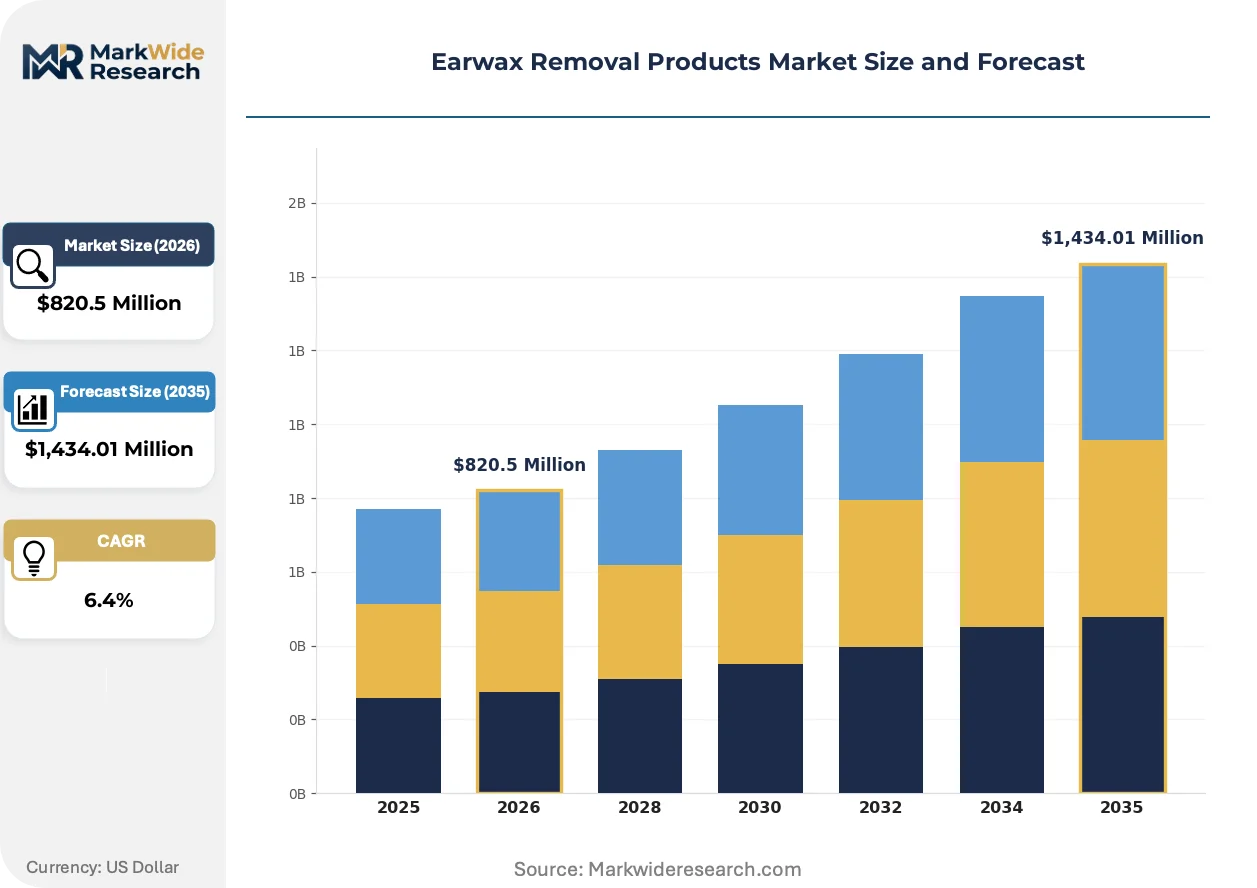
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,434.01 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ear Drops, Ear Irrigation Kits, Ear Candles, Cotton Swabs End User: Households, Clinics, Hospitals, Pharmacies Technology: Manual Tools, Automated Devices, Essential Oil Formulations, Water-based Solutions Distribution Channel: Online Retail, Supermarkets, Drugstores, Specialty Stores |
| Companies Covered | Johnson & Johnson, Bausch Health, GlaxoSmithKline, NeilMed Pharmaceuticals, Eosera Inc, Church & Dwight, Medline Industries, Cardinal Health, Prestige Consumers Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earwax Removal Products Market Strategic Shifts & Innovations
Product development trajectories are diverging between premium electromechanical systems and biotechnology-enhanced formulations, each demanding distinct regulatory navigation and manufacturing competencies.
Micro-suction technology is automating cerumen extraction through precision vacuum pressure modulation and integrated otoscope visualization. ENT clinics in the United States and Germany are adopting these systems to reduce procedure time and tympanic membrane trauma incidents. The technology is automating technician-dependent steps, compressing labor costs while elevating reimbursement coding complexity.
EU MDR biocompatibility testing expansions are requiring manufacturers to submit cytotoxicity and sensitization data for all materials contacting the ear canal. Irrigation system producers face reformulation of polymer components and extended notified body review queues. Electronic removal tools with Bluetooth connectivity encounter additional cybersecurity documentation under MDR Annex I requirements.
Subscription-based replenishment models are displacing single-transaction pharmacy purchases for cerumenolytic drops. Amazon and specialized telehealth platforms capture recurring revenue through automated shipping algorithms calibrated to usage patterns. This behavioral shift concentrates most visibly in the United States, where direct-to-consumer health product infrastructure supports seamless payment and fulfillment integration.
Earwax Removal Products Market Segmentation
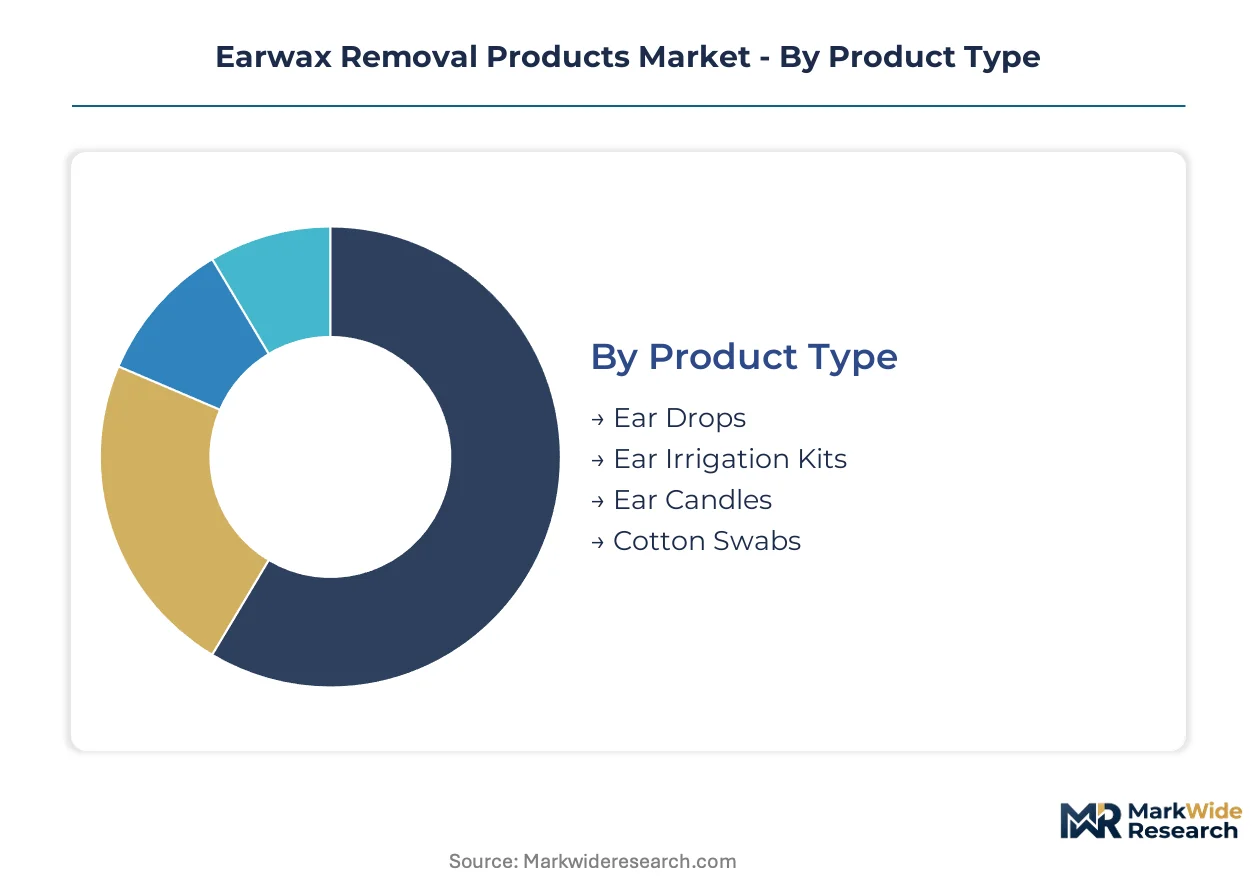
Earwax removal products fragment across four distinct taxonomies that reshape how manufacturers configure supply chains and how retailers allocate shelf space. Product type determines material sourcing and regulatory pathway complexity. End user segmentation governs pricing power and reimbursement access. Technology and distribution channel classifications increasingly overlap as direct-to-consumer automated devices bypass traditional pharmacy networks.
Product Type:
Customization intensity varies sharply across this category, from commodity cotton swabs to precision-formulated biotechnology drops requiring batch-specific stability testing.
- Ear Drops:Cerumenolytic formulations dissolve impacted wax through enzymatic or surfactant action, typically packaged in 10-15ml amber glass or HDPE containers with controlled-dropper closures. Demand concentrates among aging residential populations in Germany and Japan where self-administered regimens reduce ENT clinic visits; FDA and CE marking requirements for otologic formulations constrain preservative selection and shelf-life claims.
- Ear Irrigation Kits:Bulb syringes and electric pump systems deliver body-temperature water or saline at controlled pressure thresholds below 15 psi to prevent tympanic membrane trauma. Hospital procurement in the United States favors single-patient-use disposable tips to eliminate cross-contamination liability; home care adoption accelerates through telehealth bundling with virtual ENT consultations.
- Ear Candles:Hollow fabric cones impregnated with beeswax or paraffin claim thermal convection effects for wax removal, though clinical efficacy remains disputed and regulatory scrutiny has intensified in multiple jurisdictions.
- Cotton Swabs:Paper or plastic shafts with bleached cotton tips dominate unit volume through impulse purchases at supermarket checkout lanes, though safety labeling warnings against canal insertion have compressed growth in regulated markets.
Most installed capacity flows through cotton swabs. Expansion is steepest in ear irrigation kits.
End User:
Volume concentration tilts toward residential settings, while margin capture concentrates in clinical environments where professional liability standards justify premium device specifications.
- Households:Direct-to-consumer purchases through Amazon and pharmacy chains dominate repeat-buy economics for drops and manual tools; subscription replenishment algorithms now calibrate shipping intervals to usage patterns detected through connected device telemetry.
- Clinics:Outpatient ENT and audiology practices in the United States drive adoption of micro-suction systems with integrated otoscope visualization, compressing procedure time while elevating reimbursement coding precision.
- Hospitals:Operating room and emergency department procurement prioritizes single-use irrigation components to eliminate sterilization workflow overhead; group purchasing organizations consolidate vendor selection across health system networks.
- Pharmacies:Retail chains in Mumbai and Bangalore are establishing dedicated otologic care sections, displacing unorganized chemist counters and creating branded shelf space for formulated drops and irrigation devices.
Households absorb the highest unit volumes. Clinics deliver the steepest margin expansion.
Technology:
Patent protection intensity separates mature manual implements from emerging electromechanical systems and biotechnology-enhanced formulations.
- Manual Tools:Curettes, loops, and bulb syringes manufactured from medical-grade polymers or stainless steel require minimal regulatory documentation but face price compression from commodity Asian suppliers.
- Automated Devices:Electric irrigation pumps and micro-suction systems with Bluetooth connectivity for pressure monitoring encounter extended EU MDR certification timelines due to biocompatibility and cybersecurity documentation requirements.
- Essential Oil Formulations:Tea tree, eucalyptus, and almond oil blends with claimed antimicrobial properties face EPA additive restrictions in the United States, though revised environmental toxicity thresholds are opening preservative pathways.
- Water-based Solutions:Saline and sterile water formulations for irrigation systems offer the lowest material cost structure but commoditize rapidly without proprietary delivery mechanism differentiation.
Manual tools retain the largest installed base. Automated devices are climbing the fastest.
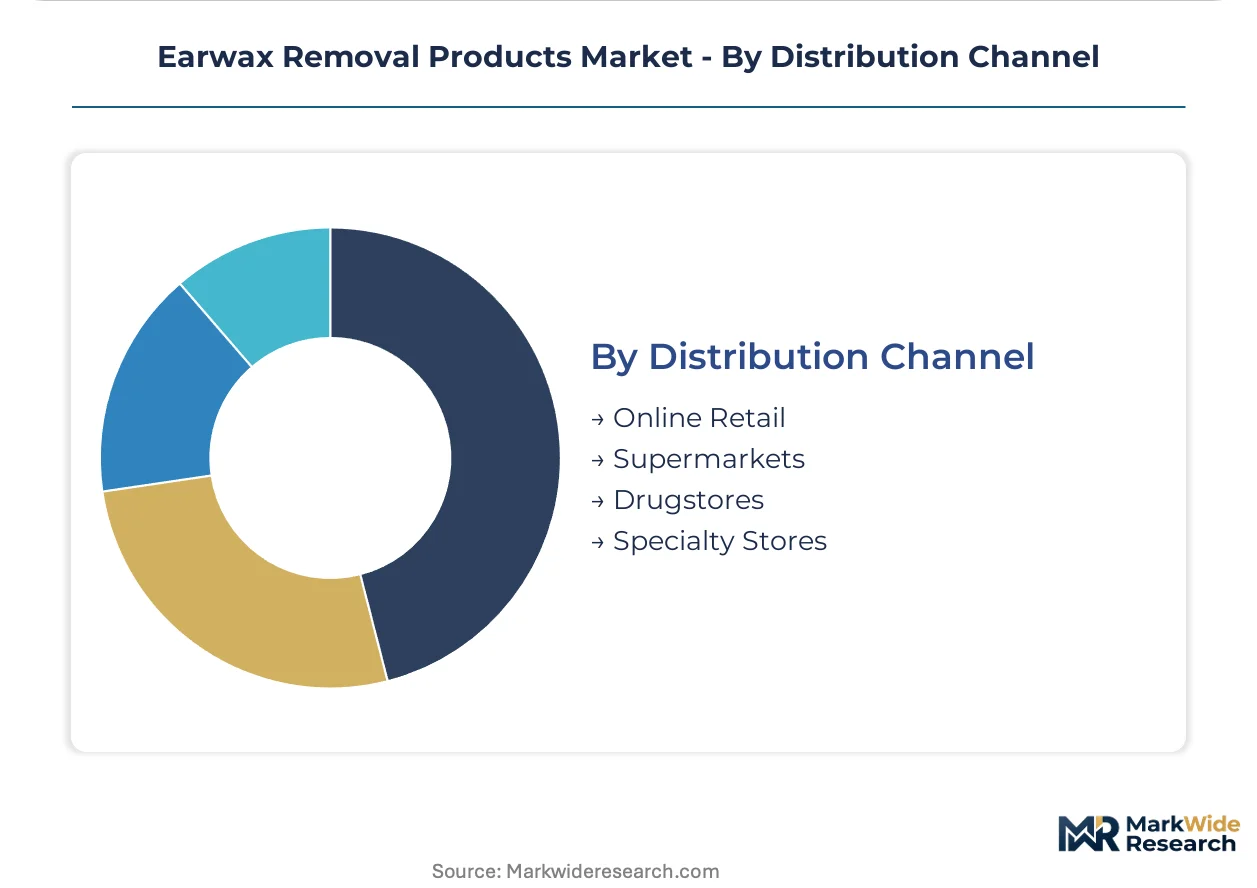
Distribution Channel:
Channel selection determines working capital requirements and customer acquisition cost structures, with e-commerce disintermediating traditional pharmacy networks most aggressively in the United States.
- Online Retail:Amazon and specialized telehealth platforms capture recurring revenue through automated replenishment algorithms; search engine optimization for cerumenolytic keywords drives customer acquisition economics.
- Supermarkets:Impulse placement at checkout lanes sustains cotton swab volume; limited shelf depth constrains irrigation kit assortment to basic bulb syringe configurations.
- Drugstores:CVS and Walgreens leverage pharmacist consultation to steer customers toward formulated drops and away from contraindicated cotton swab use; shelf resets prioritize subscription-compatible SKUs.
- Specialty Stores:Hearing aid retailers and audiology clinics bundle irrigation devices with maintenance service contracts, capturing lifetime value through repeat accessory purchases.
Drugstores process the highest transaction frequency. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacist and audiology technician concentrations in developed economies anchor geographic demand patterns for earwax removal products, with regulatory sophistication and direct-to-consumer infrastructure determining market depth.
United States
Direct-to-consumer telehealth bundling accelerates home irrigation device adoption among Medicare-eligible populations. FDA 510(k) clearance pathways for otologic devices provide predictable commercialization timelines, attracting venture investment into automated tools. Amazon's Seattle headquarters and pharmacy distribution hubs in Phoenix and Dallas-Fort Worth drive subscription replenishment algorithm deployment for cerumenolytic drops.
Germany
Aging residential populations in Bavaria and North Rhine-Westphalia expand self-administered ear hygiene without clinical visits. CE marking under EU MDR governs device safety claims, with biocompatibility testing requirements extending certification timelines for electronic removal tools. ENT clinic clusters in Munich and Hamburg adopt micro-suction systems to reduce procedure time and tympanic membrane trauma incidents.
Japan
Home care adoption accelerates among seniors managing ear hygiene independently in Tokyo and Osaka metropolitan corridors. PMDA pharmaceutical regulations constrain preservative selection for cerumenolytic formulations. METI industrial policy supports domestic manufacturing of precision polymer components for irrigation systems in Nagoya's medical device cluster.
India
Organized retail pharmacy chains in Mumbai and Bangalore establish dedicated otologic care sections, displacing unorganized chemist counters. CDSCO medical device regulations tighten material safety standards for imported irrigation kits. Domestic cotton swab manufacturers in Gujarat and Tamil Nadu retool capacity toward bulb syringe production to capture rising home care demand.
United Kingdom
Audiologist training bottlenecks for irrigation technique certification create uneven retail pharmacy staff competency across NHS trusts. MHRA post-Brexit regulatory divergence from EU MDR extends market access timelines for automated devices. London-based telehealth platforms bundle virtual ENT consultations with prescribed irrigation devices, creating subscription revenue streams.
Earwax Removal Products Market Key Industry Players
Top-tier vendors anchor consumer health infrastructure, while specialized otologic device manufacturers and regional pharmaceutical suppliers occupy mid-tier positions. The market exhibits moderate consolidation with multinational health conglomerates controlling pharmacy shelf access and biotechnology specialists capturing premium formulation segments. Two strategic archetypes dominate: diversified consumer health conglomerates leveraging distribution scale, and focused otologic specialists commanding R&D intensity in irrigation technology. Competitive moves concentrate on strategic partnerships with telehealth platforms and portfolio diversification into subscription-compatible device-plus-consumable systems.
Among diversified consumer health conglomerates, Johnson & Johnson and GlaxoSmithKline occupy positions exemplifying pharmacy chain penetration and regulatory navigation capabilities. NeilMed Pharmaceuticals and Eosera Inc represent the specialized otologic tier, with the former anchoring irrigation technology expertise and the latter exemplifying biotechnology-driven formulation approaches. These four entities collectively illustrate the competitive tension between scale-driven distribution economics and innovation-focused segment capture.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Bausch Health |
| GlaxoSmithKline |
| NeilMed Pharmaceuticals |
| Eosera Inc |
| Church & Dwight |
| Medline Industries |
| Cardinal Health |
| Prestige Consumers Healthcare |
| Others |
Cost & Logistics Intelligence
Captive polymer compounding in East Asian medical-grade silicone facilities anchors both supply security and margin capture for irrigation device manufacturers serving FDA and CE marking pathways. This backward integration into specialty material production insulates premium tier producers from commodity volatility while forcing mid-tier competitors toward spot-market sourcing that compresses pricing power.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription-based device-plus-consumable systems from transactional single-purchase economics. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with FDA 510(k) cleared automated devices commanding the widest spreads. Cost compression in the manual tools tier is intensifying because commodity Asian suppliers flood pharmacy channels with unbranded bulb syringes. Household direct-to-consumer segments exhibit highest price sensitivity, while hospital procurement through group purchasing organizations demonstrates lowest sensitivity due to liability-driven quality mandates.
Supply Chain Analysis
Reverse-logistics flows for automated irrigation devices remain underdeveloped, with warranty returns and refurbishment programs concentrated among premium manufacturers in the United States and Germany. Medical-grade silicone compounding draws from Japan, South Korea, and China, while precision polymer component machining rests on Nagoya's medical device cluster and Bavarian precision tooling networks. Single-source vulnerability in East Asian silicone supply creates exposure to logistics chokepoints through Shanghai and Busan port congestion. Distribution runs through Amazon fulfillment centers and pharmacy chain regional distribution hubs, with direct-to-consumer telemetry enabling predictive replenishment algorithms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play where EU MDR certification timelines extending 8-14 months create cost and speed-to-market advantages for manufacturers prioritizing FDA 510(k) pathways in the United States.
For Market Incumbents: To counter substitute pressure from mineral oil home remedies, Johnson & Johnson and NeilMed Pharmaceuticals should deepen backward integration into medical-grade silicone compounding and lock exclusive pharmacy chain shelf-reset agreements for subscription-compatible SKUs. Certification investment in dual FDA-CE marking capacity insulates against regulatory divergence. For New Entrants and Emerging Players: Launch via Amazon Marketplace direct-to-consumer models with telehealth bundling partnerships to bypass entrenched pharmacy distribution. The most penetrable white-space sits in India organized retail pharmacy modernization, where dedicated otologic care sections in Mumbai and Bangalore chains displace unorganized chemist counters. Target biotechnology-driven cerumenolytic formulations for sensitive canal segments underserved by commodity hydrogen peroxide solutions. For Investors and Strategic Acquirers: Roll-up economics work for specialized otologic device manufacturers because fragmented regional players lack the capital intensity to navigate simultaneous FDA 510(k) and EU MDR certification queues. Long-term viability centers on five-to-ten year subscription revenue compounding from connected device telemetry. The signal to watch is telehealth platform partnership density as an inflection indicator for home care adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Partnership | Virtual ENT consultations bundled with prescribed irrigation devices capture recurring subscription revenue in United States Medicare-eligible populations. |
| Biotechnology Formulation Development | Enzyme-based cerumenolytics replace mineral oil solutions, commanding premium pricing in sensitive ear canal segments across Germany and Japan. |
| Dual Certification Investment | Simultaneous FDA 510(k) and EU MDR pathways hedge against regulatory divergence extending market access timelines for electronic removal tools. |
| Direct-to-Consumer Channel Expansion | Amazon and specialized telehealth platforms disintermediate traditional pharmacy networks through automated replenishment algorithms calibrated to usage telemetry. |
| Backward Integration into Polymer Compounding | Captive medical-grade silicone production insulates irrigation device manufacturers from East Asian supply volatility and logistics friction. |
Research Approach
Bottom-up household and clinic demand modeling reconciled against top-down manufacturing capacity and import-export tracking forms the analytical core of this study. Primary interviews with ENT clinicians, hospital purchasing committee members, biomedical engineers, and group purchasing organization contract managers combined with secondary validation against FDA 510(k) filings, CDSCO medical device registrations, EMA submission databases, and pharmacy retail audit data. Triangulation between consumption-side telemetry and production-side customs records ensures statistical integrity across the analysis window.
Input-output matrix framing connects raw material flows in medical-grade silicone and biotechnology active ingredients to finished product segmentation across ear drops, irrigation kits, and automated devices. The analytical framework spans product type, end user, technology, and distribution channel dimensions throughout the forecast period. CAGRs derive from regression analysis against aging demographic projections and telehealth adoption curves, with pricing elasticity parameters calibrated to pharmacy chain transaction data and Amazon search volume indices for cerumenolytic keywords.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR harmonization delays or EPA antimicrobial additive restriction tightening. Practitioners should monitor telehealth reimbursement coding changes and CDSCO import tariff adjustments for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Disposable Underwear Market
Personal Health
Sexual Wellness Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
Sleep Mask Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Health Check-Up Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Foot Insole Market
Personal Health
PTBCHA Market
Personal Health
Obesity Treatment Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
Health Coaching Market
Personal Health
South America Hair Loss Treatment Products Market
Personal Health
Piercing Aftercare Spray Market