
 Europe Hair Loss Treatment Products Market | 2026-2036
Europe Hair Loss Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hair Loss Treatment Products Market Foresight
Subscription-based leasing for low-level laser therapy devices is rewriting capital deployment across European clinics. L'Oréal SA leverages its dermatological research pipeline to sustain premium positioning in topical minoxidil formulations. Johnson & Johnson Services, Inc. anchors its competitive stance through pharmacy channel control across Northern Europe. Merck & Co., Inc. differentiates via prescription-grade finasteride portfolios that dominate physician-directed treatment protocols.
Europe hair loss treatment products encompass pharmacological agents, surgical interventions, and energy-based devices designed to arrest follicular miniaturization or restore hair density through modulation of androgenic pathways or stimulation of cellular metabolism. Minoxidil formulations function as vasodilatory topicals requiring precise concentration standardization, while low-level laser therapy devices emit coherent light at wavelengths calibrated to penetrate the scalp matrix and upregulate adenosine triphosphate production in follicular cells. Male pattern baldness represents the most established application segment with mature margin pools, whereas alopecia areata is gaining traction as biologic innovations expand addressable populations. Home user delivery modes are accelerating fastest as direct-to-consumer channels reduce friction for maintenance therapies.
The EU Medical Device Regulation mandates enhanced clinical evaluation for laser therapy and implantable devices, elevating compliance costs for manufacturers seeking CE marking access. EMA oversight of finasteride formulations ensures pharmacovigilance standards that shape prescription patterns and product labeling requirements across member states. France's ANSM and Germany's BfArM maintain divergent interpretation frameworks for combination drug-device products, fragmenting registration pathways. Stakeholders must monitor evolving notified body capacity constraints and preemptive portfolio adjustments to regulatory reclassification risks.
Market Dynamics
The EU Medical Device Regulation's tightened clinical evidence requirements for laser therapy devices is forcing manufacturers to restructure their CE marking pathways and elevating capital requirements across the European device landscape.
Growth Catalysts
- MDR Compliance Infrastructure:The EU Medical Device Regulation's enhanced evaluation protocols for combination drug-device products is creating specialized demand for regulatory consulting services that bridge France's ANSM and Germany's BfArM interpretation frameworks.
- Clinic-Based Aesthetic Expansion:Dermatology centers in Germany and France are broadening their service portfolios to capture recurring revenue from maintenance-oriented hair restoration protocols.
- Direct-to-Consumer Channel Maturation:Home-use delivery modes are reducing patient friction for topical minoxidil regimens, particularly among younger demographics seeking privacy in treatment initiation.
Market Restraints
- Notified Body Capacity Bottlenecks:Constrained CE marking assessment capacity across EU-authorized bodies is extending product launch timelines for laser therapy device manufacturers by twelve to eighteen months.
- Finasteride Pharmacovigilance Burden:EMA-mandated adverse event reporting requirements for prescription-grade formulations impose ongoing compliance costs that compress margin structures for pharmaceutical portfolios.
- Substitution by Surgical Hair Transplantation:Follicular unit extraction techniques in specialized clinics present a durable alternative for patients with advanced pattern baldness, limiting addressable market for non-surgical modalities.
Strategic Opportunities
- Underpenetrated Eastern European Markets:Poland and Romania exhibit low clinic density relative to Western European benchmarks, presenting first-mover advantages for device leasing models and pharmacy channel establishment.
- Biologic Convergence for Alopecia Areata:JAK inhibitor research pipelines are expanding physician-directed treatment protocols beyond androgenetic indications into autoimmune hair loss populations.
- Subscription-Based Device Economics:Low-level laser therapy equipment leasing is rewriting capital deployment structures for independent dermatology practices seeking to minimize upfront investment.
Industry Challenges
- Cross-Border Regulatory Fragmentation:Divergent national interpretation of MDR guidelines between France's ANSM and Germany's BfArM creates compliance complexity for combination product manufacturers seeking multi-market entry.
- Specialized Clinical Training Shortfalls:Scarcity of certified technicians for laser device operation and follicular assessment limits scalable deployment of energy-based treatment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hair Loss Treatment Products Market |
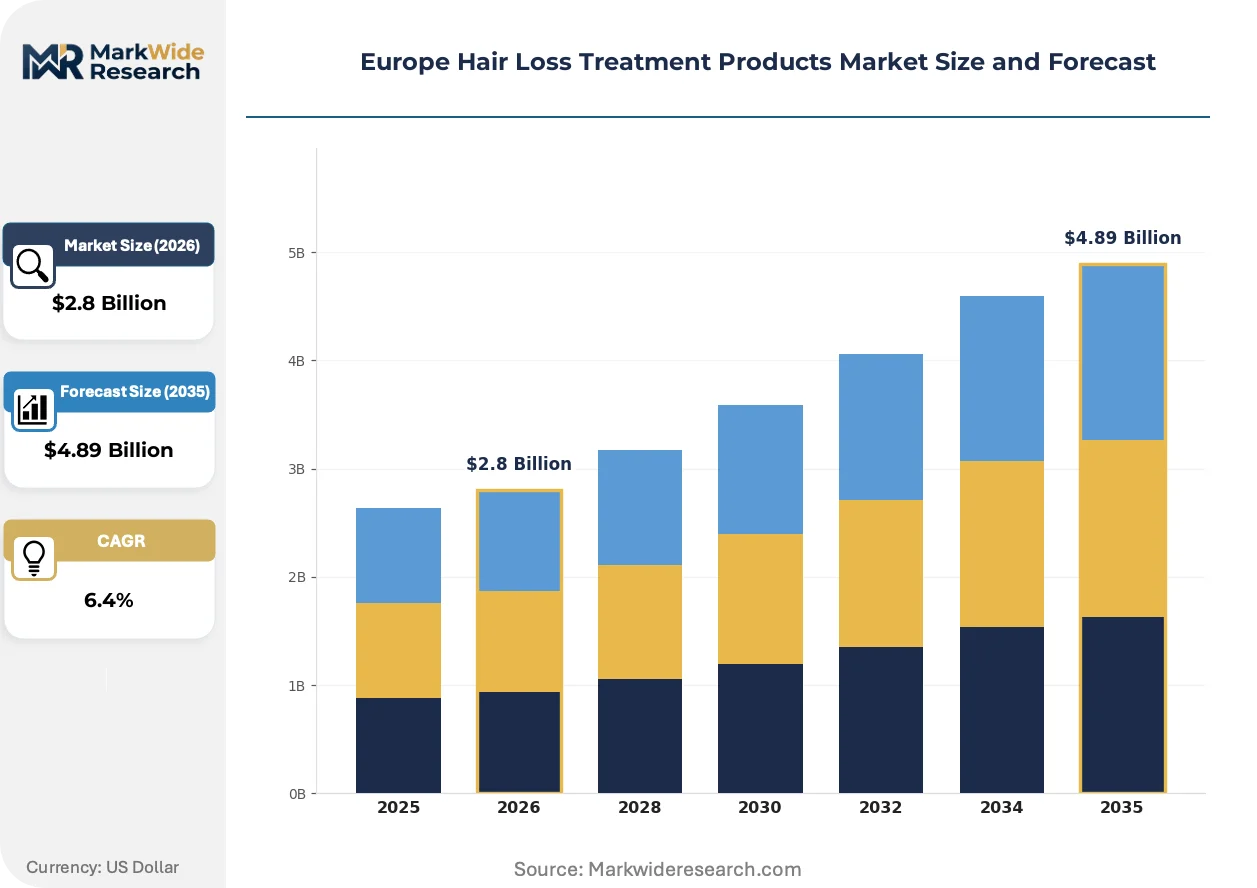
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minoxidil, Finasteride, Hair Transplant, Low-Level Laser Therapy Application: Male Pattern Baldness, Female Hair Thinning, Alopecia Areata, Post-Surgical Restoration Delivery Mode: Topical Solutions, Oral Tablets, Hair Products, Devices End User: Clinics, Salons, Home Users, Dermatology Centers |
| Companies Covered | L'Oréal SA, Procter & Gamble Company, Henkel AG & Co., KGaA, Unilever PLC, Natura & Co., Johnson & Johnson Services, Inc., Merck & Co., Inc., Sun Pharmaceutical Industries Ltd, Cipla Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hair Loss Treatment Products Market Shifts & Advancements
Digital integration across diagnostic, treatment, and monitoring workflows is compressing patient journey friction while elevating data capture capabilities for personalized protocol adjustment.
Low-level laser therapy systems with embedded scalp imaging and treatment-tracking software are digitizing the patient compliance monitoring function that previously relied on subjective self-reporting. German dermatology chains are piloting these connected devices to reduce dropout rates from maintenance regimens. The technology is digitizing outcome documentation for reimbursement negotiations with statutory health insurers.
The EU Medical Device Regulation's 2021 implementation timeline continues to reshape competitive entry barriers for energy-based devices. Manufacturers now face mandatory clinical evaluation report requirements that previously applied only to higher-risk classifications. Laser therapy device portfolios targeting the French clinic corridor are most affected, with several notified bodies withdrawing from aesthetic device certification.
Patients are consolidating purchase decisions through telehealth platforms that bundle diagnostic consultation, prescription fulfillment, and device delivery. This channel compression is displacing traditional pharmacy counter relationships for topical formulations. The shift is most visible in the United Kingdom and Netherlands, where digital health infrastructure supports integrated hair loss management subscriptions.
Europe Hair Loss Treatment Products Market Segmentation
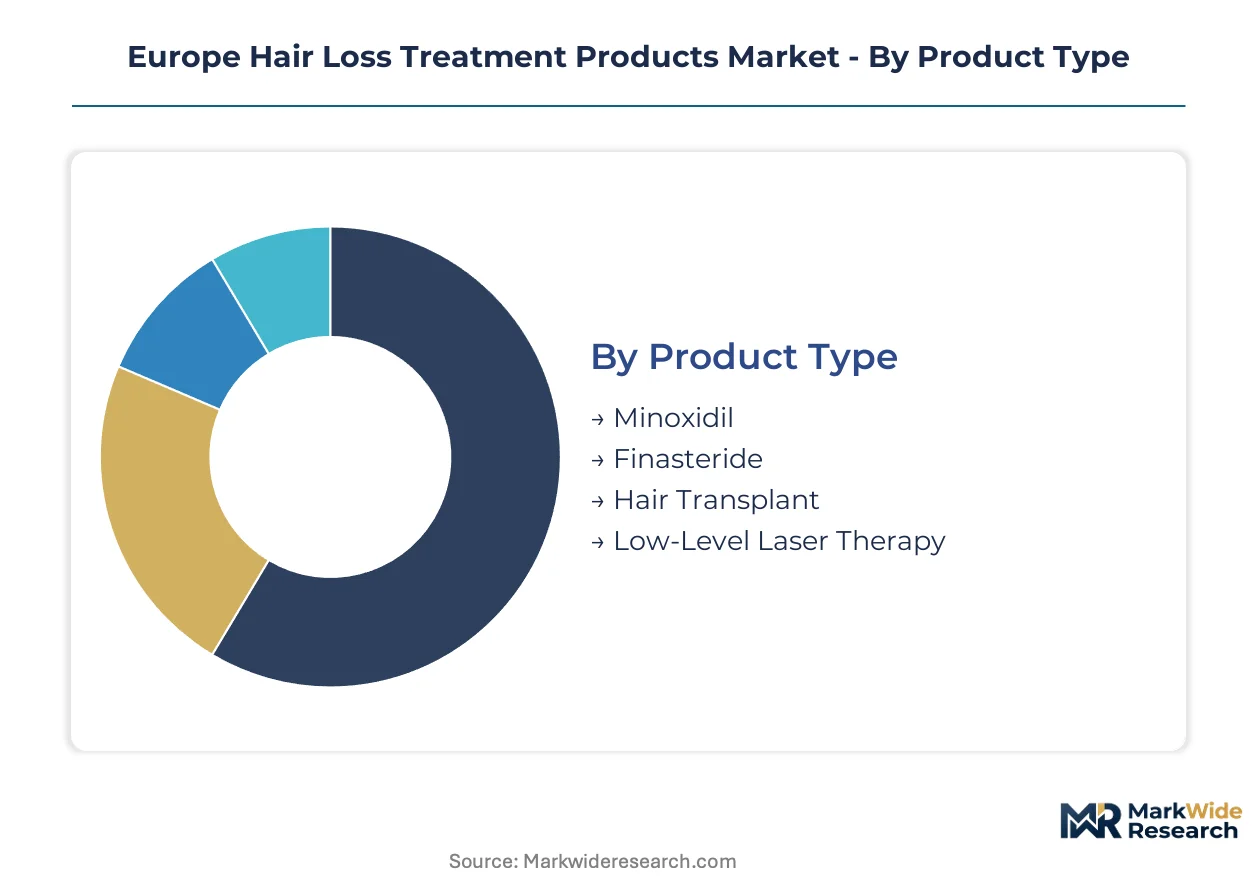
Segmentation in the Europe hair loss treatment products market reveals how therapeutic modalities, patient demographics, and care settings allocate capital and compliance burden differently. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio decisions.
Product Type:
Cost tier stratification separates mass-market topicals from capital-intensive surgical and device modalities requiring specialized infrastructure.
- Minoxidil:Vasodilatory topical formulations in standardized concentrations anchor pharmacy channel volume. German and French retail pharmacies command the highest throughput for maintenance regimens targeting early-stage follicular miniaturization.
- Finasteride:Oral 5-alpha-reductase inhibitors require prescription oversight and EMA-mandated pharmacovigilance reporting. Physician-directed protocols in France's clinic corridor concentrate demand for this systemic intervention.
- Hair Transplant:Follicular unit extraction procedures performed in specialized surgical centers.
- Low-Level Laser Therapy:Energy-based devices subject to MDR clinical evidence requirements and CE marking bottlenecks.
Minoxidil commands the established base. The steepest expansion runs through low-level laser therapy as subscription leasing reduces clinic capital barriers.
Application:
Patient population maturity and addressable market size diverge sharply between androgenetic indications and emerging autoimmune protocols.
- Male Pattern Baldness:The most established therapeutic indication with mature diagnostic criteria and reimbursement familiarity. German dermatology centers report the highest procedural density for maintenance protocols in this segment.
- Alopecia Areata:Autoimmune hair loss populations are expanding treatment protocols through JAK inhibitor research pipelines. France's ANSM oversight shapes access frameworks for biologic innovations in this indication.
- Female Hair Thinning:Diffuse pattern presentations with distinct hormonal etiologies requiring modified topical concentrations.
- Post-Surgical Restoration:Adjunctive therapies following oncological or cosmetic procedures.
Male pattern baldness commands the established base. The steepest expansion runs through alopecia areata as biologic convergence opens physician-directed protocols.
Delivery Mode:
Patient control over administration intensity separates self-managed regimens from supervised clinical interventions.
- Topical Solutions:Alcohol-based or foam carrier formulations for direct scalp application. Direct-to-consumer channels in the Netherlands and United Kingdom are compressing purchase friction for privacy-seeking younger demographics.
- Oral Tablets:Systemic absorption routes requiring prescription authorization and monitoring. Germany's BfArM maintains stringent adverse event documentation requirements that elevate compliance overhead.
- Hair Products:Shampoo and conditioner formats with functional claims.
- Devices:Energy-based and mechanical systems requiring operational training.
Topical solutions command the established base. The steepest expansion runs through devices as home-use connectivity features improve compliance monitoring.
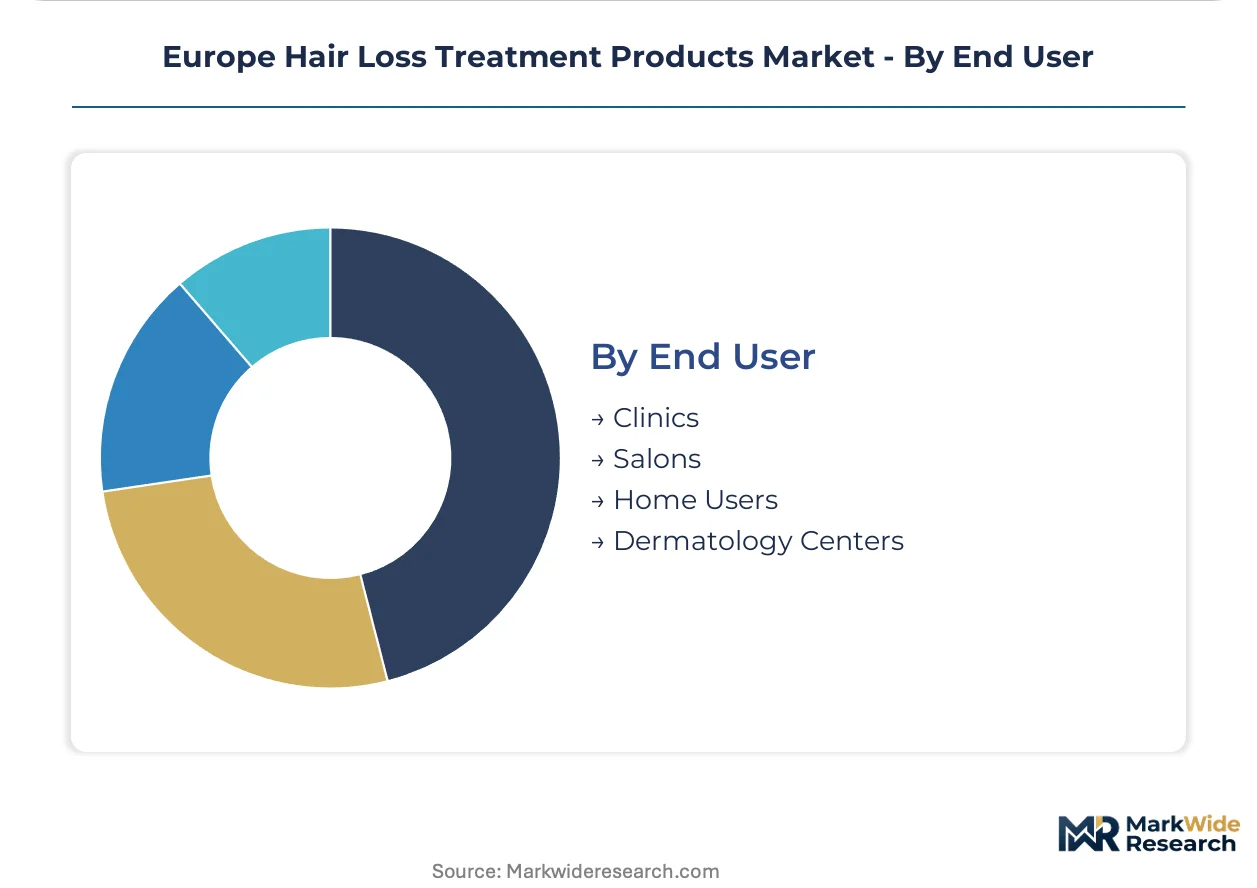
End User:
Care setting economics determine capital recovery timelines and regulatory liability exposure for product manufacturers.
- Clinics:Independent and chain-affiliated practices performing procedural interventions. French clinic-based treatment corridors are consolidating demand for combination drug-device protocols requiring ANSM registration.
- Home Users:Self-administering patients purchasing through direct-to-consumer platforms. Digital health infrastructure in the United Kingdom supports integrated subscription models bundling diagnostics, prescriptions, and device delivery.
- Salons:Non-medical aesthetic establishments with limited therapeutic scope.
- Dermatology Centers:Hospital-affiliated and academic institutions with research capabilities.
Clinics command the established base. The steepest expansion runs through home users as telehealth platforms displace traditional pharmacy relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's hair loss treatment trade flows reflect a net importer position for high-value devices and active pharmaceutical ingredients, with finished formulation exports concentrating through German and French distribution hubs serving adjacent markets.
Germany
Dermatology chains in Bavaria and North Rhine-Westphalia are consolidating procurement for low-level laser therapy devices under subscription leasing arrangements. The BfArM maintains stringent pharmacovigilance documentation for oral finasteride formulations that elevates compliance overhead for pharmaceutical portfolios. Berlin-Brandenburg hosts the densest cluster of telehealth platforms bundling diagnostic consultation with prescription fulfillment for home-use topicals.
France
The clinic-based treatment corridor through Île-de-France and Auvergne-Rhône-Alpes concentrates demand for combination drug-device protocols requiring ANSM registration. France's national health insurance framework shapes reimbursement negotiations for procedural interventions in hospital-affiliated dermatology centers. The Provence-Alpes-Côte d'Azur region exhibits accelerating direct-to-consumer channel penetration for privacy-oriented younger demographics.
United Kingdom
Digital health infrastructure in London and the Southeast supports integrated subscription models that displace traditional pharmacy relationships for topical minoxidil. The Medicines and Healthcare products Regulatory Agency oversees post-Brexit divergence from EMA guidance on finasteride labeling requirements. The Midlands corridor hosts specialized surgical centers performing follicular unit extraction procedures that compete with non-surgical modalities.
Italy
Lombardy and Emilia-Romagna maintain established manufacturing capacity for alcohol-based topical carriers serving pharmacy channel distribution across Southern Europe. The Italian Medicines Agency enforces pharmacovigilance standards aligned with EMA frameworks for prescription-grade formulations. Venice-Treviso industrial clusters supply cosmetic shampoo formats with functional claims targeting female hair thinning segments.
Netherlands
The Randstad conurbation concentrates direct-to-consumer platform headquarters leveraging logistics infrastructure for cross-border fulfillment into Belgium and Luxembourg. Dutch healthcare regulators enforce CE marking compliance for laser therapy devices entering the Benelux market through Rotterdam port distribution. Eindhoven Region medical device incubators are piloting connected diagnostic tools for scalp imaging integration.
Europe Hair Loss Treatment Products Market Competitive Landscape
On the supply side, the industry is consolidating around dermatological research pipelines and pharmacy channel control, with tiered competitive positioning separating pharmaceutical-grade portfolios from mass-market cosmetic formulations. Three strategic archetypes dominate: multinational consumer health conglomerates with regulatory compliance infrastructure, specialized pharmaceutical manufacturers with prescription-drug capabilities, and emerging telehealth-native platforms with direct-to-consumer logistics. Competitive moves concentrate on M&A activity targeting biologic research pipelines and strategic partnerships bridging device leasing with clinic network expansion.
Within the consumer health conglomerate tier, L'Oréal SA and Johnson & Johnson Services, Inc. exemplify divergent positioning strategies that anchor market structure. L'Oréal SA leverages dermatological research credentials to sustain premium-tier topical formulations. Johnson & Johnson Services, Inc. occupies a position defined by pharmacy channel density across Northern European markets. Merck & Co., Inc. represents the pharmaceutical archetype with prescription-grade finasteride portfolios dominating physician-directed treatment protocols in France and Germany.
| Leading Market Players |
|---|
| L'Oréal SA |
| Procter & Gamble Company |
| Henkel AG & Co., KGaA |
| Unilever PLC |
| Natura & Co. |
| Johnson & Johnson Services, Inc. |
| Merck & Co., Inc. |
| Sun Pharmaceutical Industries Ltd |
| Cipla Limited |
| Others |
Supply & Pricing Matrix
Italian and German manufacturing clusters for alcohol-based topical carriers concentrate upstream supply for minoxidil formulations, anchoring margin pools in pharmacy channel distribution across France and Germany where brand premiums command pricing power.
Pricing Analysis
Clinic procurement managers anchor pricing structures across three tiers: premium dermatological-grade formulations, standard pharmacy-channel topicals, and economy generic alternatives. Price differentiation rests on CE marking tier for device bundles and ANSM registration status for combination products. Pricing pressure stems from direct-to-consumer telehealth platforms compressing pharmacy markups for maintenance regimens. Younger demographics seeking privacy in treatment initiation exhibit highest price sensitivity, while hospital-affiliated dermatology centers demonstrate lowest sensitivity due to reimbursement frameworks.
Supply Chain Analysis
Contract manufacturing for low-level laser therapy devices concentrates in Eindhoven Region incubators and Bavarian medical device clusters. Active pharmaceutical ingredient sourcing draws from Indian and Chinese API manufacturers for finasteride and minoxidil base compounds. Single-source vulnerability runs through CE marking assessment capacity at EU-authorized notified bodies. Distribution runs through Rotterdam port logistics for Benelux fulfillment and German pharmacy wholesale networks serving Northern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's 2021 implementation timeline constitutes a regulatory inflection accelerating competitive consolidation around compliance infrastructure.
For Market Incumbents: Harden regulatory dossier capabilities for combination drug-device products to preempt ANSM-BfArM interpretation divergences. Deepen backward integration into laser diode component sourcing to offset notified body capacity bottlenecks extending CE marking timelines. For New Entrants and Emerging Players: Establish a beachhead in Poland and Romania's underpenetrated clinic markets through subscription-based device leasing models. Target privacy-oriented younger demographics via direct-to-consumer telehealth platforms bundling diagnostic consultation with prescription fulfillment. For Investors and Strategic Acquirers: Capital is best deployed toward telehealth-native platforms with integrated logistics infrastructure and biologic research pipelines targeting alopecia areata JAK inhibitor applications. Long-term viability across a decade horizon hinges on regulatory compliance scalability rather than single-product positioning. Monitor notified body capacity expansion announcements as inflection signal for device market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | MDR clinical evidence requirements elevate barriers for laser therapy device manufacturers seeking French clinic access. |
| Direct-to-Consumer Platform Launch | Telehealth bundling in the United Kingdom and Netherlands displaces traditional pharmacy relationships for topical formulations. |
| Biologic Pipeline Diversification | JAK inhibitor research for alopecia areata expands addressable populations beyond established androgenetic indications. |
| Subscription Device Leasing Model | Capital-light deployment structures enable independent dermatology practices in Eastern Europe to adopt laser therapy protocols. |
| Regulatory Consulting Service Expansion | Bridge services for ANSM-BfArM interpretation fragmentation capture specialized demand from combination product manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic directors, pharmacy procurement managers, regulatory affairs specialists at device manufacturers, and telehealth platform operators. Secondary validation drew from EMA pharmacovigilance databases, ANSM and BfArM registration filings, EU notified body capacity reports, and pharmacy channel sales audit data. Bottom-up patient population modeling and top-down market size triangulation anchored quantitative outputs.
Calibration against historical growth patterns and regulatory implementation timelines shaped analytical framework construction across the projection horizon. Segmentation dimensions modeled include product type, application indication, delivery mode, and end-user care setting. CAGRs were derived from elasticity-adjusted demand curves incorporating MDR compliance cost pass-through and direct-to-consumer channel penetration rates.
Stress conditions across notified body capacity constraints, API sourcing disruptions, and reimbursement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of CE marking queue lengths and telehealth platform subscriber acquisition costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
OTC Health Products Market
Personal Health
Maternity and Personal Care Market
Personal Health
Tick Repellent Market
Personal Health
Sleeping Aids Market
Personal Health
Interdental Brush Market
Personal Health
Health Coaching Market
Personal Health
Infrared Sauna Blankets Market
Personal Health
Menopause Wellness Market
Personal Health
Reusable Face Mask Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
South America Hair Loss Treatment Products Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Corporate Wellness Market
Personal Health
Feminine Hygiene Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market