
 Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market | 2026-2036
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market Foresight
Project finance for public health infrastructure is reconfiguring competitive access across the Middle East and Africa smoking cessation landscape. Johnson & Johnson leverages its pharmaceutical distribution networks to sustain pharmacy channel dominance in Gulf markets. GlaxoSmithKline plc anchors its position through nicotine patch manufacturing scale that competes on unit economics with regional generics.
Smoking cessation and nicotine de-addiction encompasses pharmacological interventions, behavioral modification protocols, and delivery systems designed to reduce nicotine dependence through controlled tapering or receptor antagonism. Nicotine Replacement Therapy patches typically deliver 7–21 mg of nicotine over 16–24 hours to maintain steady plasma levels while eliminating combustion exposure. Prescription drugs such as varenicline function as partial agonists at α4β2 neuronal nicotinic acetylcholine receptors, blocking reward pathways while reducing withdrawal severity. Behavioral therapy segments command premium reimbursement rates where healthcare providers integrate counseling protocols, though vaping products face accelerating regulatory scrutiny that compresses margin pools in markets adopting precautionary frameworks.
Saudi Arabia's SFDA and South Africa's national health regulator enforce divergent product registration pathways that shape market access timelines for nicotine replacement therapies and prescription smoking cessation drugs. The UAE's MOHAP maintains stringent import licensing for vaping products that limits distribution channel expansion beyond pharmacies and hospitals. Stakeholders must monitor evolving tobacco control harmonization efforts across Gulf Cooperation Council jurisdictions to anticipate standardization or fragmentation of approval requirements.
Market Dynamics
Gulf Cooperation Council tobacco control harmonization is fragmenting registration pathways for nicotine replacement therapies, forcing manufacturers to navigate divergent approval timelines across Saudi Arabia, UAE, and Qatar while South Africa's national health insurance expansion pulls cessation services into public procurement frameworks.
Growth Catalysts
- SFDA Accelerated Review Pathways:Saudi Arabia's pharmaceutical regulator has streamlined nicotine patch and gum registrations, cutting market access timelines for manufacturers with existing EU or US approvals.
- Corporate Wellness Mandates:Large employers in Dubai and Abu Dhabi are integrating behavioral counseling into health benefit packages, creating institutional demand for comprehensive cessation programs.
- Combustion Alternatives Taxation:GCC finance ministries are imposing escalating excise duties on cigarettes, widening the price gap between tobacco and nicotine replacement products.
Market Restraints
- API Import Dependency:Regional manufacturers rely on imported active pharmaceutical ingredients for varenicline and bupropion, exposing margins to currency volatility and shipping disruptions.
- MOHAP Vaping Restrictions:The UAE's health ministry maintains outright bans on e-cigarette flavorings and online sales, compressing margin pools for alternative nicotine delivery systems.
- Prescription-Only Frameworks:South Africa's medicines regulator classifies most pharmacotherapies as schedule 4, limiting pharmacy counter access and requiring physician gatekeeping.
Strategic Opportunities
- Telemedicine Integration:Virtual counseling platforms are penetrating underserved populations in Nigeria and Kenya, bypassing clinic infrastructure gaps through mobile health applications.
- Public Procurement Expansion:Egypt's universal health insurance rollout is adding smoking cessation to covered benefits, opening institutional volume for low-cost nicotine gum tenders.
- Combination Therapy Protocols:Pairing transdermal patches with behavioral apps is gaining reimbursement traction in Saudi wellness centers, differentiating service providers.
Industry Challenges
- Behavioral Counselor Shortage:Gulf markets lack sufficient trained psychologists to staff corporate wellness programs, forcing reliance on automated digital interventions with lower efficacy rates.
- Multi-Jurisdiction Labeling:Packaging requirements differ across SFDA, MOHAP, and South African Health Products Regulatory Authority standards, complicating regional SKU management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market |
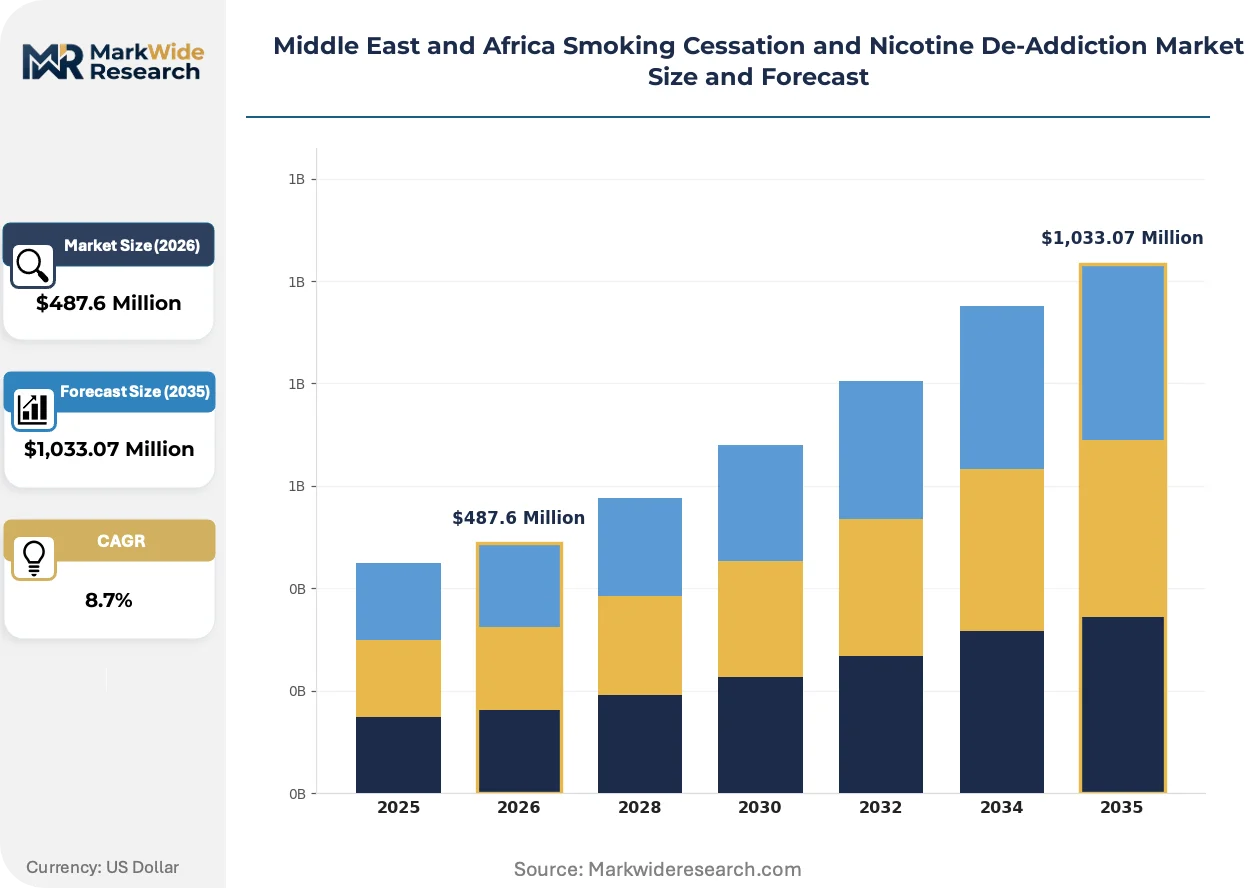
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nicotine Replacement Therapy, Prescription Drugs, Behavioral Therapy, Vaping Products End User: Individuals, Healthcare Providers, Wellness Centers, Organizations Distribution Channel: Pharmacies, Online Stores, Hospitals, Clinics Delivery Mode: Pills, Inhalers, Patches, Gum |
| Companies Covered | Japan Tobacco Inc., Pfizer Inc., GlaxoSmithKline plc, Imperial Brands, Johnson & Johnson, Philip Morris International Inc., Perrigo Company plc, Nicotek LLC, British American Tobacco, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market Shifts & Advancements
Digital therapeutics and combination pharmacotherapy protocols are restructuring how cessation services are delivered and reimbursed across Middle East and African healthcare systems.
Long-acting nicotine formulations are migrating from 16-hour to 24-hour patch designs, maintaining steadier plasma nicotine levels through sleep cycles. Sleep clinics in Riyadh and Jeddah are prescribing these extended-release systems for patients experiencing nocturnal withdrawal symptoms. This migration from daytime-focused delivery is compressing demand for twice-daily gum regimens and reshaping pharmacy inventory allocations.
South Africa's Health Products Regulatory Authority is tightening pharmacovigilance reporting requirements for smoking cessation drugs, mandating quarterly adverse event submissions from license holders. Manufacturers must now maintain local safety databases and designate in-country qualified persons for signal detection. Prescription varenicline suppliers are responding by embedding pharmacovigilance capabilities within their Johannesburg distribution operations.
Employer-funded cessation benefits are displacing out-of-pocket pharmacy purchases across Gulf corporate health schemes. Large Saudi conglomerates are contracting directly with wellness providers for bundled patch-plus-counseling packages, bypassing retail pharmacy channels. This concentration of purchasing authority is most visible in Riyadh's financial services sector, where compliance departments track quit rates as part of health risk management reporting.
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market Segmentation
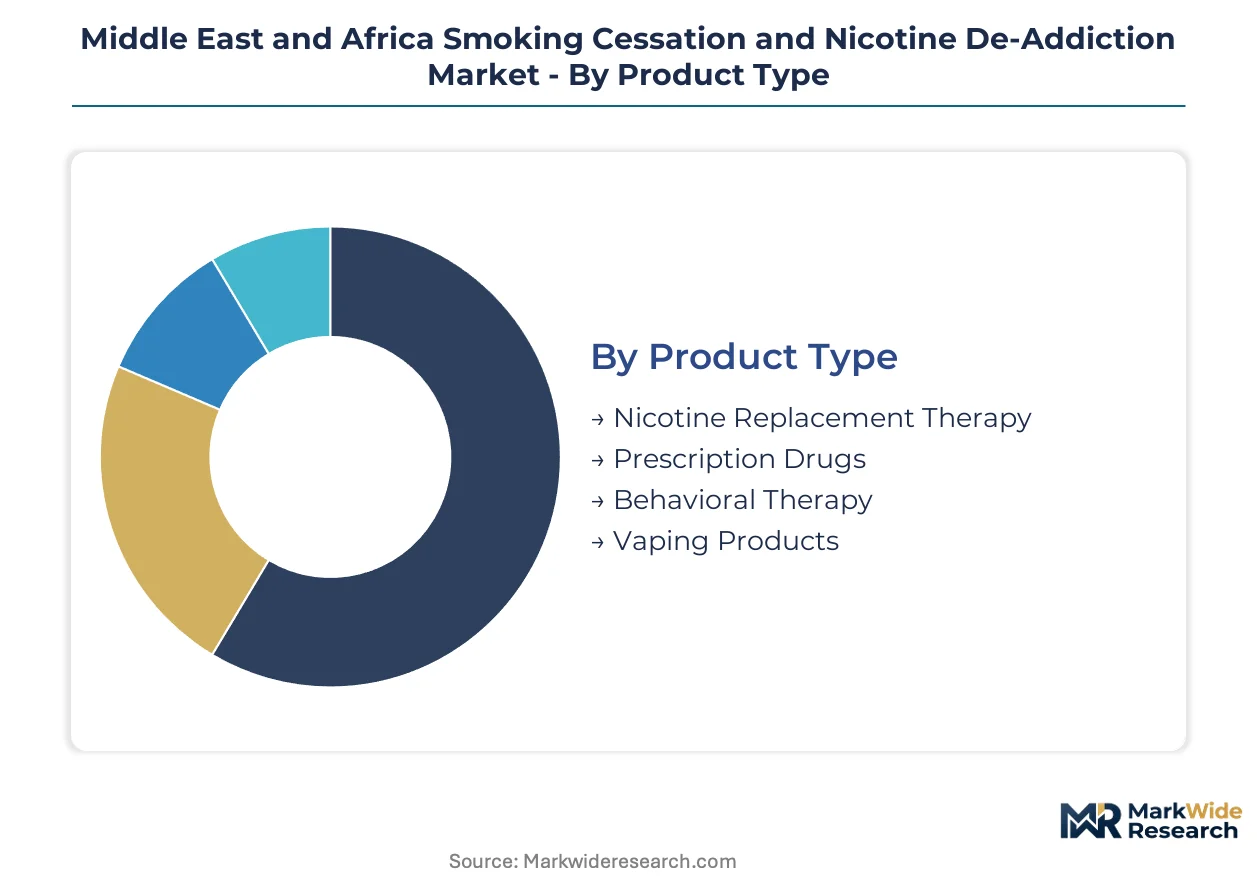
Segmentation across the Middle East and Africa smoking cessation market reveals how regulatory fragmentation and reimbursement heterogeneity concentrate revenue in distinct product and channel configurations. Understanding these divides enables stakeholders to align manufacturing investments with jurisdiction-specific access pathways.
Product Type:
Mature pharmacotherapies dominate prescription volumes while emerging digital and alternative delivery formats capture wellness-sector experimentation.
- Nicotine Replacement Therapy:Transdermal patches and oral formulations deliver controlled nicotine tapering through 16–24 hour release profiles. Demand concentrates in Saudi Arabia where SFDA fast-track approvals for EU-certified patches have compressed pharmacy stocking timelines. Corporate wellness contracts in Riyadh and Jeddah now bundle NRT with biometric monitoring.
- Prescription Drugs:Varenicline and bupropion function as partial agonists or reuptake inhibitors targeting α4β2 nicotinic receptors. South Africa's schedule 4 classification restricts these to physician dispensing, channeling volume through hospital outpatient departments rather than retail pharmacies.
- Behavioral Therapy:Structured counseling protocols command premium reimbursement where integrated with pharmacotherapy.
- Vaping Products:Alternative nicotine delivery faces MOHAP flavoring bans and online sales prohibitions in the UAE.
Nicotine Replacement Therapy handles the majority of throughput; Prescription Drugs is the fastest mover on share where public procurement expands.
End User:
Cost tier stratification separates institutional purchasers with bargaining leverage from fragmented individual out-of-pocket spending.
- Individuals:Direct pharmacy purchases dominate in markets lacking comprehensive insurance coverage for cessation services.
- Healthcare Providers:Hospital systems and clinic networks aggregate demand through formulary committees.
- Wellness Centers:Premium service providers in Dubai and Abu Dhabi integrate combination therapy protocols with biometric tracking. Saudi conglomerates contract these centers directly for employee cessation programs, bypassing traditional reimbursement channels.
- Organizations:Large employers across the GCC are mandating cessation benefits as health risk management tools. Compliance departments in Riyadh's financial sector track quit rates alongside other occupational health metrics.
Organizations command the steepest volume expansion trajectory; Individuals retain the widest absolute base despite reimbursement fragmentation.
Distribution Channel:
Supply concentration in regulated pharmacy and hospital channels contrasts with emerging digital penetration where infrastructure permits.
- Pharmacies:Community and hospital-based dispensaries remain the primary access point for NRT and prescription cessation drugs. Johnson & Johnson leverages established pharmaceutical distribution networks to sustain shelf presence across Gulf markets.
- Online Stores:E-commerce penetration varies sharply by jurisdiction. MOHAP maintains outright bans on vaping product online sales while permitting registered pharmacy digital dispensing for approved NRT.
- Hospitals:Institutional procurement channels dominate prescription drug volume in South Africa and Egypt.
- Clinics:Outpatient facilities bridge primary care access gaps in Kenya and Nigeria.
Pharmacies anchor the channel structure; Online Stores are expanding most quickly where regulatory frameworks accommodate digital health delivery.
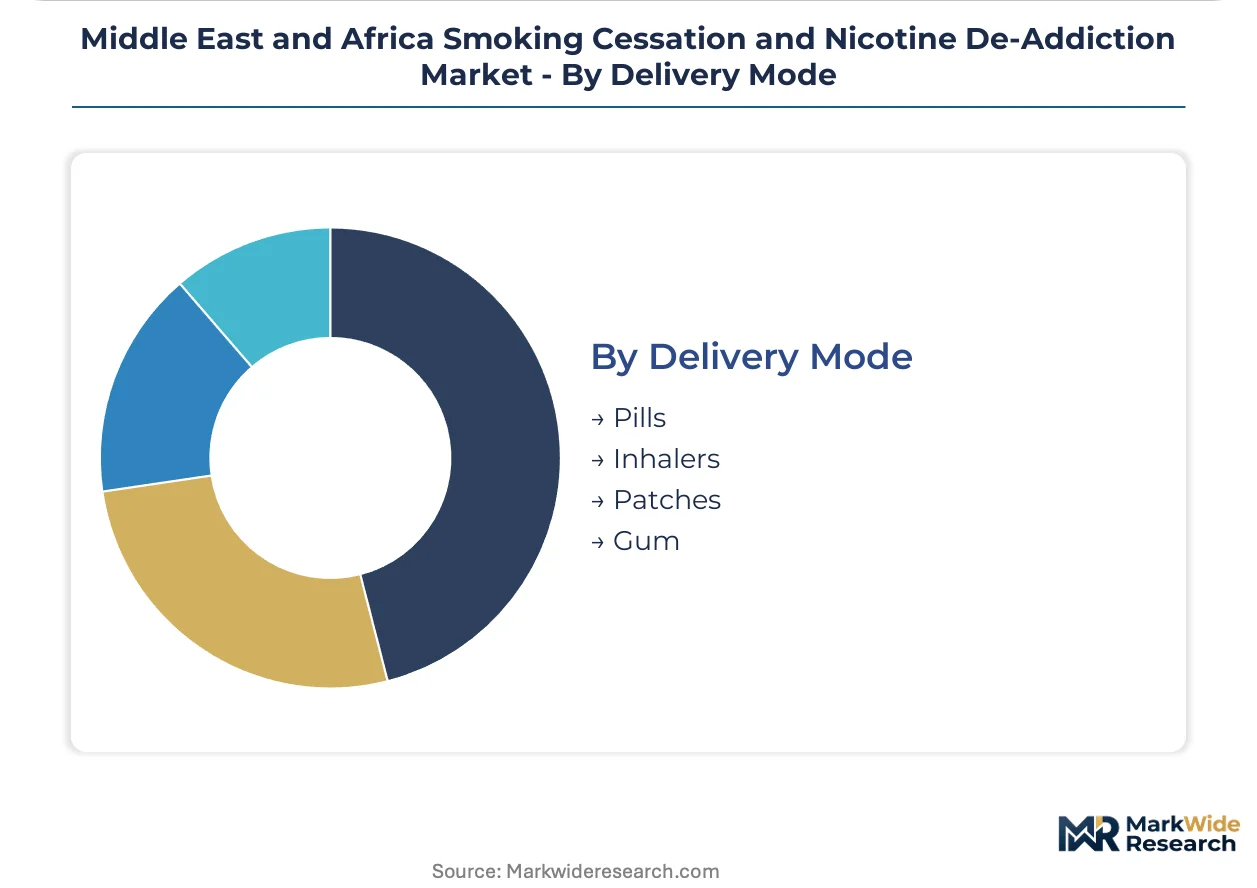
Delivery Mode:
Volume scale favors oral and transdermal formats while inhalation devices occupy niche positioning.
- Pills:Oral varenicline and bupropion formulations suit patients preferring discrete administration. South Africa's pharmacovigilance requirements mandate quarterly adverse event reporting, embedding compliance costs in pill supply chains.
- Inhalers:Nicotine vaporization devices face accelerating regulatory scrutiny across precautionary framework jurisdictions.
- Patches:Long-acting transdermal systems are migrating from 16-hour to 24-hour designs. Sleep clinics in Riyadh prescribe extended-release patches for nocturnal withdrawal management.
- Gum:Short-acting oral formats suit acute craving management but compress pharmacy margins against patch economics.
Patches capture the dominant share position; Inhalers face the most constrained expansion pathway given regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for active pharmaceutical ingredients shapes regional competitive positioning across the Middle East and Africa smoking cessation landscape. Local manufacturing capacity remains concentrated in South Africa and Egypt while Gulf markets rely on finished product imports from European and Asian suppliers.
Saudi Arabia
Corporate wellness mandates from large Riyadh-based conglomerates are institutionalizing demand for bundled cessation services. The SFDA operates accelerated review pathways for nicotine replacement therapies holding existing EU or US approvals, compressing market access timelines. Sleep clinics in Jeddah prescribe 24-hour transdermal patches for nocturnal withdrawal management, shifting pharmacy inventory toward extended-release formats.
United Arab Emirates
Dubai and Abu Dhabi employers are integrating behavioral counseling into health benefit packages, creating contracted demand for comprehensive programs. MOHAP maintains outright bans on e-cigarette flavorings and online sales, channeling volume toward regulated pharmacy and hospital channels. Wellness centers in Dubai Marina anchor premium service delivery, combining biometric tracking with combination therapy protocols.
South Africa
National health insurance expansion is pulling cessation services into public procurement frameworks, opening institutional volume for low-cost generics. The national medicines regulator classifies varenicline and bupropion as schedule 4 substances, restricting pharmacy counter access to physician dispensing. Johannesburg distribution operations are embedding pharmacovigilance capabilities to meet quarterly adverse event reporting mandates.
Egypt
Universal health insurance rollout is adding smoking cessation to covered benefits, creating tender opportunities for nicotine gum suppliers. The country's pharmaceutical regulator is harmonizing import licensing with broader African Medicines Agency alignment efforts. Cairo-based manufacturers are positioning for regional export into Sudan and Libya markets.
Nigeria
Telemedicine platforms are penetrating underserved populations through mobile health applications, bypassing clinic infrastructure gaps in Lagos and Abuja. The national drug regulatory agency is tightening registration requirements for imported nicotine replacement products. Local pharmacy chains are building distribution partnerships with South African suppliers to secure consistent patch and gum supply.
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the nicotine delivery and behavioral intervention segments. Market structure tilts toward multinational pharmaceutical conglomerates with established Gulf distribution networks, though regional generics manufacturers compete on unit economics for basic patch formulations. Three archetypes dominate: diversified healthcare conglomerates leveraging pharmacy channel relationships, specialized nicotine replacement therapy manufacturers competing on manufacturing scale, and wellness service providers bundling counseling with biometric monitoring. Consolidation pressure is accelerating through corporate wellness contract aggregation, while vertical integration into active pharmaceutical ingredient sourcing remains limited by regional manufacturing constraints.
Among the diversified healthcare conglomerates, Johnson & Johnson and GlaxoSmithKline plc occupy positions anchored by pharmaceutical distribution infrastructure and nicotine patch manufacturing scale respectively. Pfizer Inc. sits within the prescription pharmacotherapy tier, its corporate structure reflecting the pharmaceutical incumbent archetype. These three entities exemplify how established Gulf market presence and regulatory compliance capabilities create defensive positioning against emerging regional competitors.
| Leading Market Players |
|---|
| Japan Tobacco Inc. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Imperial Brands |
| Johnson & Johnson |
| Philip Morris International Inc. |
| Perrigo Company plc |
| Nicotek LLC |
| British American Tobacco |
| Others |
Supply & Pricing Matrix
The Red Sea shipping corridor's freight volatility feeds directly into landed costs for nicotine replacement therapies across Gulf markets, concentrating pricing power with European and Asian manufacturers who control finished product flows while forcing regional distributors to absorb margin compression or pass through to pharmacy retail tiers.
Pricing Analysis
Industrial OEM buyers anchor contract structures for corporate wellness bundles in Saudi Arabia and the UAE, where three-tier pricing separates premium biometric-integrated programs from standard patch-plus-counseling packages and economy NRT-only offerings. Price differentiation rests on certification tier—SFDA fast-track approval commands premium positioning—and volume scale from conglomerate health risk management contracts. Pricing pressure stems from Egyptian tender processes for universal health insurance inclusion, where low-cost generics undercut branded patch margins. Individual pharmacy purchasers exhibit highest price sensitivity, while employer-funded wellness programs demonstrate inelastic demand for comprehensive cessation protocols.
Supply Chain Analysis
Export-control frameworks for pharmaceutical manufacturing equipment limit regional production capacity expansion, channeling supply concentration through India, China, and Germany for active pharmaceutical ingredients and finished nicotine patches. Raw material dependencies center on nicotine alkaloid extraction, polyester backing substrates, and pressure-sensitive adhesives. Supply chain risk manifests as single-source vulnerability for varenicline API synthesis, where Indian contract manufacturers dominate global output. Distribution runs through hospital procurement committees in South Africa and Egypt, pharmacy wholesale networks across the GCC, and emerging telemedicine platforms in Nigeria and Kenya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine platform interoperability is reconfiguring cessation service delivery into ecosystem economics, where biometric data exchange between wellness providers and employer health risk management systems creates winner-take-most dynamics for integrated service bundlers.
For Market Incumbents: Harden formulary control through exclusive hospital system partnerships in Johannesburg and Cairo, where public procurement expansion concentrates volume authority. Secure backward integration into API sourcing from Indian contract manufacturers to defend margin position against Egyptian tender pressure. Embed pharmacovigilance capabilities within regional distribution operations to meet tightening South African adverse event reporting mandates.
For New Entrants and Emerging Players: Nigeria's underserved northern states present white-space opportunity for mobile health application deployment, bypassing clinic infrastructure gaps that constrain incumbent pharmacy channel dominance. Target Kenya's employer-funded wellness segment through direct contracting with Nairobi-based conglomerates, leveraging lower customer acquisition costs than saturated Gulf markets. Pursue combination therapy protocol differentiation—pairing transdermal patches with behavioral apps—to secure reimbursement traction in Saudi wellness centers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core nicotine replacement therapy manufacturing units amid portfolio rationalization pressures. Long-term viability hinges on regulatory compliance infrastructure—SFDA, MOHAP, and South African Health Products Regulatory Authority licensing capabilities—as durable moats against generic competition. Monitor telemedicine reimbursement codification across Gulf national health insurance frameworks as the critical signal for platform-economics value capture inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | SFDA fast-track designation compresses pharmacy stocking timelines for EU-certified patch manufacturers. |
| Platform Integration | Biometric data exchange with employer health risk management systems differentiates wellness service providers. |
| Backward Integration | In-house API sourcing from Indian contract manufacturers defends margins against Egyptian tender pressure. |
| Geographic Expansion | Mobile health penetration in Nigeria's northern states bypasses clinic infrastructure constraints. |
| Reimbursement Strategy | Employer benefit codification in Saudi corporate wellness mandates locks in contracted demand volumes. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs leads at SFDA and MOHAP and secondary validation through national medicines agency filings anchors the qualitative findings. Conversations with hospital procurement managers in Johannesburg and Cairo, wellness center operators in Dubai Marina, and pharmacy chain distribution heads in Lagos and Nairobi informed access pathway dynamics. Secondary sources include SFDA registration databases, South African Health Products Regulatory Authority pharmacovigilance reports, Egyptian universal health insurance tender disclosures, and GCC customs trade data. Bottom-up volume modeling triangulates against top-down healthcare expenditure projections across the analysis window.
Calibration against historical NRT adoption curves and prescription varenicline dispensing patterns shapes the analytical framework. Segmentation dimensions span product type, end user archetype, distribution channel, and delivery mode, with regulatory jurisdiction clusters as the cross-cutting stratifier. CAGRs derive from elasticity-adjusted demand projections and reimbursement expansion timelines. Forecast inputs incorporate corporate wellness mandate penetration rates and telemedicine platform adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital health platforms or API contract manufacturers would shift outcomes. Material shifts in Gulf Cooperation Council tobacco control harmonization, South African national health insurance benefit expansion, or Egyptian tender pricing thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Global Weight Loss Services Market
Personal Health
Corporate Wellness Market
Personal Health
Interdental Brush Market
Personal Health
Global on Site Preventive Care Market
Personal Health
Medical Wellness Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
North America Workplace Wellness Market
Personal Health
Disposable Underwear Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Hair Restoration Market
Personal Health
Asia-Pacific Mobile Health Market
Personal Health
OTC Health Products Market
Personal Health
Sleep Mask Market
Personal Health
South America Hair Loss Treatment Products Market