
 South America Hair Loss Treatment Products Market | 2026-2036
South America Hair Loss Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
South America Hair Loss Treatment Products Market Analytics
The dermatology clinic end-user vertical is decoupling from traditional salon distribution as patients seek clinically validated protocols. Johnson & Johnson sustains its presence through pharmacy-led minoxidil franchises across Brazilian retail networks. Merck & Co. Inc. anchors the prescription finasteride segment via partnerships with regional distributors. Natura &Co leverages its direct-sales infrastructure to penetrate mid-income consumer segments that clinic-based brands rarely reach.
South America hair loss treatment products comprise topical solutions, oral medications, and device-based interventions formulated with active pharmaceutical ingredients or cosmetic actives to arrest follicle miniaturization and stimulate regrowth; minoxidil formulations typically contain propylene glycol, alcohol, and water-based carriers at concentrations ranging from two to five percent for topical delivery. The product type dimension shows minoxidil occupying the volume base while finasteride commands premium pricing through prescription control. Application segmentation reveals men as the established buyer pool, though women represent the faster-expanding addressable base as postpartum and hormonal thinning awareness spreads. Delivery mode dynamics favor topical solutions for accessibility, yet laser therapy devices are gaining traction among affluent urban consumers seeking non-pharmacological options.
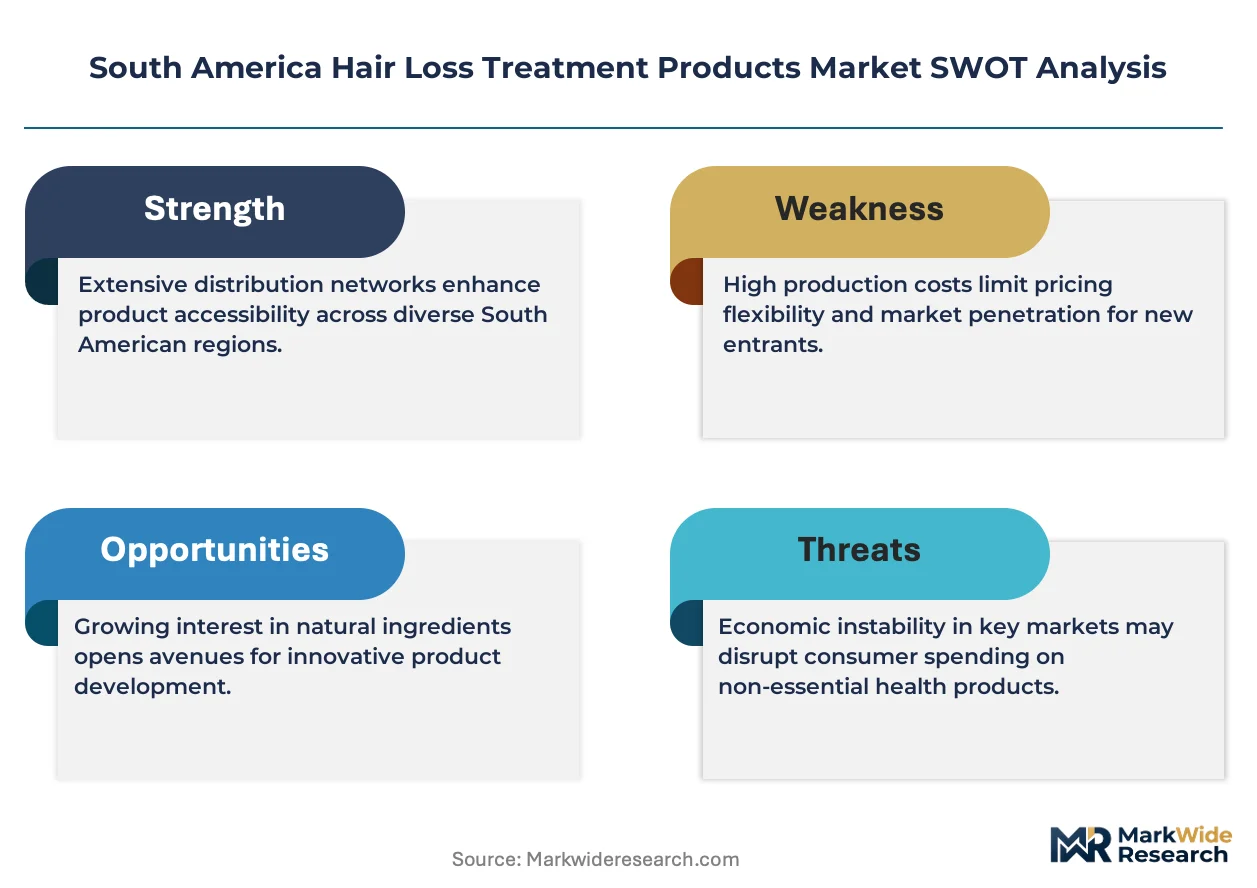
ANVISA governs pharmaceutical registration and cosmetic safety claims for hair loss products in Brazil, while Argentina's national administration of drugs, foods and medical technology enforces parallel standards that constrain cross-border formulation consistency. REACH-aligned toxicology documentation increasingly influences import acceptance for European-manufactured active ingredients. Stakeholders must monitor how regulatory divergence between Mercosur members affects multi-country labeling strategies and whether ANVISA's pending reclassification of certain DHT blockers will shift competitive advantage toward established pharmaceutical registrants.
Market Dynamics
ANVISA's cosmetic-pharmaceutical boundary reclassification is fragmenting registration pathways for combination hair loss therapies, forcing manufacturers to choose between streamlined cosmetic claims or rigorous pharmaceutical trials.
Growth Catalysts
- Postpartum hair thinning awareness:Brazilian and Argentine women are seeking clinical interventions for telogen effluvium, expanding the addressable patient base beyond androgenetic alopecia.
- REACH-aligned toxicology documentation:European-manufactured active ingredients face smoother import acceptance into Mercosur markets, accelerating product pipeline velocity for multinational suppliers.
- Direct-to-consumer telemedicine platforms:São Paulo-based digital health startups are prescribing finasteride through remote consultations, bypassing traditional dermatology clinic bottlenecks.
Market Restraints
- Propylene glycol supply volatility:Minoxidil formulation costs fluctuate with petrochemical derivative pricing, compressing margins for volume producers.
- Cross-border formulation inconsistency:Divergent standards between Brazil's ANVISA and Argentina's national drug administration force dual-labeling investments that erode economies of scale.
- Oral finasteride substitution threat:Compounding pharmacies in Colombia and Chile are producing unregulated generic alternatives that undercut prescription channel integrity.
Strategic Opportunities
- Peruvian and Ecuadorian urban corridors:Lima and Quito show rising aesthetic medicine spending with minimal established clinic presence, offering first-mover positioning for protocol-based entrants.
- Low-level laser therapy device convergence:Integration of diode arrays with smartphone-connected treatment tracking is creating premium positioning for tech-enabled hardware brands.
- Private label pharmacy partnerships:Brazilian retail chains are developing house-brand minoxidil lines, opening co-manufacturing contracts for regional API suppliers.
Industry Challenges
- Trichology specialist scarcity:Brazil trains fewer than 200 board-certified hair restoration physicians annually, constraining clinic expansion velocity in secondary cities.
- Clinical trial infrastructure gaps:ANVISA-mandated local efficacy studies for pharmaceutical-class hair loss claims require 18-24 month timelines that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Hair Loss Treatment Products Market |
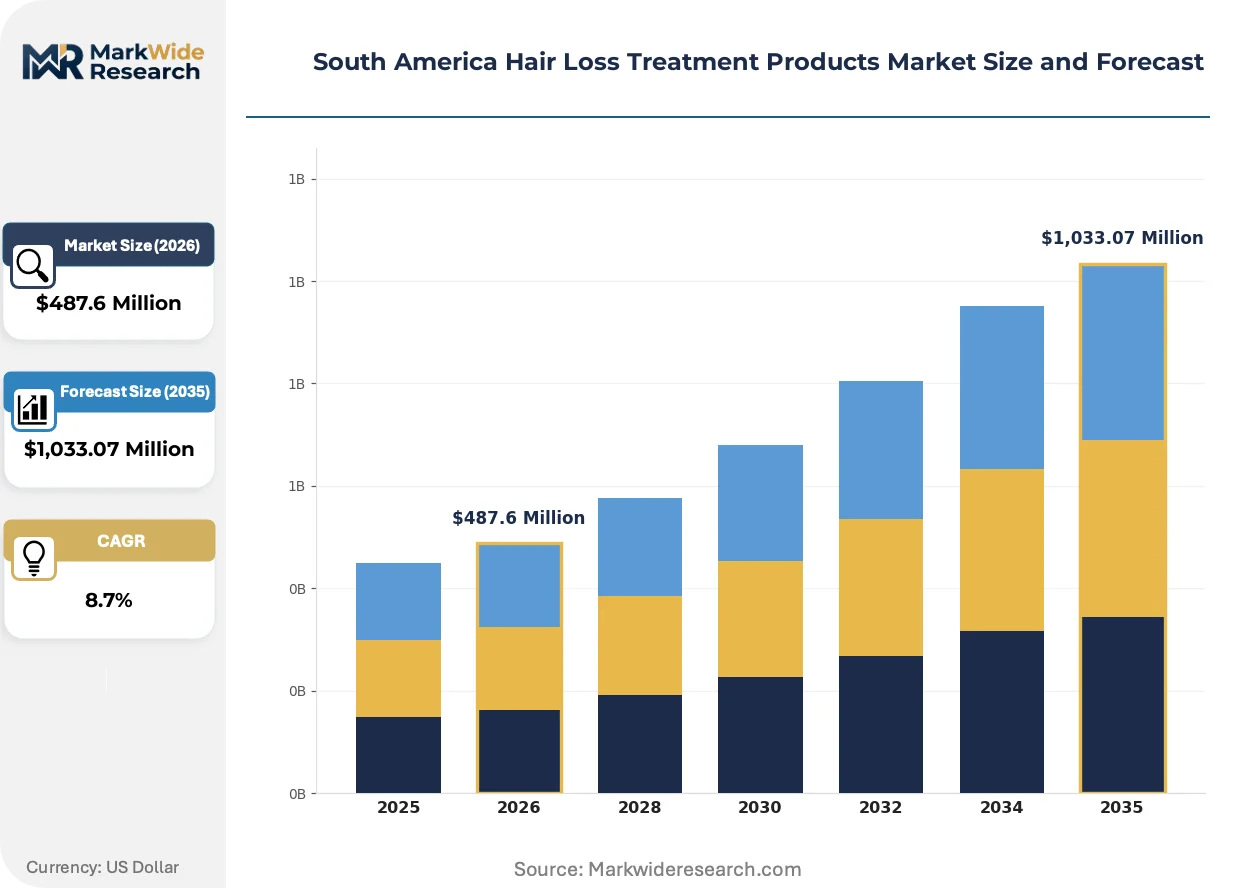
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minoxidil, Finasteride, DHT Blockers, Hair Growth Shampoos Application: Men, Women, Thinning Hair, Baldness Delivery Mode: Topical Solutions, Oral Medications, Hair Transplants, Laser Therapy End User: Salons, Clinics, Retail Consumers, Dermatologists |
| Companies Covered | Johnson & Johnson, Merck & Co. Inc., The Procter & Gamble Company, Dr Reddys Laboratories Ltd., Cipla Inc., L'Oreal SA, Natura &Co, Shiseido Co. Ltd., Unilever PLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Hair Loss Treatment Products Market Evolving Landscape
Device-based interventions are absorbing patient preference from pharmacological maintenance regimens, while regulatory clarity on combination products reshapes competitive entry strategies across the continent.
Microneedling paired with topical growth factor serums is absorbing market share from standalone minoxidil protocols in Brazilian dermatology clinics. Patients with early-stage thinning are requesting combination treatments that promise faster visible results than monotherapy. This absorption pattern is compressing the addressable market for basic topical solutions while expanding service revenue per patient visit.
ANVISA's pending reclassification of certain DHT-blocking botanical extracts is tightening claims substantiation requirements for cosmetic-positioned hair loss products. Manufacturers must now submit clinical data or retreat to vague "hair wellness" positioning. Argentine regulators are observing Brazil's framework closely, suggesting harmonized Mercosur standards may emerge within the analysis window.
Subscription-based replenishment models are displacing pharmacy counter purchases among São Paulo's affluent male consumers. Digital-native brands are capturing recurring revenue through automated 90-day supply shipments with telehealth follow-up. This behavioral shift is most visible in Brazil's southeastern corridor, where private aesthetic medicine spending supports premium service bundling.
South America Hair Loss Treatment Products Market Segmentation
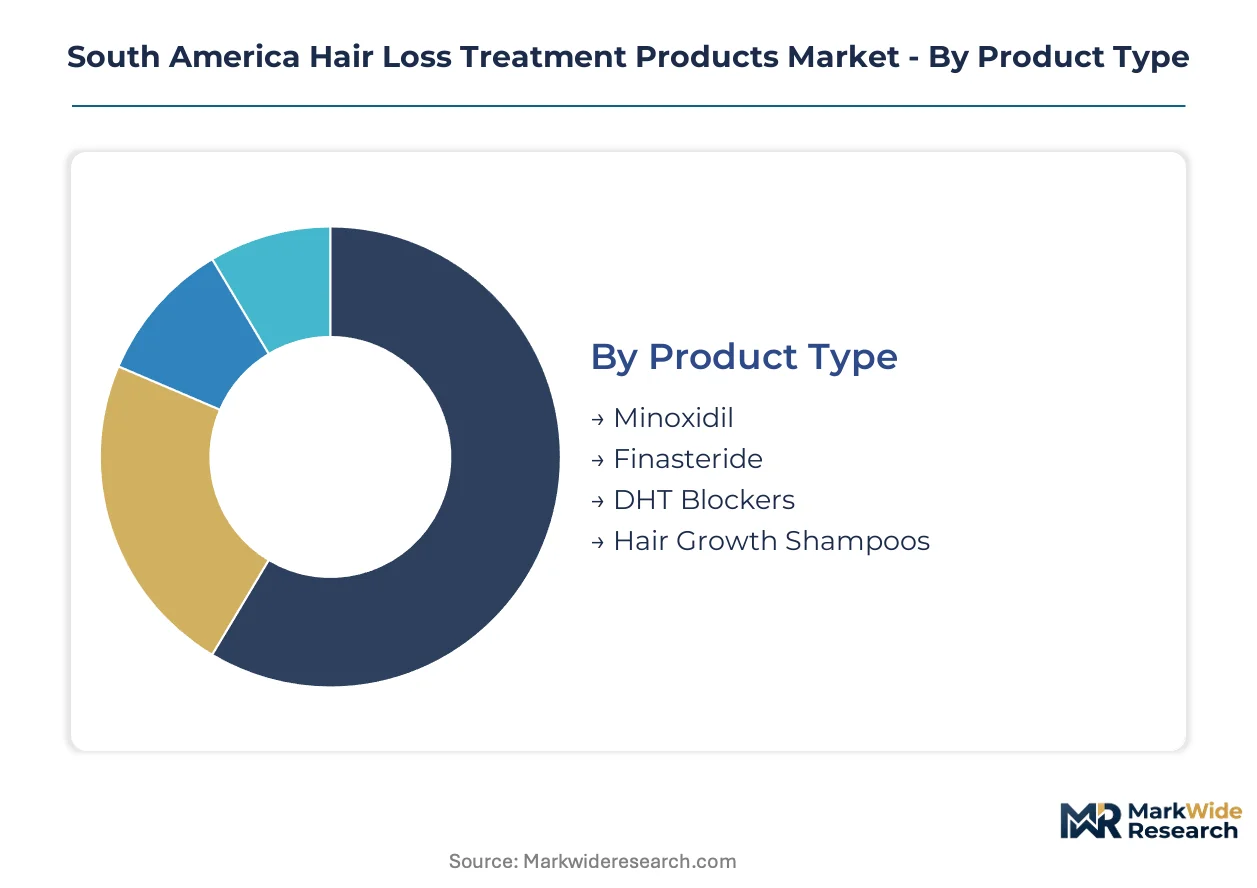
Hair loss treatment segmentation in South America maps directly onto regulatory complexity, with pharmaceutical-class products facing ANVISA's rigorous registration pathways while cosmetic-positioned alternatives navigate lighter compliance burdens. Understanding these segment boundaries determines market entry strategy and margin structure for manufacturers.
Product Type:
ANVISA's cosmetic-pharmaceutical boundary reclassification imposes distinct certification burdens across this category, with prescription-grade actives requiring full pharmaceutical trials and botanical-positioned alternatives facing tightened claims substantiation.
- Minoxidil:Formulations contain propylene glycol, alcohol, and water-based carriers at two to five percent concentrations for topical follicle stimulation. Demand concentrates in Brazil's southeastern corridor, particularly São Paulo pharmacy networks, where private aesthetic medicine spending sustains volume despite petrochemical derivative cost volatility compressing manufacturer margins.
- Finasteride:Oral and topical prescription DHT inhibitors command premium pricing through controlled distribution channels. São Paulo-based telemedicine platforms are accelerating patient access via remote consultations, bypassing traditional dermatology clinic bottlenecks that previously constrained prescription velocity.
- DHT Blockers:Botanical and synthetic anti-androgen compounds positioned at the regulatory boundary face ANVISA's pending reclassification scrutiny.
- Hair Growth Shampoos:Cosmetic-class cleansing formulations with growth actives occupy mass-market retail shelves across Brazilian and Argentine pharmacy chains.
Minoxidil sits at the top of the volume ranking, with finasteride climbing the fastest as telemedicine platforms democratize prescription access.
Application:
Patient demographics in this category stratify sharply by treatment protocol intensity, with hormonal and postpartum thinning driving clinical engagement among previously underserved populations.
- Men:Androgenetic alopecia patients constitute the established buyer pool with longest treatment persistence and highest lifetime value per patient. Brazilian men in Rio de Janeiro and São Paulo demonstrate strong adherence to minoxidil maintenance regimens purchased through pharmacy retail networks.
- Women:Postpartum telogen effluvium and hormonal thinning awareness is expanding the addressable patient base beyond traditional male-pattern baldness. Argentine and Brazilian women increasingly seek clinical interventions, with dermatology clinics in Buenos Aires reporting rising consultation volumes for female-pattern hair loss.
- Thinning Hair:Early-stage intervention patients prioritize combination protocols promising faster visible results than monotherapy approaches.
- Baldness:Advanced-stage patients gravitate toward surgical and device-based interventions as pharmacological options show diminished returns.
Men retain the largest share of current treatment volume, while women are expanding most quickly as postpartum awareness campaigns penetrate mid-income segments.
Delivery Mode:
Accessibility gradients shape competitive positioning here, with at-home solutions dominating volume and clinic-based interventions capturing premium pricing.
- Topical Solutions:Minoxidil and growth factor serums applied directly to scalp tissue remain the most accessible entry point for new patients. Brazilian retail pharmacy chains across São Paulo and Rio de Janeiro sustain volume through over-the-counter availability and private label expansion.
- Oral Medications:Systemic finasteride and emerging oral minoxidil formulations require prescription control, creating channel concentration around dermatology clinics and telemedicine platforms. Compounding pharmacies in Colombia and Chile threaten prescription channel integrity with unregulated generic alternatives.
- Hair Transplants:Surgical follicular unit extraction procedures concentrate in São Paulo's specialized aesthetic medicine centers.
- Laser Therapy:Low-level diode array devices with smartphone-connected treatment tracking are gaining traction among affluent urban consumers seeking non-pharmacological maintenance options.
Topical solutions maintain the broadest patient reach, with laser therapy devices gaining share fastest among premium-positioned urban consumers.
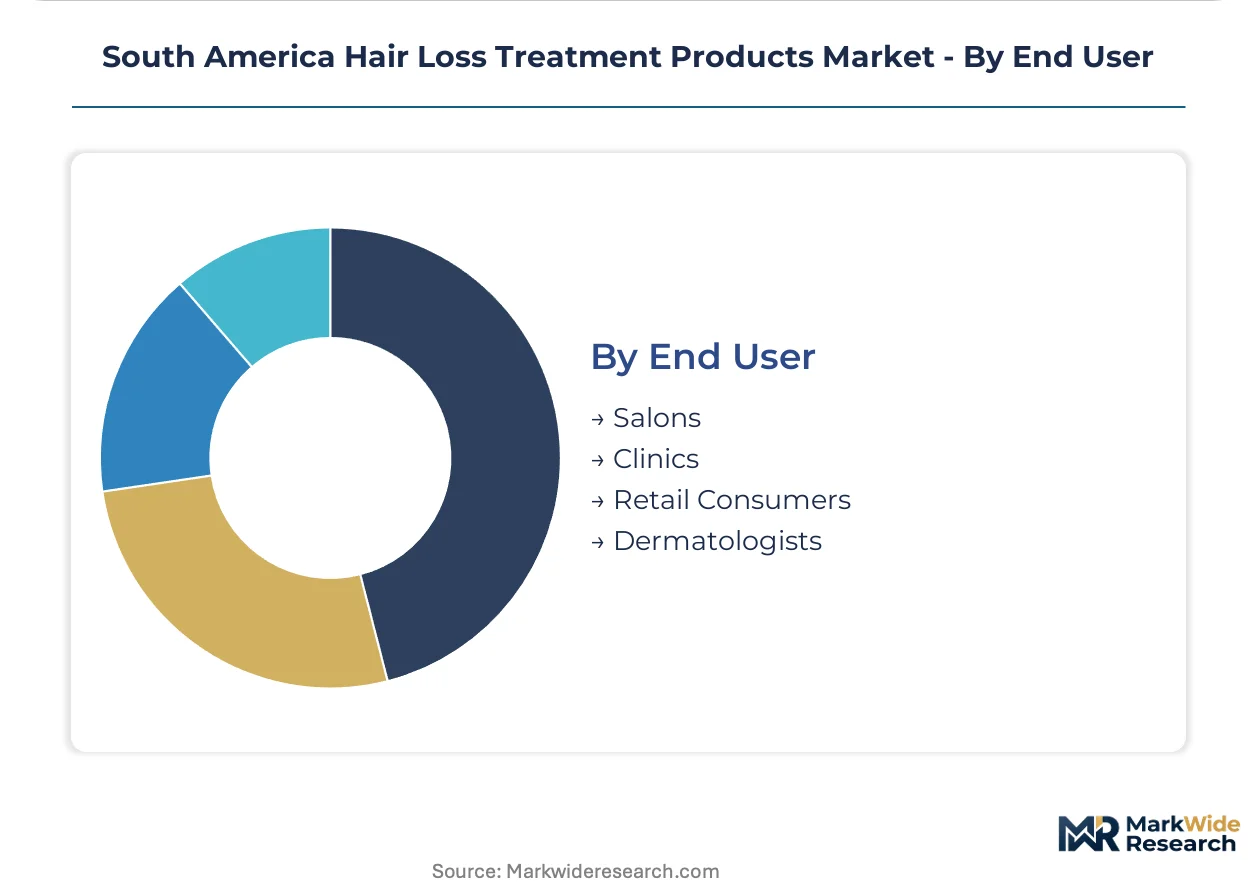
End User:
Channel evolution is fragmenting traditional distribution, with clinical settings decoupling from salon networks as patients prioritize protocol validation over convenience.
- Salons:Traditional beauty and barber establishments face declining relevance as clinical protocols displace cosmetic-only interventions. Brazilian salon networks struggle to retain male clients seeking prescription-grade solutions unavailable through non-medical channels.
- Clinics:Dermatology and aesthetic medicine centers are expanding service menus to include prescription-grade topical and oral therapies. São Paulo and Rio de Janeiro clinics absorb patient preference through combination treatment protocols pairing microneedling with growth factor serums.
- Retail Consumers:Direct-to-patient digital platforms and pharmacy counter purchases sustain mass-market minoxidil volume.
- Dermatologists:Specialist physicians control prescription finasteride access and influence protocol selection for complex cases.
Clinics command the highest revenue per patient interaction, with dermatologist-directed care climbing fastest as trichology specialization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting formulation sourcing toward Mercosur members with streamlined cosmetic registration pathways, while pharmaceutical-grade production concentrates where ANVISA's trial infrastructure supports extended efficacy studies.
Brazil
São Paulo's southeastern corridor absorbs the majority of prescription finasteride demand through telemedicine platforms and dermatology clinic networks. ANVISA's evolving cosmetic-pharmaceutical boundary regulations force manufacturers to choose between streamlined cosmetic claims or rigorous pharmaceutical trials. Rio de Janeiro's aesthetic medicine centers are expanding combination treatment protocols pairing microneedling with growth factor serums.
Argentina
Buenos Aires dermatology clinics report rising consultation volumes for female-pattern hair loss driven by postpartum telogen effluvium awareness. The national administration of drugs, foods and medical technology enforces standards that constrain cross-border formulation consistency with Brazilian counterparts. Córdoba's compounding pharmacy sector threatens prescription channel integrity with unregulated generic alternatives.
Chile
Santiago's affluent urban consumers are adopting low-level laser therapy devices as non-pharmacological maintenance options. The country's national pharmaceutical regulator maintains REACH-aligned toxicology documentation requirements for European-manufactured active ingredient imports. Valparaíso's pharmacy retail chains are developing private label minoxidil lines through regional API supplier partnerships.
Colombia
Bogotá's direct-to-consumer digital health startups are bypassing traditional dermatology clinic bottlenecks through remote finasteride prescriptions. Regulatory divergence from Mercosur standards forces dual-labeling investments that erode economies of scale for multi-country entrants. Medellín's aesthetic medicine spending is rising with minimal established clinic presence, offering first-mover positioning opportunities.
Peru
Lima's urban corridor shows expanding demand for protocol-based hair loss interventions among mid-income consumer segments. The country's national health authority observes Brazil's regulatory framework closely, suggesting harmonized standards may emerge within the forecast period. Arequipa's pharmacy networks sustain over-the-counter minoxidil volume through retail chain distribution.
South America Hair Loss Treatment Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade portfolios concentrating around prescription-controlled distribution while cosmetic-positioned alternatives fragment across retail and direct-sales channels. The market structure tiers between multinational registrants with ANVISA-approved pharmaceutical trials and regional formulators exploiting lighter cosmetic compliance burdens. Three archetypes dominate: established pharmaceutical companies with dermatology clinic partnerships, consumer goods conglomerates with pharmacy retail penetration, and direct-sales specialists with mid-income consumer reach. Competitive moves center on telemedicine platform integration for prescription access and private label co-manufacturing contracts with Brazilian retail chains.
Among multinational pharmaceutical registrants, Johnson & Johnson and Merck & Co. Inc. anchor the prescription-grade segment through contrasting channel strategies. Johnson & Johnson occupies a position exemplifying pharmacy-led mass-market penetration, while Merck & Co. Inc. represents the controlled-distribution archetype via regional distributor partnerships. Natura &Co sits within the direct-sales tier, leveraging its infrastructure to reach consumer segments that clinic-based brands rarely access. These three companies illustrate the market's tripartite competitive structure: pharmaceutical registrants, consumer goods conglomerates, and direct-sales specialists each defending distinct positioning through channel-specific advantages rather than direct product confrontation.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Merck & Co. Inc. |
| The Procter & Gamble Company |
| Dr Reddys Laboratories Ltd. |
| Cipla Inc. |
| L'Oreal SA |
| Natura &Co |
| Shiseido Co. Ltd. |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
REACH-aligned toxicology documentation gates qualified supply for European-manufactured active ingredients and anchors premium-tier pricing access for pharmaceutical-grade entrants serving Brazilian and Argentine dermatology networks. Manufacturers lacking compliant documentation face exclusion from prescription channels or relegation to cosmetic-class positioning with compressed margin structures.
Pricing Analysis
Distributor margins in Brazil's pharmacy retail networks absorb 25-35% of manufacturer price before patient purchase, while direct-to-consumer telemedicine platforms capture margin compression through subscription bundling. Three-tier pricing structure across premium clinic protocols, standard pharmacy lines, and economy private-label tiers stratifies by certification burden and channel control. Pricing pressure stems from Colombian and Chilean compounding pharmacies producing unregulated finasteride alternatives that undercut prescription integrity. Price-sensitive mid-income consumers in Peru and Ecuador gravitate toward direct-sales channels, while affluent São Paulo patients demonstrate low sensitivity to premium clinic-based combination therapies.
Supply Chain Analysis
Propylene glycol supply rests on petrochemical derivative production concentrated in the United States, China, and Saudi Arabia, with Brazilian formulators drawing from import-dependent stockpiles subject to currency fluctuation. Minoxidil API synthesis, finasteride raw materials, and botanical DHT blocker extracts constitute the core input dependencies. Single-source vulnerability in propylene glycol exposes Brazilian volume producers to margin compression when petrochemical feedstock costs spike. Distribution runs through São Paulo-based pharmaceutical wholesalers for prescription products, while cosmetic-positioned alternatives reach consumers via retail pharmacy chains and direct-sales infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ANVISA's pending DHT blocker reclassification will concentrate demand among established pharmaceutical registrants with compliant trial infrastructure.
For Market Incumbents: Extend clinic partnership networks into secondary Brazilian cities before trichology specialist scarcity hardens competitive moats. Backward integration into propylene glycol sourcing or captive API production buffers petrochemical cost volatility. Certification investment in REACH-aligned documentation preserves premium channel access as Argentine regulators harmonize toward Brazilian standards. For New Entrants and Emerging Players: Enter via telemedicine platform partnerships in Colombia and Peru where regulatory divergence has suppressed incumbent pharmaceutical presence. The most penetrable white space sits in Lima and Quito's protocol-based clinic segments with minimal established dermatology infrastructure. A direct-to-consumer subscription model with automated replenishment captures recurring revenue from affluent urban consumers seeking convenience over pharmacy counter purchases. For Investors and Strategic Acquirers: Roll-up economics work for regional API suppliers with ANVISA-registered manufacturing because pharmaceutical-class compliance burdens deter new capacity entry. Long-term viability favors acquisition targets with dual cosmetic-pharmaceutical registration capabilities spanning both regulatory pathways. The signal to watch is ANVISA's final DHT blocker reclassification ruling, which will trigger consolidation pressure on botanical-positioned brands lacking clinical data.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | São Paulo-based digital health startups bypass dermatology clinic bottlenecks for finasteride prescription velocity. |
| Private Label Co-Manufacturing | Brazilian retail pharmacy chains develop house-brand minoxidil lines through regional API supplier partnerships. |
| Low-Level Laser Device Convergence | Smartphone-connected diode arrays create premium positioning for tech-enabled hardware brands in Santiago. |
| Backward Integration into API Supply | Captive propylene glycol sourcing insulates Brazilian formulators from petrochemical derivative cost volatility. |
| Clinic Network Expansion | Protocol-based entrants capture first-mover positioning in Peruvian and Ecuadorian urban corridors with rising aesthetic medicine spending. |
Research Methodology
Coverage spans Brazil, Argentina, Chile, Colombia, and Peru, with primary inputs from each market's dermatology clinic operators, pharmaceutical distribution executives, ANVISA regulatory affairs specialists, and telemedicine platform founders. Secondary validation drew from ANVISA registration databases, Argentina's national drug administration filings, REACH compliance documentation, and customs records tracking active ingredient imports. Bottom-up patient volume estimates triangulated against top-down pharmaceutical sales data and clinic service revenue reporting.
Granularity-level modeling segmented the market by product type, application demographic, delivery mode, and end-user channel across national regulatory clusters with distinct registration pathways. CAGRs derived from patient population growth, treatment persistence rates, and price evolution assumptions through the projection horizon. Forecast inputs incorporated telemedicine prescription velocity trends, microneedling protocol adoption curves, and laser therapy device penetration patterns among affluent urban consumers.
The model holds under stable ANVISA regulatory interpretation; deviation in DHT blocker reclassification timing or Mercosur harmonization acceleration would shift competitive positioning and revenue allocation. Forecasts reflect documented assumptions regarding patient awareness campaign effectiveness and specialist physician training pipeline expansion. A small set of named triggers—ANVISA ruling finalization, propylene glycol supply disruption, and telemedicine regulatory clarity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Skin Tag Remover Market
Personal Health
Hair Restoration Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
Menstrual Cup Market
Personal Health
Obesity Treatment Market
Personal Health
Feminine Hygiene Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Health Coaching Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Infrared Sauna Blankets Market
Personal Health
Disposable Underwear Market
Personal Health
Tongue Scraper Market
Personal Health
Asia-Pacific Mobile Health Market