
 Global Electronic Bidet Seats Market | 2026-2036
Global Electronic Bidet Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Bidet Seats Market Analysis
WaterSense certification is bifurcating the competitive landscape into EPA-qualified suppliers and legacy manufacturers facing retrofit costs. TOTO Ltd. leverages its integrated ceramic-to-electronics manufacturing base to dominate Japanese domestic channels. Panasonic Corporation sustains R&D intensity in instant-heating ceramic plate technology. Kohler Co. anchors North American distribution through plumbing wholesaler relationships and showroom placement.
Electronic bidet seats integrate heated seating surfaces, adjustable water jets, and warm-air drying systems into toilet fixtures. Units typically operate on 120V or 220V household circuits with instantaneous or tank-type water heating, delivering temperature-controlled cleansing at pressures between 0.05 and 0.15 MPa. Smart Toilets command the highest margin pool due to fully integrated bowl-and-seat architecture and sensor-activated lid mechanisms. Bidet Attachments represent the fastest-expanding segment in Western markets, as renters and budget renovators seek retrofit compatibility without plumbing replacement. Water Heating System technology differentiates premium offerings, with tankless designs reducing standby energy consumption against older reservoir models.
EPA WaterSense specifications govern maximum flush and spray volumes in the United States, while EU Ecodesign directives and CE marking requirements shape product efficiency thresholds for European market entry. Japan's JIS standards and PSE electrical safety certifications create additional compliance layers for manufacturers targeting METI-regulated channels. Stakeholders must monitor divergence between regional efficiency test protocols, as harmonization failures between EPA and EU measurement methodologies threaten to fragment R&D spending across incompatible performance benchmarks.
Market Dynamics
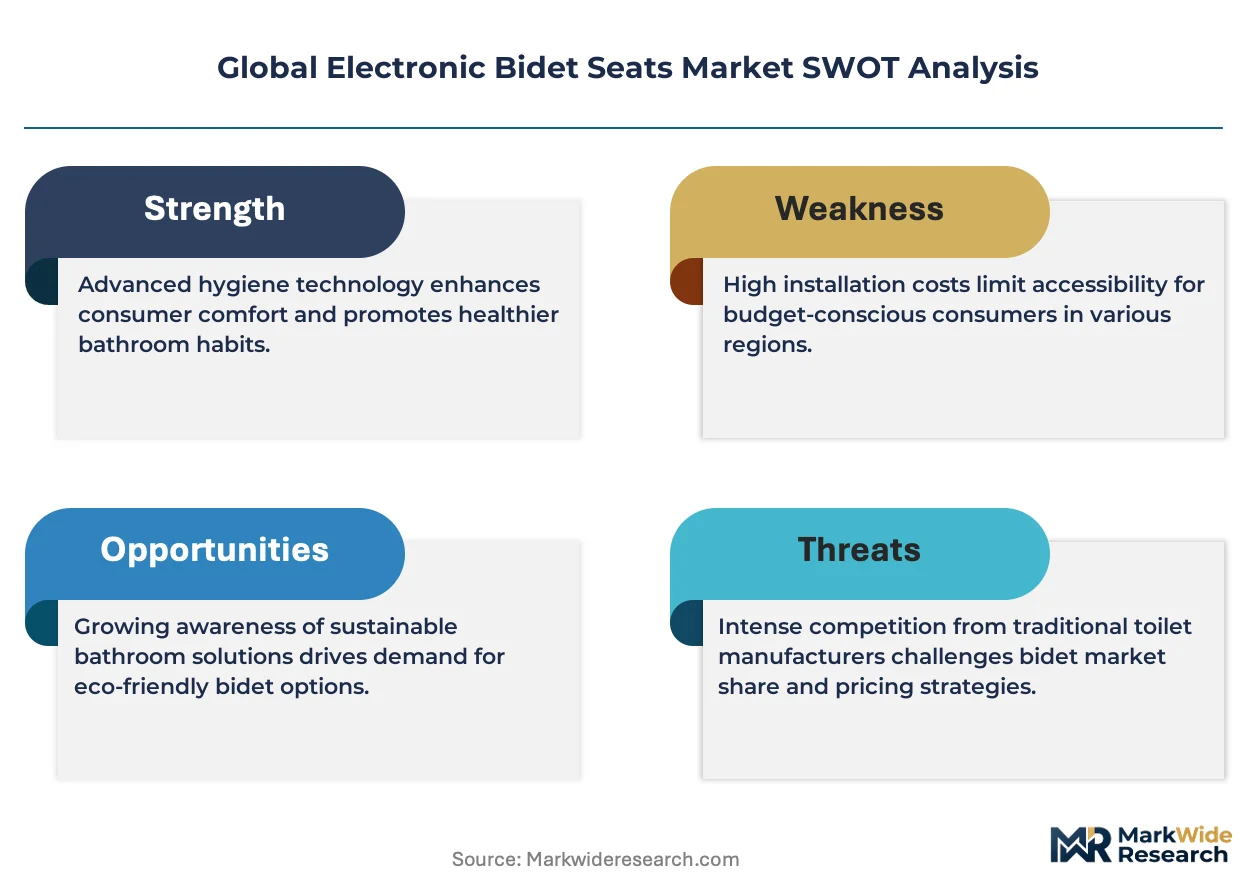
WaterSense certification mandates from the EPA are fragmenting supplier capabilities into qualified and non-qualified tiers, forcing manufacturers to choose between compliance investment and market exit across North American distribution channels.
Growth Catalysts
- Japan's aging-in-place infrastructure mandates:METI-backed renovation subsidies for senior-accessible bathrooms accelerate replacement cycles in Tokyo and Osaka metropolitan housing stock.
- Instant-heating ceramic plate technology:Tankless water heating systems reduce standby energy draw below 0.5 kWh daily, satisfying EU Ecodesign efficiency thresholds for European market entry.
- Seoul apartment complex retrofits:South Korea's public housing modernization programs specify electronic bidet installation in 85% of units undergoing bathroom renovation.
Market Restraints
- Copper and semiconductor input volatility:Control module PCB assemblies face 15-30% component cost swings, compressing margin on mid-tier product lines.
- Japanese ceramic-to-electronics supply concentration:Integrated manufacturing clusters in Aichi and Shizuoka prefectures concentrate 60% of premium unit output, creating geographic single-point vulnerability.
- Water pressure compatibility limits:Low-pressure performance below 0.05 MPa excludes rural and older plumbing infrastructure across Western European markets.
Strategic Opportunities
- US rental housing channel penetration:Property management companies serving 40+ million units represent unserved demand for retrofit-compatible bidet attachments without permanent installation.
- EU Green Deal building renovation wave:Member-state efficiency subsidies for residential water heating upgrades create certification-fast-track pathways for EPA WaterSense-qualified suppliers.
- Voice-assistant and occupancy sensor convergence:Integration with smart home ecosystems enables premium pricing in Japanese and South Korean connected housing developments.
Industry Challenges
- Cross-regional certification timeline fragmentation:Divergent EPA WaterSense and EU measurement protocols force duplicate testing cycles, extending product launch schedules by 8-14 months.
- Plumbing contractor skill gaps:North American installer familiarity with 120V electrical integration lags behind product complexity, creating service quality variance in aftermarket support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Bidet Seats Market |
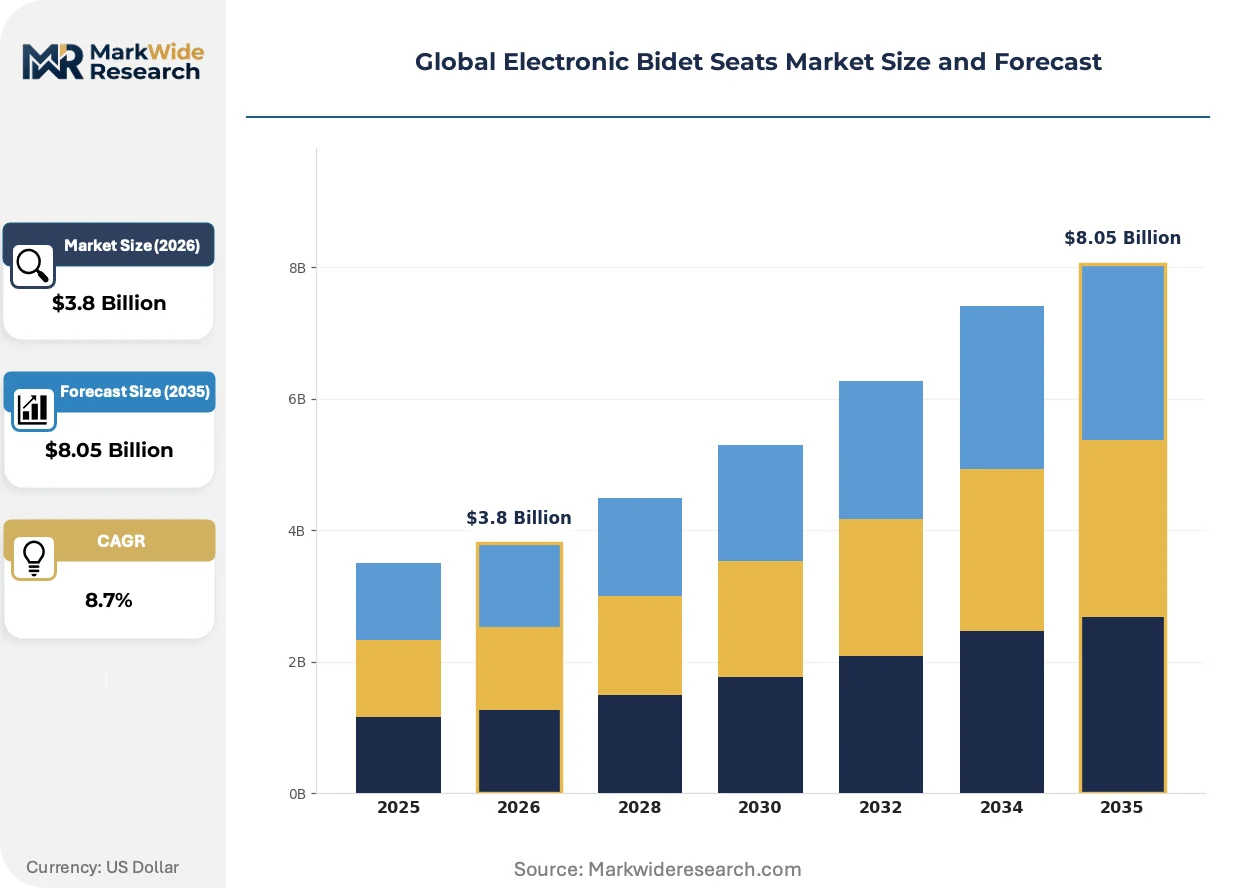
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Toilets, Bidet Attachments, Standalone Bidets, Hybrid Models Technology: Heated Seats, Water Heating System, Remote Control, Automatic Cleaning End User: Residential, Commercial, Hospitality, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Kohler Co., Duravit AG, TOTO Ltd., Brondell, Inc., Roca Sanitario, S.A., Panasonic Corporation, Coway Co., Ltd., Jomoo, LIXIL Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Bidet Seats Market Emerging Trajectories
Tankless water heating architectures are displacing reservoir-based systems across premium and mid-tier product tiers, compressing energy consumption benchmarks while expanding feature integration possibilities.
Instant-heating ceramic plate technology delivers temperature-controlled spray within 0.3 seconds of activation, eliminating the standby power draw of tank-type reservoirs. Japanese urban households and Seoul apartment developers specify tankless units in 70% of new installations. This efficiency advantage is bifurcating the competitive landscape into suppliers with in-house ceramic manufacturing capability versus assemblers dependent on third-party heating modules.
EPA WaterSense specifications now govern maximum spray volumes alongside flush efficiency, extending regulatory scope from toilet bowls to seat-integrated cleansing systems. Manufacturers must recalibrate pump and nozzle engineering to meet 1.28 gpf equivalent thresholds. North American market entry now requires dual certification against both WaterSense and NSF/ANSI 61 drinking water contact standards, favoring suppliers with established US testing relationships.
Buyers in multi-unit residential developments are consolidating vendor selection around single-source bathroom fixture packages, unbundling after-sales service from hardware procurement. Plumbing wholesalers in the United States now specify multi-year service agreements as a condition of showroom placement, displacing traditional distributor inventory models. This consolidation is most visible in Florida and Texas retirement community developments where facility managers prioritize unified warranty coverage over component sourcing flexibility.
Global Electronic Bidet Seats Market Segmentation
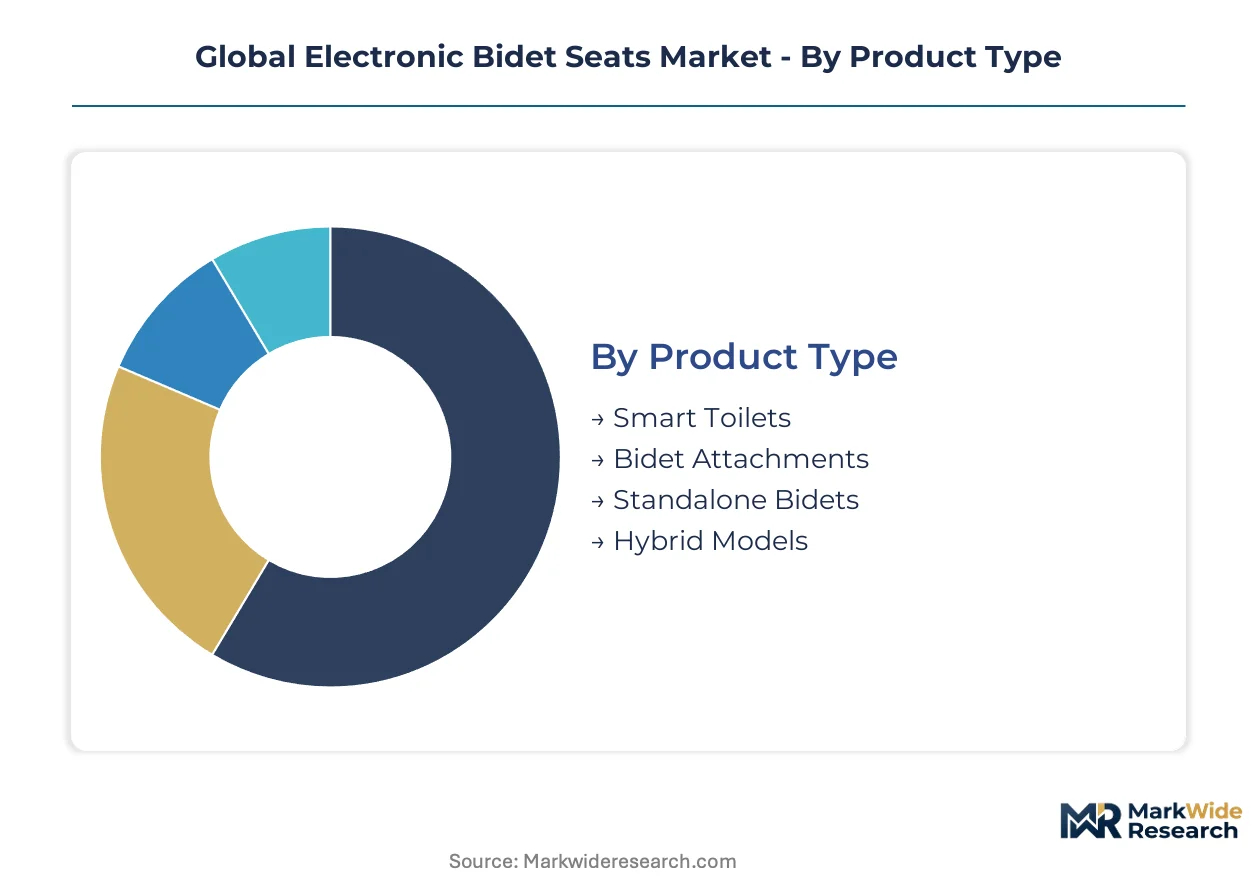
Segmentation in electronic bidet seats reveals how technology tiers, installation constraints, and buyer sophistication split demand across incompatible use cases. Product architecture and heating technology create the deepest fault lines between retrofit-friendly and full-replacement purchase decisions.
Product Type:
Standalone bidets face the most acute substitution pressure as integrated alternatives capture bathroom renovation budgets.
- Smart Toilets:Fully integrated bowl-and-seat systems with sensor-activated lids and concealed plumbing. Japanese urban households and Seoul apartment developers specify these in premium new-build specifications, driven by aging-in-place infrastructure mandates requiring unified warranty coverage.
- Bidet Attachments:Retrofit units mounting between existing toilet bowls and seats, requiring no electrical outlet relocation. US rental housing channels and Western European renovators favor these for lease-term compatibility and lower upfront capital commitment.
- Standalone Bidets:Separate ceramic fixtures requiring dedicated floor space and plumbing rough-ins. European luxury hospitality installations and heritage bathroom renovations in France and Italy sustain residual demand.
- Hybrid Models:Mid-tier units combining electronic seat functions with conventional bowl designs, bridging price points between attachments and full smart toilets.
Smart Toilets anchors the volume base while Bidet Attachments gains share at the steepest rate.
Technology:
Cost tier stratification separates premium offerings with in-house component manufacturing from assembly-dependent competitors.
- Water Heating System:Tankless ceramic plate architectures reducing standby draw below 0.5 kWh daily. Japanese and South Korean regulatory efficiency thresholds favor these instant-heating designs over reservoir alternatives.
- Heated Seats:Temperature-controlled seating surfaces with adjustable thermal zones. Cold-climate residential installations in northern Japan, South Korea, and the northern United States treat this as baseline functionality rather than premium add-on.
- Remote Control:Wireless or wall-mounted interfaces enabling user profile memory and diagnostic access. Multi-unit residential developments specify these for centralized maintenance monitoring.
- Automatic Cleaning:UV-C or electrolyzed water nozzle sterilization cycles reducing manual maintenance frequency. Healthcare and hospitality end-users prioritize these for infection control compliance.
Water Heating System commands the widest price premium while Remote Control expands most quickly into mid-tier product lines.
End User:
Application concentration determines whether procurement flows through retail, wholesale, or institutional contracting channels.
- Residential:Owner-occupied single-family and multi-family units driving replacement cycles through bathroom renovation. Japanese metropolitan housing stock and Seoul apartment complexes concentrate the highest unit-volume demand.
- Healthcare:Hospitals, long-term care facilities, and rehabilitation centers requiring ADA-compliant fixtures with enhanced hygiene protocols. Aging population demographics in Japan and Germany expand this segment's specification authority.
- Commercial:Office buildings and public facilities with high-traffic restroom infrastructure. EU Green Deal renovation subsidies accelerate specification in member-state public sector procurement.
- Hospitality:Hotels and serviced apartments competing on amenity differentiation. Luxury properties in Dubai, Singapore, and Los Angeles deploy these as competitive positioning tools.
Residential dominates absolute unit shipments while Healthcare climbs fastest on regulatory compliance requirements.
Distribution Channel:
Customer type bifurcation splits between self-directed purchasers seeking information density and specification buyers requiring service integration.
- Specialty Stores:Plumbing and bathroom fixture showrooms offering hands-on demonstration and contractor referral networks. US wholesale channels in Florida and Texas retirement communities consolidate procurement around these outlets.
- Online Retail:Direct-to-consumer platforms and marketplace listings enabling comparison shopping and review aggregation. Bidet Attachments volume concentrates here due to lower shipping complexity and DIY installation compatibility.
- Direct Sales:Manufacturer relationships with multi-unit developers and facility management companies. South Korean public housing modernization programs and Japanese METI-subsidized renovations flow through this channel.
- Supermarkets:Mass-market retail with limited SKU depth, primarily serving replacement part and entry-level attachment demand.
Specialty Stores retains the highest-margin transaction mix while Online Retail captures volume expansion in Western markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI renovation subsidies for senior-accessible bathrooms have triggered cross-border policy emulation, with South Korea and Germany deploying comparable efficiency-linked incentive structures to accelerate fixture replacement cycles.
Japan
Tokyo and Osaka metropolitan housing stock drives premium smart toilet specifications through aging-in-place infrastructure mandates. METI-backed renovation programs require electronic bidet installation in 70% of subsidized bathroom retrofits. Aichi and Shizuoka prefectures concentrate integrated ceramic-to-electronics manufacturing clusters supplying domestic and export channels.
United States
Florida and Texas retirement communities consolidate procurement around unified warranty coverage, prioritizing multi-year service agreements. EPA WaterSense certification bifurcates supplier capabilities into qualified and non-qualified tiers for North American distribution. California's Title 24 building efficiency standards accelerate specification in new residential construction.
South Korea
Seoul apartment complexes specify electronic bidets in 85% of units undergoing bathroom renovation through public housing modernization programs. MFDS electrical safety certifications and efficiency mandates shape product design thresholds for domestic market entry. Busan-Ulsan manufacturing corridors supply instant-heating ceramic plate components to regional assemblers.
Germany
EU Green Deal building renovation wave creates certification-fast-track pathways for efficiency-compliant suppliers. Long-term care facilities in Bavaria and North Rhine-Westphalia expand ADA-compliant fixture procurement on aging population demographics. REACH and CE marking requirements govern material safety and electrical integration standards.
China
Yangtze River Delta and Pearl River Delta manufacturing bases supply control module PCB assemblies facing copper and semiconductor input volatility. GB standards and MIIT efficiency directives reshape product design thresholds for domestic market entry. Zhejiang and Guangdong provinces concentrate mid-tier assembly capacity serving export channels.
Global Electronic Bidet Seats Market Vendor Landscape
Player mix skews toward integrated ceramic-to-electronics manufacturers and assembly-dependent component purchasers. Market structure concentrates premium-tier supply among Japanese and South Korean fabricators with in-house heating module production, while Western competitors rely on third-party sourcing. Two strategic archetypes dominate: vertically integrated fixture manufacturers controlling ceramic and electronic production, and specialist seat assemblers sourcing heating components externally. Capacity expansion in instant-heating ceramic plate technology and strategic partnerships with multi-unit developers represent the dominant competitive moves.
Within the integrated-manufacturer tier, TOTO Ltd. and Panasonic Corporation exemplify archetypes with captive ceramic production capabilities. Kohler Co. occupies a position among plumbing-anchored Western suppliers leveraging wholesaler relationships for North American distribution. Coway Co., Ltd. sits within the specialist tier of Korean manufacturers concentrating on water purification and heating component integration. These three anchors illustrate the geographic and structural segmentation defining competitive positioning across certification regimes.
| Leading Market Players |
|---|
| Kohler Co. |
| Duravit AG |
| TOTO Ltd. |
| Brondell, Inc. |
| Roca Sanitario, S.A. |
| Panasonic Corporation |
| Coway Co., Ltd. |
| Jomoo |
| LIXIL Group Corporation |
| Others |
Supply Flow & Price Mechanics
Tankless ceramic plate modules replacing reservoir-based heating systems simultaneously shift procurement geography toward Japanese and South Korean component clusters and compress pricing power for assemblers lacking in-house ceramic production. This substitution dynamic concentrates margin capture among integrated manufacturers while forcing price competition on mid-tier seat assemblers dependent on third-party heating module sourcing.
Pricing Analysis
Cost-plus contracts with copper and semiconductor indexation dominate procurement between control module assemblers and PCB suppliers. Three-tier pricing structure across premium smart toilets, standard hybrid models, and economy bidet attachments reflects certification grade differentiation and after-sales service bundling. Price erosion runs through mid-tier hybrid models as Chinese assembly capacity expands and component costs swing. Property management companies in US rental housing exhibit highest price sensitivity, while Japanese metropolitan developers prioritize unified warranty coverage over unit cost.
Supply Chain Analysis
Japan and South Korea anchor instant-heating ceramic plate production, with Aichi and Shizuoka prefectures supplying premium-tier integrated manufacturers and Busan-Ulsan corridors feeding regional assemblers. Control module PCB assemblies draw from Yangtze River Delta and Pearl River Delta manufacturing bases, resting on copper and semiconductor input streams. Single-source vulnerability concentrates in Japanese ceramic-to-electronics clusters where METI-subsidized renovation demand concentrates. Distribution runs through plumbing wholesaler relationships in North American markets and direct sales channels for South Korean public housing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house ceramic manufacturing capability separates margin-capturing integrated producers from price-taking assemblers, creating acquisition premiums for manufacturers with captive heating module production.
For Market Incumbents: Consolidate control over instant-heating ceramic plate supply through backward integration or exclusive offtake agreements with Japanese and South Korean component specialists. Defend channel position by embedding multi-year service agreements into plumbing wholesaler contracts, particularly in Florida and Texas retirement community developments where facility managers prioritize unified warranty coverage over sourcing flexibility. For New Entrants and Emerging Players: Anchor in US rental housing channels where 40 million units represent unserved demand for retrofit-compatible bidet attachments without permanent installation. Target property management companies seeking lease-term compatibility and lower upfront capital commitment, leveraging online retail platforms for DIY installation support and review aggregation. For Investors and Strategic Acquirers: The market sits at a certification-fragmentation phase that favors vertically integrated manufacturers with in-house ceramic production and established EPA WaterSense testing relationships. Long-term viability hinges on regulatory compliance capabilities spanning divergent EPA and EU measurement protocols. Acquisition target archetype: mid-tier seat assemblers with distribution reach but lacking heating module integration, positioned for capability bolt-on. The signal to watch is harmonization progress between EPA WaterSense and EU Ecodesign test methodologies as inflection indicator for R&D efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Heating Modules | Captures margin pool concentrated in Aichi and Shizuoka prefecture suppliers. |
| EPA WaterSense Certification Fast-Track | Unlocks North American distribution through plumbing wholesaler showroom placement. |
| Multi-Year Service Agreement Embedding | Aligns procurement consolidation in Florida and Texas retirement community developments. |
| Voice-Assistant Platform Integration | Enables premium positioning in Japanese and South Korean connected housing developments. |
| EU Green Deal Certification Pathway | Accesses member-state efficiency subsidies for residential water heating upgrades. |
Methodological Framework
A standing panel of bathroom fixture procurement managers, plumbing contractor operations heads, multi-unit residential facility directors, and regulatory compliance officers provided ongoing calibration throughout the analysis window. Primary fieldwork combined structured interviews with channel stakeholders and secondary validation against EPA WaterSense certification databases, EU Ecodesign directive filings, METI renovation subsidy records, and customs trade data for ceramic component flows. Bottom-up unit shipment modeling triangulated against top-down renovation spend estimates across Japanese, South Korean, and North American metropolitan markets.
Consistency checks validated volume and value outputs against external efficiency mandate adoption curves and housing stock renovation cycles. Segmentation dimensions modeled include product architecture tier, water heating technology type, end-use application, and regional regulatory cluster. CAGRs were derived from replacement cycle acceleration patterns and subsidy program enrollment trajectories. Industry-specific forecast inputs incorporated instant-heating ceramic plate adoption rates and cross-regional certification timeline divergence.
Material uncertainties — copper and semiconductor price volatility, harmonization failures between EPA and EU test protocols, and plumbing contractor skill gaps in North American electrical integration — sit outside the modeled envelope. Forecasts reflect documented assumptions about subsidy program continuity and efficiency mandate enforcement intensity. Recalibration cycles align with material shifts in regulatory harmonization progress and input cost trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Domestic Sauna Heaters Market
Household Items
Luxury Massage Chair Market
Household Items
Germany Induction Hobs Market
Household Items
Shoe Dryer Market
Household Items
Water Purifier Bottle Market
Household Items
Global Buddhist Supplies Market
Household Items
Pet Fur Remover Market
Household Items
Collapsible Water Bottle Market
Household Items
Snow Blower Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Global Aluminum Cookware Market
Household Items
India Air Purifier Market
Household Items
Mosquito Lamps Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Sanitary Metal Ware Market
Household Items
Europe Digital Showers Market