
 Air Care Market | 2026-2036
Air Care Market Size, Share, and Industry Trends Forecast 2026-2036
Air Care Market Analysis
Commercial buyers in the hospitality and healthcare facility segments are rotating toward higher-performance air care systems as post-pandemic indoor air quality standards harden. Procter & Gamble leverages its retail shelf dominance and brand equity to sustain volume leadership in mass-market aerosols and plug-in formats. S.C. Johnson & Son anchors its position through concentrated R&D investment in natural fragrance chemistry and sustainable packaging architectures. Reckitt Benckiser competes aggressively on clinical efficacy claims, positioning its odor elimination portfolio for premium commercial contracts.
Air care encompasses devices and formulations engineered to modify indoor atmospheric quality through fragrance dispersion, particulate filtration, or molecular odor neutralization, typically employing substrates such as activated carbon media with surface areas exceeding 500 square meters per gram or HEPA membranes rated at 99.97% efficiency for 0.3-micron particles. The product type dimension shows air purifiers capturing the fastest expansion as consumer awareness of PM2.5 and allergen exposure intensifies, while essential oil diffusers concentrate margin pools through recurring consumable attachment. Technology segmentation reveals activated carbon and HEPA filter combinations dominating commercial and industrial application tiers, whereas ionic systems face structural pressure from ozone emission scrutiny.
The EPA regulates volatile organic compound emissions from consumer products under 40 CFR Part 59, constraining aerosol propellant formulations and spray delivery chemistries, while the EU REACH framework imposes registration and restriction protocols on fragrance allergens and persistent organic compounds. The FDA exercises indirect influence through indoor air quality guidance for healthcare facilities, shaping demand specifications for hospital-grade purification equipment. Stakeholders must monitor the trajectory of chemical disclosure mandates and filter efficiency certification harmonization between North American and European testing protocols to anticipate compliance-driven product redesign cycles.
Market Dynamics
Post-pandemic indoor air quality mandates are hardening procurement specifications across hospitality, healthcare, and commercial real estate, compressing vendor qualification timelines and elevating filtration efficiency thresholds as baseline bid requirements.
Growth Catalysts
- EU REACH chemical disclosure:Formulation transparency requirements are accelerating R&D investment in bio-based fragrance substrates and low-VOC propellant systems among European manufacturers.
- Connected diffuser hardware:WiFi-enabled devices with consumable subscription models are capturing recurring revenue pools in urban Chinese and South Korean households.
- HEPA-activated carbon stacking:Hospital and hotel engineering teams specify multi-stage filtration architectures that combine 99.97% particle capture with molecular odor adsorption.
Market Restraints
- Activated carbon feedstock volatility:Coconut shell and coal-derived carbon prices fluctuate with agricultural yield cycles and mining permitting delays in Southeast Asian supply basins.
- Ozone emission scrutiny:Ionic and electrostatic precipitation technologies face structural pressure from EPA indoor air quality guidance and California Air Resources Board certification thresholds.
- Fragrance allergen labeling:EU regulation (EC) No 1223/2009 and state-level US disclosure laws are constraining formulation flexibility and extending product development timelines.
Strategic Opportunities
- India tier-2 urbanization:Rising disposable incomes in cities such as Pune and Ahmedabad are creating first-time buyer segments for mid-range purification devices.
- Building-integrated air care:HVAC-embedded scent diffusion and filtration modules are penetrating premium commercial construction projects in the UAE and Saudi Arabia.
- Refillable pod systems:Closed-loop consumable architectures align with extended producer responsibility frameworks emerging under the EU Green Deal and UK Plastic Packaging Tax.
Industry Challenges
- Filter certification harmonization:Divergent testing protocols between AHAM (US) and EN (European) standards force dual qualification investments for cross-border suppliers.
- Embedded firmware security:Connected device manufacturers face escalating cybersecurity audit requirements from national regulators and enterprise procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Care Market |
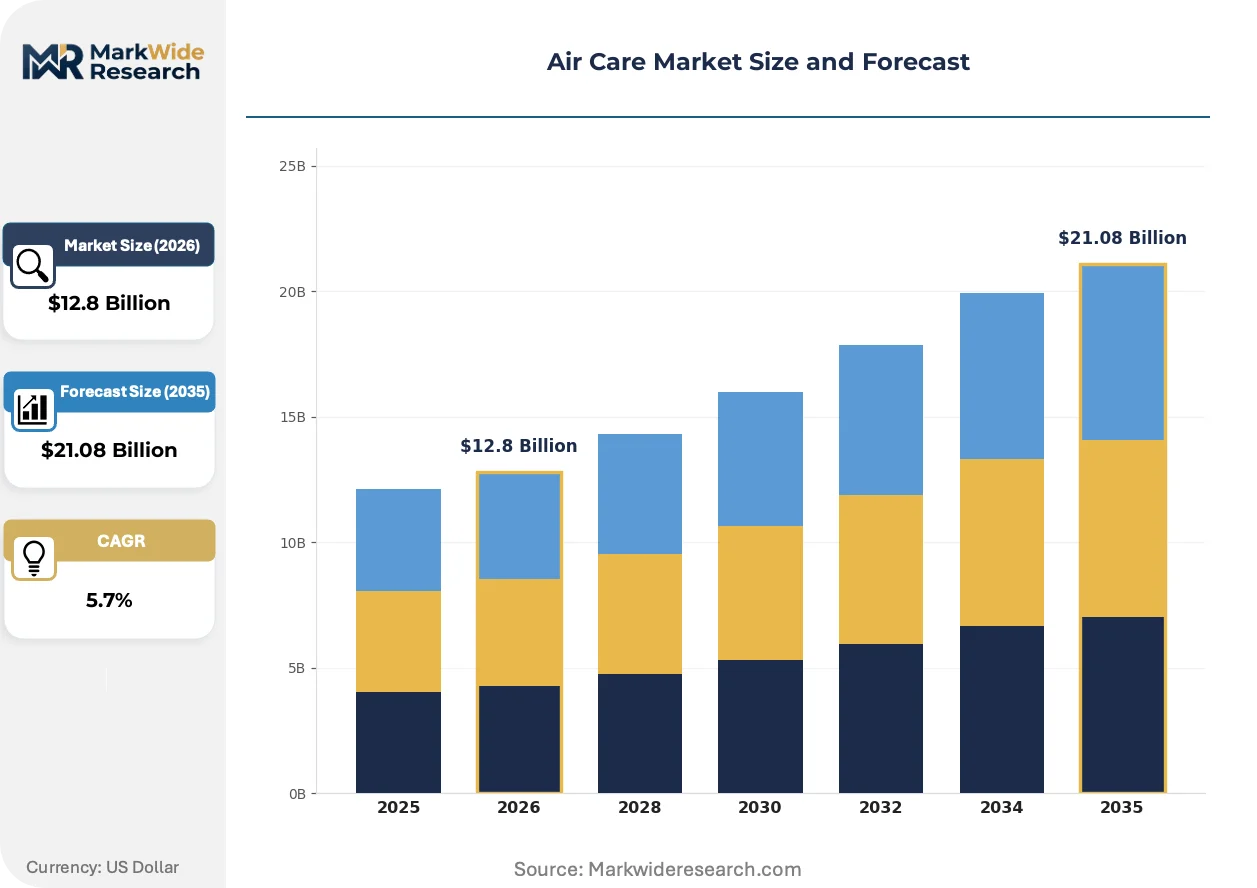
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Fresheners, Air Purifiers, Essential Oil Diffusers, Odor Eliminators Technology: HEPA Filters, Activated Carbon, Ionic, UV Light Application: Residential, Commercial, Automotive, Industrial End User: Households, Offices, Healthcare Facilities, Restaurants |
| Companies Covered | Procter & Gamble, Reckitt Benckiser Group PLC, S.C. Johnson & Son, Inc., Henkel AG & Co. KGaA, Church & Dwight Co. Inc., Newell Brands, Godrej Consumer Products Ltd., Bath & Body Works, Car-Freshner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Care Market Emerging Trajectories
Solid-state fragrance delivery and intelligent environmental sensing are compressing hardware footprints while expanding addressable use cases beyond traditional residential and commercial installations.
Electrochemical odor detection arrays paired with micro-dispersion pumps are miniaturizing. Automotive OEMs and aircraft cabin integrators are embedding these systems at scale. The technology is miniaturizing personal air care into wearables and portable enclosures previously inaccessible to active fragrance systems.
EPA enforcement of 40 CFR Part 59 volatile organic compound limits is tightening aerosol propellant chemistries. Reformulation costs are concentrating supplier relationships around compliant hydrocarbon and compressed gas alternatives. Mass-market spray categories in the United States are experiencing the most acute compliance-driven product redesign cycles.
Facility management teams are consolidating vendor relationships around full-service indoor air quality contracts. Single-source accountability for equipment, consumables, and maintenance is displacing fragmented procurement of standalone devices. This pattern is most visible in North American healthcare systems and European hospitality chains pursuing LEED and WELL certification.
Air Care Market Segmentation
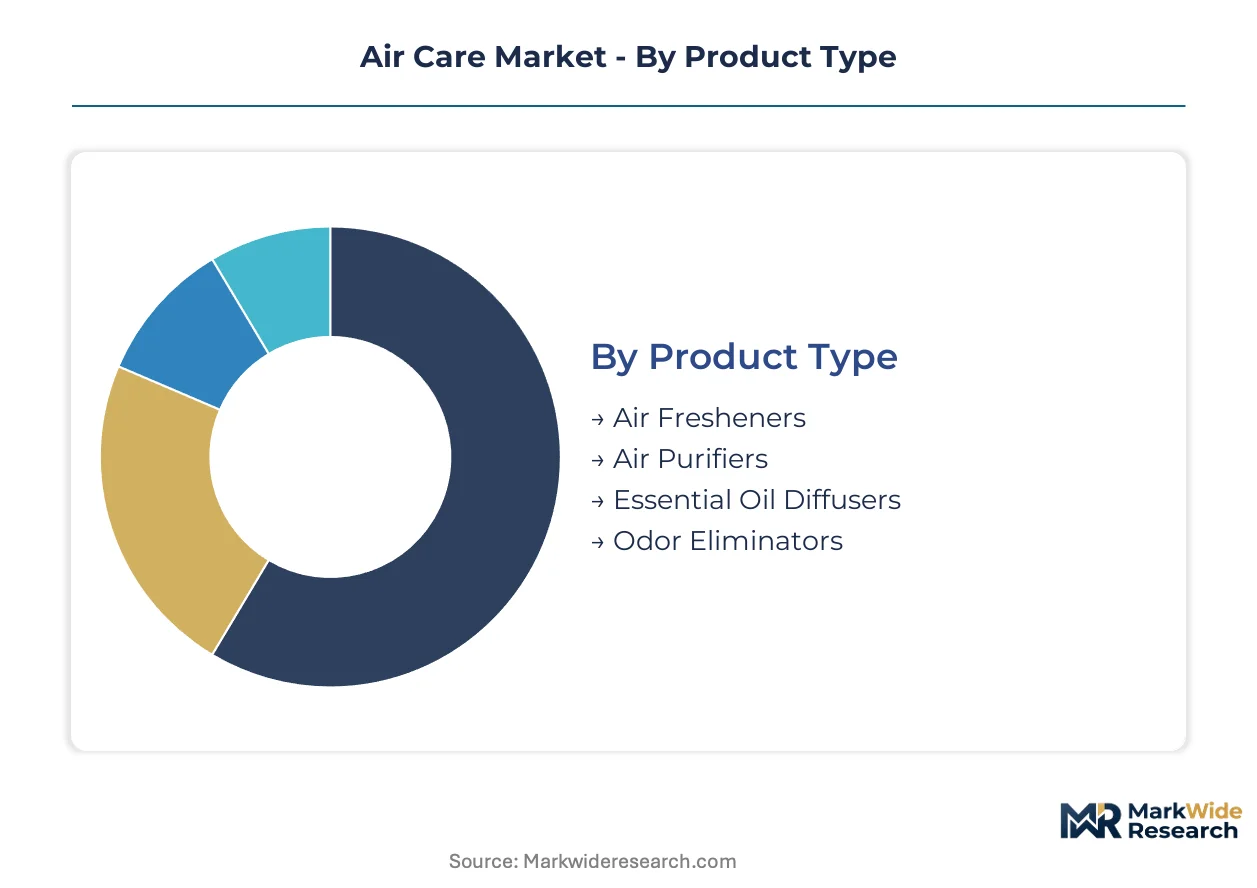
Segmentation in air care reveals divergent margin architectures across hardware and consumable formats. Technology choices determine capital intensity and recurring revenue potential, while application contexts dictate certification requirements and procurement cycles.
Product Type:
Margin pools concentrate in devices with attached consumable streams rather than one-time hardware sales.
- Air Fresheners:Aerosol and gel formats dominate mass retail through low price points and impulse purchase placement. EU REACH volatile organic compound limits are forcing propellant reformulation investments that compress margins for European suppliers.
- Air Purifiers:HEPA-activated carbon stacking architectures command premium pricing in hospital and hotel engineering specifications. Demand concentrates in Chinese urban households where PM2.5 awareness drives replacement filter subscriptions.
- Essential Oil Diffusers:Ultrasonic and nebulizing devices generate recurring revenue through proprietary oil pod systems. WiFi-enabled models with mobile app control are penetrating South Korean and Japanese residential markets.
- Odor Eliminators:Molecular neutralization formulations serve commercial kitchens, waste facilities, and veterinary clinics. Enzyme-based and oxidizing chemistries face EPA 40 CFR Part 59 compliance scrutiny on emission profiles.
The dominant share belongs to Air Fresheners, while Air Purifiers is closing the gap fastest.
Technology:
Certification complexity varies sharply across purification mechanisms, with stacked multi-stage systems commanding specification premiums.
- HEPA Filters:Fibrous media rated at 99.97% efficiency for 0.3-micron particles anchor hospital-grade and cleanroom applications. AHAM and EN standard harmonization gaps force dual testing investments for cross-border suppliers.
- Activated Carbon:Coconut shell and coal-derived substrates with surface areas exceeding 500 square meters per gram adsorb molecular odors and volatile organic compounds. Feedstock price volatility from Southeast Asian agricultural yields and mining permits constrains margin stability.
- Ionic:Electrostatic precipitation systems face structural pressure from California Air Resources Board ozone emission thresholds and EPA indoor air quality guidance.
- UV Light:Germicidal irradiation at 254 nanometers targets biological contaminants in HVAC-embedded and portable configurations. Healthcare facility procurement teams prioritize units with documented kill-rate validation against antibiotic-resistant pathogens.
HEPA Filters retains the largest installed base, though Activated Carbon is expanding most quickly through multi-stage stacking architectures.
Application:
Volume concentration sits in residential replacement cycles, while commercial contracts deliver longer tenure and service attach rates.
- Residential:Single-unit purchases dominate through retail and direct-to-consumer channels. Connected device adoption is highest in Chinese and South Korean urban middle-class households.
- Commercial:Facility management consolidation around full-service indoor air quality contracts is displacing fragmented device procurement. LEED and WELL certification requirements in North American and European hospitality chains elevate specification thresholds.
- Automotive:Cabin air filtration and scent diffusion integrate into HVAC systems at the OEM tier. Solid-state electrochemical sensors with micro-dispersion pumps are miniaturizing for premium vehicle segments.
- Industrial:High-volume particulate and chemical vapor extraction serves manufacturing, warehousing, and waste processing environments. Activated carbon bed systems with regeneration capabilities reduce long-term consumable costs.
Residential claims the highest unit volume, but Commercial is gaining share fastest through vendor consolidation and certification-driven upgrades.
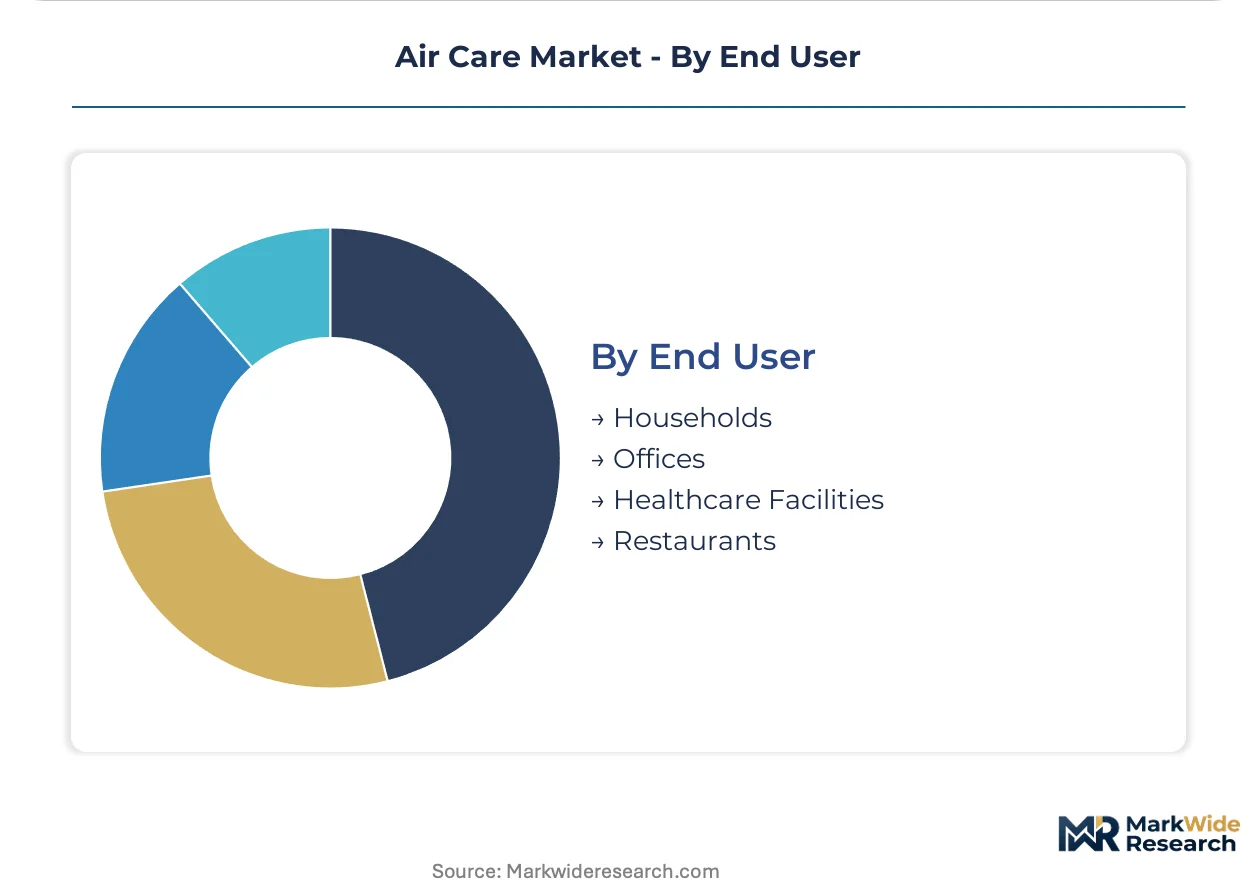
End User:
Procurement sophistication escalates from household discretionary purchase to institutional specification compliance.
- Households:Price-sensitive mass-market demand concentrates in spray and plug-in formats. Subscription diffuser models are penetrating connected-home adopters.
- Offices:Corporate real estate teams specify building-integrated scent diffusion and filtration for tenant experience differentiation. Post-pandemic indoor air quality mandates harden filtration efficiency baselines.
- Healthcare Facilities:FDA indoor air quality guidance shapes demand for hospital-grade purification with documented pathogen capture validation. Filter replacement protocols align with infection control committee schedules.
- Restaurants:Odor elimination systems address kitchen exhaust and dining room ambient scent as branded guest experience priorities. Procurement teams specify molecular neutralization over masking fragrances.
Households represents the broadest addressable base, yet Healthcare Facilities is climbing the fastest as clinical efficacy claims concentrate vendor selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German air care manufacturers export HEPA-activated carbon systems to Chinese hospitality chains, while South Korean connected diffuser brands penetrate Japanese and Southeast Asian retail channels.
United States
Healthcare facility procurement teams specify hospital-grade purification equipment under FDA indoor air quality guidance. EPA 40 CFR Part 59 constrains aerosol propellant formulations, forcing reformulation investments. California's Air Resources Board ozone thresholds pressure ionic technology suppliers in Los Angeles and San Francisco industrial corridors.
China
Urban middle-class households in Shanghai and Beijing drive premium adoption of WiFi-enabled diffusers and HEPA-based devices. MIIT standards and MEE dual carbon goals shape manufacturing compliance requirements. Yangtze River Delta electronics clusters concentrate connected hardware assembly for domestic and export markets.
Germany
EU REACH chemical disclosure mandates accelerate R&D in bio-based fragrance substrates and low-VOC propellants. ECHA registration protocols constrain formulation flexibility for aerosol manufacturers. North Rhine-Westphalia chemical parks host concentrated production of activated carbon media and filtration membranes.
Japan
Residential demand concentrates in ultrasonic and nebulizing essential oil diffusers with mobile app integration. METI energy efficiency standards shape device power consumption specifications. Osaka-Kansai manufacturing clusters produce compact solid-state electrochemical sensors for automotive and aircraft cabin integration.
India
Rising disposable incomes in Pune and Ahmedabad create first-time buyer segments for mid-range purification devices. BIS certification requirements and DGFT import regulations shape competitive dynamics for foreign suppliers. Maharashtra industrial zones concentrate domestic assembly of HEPA filter housings and activated carbon cartridges.
Air Care Market Vendor Landscape
Listed leaders compete with private specialists across formulation chemistry and connected hardware dimensions. The vendor base stratifies into three tiers: multinational FMCG conglomerates with retail shelf dominance, regional specialists with regulatory proximity advantages, and emerging connected-device startups with subscription revenue models. Consolidation pressure concentrates around natural fragrance chemistry capabilities and sustainable packaging architectures. Dominant competitive moves include strategic partnerships for refillable pod systems and geographic expansion into Indian tier-2 cities.
Within the multinational conglomerate tier, Procter & Gamble, Reckitt Benckiser Group PLC, and S.C. Johnson & Son, Inc. exemplify scale-driven positioning. Procter & Gamble anchors mass-market aerosol and plug-in formats through retail distribution depth. Reckitt Benckiser occupies a position emphasizing clinical efficacy claims for commercial contract pursuit. S.C. Johnson & Son sits within the sustainability-focused archetype, representing concentrated investment in natural fragrance substrates.
| Leading Market Players |
|---|
| Procter & Gamble |
| Reckitt Benckiser Group PLC |
| S.C. Johnson & Son, Inc. |
| Henkel AG & Co. KGaA |
| Church & Dwight Co. Inc. |
| Newell Brands |
| Godrej Consumer Products Ltd. |
| Bath & Body Works |
| Car-Freshner Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term filter replacement contracts lock in supply access for activated carbon and HEPA membrane suppliers while anchoring price visibility for hospitality and healthcare procurement teams navigating EU REACH compliance costs and Southeast Asian feedstock volatility.
Pricing Analysis
Current-generation HEPA-activated carbon stacking commands premium positioning against prior-generation single-stage ionic systems and emerging next-generation solid-state electrochemical arrays. Three-tier pricing structure across premium hospital-grade, standard commercial, and economy residential levels differentiates on AHAM certification tier and after-sales service bundling. Cost compression in mass-market aerosol formats is intensifying because EPA 40 CFR Part 59 reformulation investments compress margins without commensurate price recovery. Household buyers exhibit highest price sensitivity, while healthcare facility procurement teams prioritize clinical efficacy validation over unit cost.
Supply Chain Analysis
Strategic stockpiling of coconut shell activated carbon prevails among German and Chinese filtration manufacturers confronting agricultural yield volatility, while just-in-time assembly dominates Yangtze River Delta connected diffuser production. Feedstock dependence draws from Indonesian coconut plantations, North Rhine-Westphalia chemical synthesis clusters, and Zhejiang province electronics component basins. Single-source vulnerability concentrates in Southeast Asian activated carbon preprocessing where mining permit delays cascade through multi-stage filtration supply chains. Distribution runs through specialized HVAC contractors in commercial segments and mass retail chains in residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor fragmentation across formulation chemistry and connected hardware creates entry niches as facility management consolidation demands single-source accountability for equipment, consumables, and maintenance contracts.
For Market Incumbents: Secure backward integration into activated carbon feedstock processing to buffer margin volatility from Southeast Asian agricultural yield cycles. Deepen certification investments in dual AHAM-EN standard harmonization to compress cross-border qualification timelines for hospital and hotel engineering specifications. For New Entrants and Emerging Players: Anchor in India's tier-2 urbanization corridors—Pune and Ahmedabad—where first-time buyer segments for mid-range purification devices remain underpenetrated by multinational FMCG conglomerates. Pursue building-integrated air care partnerships with UAE and Saudi Arabian premium commercial construction developers specifying HVAC-embedded scent diffusion modules. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected diffuser hardware manufacturers with proprietary oil pod subscription models in South Korean and Japanese residential markets. Acquisition targets with natural fragrance chemistry capabilities and sustainable packaging architectures align with extended producer responsibility frameworks emerging under EU Green Deal compliance timelines. Watch for EPA enforcement intensity on 40 CFR Part 59 volatile organic compound limits as inflection indicator for mass-market spray category restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Refillable Pod System Development | Closed-loop consumable architectures align with UK Plastic Packaging Tax and EU extended producer responsibility mandates. |
| Dual Certification Investment | Simultaneous AHAM and EN standard qualification compresses vendor approval timelines for cross-border hospital contracts. |
| Natural Fragrance Chemistry Acquisition | Bio-based substrate capabilities differentiate against Reckitt Benckiser clinical efficacy positioning and S.C. Johnson sustainability investments. |
| Connected Hardware Platform Launch | WiFi-enabled diffusers with mobile app control capture recurring revenue pools in Shanghai and Beijing urban middle-class households. |
| HVAC-Embedded Module Partnership | Integration into premium commercial construction projects in Dubai and Riyadh leverages WELL certification requirements. |
Methodological Framework
A standing panel of facility management directors, hospital infection control committee members, HVAC contractor procurement leads, and retail category buyers provided ongoing calibration against secondary validation from EPA 40 CFR regulatory filings, EU ECHA registration databases, MIIT equipment standards disclosures, and customs trade data on activated carbon imports. Bottom-up demand modeling across product type, technology, application, and end user segments triangulated with top-down market sizing from manufacturer revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include device format, filtration mechanism, installation context, and procurement sophistication tier. CAGRs derived from replacement cycle analysis, urbanization penetration curves, and regulatory compliance-driven upgrade timelines. Industry-specific forecast inputs incorporated PM2.5 awareness indices in Chinese metropolitan areas and LEED certification adoption rates in North American commercial real estate.
Material uncertainties—activated carbon feedstock price shocks, EPA enforcement intensity variations, and harmonization delays between AHAM and EN testing protocols—sit outside the modeled envelope. Forecasts reflect assumptions on urban middle-class disposable income trajectories and hospitality sector capital expenditure recovery patterns. Revision becomes warranted when coconut shell agricultural yield volatility or EU REACH chemical disclosure expansion crosses thresholds that fundamentally alter formulation cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Dishwasher Tablets Market
Household Items
US Air Purifier Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
Global Tableware Market
Household Items
Window Rain Guards Market
Household Items
Toilet Cistern Blocks Market
Household Items
Electric Mop Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Air Mattress Market
Household Items
Toilet Paper Market
Household Items
Residential Water Purifier Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
North America Water Purifier Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Electric Brooms Market