
 Bagless Vacuum Cleaner Market | 2026-2036
Bagless Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Bagless Vacuum Cleaner Market Analytics
Multi-source motor procurement is hardening as a competitive necessity among bagless vacuum manufacturers seeking cost resilience against rare-earth price swings. Dyson sustains in-house cyclone R&D intensity across its Singapore and UK engineering centers. SharkNinja leverages direct-to-consumer channel control to dominate North American stick-vacuum volume. Miele anchors premium canister positioning through German manufacturing scale and component traceability.
A bagless vacuum cleaner employs cyclonic or multi-cyclonic airflow separation to extract particulate matter without disposable bags, typically incorporating pleated HEPA media rated at 99.97% efficiency at 0.3 microns to capture allergens and fine dust. The primary commercial purpose centers on reducing consumable costs and improving suction consistency across the product lifespan. Robotic units represent the fastest-expanding product type as autonomous navigation and LiDAR mapping migrate from premium to mid-tier price bands. HEPA Filtration technology commands the strongest margin pool due to certification requirements in healthcare and hospitality end-user segments. Stick formats lead household penetration in dense urban dwellings where storage constraints favor compact architectures.
EU Ecodesign and REACH frameworks govern motor efficiency thresholds and restricted substances in plastics and electronics, compelling manufacturers to reformulate housing polymers and redesign airflow paths. The US EPA Energy Star program and California Air Resources Board indoor air quality guidelines shape filtration performance claims and test protocol alignment for products sold in North America. Stakeholders must monitor evolving cordless battery regulations and right-to-repair legislation across multiple jurisdictions to anticipate compliance-driven redesign cycles and aftermarket service obligations.
Market Dynamics
Cordless stick vacuum architectures are compressing replacement cycles as lithium-ion energy density improvements enable runtime parity with corded units, while EU Ecodesign motor efficiency mandates force simultaneous redesigns of airflow systems and filtration media.
Growth Catalysts
- EU Ecodesign motor efficiency mandates:Tiered minimum efficiency requirements for universal motors and brushless DC variants compel manufacturers to redesign stator windings and rotor geometries, accelerating technology turnover in the installed base.
- Healthcare and hospitality certification requirements:HEPA filtration specifications for allergen containment in clinical and hotel environments create premium pricing power for certified units, expanding addressable margin pools beyond residential segments.
- Urban household storage constraints:Dense residential clusters in Tokyo, London, and New York favor compact stick formats over canister designs, concentrating demand for wall-mountable, lightweight architectures.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings concentrated in Chinese processing facilities compress margins on brushless motor production, forcing multi-source procurement strategies.
- REACH substance restrictions:ECHA limitations on phthalates and flame retardants in housing polymers require reformulation of ABS and polycarbonate blends, extending qualification timelines for new material sets.
- Robotic vacuum substitution:Autonomous navigation platforms with LiDAR mapping capture floor-cleaning tasks without human operation, eroding manual stick vacuum utility in single-story dwellings.
Strategic Opportunities
- India urban middle-class expansion:Metro clusters in Mumbai, Delhi, and Bangalore exhibit underpenetration of bagless formats relative to traditional broom-and-dustpan habits, creating first-mover positioning for cordless stick entrants.
- Right-to-repair legislative tailwinds:French repairability index mandates and proposed EU-wide frameworks incentivize modular battery and motor designs that extend product lifespans through component replacement rather than full unit discard.
- LiDAR and vSLAM convergence:Integration of visual simultaneous localization with laser ranging is enabling mid-tier robotic units to navigate complex furniture layouts previously requiring premium sensor suites.
Industry Challenges
- Brushless motor control firmware expertise:Scarcity of embedded systems engineers proficient in field-oriented control algorithms for high-speed motor drives extends development timelines for cordless platform launches.
- Multi-jurisdiction certification timelines:Divergent test protocols between EPA Energy Star, EU Ecodesign, and Japan's Top Runner programs require parallel validation streams, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bagless Vacuum Cleaner Market |
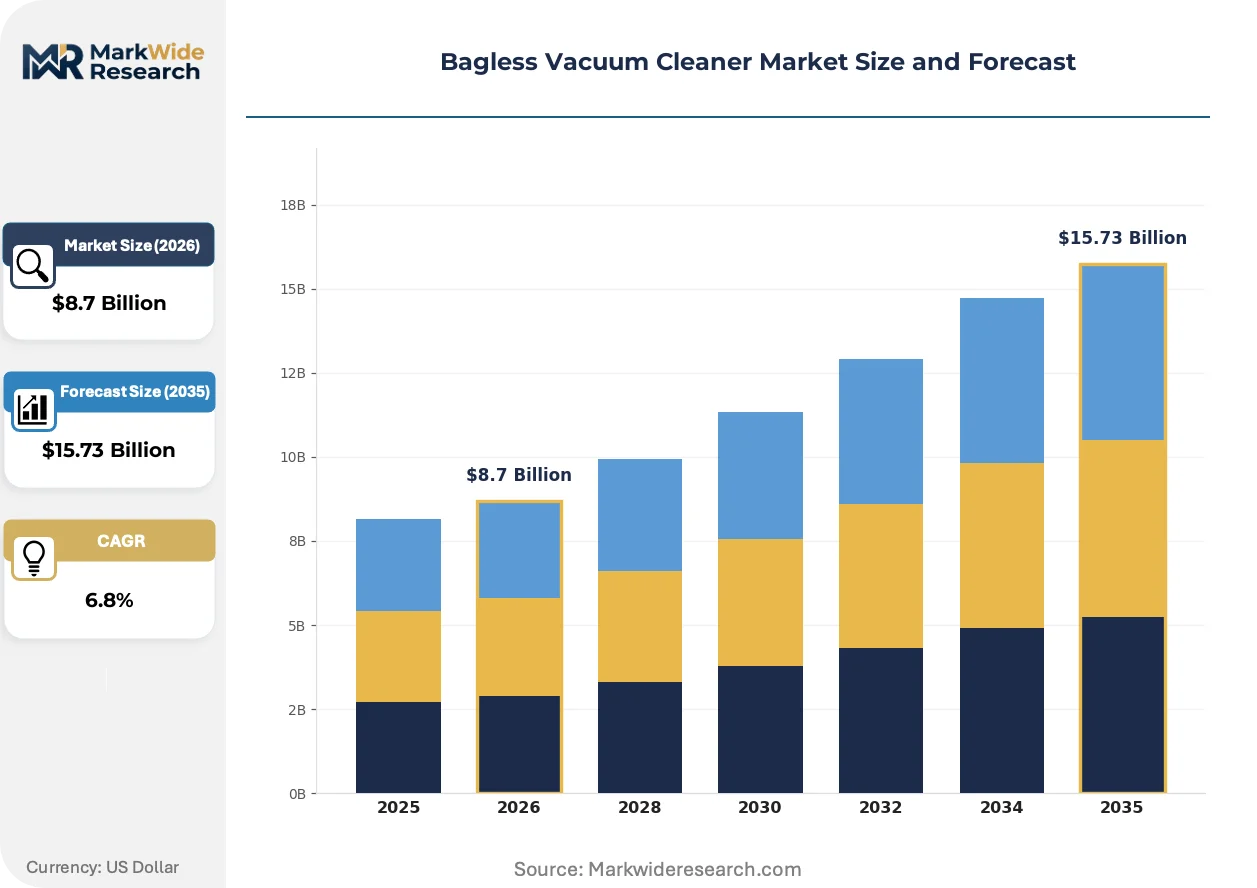
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Robotic, Stick End User: Households, Commercial Spaces, Industrial Facilities, Educational Institutions Technology: Cyclonic, Multi-Cyclonic, Non-Cyclonic, HEPA Filtration Power Rating: Below 500W, 500W-1000W, Above 1000W, Others |
| Companies Covered | Dyson, SharkNinja, Electrolux AB, Bissell, Philips, Panasonic Corporation, Miele, TTI Floor Care, Haier Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bagless Vacuum Cleaner Market Evolving Landscape
Autonomous navigation platforms, battery chemistry advances, and regulatory pressure on material composition are converging to reshape competitive positioning across manual and robotic product categories.
Lithium-silicon anode formulations are decentralizing energy storage architectures in cordless stick vacuums by enabling higher gravimetric density without cobalt supply exposure. Premium residential buyers in Germany and Japan are adopting these platforms as runtime thresholds cross forty-minute barriers. The technology is decentralizing manufacturing footprints by reducing dependence on cylindrical cell formats concentrated in East Asian production.
REACH Annex XVII restrictions on microplastic release from textile cleaning applications are forcing reformulation of brush roll materials and pre-motor filter media. Industrial consequence includes accelerated qualification of bio-based polyamide alternatives and bonded fiber constructions that shed fewer particulates during operation. Canister-format manufacturers serving commercial cleaning contracts face the steepest compliance costs, with German engineering centers leading material substitution timelines.
Direct-to-consumer channel control is compressing distributor margins as stick-vacuum buyers research specifications through manufacturer-owned content before purchase completion. Retail floor space allocation in electronics chains is shrinking as online configuration tools and video demonstration content substitute for physical handling. North American suburban households exhibit the most pronounced channel migration, with warranty registration data showing sixty-day purchase-to-delivery windows becoming standard.
Bagless Vacuum Cleaner Market Segmentation
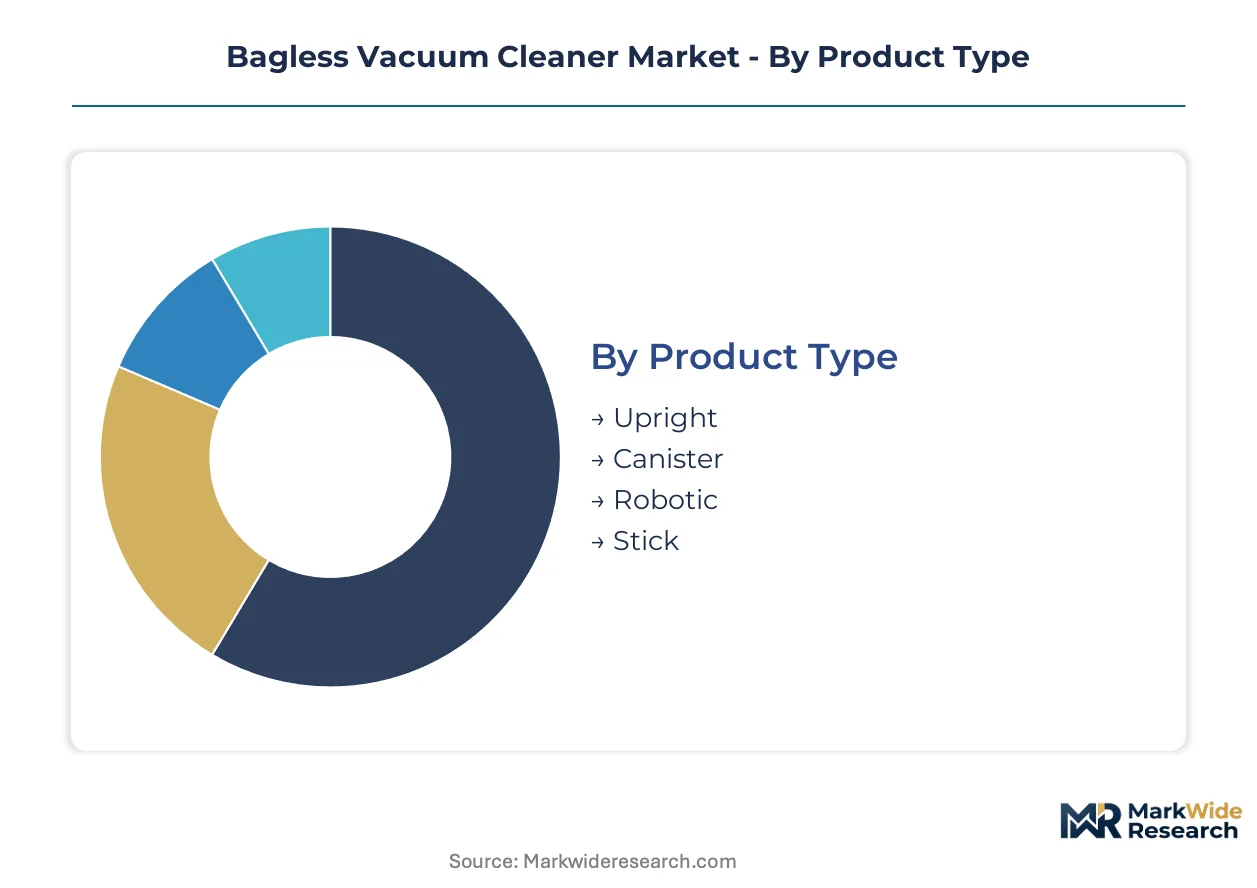
Bagless vacuum architectures diverge sharply across power delivery, autonomy level, and filtration specification. Each axis carries distinct margin profiles and regulatory exposure that reshape procurement priorities for residential buyers and commercial operators.
Product Type:
Cyclonic airflow physics and battery energy density define the competitive frontier across physical formats.
- Stick:Cordless lithium-ion architectures dominate dense urban dwellings in Tokyo and London where wall-mounted storage and sub-2kg weights override suction power metrics. EU Ecodesign motor efficiency mandates accelerate brushless DC adoption in this format.
- Robotic:Autonomous navigation platforms with LiDAR and vSLAM sensors are gaining share fastest in single-story suburban layouts across Germany and the United States. Runtime autonomy and docking reliability determine replacement cycles.
- Upright:Self-standing motorized brush roll designs retain volume in North American carpet-dense households.
- Canister:Separate motor-hose units with large dustbin capacity anchor commercial cleaning contracts in hospitality and healthcare.
Mature deployment sits with canister formats in European commercial sectors. Newer deployment is concentrated in robotic platforms.
End User:
Purchase criteria fragment across dust load intensity, operating hours, and certification requirements.
- Commercial Spaces:Hotels and clinical environments in Germany and Japan specify HEPA-certified units with sealed airflow paths and traceable filter replacement intervals. EPA Energy Star alignment and hospitality chain procurement standards create qualification barriers.
- Households:Urban apartments in Mumbai and New York prioritize compact stick formats with 30-40 minute runtime and rapid-charge docks. Price sensitivity stratifies across cordless premium tiers and entry-level corded alternatives.
- Industrial Facilities:Manufacturing floors and warehouse operations demand above-1000W suction ratings with metal debris handling and spark-resistant construction.
- Educational Institutions:School districts and university maintenance departments balance acquisition cost against durability under high-frequency use.
Commercial spaces generate the steepest margin expansion. Household penetration is climbing fastest in underpenetrated metro clusters.
Technology:
Filtration efficiency and particulate separation mechanics determine regulatory compliance and allergen containment performance.
- HEPA Filtration:Pleated media rated at 99.97% efficiency at 0.3 microns commands premium positioning in healthcare and hospitality segments. Certification requirements from EPA and EU Ecodesign dust re-emission thresholds enforce sealed system engineering.
- Multi-Cyclonic:Staged centrifugal separation arrays sustain suction consistency without filter clogging across extended runtime. Dyson and SharkNinja engineering centers concentrate patent activity in this architecture.
- Cyclonic:Single-chamber vortex designs remain cost-optimized for entry-tier residential markets.
- Non-Cyclonic:Direct suction with pleated or foam pre-motor filters persists in budget robotic and compact handheld units.
HEPA certification anchors the premium tier. Multi-cyclonic deployment is expanding most quickly across mid-tier cordless platforms.
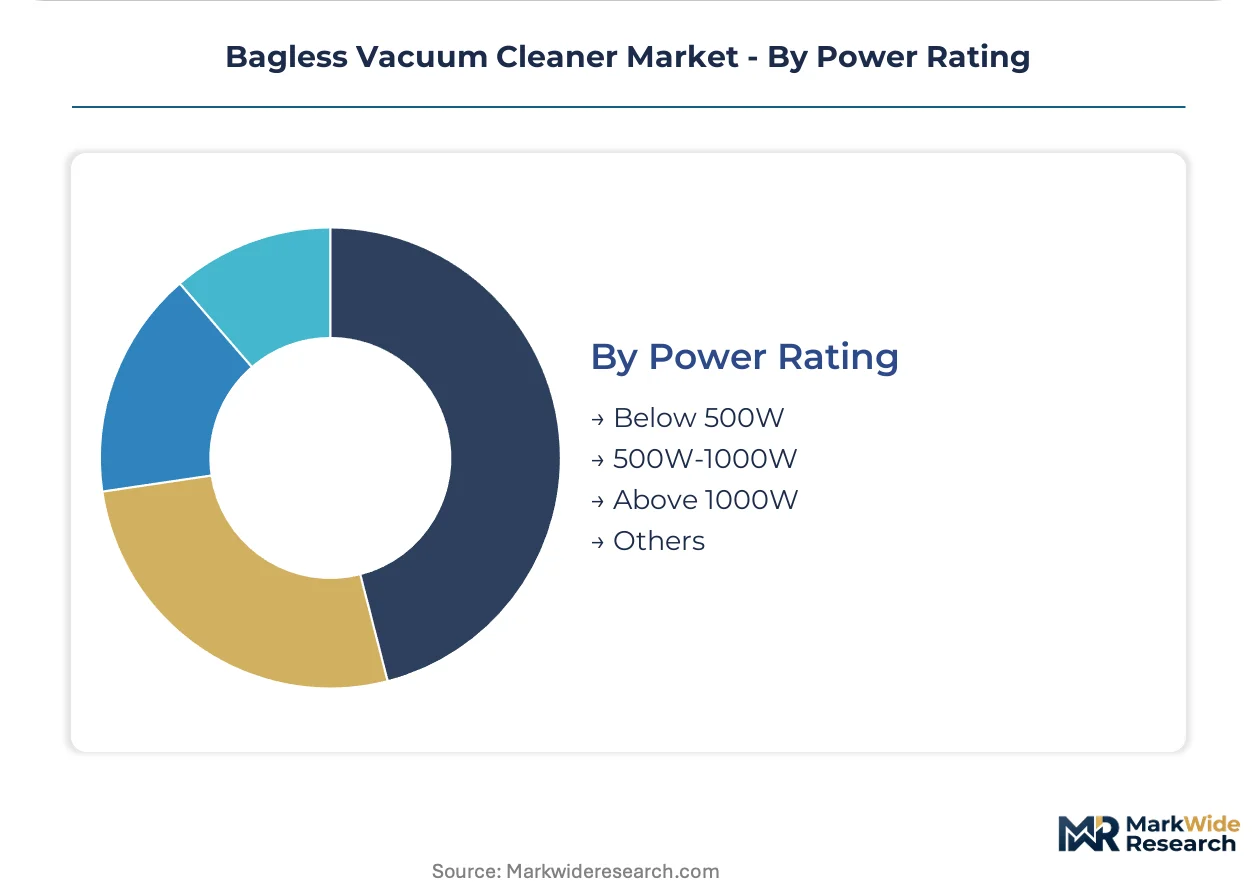
Power Rating:
Motor wattage corridors align with runtime requirements, debris type, and jurisdiction-specific efficiency mandates.
- 500W-1000W:Brushless DC motors in this band achieve runtime parity with corded units while satisfying EU Ecodesign minimum efficiency thresholds. German and Japanese manufacturers optimize stator winding geometries for this corridor.
- Above 1000W:Universal motors and high-torque brushless variants serve commercial deep-cleaning and industrial debris recovery where sustained suction overrides energy consumption metrics.
- Below 500W:Compact robotic and handheld units trade peak suction for battery longevity and thermal management.
- Others:Variable-speed and hybrid power architectures span specialized applications with non-standard electrical requirements.
Above-1000W systems dominate commercial procurement. The 500W-1000W band is gaining share fastest as cordless runtime thresholds cross usability barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing clusters in Inner Mongolia and Jiangxi Province anchor upstream supply elasticity for brushless motor production, while downstream demand concentrates in metropolitan households across Germany, the United States, and Japan where premium replacement cycles are compressing.
United States
Suburban carpet-dense households in Texas and the Midwest sustain upright-format volume, while EPA Energy Star efficiency guidelines and California Air Resources Board indoor air quality standards shape filtration performance claims. The Pacific Northwest corridor around Seattle exhibits pronounced direct-to-consumer channel migration, with online configuration tools substituting for physical retail handling.
Germany
EU Ecodesign motor efficiency mandates and REACH substance restrictions on housing polymers compel simultaneous redesigns of stator geometries and ABS blend formulations. Engineering centers in Stuttgart and Munich concentrate material substitution timelines for bio-based polyamide brush roll alternatives serving commercial hospitality contracts.
Japan
Tokyo and Osaka metropolitan clusters favor wall-mountable stick formats where sub-2kg weights override suction power metrics, while METI Top Runner programs enforce minimum efficiency thresholds for universal and brushless DC variants. Kansai-region manufacturers optimize stator winding geometries for the 500W-1000W runtime parity corridor.
India
Mumbai, Delhi, and Bangalore metro clusters exhibit underpenetration of bagless formats relative to traditional cleaning habits, creating positioning opportunities for cordless stick entrants. BIS energy efficiency labeling requirements and DGFT import tariff structures on lithium-ion cells shape local assembly economics for battery pack integration.
China
Yangtze River Delta manufacturing bases concentrate rare-earth magnet processing and brushless motor winding operations, while MIIT efficiency standards and GB certification protocols govern domestic market entry. Shenzhen and Dongguan clusters house robotic vacuum OEMs integrating LiDAR navigation modules for mid-tier price band migration.
Bagless Vacuum Cleaner Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers establish regional assembly footprints to circumvent lithium-ion cell import tariffs and compress logistics lead times. The vendor base exhibits moderate consolidation around engineering-intensive cyclone architecture specialists, diversified home appliance conglomerates, and contract manufacturing platforms serving private-label brands. Three strategic archetypes define competitive positioning: in-house cyclone R&D specialists, direct-to-consumer channel controllers, and premium canister manufacturers leveraging component traceability. Geographic expansion and technology licensing represent the dominant competitive moves, with players securing multi-source motor procurement agreements to hedge rare-earth price volatility.
Among the engineering-intensive specialists, Dyson exemplifies the in-house cyclone R&D archetype through Singapore and UK engineering center concentration, while SharkNinja represents direct-to-consumer channel control strategies dominating North American stick-vacuum volume. Miele anchors the premium canister positioning archetype through German manufacturing scale and sealed system engineering for healthcare and hospitality certification requirements.
| Leading Market Players |
|---|
| Dyson |
| SharkNinja |
| Electrolux AB |
| Bissell |
| Philips |
| Panasonic Corporation |
| Miele |
| TTI Floor Care |
| Haier Group |
| Others |
Value Network & Pricing Analysis
Premium cordless stick OEM procurement teams concentrate demand for lithium-silicon battery packs and brushless DC motors, anchoring contract-based long-term offtake structures that bundle extended warranty coverage with replacement component subscriptions.
Pricing Analysis
Warranty and service bundling separates certified HEPA-tier units from unbundled economy alternatives, with sealed-system engineering and traceable filter replacement intervals commanding premium positioning. Price differentiation rests on EU Ecodesign certification grade and direct-to-consumer channel control, while cost compression in mid-tier cordless segments intensifies due to rare-earth magnet volatility. Commercial hospitality buyers in Germany exhibit the least price sensitivity, whereas Indian urban households in Mumbai and Delhi show acute responsiveness to entry-tier corded alternatives.
Supply Chain Analysis
Freight cost fluctuations from Yangtze River Delta ports to European distribution hubs are compressing margins on finished robotic units. Rare-earth magnet processing draws from Inner Mongolia and Jiangxi Province in China, while lithium-ion cell assembly concentrates in South Korea and Japan. Single-source vulnerability in neodymium supply chains threatens brushless motor production timelines. Distribution runs through manufacturer-owned direct-to-consumer platforms and contracted electronics retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over cyclone R&D and battery pack assembly determines margin defense against rare-earth price swings.
For Market Incumbents: Extend patent thickets around multi-cyclonic airflow architectures to block SharkNinja and emerging Chinese OEMs from mid-tier cordless penetration. Backward integration into lithium-silicon anode sourcing secures runtime parity advantages as EU Ecodesign mandates accelerate brushless DC adoption. For New Entrants and Emerging Players: The premium-economy price gap in Indian metro clusters offers white-space positioning for cordless stick entrants with rapid-charge dock configurations. Target Mumbai and Bangalore households through direct-to-consumer video demonstration content that substitutes for physical retail handling. For Investors and Strategic Acquirers: The window for entry favors engineering-intensive cyclone specialists with in-house motor control firmware capabilities. Acquisition candidates must demonstrate field-oriented control algorithm expertise for high-speed brushless drives. Monitor right-to-repair legislative passage in France and proposed EU frameworks as inflection signals for modular battery platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Motor Procurement Agreement | Hedges rare-earth price volatility from Chinese processing concentration. |
| Direct-to-Consumer Channel Expansion | Captures Pacific Northwest and North American suburban buyer migration online. |
| LiDAR Navigation Module Integration | Enables mid-tier robotic units to navigate complex furniture layouts. |
| EU Ecodesign Certification Investment | Unlocks German and French hospitality procurement contract eligibility. |
| Modular Battery Platform Development | Aligns product architecture with French repairability index mandates. |
Research Methodology
Document review covered EU Ecodesign regulatory filings, EPA Energy Star test protocols, and METI Top Runner efficiency standards, complemented by interviews with brushless motor control firmware engineers, cyclone R&D directors at Singapore and UK engineering centers, lithium-ion cell procurement leads, and commercial hospitality buyers in German hotel chains. Secondary validation drew from customs trade data on rare-earth magnet imports, SEC 10-K appliance segment disclosures, and BIS energy efficiency labeling records. Bottom-up unit shipment estimates triangulated against top-down category spend analysis.
Cross-referencing historical replacement cycle compression with panel input from OEM product planners shaped the analytical framework across product type, power rating, and end-use segmentation. CAGRs derived from weighted average of technology diffusion curves and regulatory mandate implementation timelines. Forecast inputs incorporated lithium-silicon anode commercialization trajectories and REACH Annex XVII material substitution timelines for brush roll polymers.
Underlying measurement precision varies by segment; robotic and cordless stick formats carry tighter precision than canister and upright categories due to concentrated OEM disclosure. Forecasts reflect assumptions on EU Ecodesign enforcement consistency and rare-earth supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Asean Cookware Market
Household Items
Portable Car Vacuum Market
Household Items
Russia Residential Water Heaters Market
Household Items
Plastic Bathtub Market
Household Items
Fine Mist Sprayer Market
Household Items
Mirror Holder Market
Household Items
Kitchen Towel Market
Household Items
Mosquito Repellent Candles Market
Household Items
Saudi Arabia Cookware Market
Household Items
Shower Heads and Systems Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Bladeless Neck Fan Market
Household Items
Global Buddhist Supplies Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Range Hood Cleaning Service Market
Household Items
Global Ceramic Tableware Market