
 Dosage Spoon Market | 2026-2036
Dosage Spoon Market Size, Share, and Industry Trends Forecast 2026-2036
Dosage Spoon Market Foresight
Market Context
EU MDR is decoupling low-cost Asian suppliers from European hospital procurement channels. Gerresheimer sustains its position through captive glass-forming capacity and cleanroom certification. Comar LLC dominates North American pharmacy supply with in-house resin compounding and FDA-registered blow-fill-seal lines. Medi-Dose Group differentiates via unit-dose packaging integration that bundles spoons with barcoded medication cups.
Technical Definition and Segment Structure
A dosage spoon is a calibrated liquid-measurement instrument, typically molded in food-grade polypropylene or borosilicate glass with volumetric graduations at 2.5 mL, 5 mL, and 10 mL intervals, designed to deliver oral pharmaceutical suspensions with accuracy within ±10% of stated volume. Plastic single-use spoons lead hospital infection-control protocols, while silicone reusable variants capture premium homecare margins due to dishwasher durability and pediatric safety profiles. Stainless steel manual spoons retain niche pharmacy compounding demand where solvent resistance matters, though automatic dosing syringes displace them in oncology infusion settings.
Regulatory Frame and Outlook
FDA's Current Good Manufacturing Practice for combination products and EMA's MDR technical documentation requirements both mandate extractables-leachables testing for polymer dosage spoons in pediatric indications. BIS certification in India and CDSCO material-safety filings further fragment market access for non-specialist molders. Stakeholders must monitor evolving pharmacopeial chapters on plastic packaging systems, as USP <661.1> revisions could trigger reformulation costs across existing product lines.
Market Dynamics
EU MDR biocompatibility mandates are decoupling low-cost Asian molders from European hospital procurement channels, forcing manufacturers to absorb extractables-leachables testing costs or exit the market entirely.
Growth Catalysts
- Pediatric homecare expansion:Caregivers in Germany and France now demand pharmacy-grade calibrated spoons for liquid antibiotics, creating pull-through for dishwasher-safe silicone variants with 2.5 mL precision graduations.
- REACH compliance automation:Polypropylene resin suppliers investing in automated material-safety documentation are shortening EU hospital qualification cycles from eighteen months to six.
- Unit-dose bundling:Pharmacy chains in Central Europe now specify barcoded medication cup-and-spoon combinations to reduce dispensing errors in high-volume retail settings.
Market Restraints
- Glass-forming capacity scarcity:Borosilicate dosage spoon production concentrates among three European suppliers with captive furnace operations, creating 14-month lead times for new pharmacy customers.
- USP <661.1> revision exposure:Pending pharmacopeial updates on plastic packaging extractables could trigger reformulation costs across existing polypropylene product lines without grandfathering provisions.
- Automatic dosing syringe substitution:Oncology infusion centers are replacing stainless steel manual spoons with closed-system syringe pumps, compressing demand in solvent-resistant compounding applications.
Strategic Opportunities
- India CDSCO pathway acceleration:Domestic manufacturers with BIS-certified cleanroom molding can capture hospital tender share as import substitution policies tighten pharmaceutical device sourcing rules.
- Smart packaging convergence:Near-field communication tags embedded in disposable spoons enable dose-verification apps, opening pediatric adherence monitoring contracts with telehealth platforms.
- Amazon Pharmacy channel expansion:Direct-to-consumer liquid medication shipments create demand for individually wrapped single-use spoons with tamper-evident seals, bypassing traditional wholesale distribution.
Industry Challenges
- Biocompatibility testing backlog:EU notified body capacity constraints are extending MDR technical documentation review timelines, delaying product launches for molders without prior CE-mark portfolio experience.
- Cleanroom capex intensity:ISO 14644 Class 7 certification for blow-fill-seal lines requires 4 million euro minimum investment, excluding mid-tier Asian competitors from European hospital supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dosage Spoon Market |
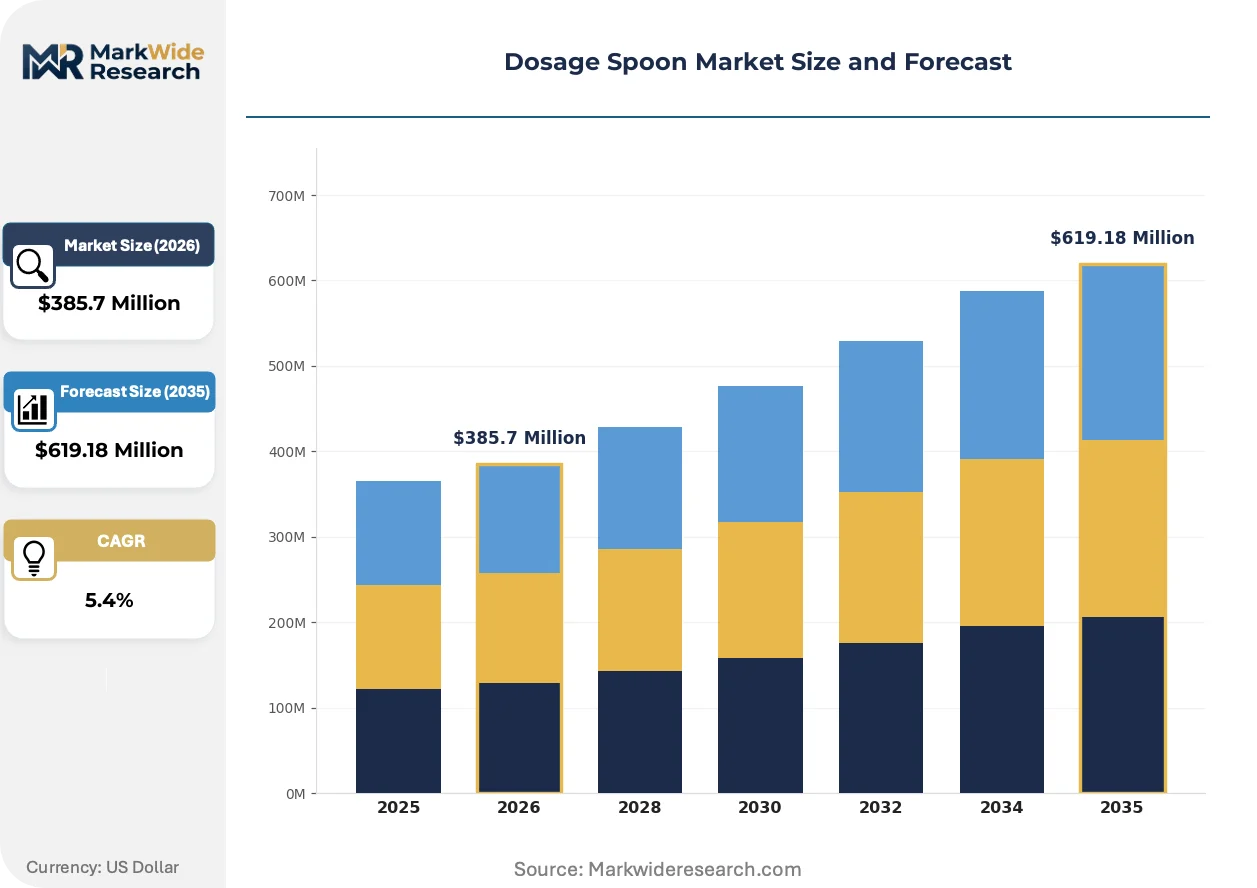
| Market Size in 2026 | $385.7 Million |
| Market Size in 2035 | $619.18 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Use, Reusable, Automatic, Manual Material: Plastic, Stainless Steel, Silicone, Glass End User: Hospitals, Pharmacies, Homecare, Clinics Size: Small, Medium, Large, Extra Large |
| Companies Covered | Comar LLC, Stiplastics Healthcaring, Medi-Dose Group, Bormioli Pharma, Parekhplast India, Rommelag, Gerresheimer, Abbott Laboratories, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dosage Spoon Market Shifts & Advancements
Silicone-overmolding and connected packaging technologies are compressing the traditional segmentation between hospital infection control and homecare durability requirements, forcing material science investments across tier-1 suppliers.
Photoluminescent volumetric markings are electrifying pediatric safety design by enabling dose verification under low-light conditions. Neonatal intensive care units in France and Belgium are specifying glow-in-the-dark 5 mL graduations for nighttime medication rounds. This capability is compressing demand for standard printed markings in premium pediatric segments.
EMA's MDR Annex I general safety and performance requirements now mandate traceability documentation for all patient-contact dosing tools, including batch-level polymer certification. German pharmacy procurement offices are rejecting tenders lacking full supply chain substance disclosure. Small molders without ERP-integrated quality systems are exiting the hospital channel entirely.
Hospital buying consortia are consolidating liquid medication delivery device specifications across multi-site health systems, replacing individual pharmacy autonomy with centralized formularies. This pattern is most visible in the Rhineland region, where three hospital networks now mandate identical spoon specifications across 47 facilities, compressing supplier diversity to four approved vendors.
Dosage Spoon Market Segmentation
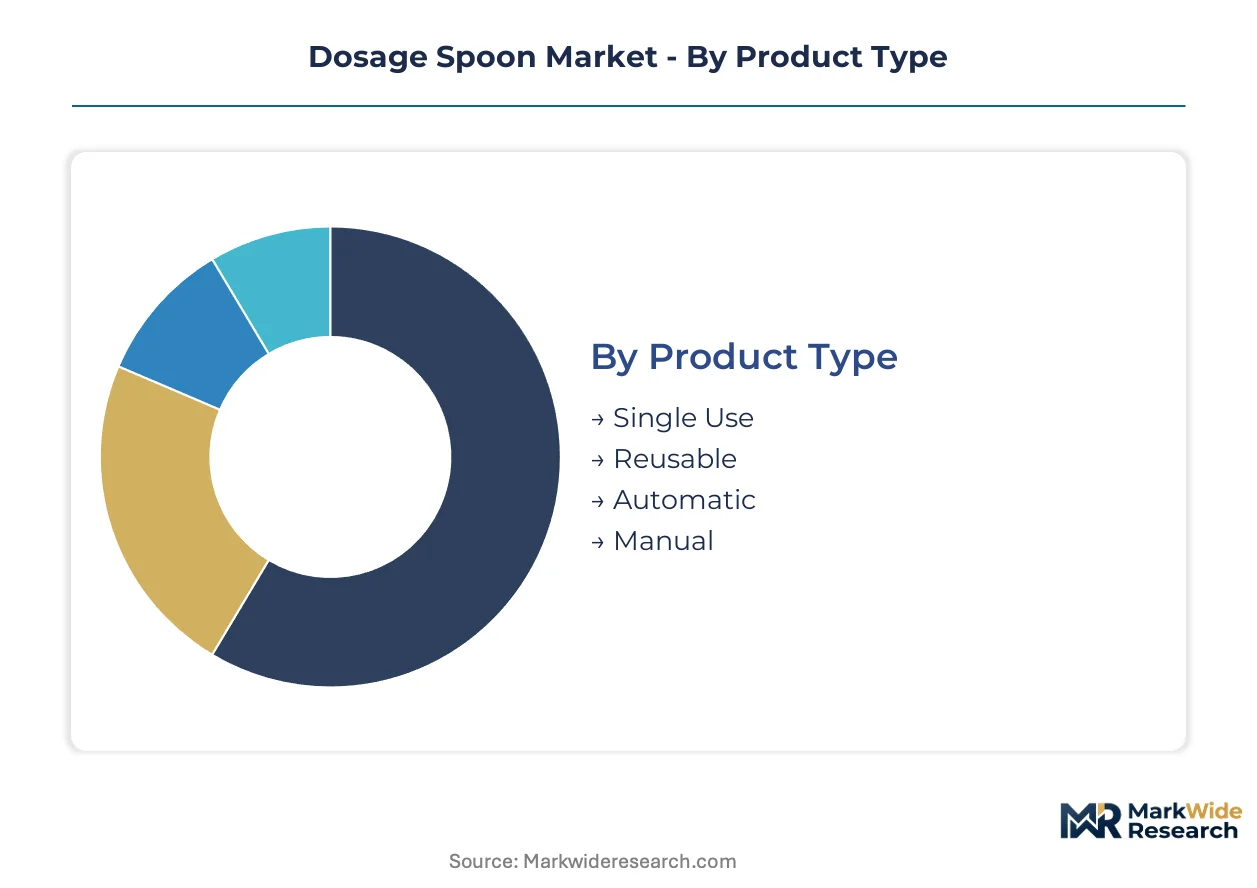
Material compliance and end-use sterility requirements fragment the dosage spoon market into distinct procurement channels. Each segment carries unique regulatory burdens and margin profiles that determine supplier viability.
Product Type:
Hospital infection-control protocols drive purchasing decisions toward disposability or automation, while homecare economics favor durability.
- Single Use:Polypropylene spoons manufactured in ISO 14644 Class 7 cleanrooms dominate hospital formularies. German hospital buying consortia now mandate individual sterile wrapping with tamper-evident seals across 47-facility networks.
- Reusable:Dishwasher-safe silicone variants capture pediatric homecare margins in France and Belgium. Caregivers demand 2.5 mL precision graduations for liquid antibiotics, creating pull-through for premium-priced durable designs.
- Automatic:Closed-system syringe pumps displace manual spoons in oncology infusion centers. Solvent-resistant compounding applications now specify automated dosing to eliminate human measurement error.
- Manual:Stainless steel retains niche pharmacy compounding demand where chemical resistance matters. Manual operation persists in resource-constrained settings lacking capital for automation infrastructure.
Single Use leads on scale; Automatic leads on momentum.
Material:
Extractables-leachables testing costs and furnace capacity constraints reshape competitive positioning across material categories.
- Plastic:Food-grade polypropylene with volumetric graduations at 2.5 mL, 5 mL, and 10 mL intervals delivers ±10% accuracy. Pending USP revisions on plastic packaging extractables threaten reformulation costs without grandfathering provisions.
- Glass:Borosilicate spoons concentrate among three European suppliers with captive furnace operations. Fourteen-month lead times for new pharmacy customers create supply bottlenecks in Central European procurement.
- Silicone:Overmolded designs bridge hospital infection control and homecare durability requirements. Photoluminescent graduations enable dose verification under low-light conditions in neonatal intensive care units.
- Stainless Steel:Solvent resistance sustains demand in pharmacy compounding where aggressive chemicals degrade polymer alternatives. Manual stainless designs face displacement from automatic syringe systems in high-volume infusion settings.
Plastic leads on scale; Silicone climbs the fastest.
End User:
Procurement centralization and regulatory stringency vary dramatically across patient care settings.
- Hospitals:Multi-site health systems consolidate liquid medication delivery specifications. Rhineland hospital networks compress supplier diversity to four approved vendors through centralized formularies.
- Homecare:Pediatric applications in Germany and France drive pharmacy-grade calibrated spoon demand. Caregivers seek dishwasher-safe silicone with precision graduations for antibiotic administration.
- Pharmacies:Central European retail chains specify barcoded medication cup-and-spoon combinations. Unit-dose bundling reduces dispensing errors in high-volume settings.
- Clinics:Outpatient facilities balance cost constraints against infection-control requirements. Intermediate procurement volumes limit negotiating leverage with tier-1 suppliers.
Hospitals lead on scale; Homecare gains share fastest.
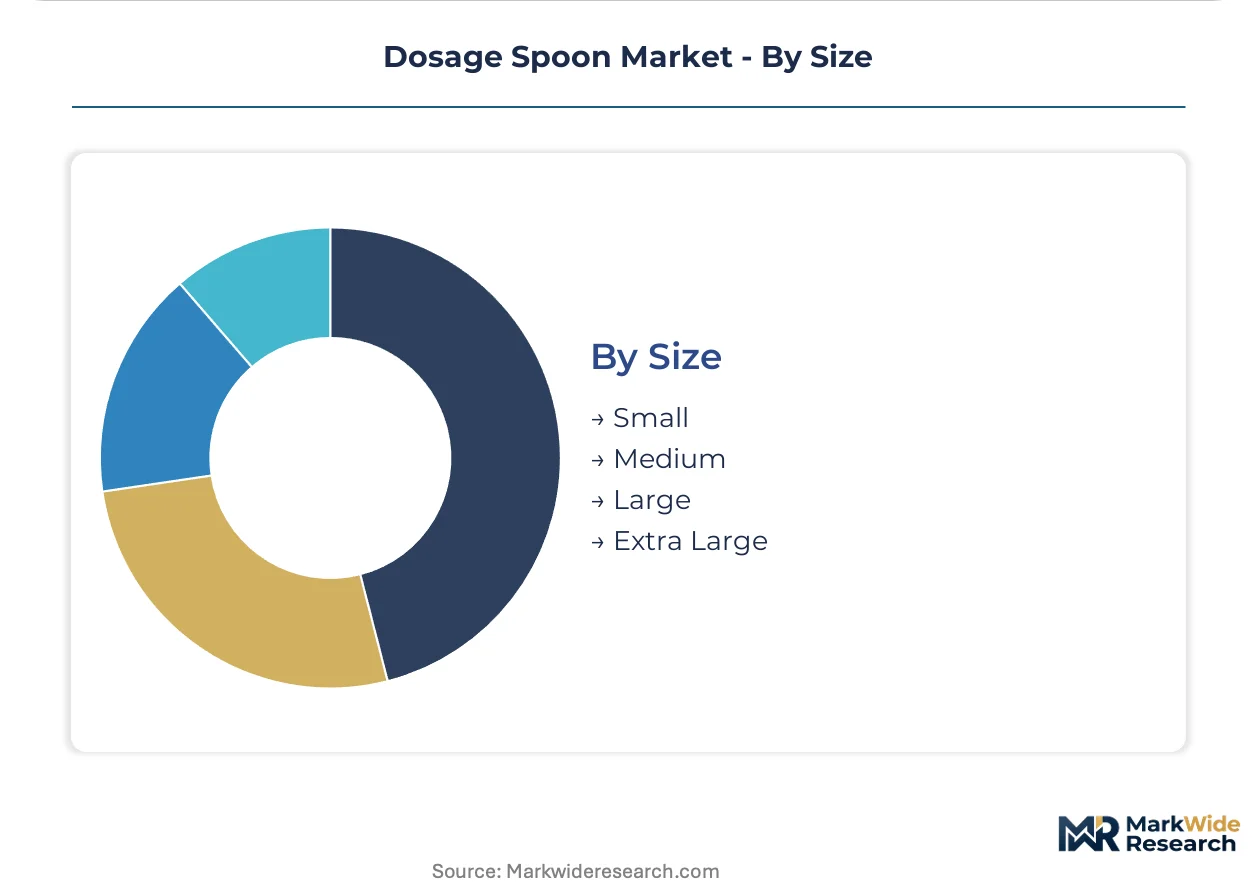
Size:
Volumetric precision requirements and patient population demographics determine size-category demand concentration.
- Small:2.5 mL capacity serves neonatal and pediatric indications requiring micro-dosing precision. Photoluminescent markings specified by French and Belgian NICUs enable nighttime dose verification.
- Medium:5 mL standard dominates adult liquid antibiotic prescriptions. German pharmacy procurement offices reject tenders lacking batch-level polymer certification for patient-contact dosing tools.
- Large:10 mL capacity addresses cough syrup and nutritional supplement delivery. Homecare applications favor graduated large spoons for multivitamin administration.
- Extra Large:Specialized institutional feeding applications require volumes exceeding standard pharmaceutical specifications. Limited demand concentrates in long-term care facilities.
Medium leads on scale; Small shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered pharmacy-grade dosage spoon standardization through its hospital buying consortia, establishing procurement templates that radiated across Central Europe. The industry's regulatory lineage traces to Rhineland hospital networks consolidating liquid medication delivery specifications across multi-site health systems.
Germany
Pharmacy-grade compliance standards shape procurement across Central Europe, with Rhineland hospital networks mandating identical spoon specifications across 47 facilities. EMA's MDR Annex I requirements enforce batch-level polymer certification for all patient-contact dosing tools. Stuttgart and Frankfurt host ISO 14644 Class 7 cleanroom operations serving hospital infection-control protocols.
France
Neonatal intensive care units in Paris and Lyon specify photoluminescent 5 mL graduations for nighttime medication rounds, compressing demand for standard printed markings. ANSM enforces traceability documentation alignment with MDR general safety requirements. The Auvergne-Rhône-Alpes cluster concentrates dishwasher-safe silicone production for pediatric homecare.
United States
Amazon Pharmacy direct-to-consumer shipments create demand for individually wrapped single-use spoons with tamper-evident seals. FDA Current Good Manufacturing Practice for combination products mandates extractables-leachables testing for polymer spoons in pediatric indications. New Jersey and Pennsylvania host blow-fill-seal operations supplying North American pharmacy chains.
India
Domestic manufacturers with BIS-certified cleanroom molding capture hospital tender share as CDSCO import substitution policies tighten pharmaceutical device sourcing. Maharashtra and Gujarat molders invest in automated material-safety documentation to shorten qualification cycles. Mumbai anchors resin compounding operations serving regional pharmacy supply.
Belgium
Pediatric caregivers in Brussels and Antwerp demand 2.5 mL precision graduations for liquid antibiotics, driving silicone variant adoption. REACH compliance automation among polypropylene suppliers accelerates EU hospital qualification timelines. The Flanders region concentrates unit-dose packaging integration bundling spoons with barcoded medication cups.
Dosage Spoon Market Competitive Landscape
The competitive structure tilts toward material-specialist incumbents with captive certification infrastructure. Three European glass-forming operations and North American resin compounders dominate hospital procurement channels, while mid-tier Asian molders face exclusion from EU tenders under MDR biocompatibility mandates. Strategic archetypes include cleanroom-certified disposables manufacturers, silicone-overmolding specialists, and integrated pharmacy packaging bundlers. Competitive moves center on backward integration into resin compounding and geographic expansion through notified body pre-certification.
Among glass-forming specialists, Gerresheimer exemplifies the European incumbent archetype through captive furnace operations. Comar LLC and Medi-Dose Group anchor North American positioning, with the former representing resin-compounding integration and the latter exemplifying unit-dose packaging convergence. Bormioli Pharma occupies a position within Mediterranean pharmacy supply, while Parekhplast India sits within the emerging domestic certification tier targeting CDSCO pathway acceleration.
| Leading Market Players |
|---|
| Comar LLC |
| Stiplastics Healthcaring |
| Medi-Dose Group |
| Bormioli Pharma |
| Parekhplast India |
| Rommelag |
| Gerresheimer |
| Abbott Laboratories |
| Becton Dickinson |
| Others |
Supply & Pricing Matrix
Cleanroom-certified polymer molders concentrated in Stuttgart and Frankfurt command wage premiums that compress pricing spreads between pharmacy-grade and standard-tier dosage spoons. Labor-cost differentials between Western European ISO 14644 Class 7 operations and mid-tier Asian facilities drive tier separation, with automated material-safety documentation investments narrowing historical gaps.
Pricing Analysis
Three-tier pricing structure across pharmacy-certified, standard medical-grade, and economy non-sterile levels dominates procurement. Price differentiation hinges on EMA MDR biocompatibility certification tier and batch-level polymer traceability documentation. Cost compression in the economy tier intensifies because import substitution policies in India and China expand domestic molding capacity. Hospital buying consortia exhibit lowest price sensitivity due to formulary standardization mandates, while retail pharmacy chains face acute pressure from Amazon Pharmacy direct-to-consumer channel expansion.
Supply Chain Analysis
Certification gating through EU notified body MDR technical documentation review restricts supply base concentration to Germany, France, and select North American resin compounders. Raw material dependencies center on food-grade polypropylene resin, borosilicate glass furnace capacity, and medical-grade silicone elastomer. Single-source vulnerability concentrates in captive glass-forming operations among three European suppliers. Distribution runs through hospital buying consortia in Central Europe, pharmacy wholesale networks, and emerging direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in dosage spoons rest on REACH compliance automation reducing qualification cycle costs and silicone-overmolding capturing premium pediatric homecare positioning.
For Market Incumbents: To counter automatic dosing syringe substitution in oncology settings, backward integration into resin compounding secures material cost control while ISO 14644 Class 7 capacity additions in Rhineland hospital network proximity defend formulary lock-in against emerging Asian competitors. For New Entrants and Emerging Players: The price-point gap between dishwasher-safe silicone homecare variants and single-use polypropylene hospital disposables opens entry paths. Pediatric antibiotic administration applications in Belgium and France present the most penetrable segment, with BIS-certified cleanroom molding in Maharashtra enabling CDSCO pathway qualification as the optimal go-to-market angle. For Investors and Strategic Acquirers: Pharmaceutical packaging conglomerates with existing blow-fill-seal infrastructure are the most active acquirers in this space, targeting notified body pre-certified molders to accelerate EU market access. Five-to-ten year viability favors suppliers with ERP-integrated quality systems and captive polymer certification documentation. The signal to monitor is USP Chapter 661.1 revision finalization timing, which would trigger reformulation cost inflections across existing product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply secures margin control against volatile feedstock pricing from German chemical suppliers. |
| CE Marking Pathway Acceleration | EU notified body pre-certification compresses hospital tender qualification timelines from eighteen months to six. |
| Hospital System Partnership | Rhineland network formulary consolidation across 47 facilities creates multi-year supply contract visibility. |
| Software Companion Development | NFC-enabled dose-verification apps open pediatric adherence monitoring contracts with telehealth platforms. |
| Reimbursement Strategy | Pharmacy-grade calibration documentation supports insurance coding for precision medication delivery devices. |
Research Methodology
Bottom-up pediatric homecare and hospital procurement modeling reconciled against top-down resin compounding and glass-forming capacity tracking forms the analytical core. Primary interviews with hospital pharmacy directors, biomedical engineers, GPO contracts managers, and CDSCO regulatory consultants combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation databases, and German hospital procurement consortium tender records. Triangulation across stakeholder inputs and regulatory filing analysis ensures segmentation integrity.
Historical trendline analysis of material certification adoption rates and cleanroom capacity expansion patterns informs projection frameworks across the modeling period. Segmentation dimensions include product disposability tier, material compliance grade, end-use sterility requirement, patient population size category, and regional regulatory cluster. CAGRs derive from calibrated adoption curves for silicone-overmolding and connected packaging technologies, with extractables-leachables testing cost trajectories and automatic dosing substitution rates as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for photoluminescent volumetric marking integration would alter the outlook. Forecasts reflect assumptions regarding MDR notified body capacity constraints and USP pharmacopeial revision timing. A model refresh is warranted upon material change in EU hospital buying consortia tender specifications or CDSCO import substitution policy enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Underwear Disinfection Dryers Market
Household Items
Plastic Carafe Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Ultrasonic Diffusers Market
Household Items
Japan Faucets Market
Household Items
Dryer Sheets Market
Household Items
Replacement Sheets Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Indoor Humidifier Market
Household Items
Global Aluminum Cookware Market
Household Items
Steam Cleaners Market
Household Items
North America Water Purifier Market
Household Items
Saudi Arabia Cookware Market
Household Items
North America Tankless Water Heater Market
Household Items
Electric Mop Market
Household Items
Global Residential Robotic Vacuum Cleaner Market