
 United Arab Emirates Dairy Market | 2026-2036
United Arab Emirates Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Dairy Market Analytics
Market Context
The United Arab Emirates dairy sector is consolidating around a widening split between premium organic and functional product tiers and commodity fluid milk lines. Almarai Co. leverages its integrated desert farming infrastructure to anchor supply security for fresh milk categories. Al Ain Farms competes through direct-to-retail channel control across UAE hypermarket networks. Arla Foods amba differentiates via specialized lactose-free and protein-enriched formulations targeting health-conscious expatriate consumers.
Product Definition and Segment Structure
Dairy in the UAE context encompasses bovine-derived fluid milk, fermented products, ripened cheeses, and fat-based spreads, typically processed under ultra-high temperature or extended shelf-life protocols to withstand ambient distribution temperatures reaching 45°C. The product type dimension shows yogurt and cheese outpacing fluid milk in margin contribution as consumers shift toward convenient, high-protein snacking formats. Within distribution channels, supermarkets sustain volume dominance while online retail captures the fastest expansion, driven by subscription-based fresh delivery models and app-integrated loyalty programs.
Regulatory Environment and Outlook
MOHAP enforces stringent microbiological and labeling standards that elevate compliance costs for imported dairy, while the UAE's technical regulations bureau mandates bilingual Arabic-English nutritional declarations that reshape packaging procurement decisions. ESMA's halal certification protocols and MOHAP's import residue testing regimes collectively filter market access, favoring suppliers with established in-country laboratory partnerships. Stakeholders must monitor evolving fortification mandates and single-use packaging restrictions as policy levers that will redefine product development priorities and capital allocation across the Emirates.
Market Dynamics
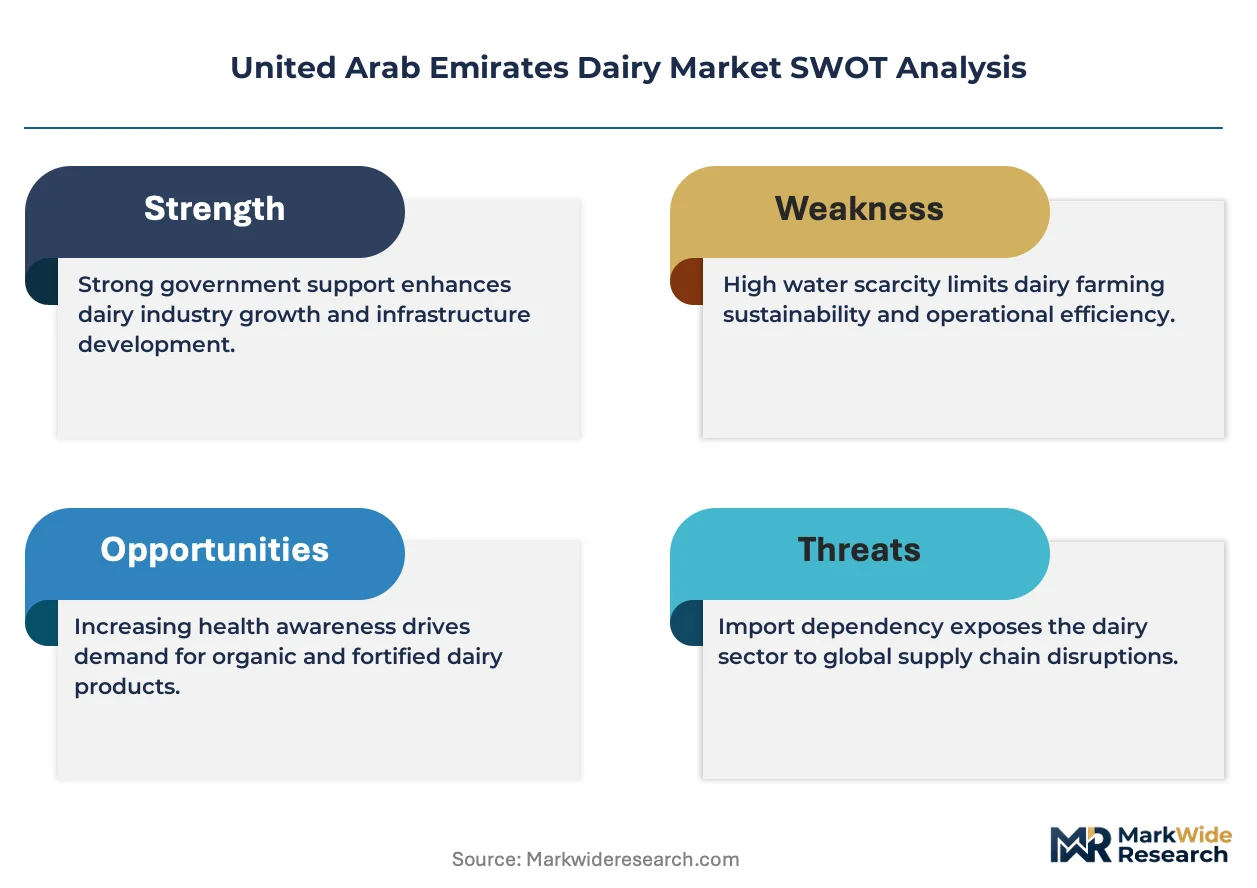
The UAE dairy sector is bifurcating between premium functional products and commodity fluid milk as desert farming infrastructure and cold-chain investments reshape supply economics. This structural split is accelerating channel specialization and margin compression at the commodity tier.
Growth Catalysts
- HoReCa Expansion:Hotel and restaurant chains across Dubai and Abu Dhabi are driving volume pull for UHT milk and processed cheese formats. This end-use concentration creates predictable offtake agreements for domestic processors.
- MOHAP Food Safety Modernization:The Ministry of Health and Prevention's upgraded microbiological standards are filtering subscale importers. Compliance investments by established suppliers are consolidating shelf access.
- Cold-Chain Technology Upgrades:Refrigerated logistics networks extending into northern emirates are reducing spoilage rates for fresh categories. This infrastructure expansion enables same-day delivery models in Sharjah and Ras Al Khaimah.
Market Restraints
- Feed Input Volatility:Alfalfa and soybean meal prices fluctuate with global commodity cycles. Desert dairy operations bear elevated transport costs for imported feedstock that compresses farm-gate margins.
- Water Scarcity Constraints:Groundwater depletion limits expansion of local fodder cultivation. UAE dairy producers remain dependent on desalinated water infrastructure with energy-linked cost exposure.
- ESMA Halal Certification Complexity:The Emirates Authority for Standardization and Metrology's multi-stage approval process creates six-to-nine month entry barriers for new imported brands.
Strategic Opportunities
- Northern Emirates Underpenetration:Ajman, Umm Al Quwain, and Fujairah exhibit lower per-capita dairy consumption than Dubai. Direct distribution investments in these emirates capture first-mover advantages in modern retail.
- Functional Product White Space:Protein-enriched and lactose-free formulations targeting South Asian expatriate populations remain underserved. Product development aligned with diabetes-prevention positioning opens pharmacy channel access.
- Subscription Delivery Models:App-integrated fresh milk subscriptions are displacing traditional supermarket replenishment cycles. Technology platforms enabling recurring revenue streams reduce customer acquisition costs.
Industry Challenges
- Talent Scarcity in Cold-Chain Operations:Qualified technicians for refrigerated transport maintenance and warehouse temperature management are in short supply. Vocational training pipelines have not kept pace with logistics network expansion.
- Packaging Compliance Timelines:MOHAP's bilingual Arabic-English labeling mandates require redesign cycles that delay product launches. Procurement lead times for compliant packaging materials extend inventory planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Dairy Market |
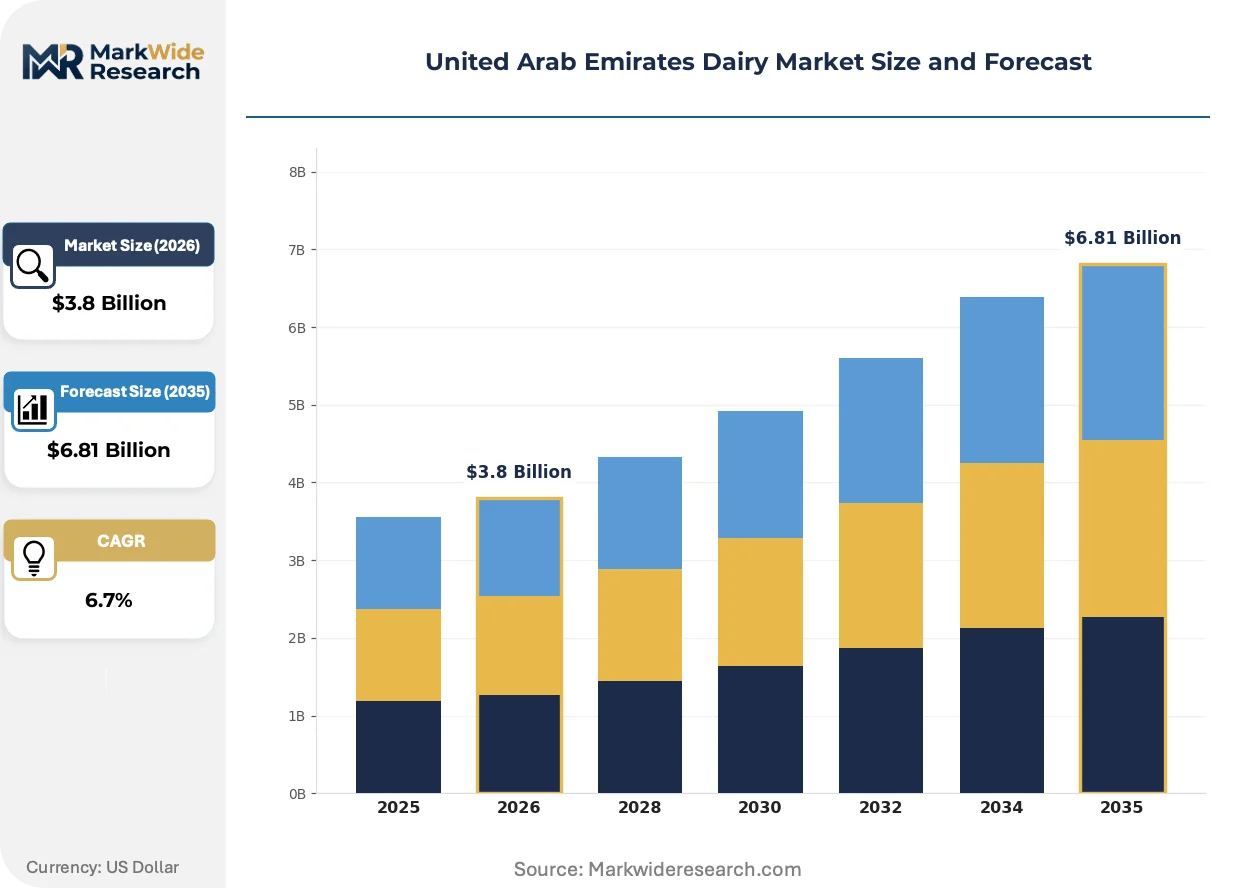
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores Packaging Type: Bottles, Cartons, Tetra Packs, Bulk End User: Households, HoReCa, Food Processing, Exporters |
| Companies Covered | Al Ain Farms (YAS Holding), Arla Foods amba, Emirates Rawabi, Marmum Dairy Farm, Saudia Dairy & Foodstuff Co. (SADAFCO), Almarai Co., Groupe Lactalis, Agthia Group PJSC, National Food Products Co. (NFPC Milco, Lacnor), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Dairy Market Evolving Landscape
Automation, regulatory fortification mandates, and channel disintermediation are converging to reshape how dairy reaches UAE consumers. These forces are compressing traditional intermediaries while elevating traceability requirements.
Robotic milking systems and automated herd management platforms are automating labor-intensive operations across UAE desert dairy farms. Large-scale producers in Al Ain and Dubai are deploying sensor-based health monitoring at accelerating rates. This technology diffusion is automating yield optimization and reducing veterinary intervention costs while tightening biosecurity protocols.
MOHAP's evolving fortification mandates for vitamin D and calcium are restructuring product formulation requirements. Processors must reformulate standard fluid milk lines to meet minimum nutritional thresholds. The fresh milk segment bears the highest compliance burden as ambient-distributed UHT products face distinct additive regulations.
Direct-to-consumer subscription platforms are displacing traditional supermarket replenishment for fresh milk categories. Younger expatriate households in Dubai Marina and Downtown Dubai are adopting app-based recurring delivery. This behavioral shift is most visible among dual-income professional segments prioritizing convenience over price comparison.
United Arab Emirates Dairy Market Segmentation
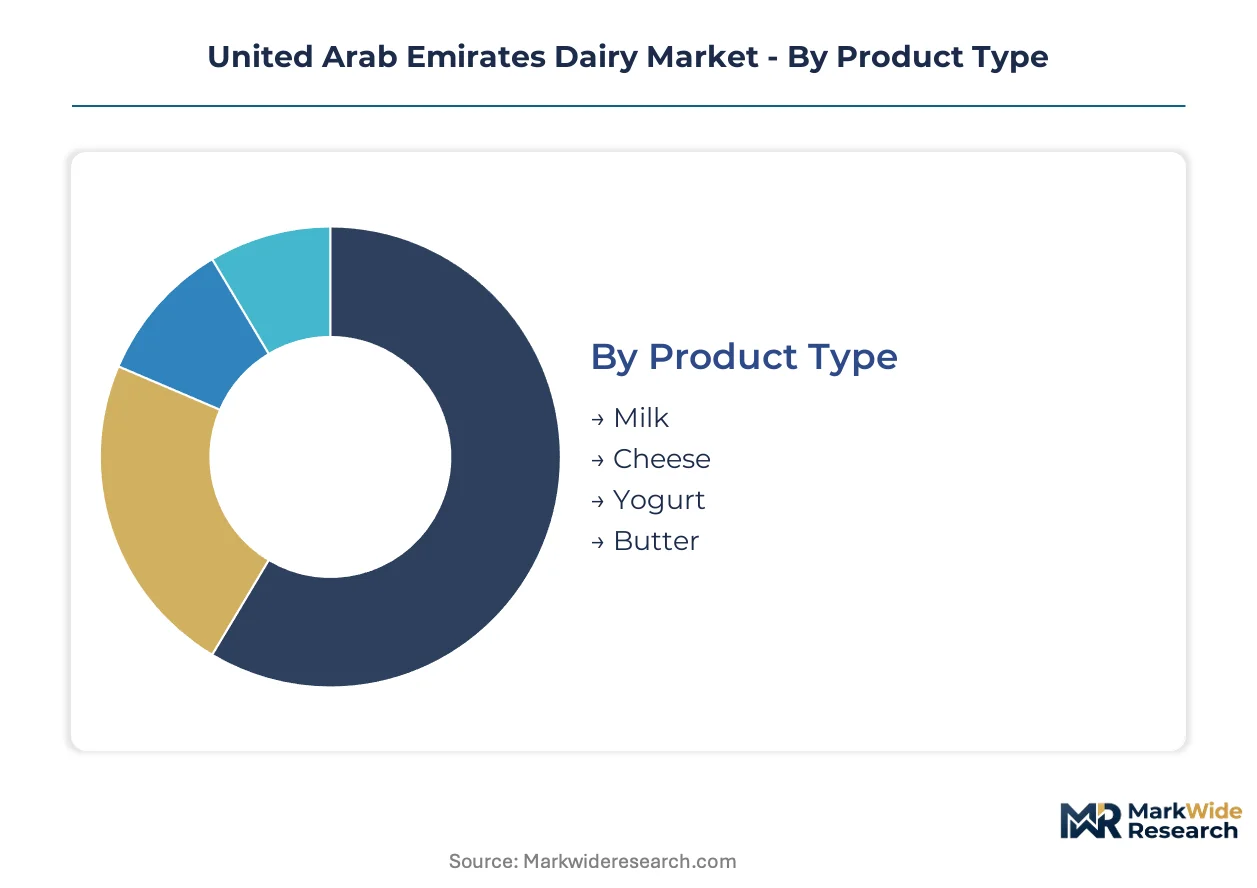
The UAE dairy market's segmentation reflects capital allocation priorities across desert farming infrastructure, cold-chain logistics, and regulatory compliance. Each dimension reveals distinct margin structures and investment barriers that shape competitive positioning.
Product Type:
Capital intensity varies sharply across processing equipment requirements, with fermentation infrastructure demanding specialized bioreactor investments distinct from fluid milk pasteurization lines.
- Milk:UHT and extended shelf-life processing dominates UAE production, with ambient distribution protocols engineered for 45°C summer conditions. Dubai and Abu Dhabi households absorb the majority of fresh milk volumes, though margin compression intensifies as private-label supermarket lines expand.
- Yogurt:Fermented dairy commands premium shelf positioning through protein-enriched and functional formulations. Health-conscious expatriate consumers in Dubai Marina and Jumeirah drive demand for Greek-style and probiotic variants, with pharmacy channel placement emerging for diabetes-prevention positioned products.
- Cheese:Ripened and processed formats concentrate in HoReCa procurement contracts.
- Butter:Fat-based spreads face substitution pressure from plant-based alternatives in retail.
Milk absorbs the bulk of installed capacity; yogurt is expanding most quickly.
Distribution Channel:
Channel economics diverge around working capital requirements, with subscription platforms demanding technology investment while supermarkets extract slotting fees that strain smaller processors.
- Supermarkets:Hypermarket networks across Dubai and Abu Dhabi sustain volume dominance through centralized procurement and private-label development. Carrefour and Lulu control shelf access for domestic processors, with bilingual Arabic-English labeling mandates reshaping packaging procurement timelines.
- Online Retail:App-integrated subscription models capture younger expatriate households in Downtown Dubai and Business Bay. Same-day delivery infrastructure in Sharjah and Ras Al Khaimah extends geographic reach beyond traditional retail footprints.
- Convenience Stores:Neighborhood retail in northern emirates offers underpenetrated expansion terrain.
- Specialty Stores:Organic and import-focused formats serve premium positioning strategies.
Supermarkets command the deepest inventory positions; online retail climbs the fastest.
Packaging Type:
Packaging procurement decisions hinge on MOHAP compliance timelines and bilingual labeling mandates that extend lead times for imported materials.
- Tetra Packs:Aseptic carton technology dominates ambient distribution for UHT milk, with multi-layer barrier properties engineered for Emirates climate conditions. Dubai's retail corridor relies on this format for shelf-stable inventory management.
- Bottles:HDPE and PET formats serve fresh milk categories requiring refrigerated logistics. Cold-chain infrastructure investments in northern emirates enable bottle format expansion beyond Dubai's core market.
- Cartons:Gable-top formats compete in fresh segments with shorter shelf lives.
- Bulk:Food service and industrial processing channels drive institutional packaging demand.
Tetra Packs hold the largest installed base; bottles gain share fastest.
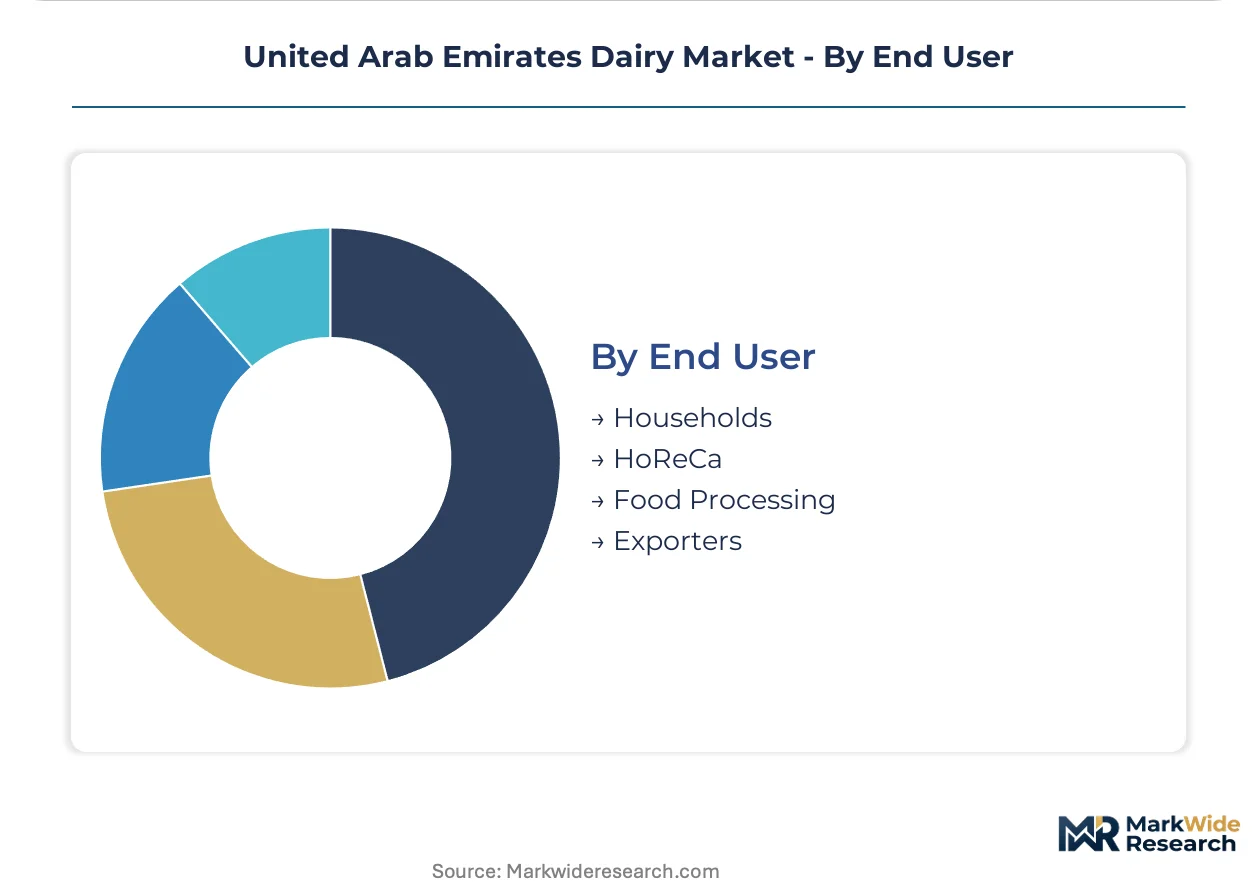
End User:
End-use concentration determines contract structures, with HoReCa offtake agreements offering volume predictability distinct from fragmented household replenishment patterns.
- HoReCa:Hotel and restaurant chains across Dubai and Abu Dhabi generate predictable demand for UHT milk and processed cheese formats. International hospitality brands standardize procurement specifications that favor suppliers with MOHAP laboratory partnerships and established halal certification.
- Households:Expatriate family units in Dubai's residential clusters drive premium functional product adoption. Subscription delivery models displace traditional supermarket replenishment among dual-income professional segments prioritizing convenience.
- Food Processing:Industrial dairy ingredients supply bakery and confectionery manufacturers.
- Exporters:Re-export activity to GCC neighbors leverages UAE's logistics hub position.
HoReCa locks in the majority of contracted volume; households show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's retail and hospitality corridor dominates UAE dairy consumption, with the emirate's hypermarket networks and international hotel chains anchoring volume demand. Cold-chain infrastructure investments now extend distribution reach into secondary markets.
Dubai
International hospitality brands and hypermarket headquarters concentrate procurement decisions here. MOHAP's food safety modernization elevates compliance costs for imported dairy, filtering subscale suppliers. The Dubai Marina and Downtown Dubai residential clusters drive subscription delivery adoption among expatriate professionals.
Abu Dhabi
Desert farming infrastructure and government-backed agricultural investments anchor domestic production capacity. Al Ain Farms leverages integrated operations to supply fresh milk categories. The emirate's food security initiatives prioritize local dairy self-sufficiency through desalinated water infrastructure and imported feedstock logistics.
Sharjah
Same-day delivery infrastructure expansion captures household replenishment outside Dubai's core market. Cold-chain technology upgrades reduce spoilage rates for fresh categories. The emirate's mid-income residential density supports volume growth in standard-tier UHT and yogurt segments.
Northern Emirates
Ajman, Umm Al Quwain, and Fujairah exhibit underpenetrated per-capita dairy consumption relative to Dubai. Direct distribution investments in modern retail capture first-mover advantages. ESMA's halal certification protocols create six-to-nine month entry barriers that favor established suppliers with in-country laboratory partnerships.
Ras Al Khaimah
Tourism development and hospitality construction generate emerging HoReCa demand for processed cheese and UHT formats. Refrigerated logistics networks now enable fresh category distribution beyond ambient-stable lines. The emirate's lower commercial real estate costs attract secondary distribution center placement.
United Arab Emirates Dairy Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across the UAE dairy sector. Domestic integrated operators with desert farming infrastructure face competition from import-reliant brands leveraging specialized formulations. The market structure consolidates around three archetypes: vertically integrated local producers, regional Gulf cooperatives with cross-border supply networks, and European multinationals targeting premium functional segments. Competitive dynamics center on cold-chain infrastructure expansion and direct-to-retail channel control.
Among integrated domestic producers, Al Ain Farms and Marmum Dairy Farm exemplify the capital-intensive archetype with captive supply chains. Arla Foods amba represents the European multinational positioning, while Almarai Co. anchors the regional Gulf cooperative model with cross-emirate distribution scale.
| Leading Market Players |
|---|
| Al Ain Farms (YAS Holding) |
| Arla Foods amba |
| Emirates Rawabi |
| Marmum Dairy Farm |
| Saudia Dairy & Foodstuff Co. (SADAFCO) |
| Almarai Co. |
| Groupe Lactalis |
| Agthia Group PJSC |
| National Food Products Co. (NFPC Milco, Lacnor) |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers with captive desert farming infrastructure anchor supply-side discipline across the Emirates, translating feedstock cost exposure into tiered pricing power that commodity fluid milk processors cannot replicate. This ownership pattern concentrates margin capture at the premium functional tier while ambient-stable UHT lines face persistent price compression from private-label supermarket competition.
Pricing Analysis
Value-based pricing anchored to cold-chain reliability and halal certification integrity commands premium positioning across Dubai's hospitality corridor. Three-tier pricing structure across premium organic, standard fortified, and economy private-label levels stratifies margin pools, with certification grade and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from feed input volatility compressing farm-gate margins for domestic producers. HoReCa procurement teams exhibit lowest price sensitivity due to standardized menu cost structures, while northern emirate household segments drive hardest bargain hunting.
Supply Chain Analysis
Reverse-logistics for temperature-compromised fresh milk returns remains underdeveloped across UAE cold-chain networks, creating write-off cost burdens that distort upstream planning. Geographic supply concentration centers on domestic desert dairy operations in Abu Dhabi and Al Ain, with supplemental feedstock draws from Argentina and the United States. Alfalfa, soybean meal, and desalinated water inputs anchor cost structures vulnerable to energy-linked price volatility. Single-source vulnerability in veterinary pharmaceutical supplies for herd health management constrains biosecurity resilience. Distribution runs through hypermarket centralized procurement with emerging direct-to-consumer subscription platforms disintermediating traditional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE dairy sector sits at a technology-transition inflection where automated herd management platforms and sensor-based health monitoring displace labor-intensive legacy operations. This displacement favors capital-rich operators capable of absorbing upfront automation investment while smaller processors face obsolescence risk.
For Market Incumbents: Hedge against margin compression in commodity fluid milk by deepening backward integration into feedstock logistics and expanding pharmacy channel placement for functional yogurt formats. Automation investment in robotic milking systems preserves labor cost advantage as regional wage pressures intensify. ESMA halal certification complexity creates defensive moats against import competition.
For New Entrants and Emerging Players: Dual-income professional households in Sharjah and Ras Al Khaimah represent the most penetrable buyer archetype currently underserved by subscription delivery infrastructure. Direct distribution investments in northern emirate modern retail capture first-mover positioning ahead of incumbent channel expansion. App-integrated fresh milk subscriptions with Arabic-language interfaces address localized convenience gaps.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap processors with established MOHAP laboratory partnerships in Dubai and Abu Dhabi as feed cost volatility strains subscale competitors. Long-term viability over the next decade rests on cold-chain technology ownership and direct retail channel control. Monitor northern emirate per-capita consumption convergence toward Dubai levels as inflection signal for geographic expansion returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Same-day delivery capability in Sharjah and Ras Al Khaimah unlocks household subscription penetration. |
| Backward Integration into Feed Logistics | Captive alfalfa and soybean meal sourcing insulates Al Ain Farms from global commodity price cycles. |
| Functional Product Line Extension | Protein-enriched yogurt with diabetes-prevention positioning opens pharmacy channel access in Dubai Marina. |
| Direct-to-Consumer Platform Launch | App-integrated subscriptions displace Carrefour and Lulu replenishment cycles among expatriate professionals. |
| Halal Certification Investment | ESMA laboratory partnerships reduce six-to-nine month entry barriers for imported brand expansion. |
Research Methodology
Independent corroboration across dairy processor executives, cold-chain logistics operators, MOHAP regulatory affairs specialists, and hypermarket category buyers underwrites the qualitative findings in this study. Primary fieldwork with desert farm operations managers and veterinary health directors combined with secondary validation from UAE customs trade data, ESMA technical regulation filings, and MOHAP food safety bulletins. Bottom-up volume modeling triangulated against top-down consumption surveys across Dubai, Abu Dhabi, and northern emirates.
Rate-of-change decomposition across product type, distribution channel, packaging format, and end-user segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization trends. Modeled inputs incorporated feedstock cost indices, desalinated water energy pricing, and HoReCa contract renewal patterns specific to UAE hospitality procurement.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to groundwater depletion limits and evolving MOHAP fortification mandates. Practitioners should monitor northern emirate retail infrastructure buildout and subscription platform adoption rates among dual-income households for early signals of channel shift velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Dairy Market
Dairy Products
Clotted Cream Market
Dairy Products
Natural Cheese Market
Dairy Products
Sour Cream Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Condensed Milk Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Global Butter Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Lactic Butter Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
White Cheese Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Global Grass Fed Dairy Product Market