
 Hair Tonic Market | 2026-2036
Hair Tonic Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Tonic Market Insights
The capital-intensity gap between contract manufacturers and brand owners is collapsing as in-house fermentation and extraction capabilities become table stakes. Rhine International Biotechnology leverages captive bioreactor capacity in Guangdong to control raw material costs for peptide-based tonics. NatureLab. Tokyo anchors its position through dedicated R&D on ceramide complexes, while HSA Cosmetics competes via vertical integration into fragrance compounding for differentiated sensorial profiles.
Hair tonic denotes a topical scalp treatment typically formulated with ethanol-water bases carrying active concentrations of minoxidil, caffeine, or botanical extracts such as ginseng saponins and saw palmetto liposterols, designed to improve follicle vascularization, reduce dihydrotestosterone binding, or restore sebum balance. Herbal tonic formulations command premium shelf positioning in Asian markets where traditional medicine associations confer trust, while organic tonic segments attract clean-beauty consumers willing to absorb higher per-unit costs for certified ingredient provenance. Spray formulations lead volume due to dosing convenience, though serum formats capture disproportionate margin pools through concentrated active loading and clinical positioning.
REACH compliance in Europe and China's NMPA cosmetic registration requirements are reshaping preservative choices and substantiation protocols, forcing reformulation cycles that favor players with dedicated regulatory affairs teams. The US FDA maintains distinct oversight for drug-claim hair growth products versus cosmetic tonics, creating a bifurcated compliance landscape that rewards precise positioning. Stakeholders must monitor evolving classification boundaries between cosmetic and drug claims across major jurisdictions to avoid market access disruptions.
Market Dynamics
Professional salon channels are consolidating procurement power while EU REACH compliance forces wholesale preservative substitution, collapsing the traditional cost advantage of synthetic formulations and redistributing margin toward botanical ingredient suppliers with captive extraction infrastructure.
Growth Catalysts
- REACH-driven reformulation:The EU's tightening restrictions on synthetic preservatives accelerate migration toward botanical actives, expanding addressable premium shelf space in European retail.
- Professional salon channel expansion:Male grooming segments in professional settings normalize scalp treatment protocols, creating recurring B2B demand with higher retention than consumer-direct channels.
- TCM heritage positioning:Domestic Chinese brands leverage traditional medicine credentials in tier-one cities, capturing trust premiums against imported competitors without clinical marketing spend.
Market Restraints
- Ethanol-water base cost volatility:Bioethanol feedstock prices fluctuate with agricultural commodity cycles, compressing margins for volume-format spray producers.
- Peptide supply concentration:Contract fermentation capacity clusters in Guangdong province, creating single-geography exposure for premium serum manufacturers.
- Minoxidil regulatory bifurcation:The US FDA maintains distinct drug-claim oversight versus cosmetic classification, fragmenting product development roadmaps and compliance investment.
Strategic Opportunities
- Underpenetrated Indian mass market:Ayurvedic scalp oil traditions create receptive entry points for tonic formats with herbal positioning at accessible price tiers.
- Clean beauty certification tailwind:COSMOS and ECOCERT standards attract capital-light brand entrants willing to absorb higher per-unit ingredient costs for provenance marketing.
- Subscription direct-to-consumer channels:Replenishment-dependent formats like daily-use serums enable recurring revenue models with superior lifetime value metrics versus retail.
Industry Challenges
- Regulatory affairs talent scarcity:NMPA cosmetic registration requirements in China demand specialized dossier preparation skills that outpace available consultant supply.
- Clinical substantiation capex:Follicle vascularization claims require trichoscopy instrumentation and dermatologist partnerships that strain mid-cap R&D budgets.
- Cross-border formulation drift:Divergent preservative approvals between EU REACH, US FDA, and China NMPA force SKU proliferation that complicates inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Tonic Market |
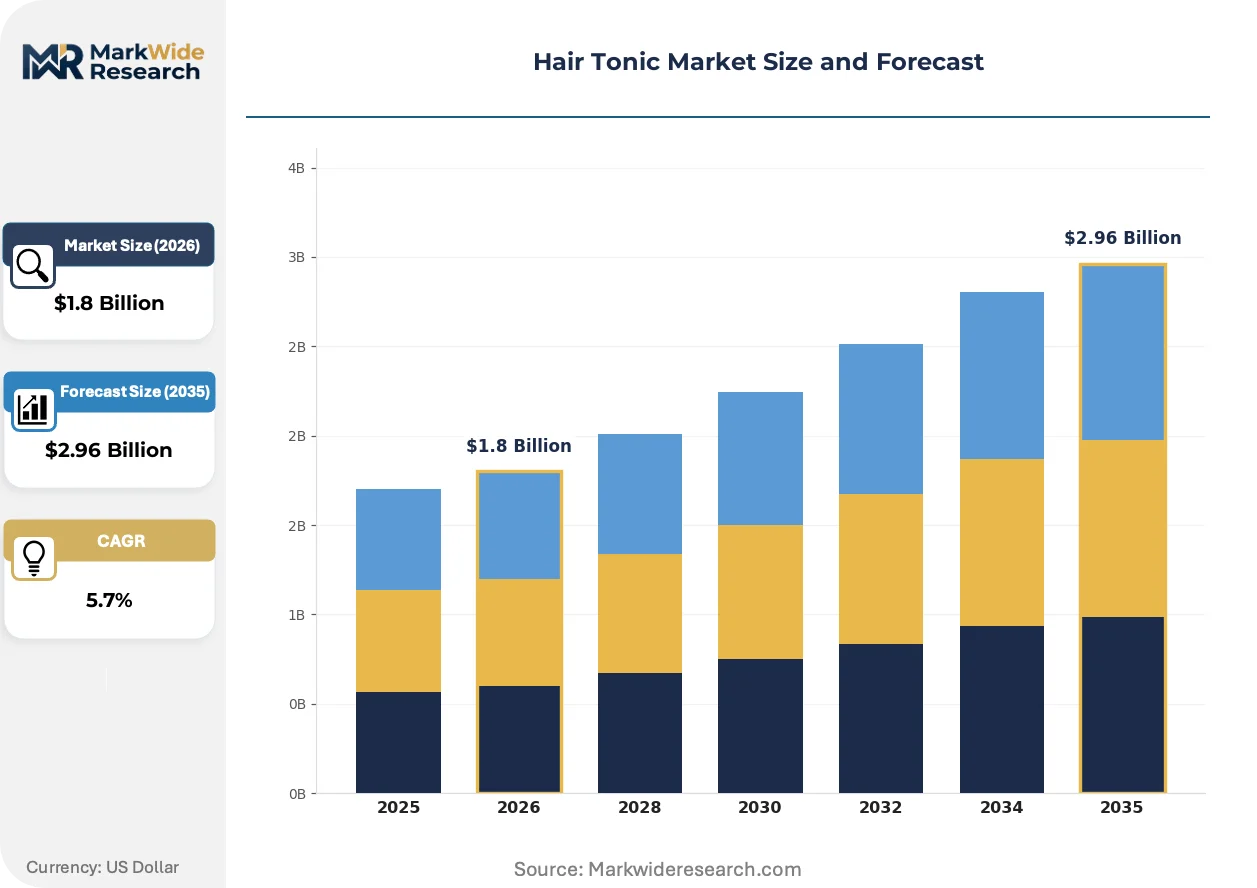
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Tonic, Chemical-Based Tonic, Organic Tonic, Leave-In Treatment Target Audience: Men, Women, Children, Seniors Distribution Channel: Online Retail, Supermarkets, Salons, Pharmacies Formulation: Spray, Oil, Gel, Serum |
| Companies Covered | Rhine International Biotechnology (Guangdong) Co., Ltd., Made By Nature Labs, Poleview Biotechnology Co., Ltd., RainShadow Labs, HSA Cosmetics, Guangzhou Labochy Cosmetics Co., Ltd., Guangzhou Chingo Cosmetics Co., Ltd., NatureLab. Tokyo, Guangzhou Haishi Biological Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Tonic Market Trends and Innovations
Active delivery systems and claim substantiation protocols are diverging sharply between clinical-positioned and wellness-positioned products, creating parallel development tracks with incompatible investment profiles and distribution strategies.
Fermentation-derived peptide complexes are fragmenting the traditional active ingredient supply structure. Bioreactor-captive manufacturers now supply bioactive signal molecules directly to finished goods producers, bypassing commodity chemical distributors. This shift compresses margin pools for traditional ingredient traders while enabling precise batch-to-batch consistency claims that command shelf price premiums in professional channels.
REACH authorization requirements for synthetic biocides are accelerating botanical preservative adoption across European formulations. ECHA's candidate list expansion forces reformulation cycles that favor players with dedicated regulatory affairs teams and pre-validated natural alternatives. German and French mass-market retailers now require full ingredient transparency disclosures that exceed baseline compliance, filtering supplier bases toward documented supply chain operators.
Serum-format consumption is displacing spray volumes in premium positioning. Concentrated active loading enables clinical-style dosing protocols that justify per-unit price multiples, while spray formats commoditize toward convenience-driven mass retail. This bifurcation concentrates margin recovery in South Korean and Japanese domestic markets where multi-step scalp care routines already dominate consumer behavior patterns.
Hair Tonic Market Segmentation
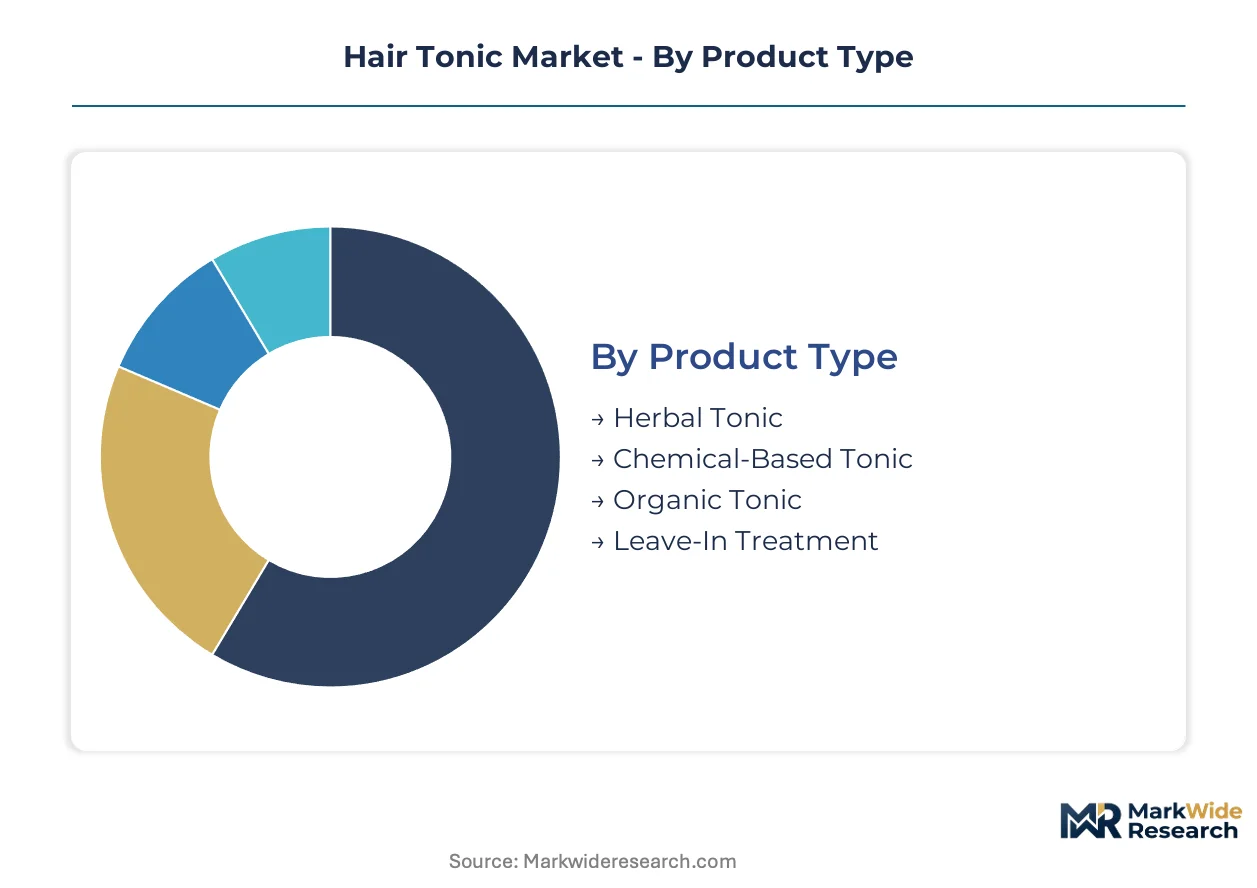
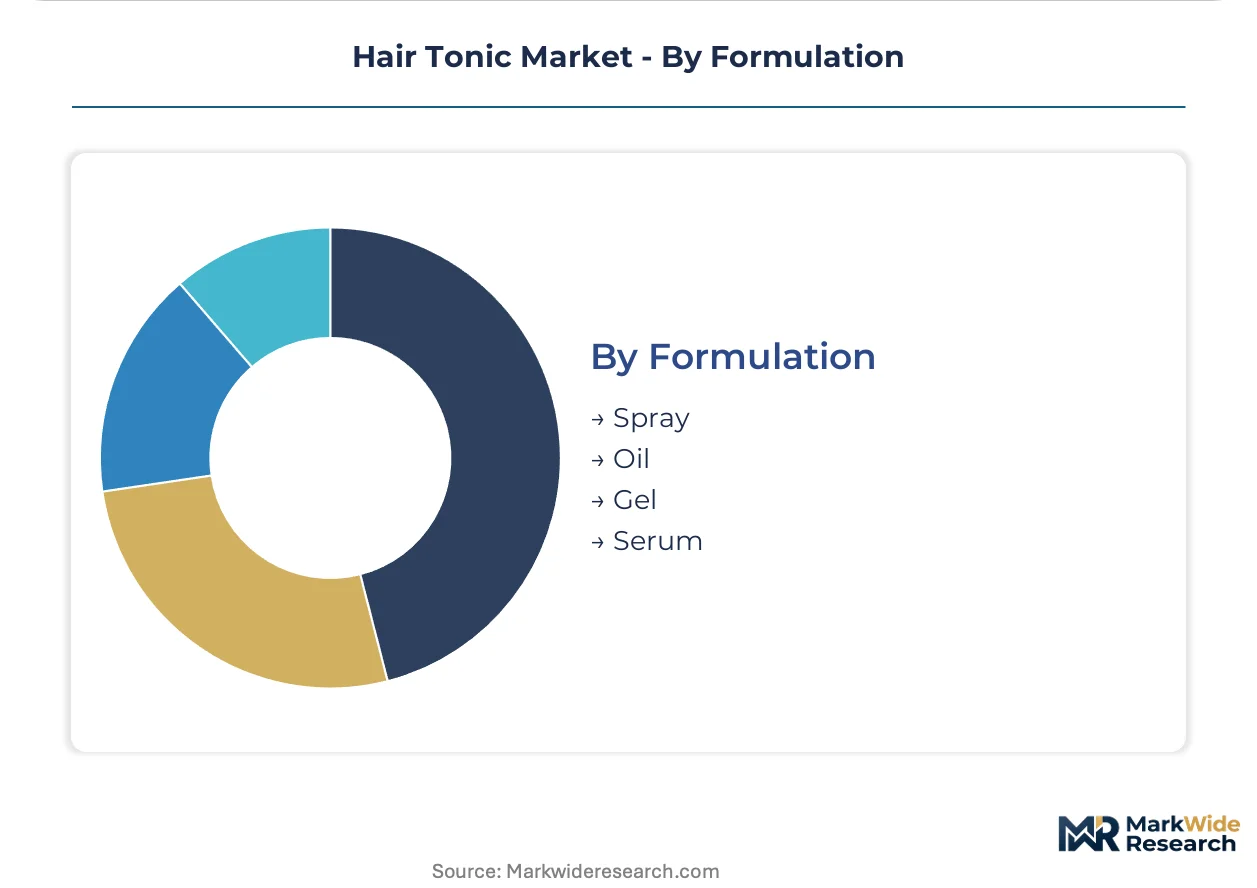
Segmentation in the hair tonic market determines channel economics and margin recovery. Spray formats dominate volume throughput in mass retail, while serum concentrates capture professional salon premiums. Regulatory positioning—cosmetic versus drug-claim—further fragments product development roadmaps across jurisdictions.
Product Type:
Channel-mix patterns diverge sharply: herbal and organic variants command specialty retail and professional salon placement, while chemical-based formulations anchor pharmacy and mass-market distribution.
- Herbal Tonic:Formulations leverage ginseng saponins, saw palmetto liposterols, and traditional medicine botanicals in ethanol-water carriers. Demand clusters in China's tier-one cities and South Korean domestic markets where TCM heritage credentials confer trust premiums against imported competitors. Professional salons in Guangzhou and Seoul drive recurring B2B procurement with higher retention rates than consumer-direct channels.
- Chemical-Based Tonic:Synthetic active platforms center on minoxidil, caffeine complexes, and peptide signal molecules with standardized concentration protocols. Pharmacy channels in Germany and the United States concentrate volume, though FDA drug-claim bifurcation fragments compliance investment and limits cosmetic-positioned variants.
- Organic Tonic:COSMOS and ECOCERT-certified ingredient provenance attracts clean-beauty consumers absorbing higher per-unit costs. Direct-to-consumer subscription models enable recurring revenue capture with superior lifetime value metrics versus retail.
- Leave-In Treatment:Extended-contact formulations with ceramide complexes and ceramide precursors target overnight repair protocols. Japanese domestic manufacturers lead format innovation through multi-step scalp care routine integration.
Herbal tonic dominates installed base in Asian markets. Organic tonic is where expansion concentrates in European premium retail.
Target Audience:
Cost-tier stratification separates clinical-positioned premium offerings from accessible mass-market entry points, with male grooming segments driving professional channel normalization.
- Men:Androgenetic alopecia protocols with DHT-binding inhibitors and follicle vascularization actives. Male grooming segments in professional salon settings normalize scalp treatment as recurring service revenue.
- Women:Postpartum and hormonal fluctuation-focused formulations with sebum balance restoration. Premium serum concentrates capture disproportionate margin pools through clinical-style dosing positioning.
- Children:Gentle surfactant-free bases with botanical soothing agents for sensitive scalp conditions. Pediatric dermatologist partnerships required for claim substantiation strain mid-cap R&D budgets.
- Seniors:Age-related thinning protocols with peptide complexes and bioactive signal molecules. German and French mass-market retailers require full ingredient transparency disclosures filtering supplier bases.
Men's segments anchor professional salon revenue. Women's segments are climbing the fastest in direct-to-consumer subscription channels.
Distribution Channel:
Volume concentration versus margin recovery splits across channel types, with digital-native entrants disrupting traditional pharmacy dominance in claim-substantiated segments.
- Online Retail:Subscription replenishment models for daily-use serums enable recurring revenue capture. Clean beauty certification standards attract capital-light brand entrants willing to absorb higher per-unit ingredient costs for provenance marketing.
- Supermarkets:Spray-format commoditization toward convenience-driven mass retail with ethanol-water base cost volatility compressing margins. Bioethanol feedstock price fluctuations with agricultural commodity cycles challenge volume producers.
- Salons:Professional scalp treatment protocol normalization creates recurring B2B demand with higher retention than consumer-direct channels. Captive bioreactor capacity in Guangdong controls raw material costs for peptide-based professional offerings.
- Pharmacies:Clinical-positioned minoxidil and drug-claim products with dermatologist endorsement requirements. NMPA cosmetic registration dossier preparation skills outpace available consultant supply in China.
Pharmacy channels dominate drug-claim installed base. Salon channels are gaining share fastest in male grooming protocol expansion.
Formulation:
Application-method preferences fragment by geography, with multi-step routine cultures in Northeast Asia concentrating serum adoption while spray convenience drives mass-market penetration elsewhere.
- Spray:Ethanol-water base delivery systems with dosing convenience for daily-use protocols. Volume leadership in mass retail though margin compression from bioethanol feedstock volatility challenges producers.
- Oil:Ayurvedic scalp oil tradition alignment creates receptive entry points for herbal-positioned formats at accessible price tiers in Indian mass market. Extended contact time enables lipid-soluble active delivery.
- Gel:Non-drip styling-compatible bases targeting younger demographics with sensorial preference for lightweight textures. Fragrance compounding differentiation commands shelf price premiums in professional channels.
- Serum:Concentrated active loading enables clinical-style dosing protocols justifying per-unit price multiples. South Korean and Japanese domestic markets where multi-step scalp care routines dominate consumer behavior patterns concentrate adoption.
Spray formulations dominate volume installed base. Serum formats are expanding most quickly in premium positioning and professional channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for peptide actives and botanical extracts shapes regional trade flows, with captive fermentation capacity in Guangdong province supplying finished goods producers across Northeast Asia while European manufacturers source certified organic feedstock through specialized distributors.
China
Tier-one cities drive premium herbal tonic demand through TCM heritage positioning against imported competitors. NMPA cosmetic registration requirements force specialized dossier preparation that outpaces available consultant supply. Guangdong province concentrates captive bioreactor capacity for peptide-based professional offerings serving salon channels in Guangzhou and Shenzhen.
Japan
Multi-step scalp care routines concentrate serum-format adoption in Kanto and Kansai metropolitan areas. METI standards for quasi-drug classification create distinct compliance pathways for follicle vascularization claims. Osaka-based manufacturers lead ceramide complex innovation for overnight repair protocols targeting aging demographics.
Germany
Pharmacy channels anchor clinical-positioned minoxidil distribution with dermatologist endorsement requirements. REACH authorization for synthetic biocides accelerates botanical preservative adoption, forcing reformulation cycles that favor documented supply chain operators. Mass-market retailers in Bavaria and North Rhine-Westphalia now mandate full ingredient transparency disclosures exceeding baseline ECHA compliance.
United States
FDA drug-claim bifurcation fragments product development roadmaps between cosmetic tonics and hair growth treatments. Subscription direct-to-consumer channels enable recurring revenue capture for daily-use serum formats. California and New York metro areas concentrate clean beauty certification demand, attracting capital-light brand entrants willing to absorb higher per-unit ingredient costs.
India
Ayurvedic scalp oil traditions create receptive entry points for herbal-positioned tonic formats at accessible price tiers. BIS standards for cosmetic safety intersect with state-level Ayurveda promotion policies in Maharashtra and Karnataka. Mumbai and Bangalore industrial clusters support contract manufacturing for domestic brands competing against multinational entrants.
Hair Tonic Market Competitive Landscape
Concentration sits with vertically integrated bioreactor operators and dedicated R&D houses rather than commodity formulators. The vendor base spans captive fermentation specialists, botanical extraction houses, and fragrance compounding integrators with divergent margin recovery profiles. Two strategic archetypes dominate: Guangdong-based manufacturers controlling upstream peptide supply, and Japanese specialists commanding ceramide complex premiums. Competitive moves center on backward integration into raw material production and regulatory affairs team expansion to manage divergent preservative approvals.
Among China-based biotechnology operators, Rhine International Biotechnology (Guangdong) Co., Ltd. and Guangzhou Labochy Cosmetics Co., Ltd. exemplify the captive bioreactor archetype, while NatureLab. Tokyo and HSA Cosmetics occupy positions within the R&D-intensive and sensorial-differentiation tiers respectively. These entities represent the geographic and strategic fragmentation defining competitive positioning across professional salon and direct-to-consumer channels.
| Leading Market Players |
|---|
| Rhine International Biotechnology (Guangdong) Co., Ltd. |
| Made By Nature Labs |
| Poleview Biotechnology Co., Ltd. |
| RainShadow Labs |
| HSA Cosmetics |
| Guangzhou Labochy Cosmetics Co., Ltd. |
| Guangzhou Chingo Cosmetics Co., Ltd. |
| NatureLab. Tokyo |
| Guangzhou Haishi Biological Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Botanical actives substituting synthetic preservatives simultaneously redistributes manufacturing toward Guangdong extraction clusters and compresses margin pools for commodity chemical distributors unable to demonstrate batch-to-batch consistency. Professional salon buyers now absorb per-unit premiums for fermented peptide complexes while mass-market spray formats face ethanol feedstock volatility.
Pricing Analysis
Professional salon buyers anchor a three-tier pricing structure across premium serum, standard herbal, and economy spray levels. Price differentiation rests on certification grade—COSMOS and ECOCERT tiers command shelf premiums—and captive bioreactor ownership that insulates against peptide supply shocks. Cost compression in spray formats is intensifying because bioethanol prices track agricultural commodity cycles. Direct-to-consumer subscription segments exhibit lowest price sensitivity, while supermarket mass-market buyers demand volume discounts that strain ethanol-water base producers.
Supply Chain Analysis
Strategic stockpiling of botanical extracts dominates inventory strategy among European formulators facing REACH-driven preservative substitution deadlines. Raw material supply concentrates in China, South Korea, and Japan, with peptide fermentation capacity clustering in Guangdong province. Formulators draw from ginseng saponin harvests, saw palmetto liposterol extractions, and ceramide precursor feedstocks. Single-source vulnerability in Guangdong bioreactor infrastructure threatens premium serum manufacturers. Distribution runs through professional salon networks for high-margin concentrates and pharmacy channels for clinical-positioned SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hair tonic market sits at early-cycle expansion, with male grooming protocol normalization in professional salons driving recurring revenue capture ahead of household penetration saturation.
For Market Incumbents: Compound regulatory affairs capabilities to manage divergent NMPA, FDA, and REACH dossier requirements that outpace available consultant supply. Deepen backward integration into captive fermentation capacity to defend margin position against Guangdong-based peptide suppliers. Prioritize ceramide complex R&D investment as Japanese competitors consolidate overnight repair protocol leadership. For New Entrants and Emerging Players: COSMOS certification fast-tracks entry into European premium retail where mass-market retailers now mandate full ingredient transparency disclosures exceeding baseline ECHA compliance. White-space concentration sits in India's Ayurvedic-positioned mass market and subscription direct-to-consumer channels for daily-use serum formats. Launch through clean-beauty capital-light positioning with provenance marketing that justifies higher per-unit ingredient absorption. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated bioreactor operators over commodity formulators. Long-term viability across the next decade hinges on regulatory affairs team scale and pre-validated natural preservative portfolios. Acquisition targets should demonstrate documented supply chain operations with batch-to-batch consistency claims. Watch NMPA cosmetic registration backlog clearance as inflection indicator for China market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Buildout | Guangdong bioreactor ownership insulates peptide supply costs for professional salon channels. |
| REACH Compliance Certification | ECHA-aligned botanical preservative validation opens premium European retail placement. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture for serum formats exceeds retail lifetime value metrics. |
| TCM Heritage Brand Repositioning | Domestic Chinese credentials in tier-one cities capture trust premiums against imports. |
| Professional Salon Channel Partnership | B2B procurement normalization in male grooming segments anchors recurring demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs directors, professional salon procurement managers, botanical extraction facility operators, and clean-beauty brand founders; and secondary validation through NMPA cosmetic registration databases, ECHA REACH authorization records, FDA drug-claim classification rulings, and customs trade flow documentation. Bottom-up triangulation across formulation-grade segmentation and top-down cross-check against channel revenue estimates anchored forecast integrity.
Across the projection horizon, the analytical framework modeled volume and value outputs through product type, target audience, distribution channel, and formulation dimensions. CAGRs derived from trend-line extrapolation of professional salon channel expansion rates, peptide supply capacity additions, and regulatory-driven reformulation cycle frequencies. Forecast inputs incorporated bioethanol feedstock price correlation coefficients and COSMOS certification adoption curves.
Underlying assumptions cover sustained REACH enforcement stringency and NMPA consultant supply constraints, with deviation risk concentrated in peptide fermentation capacity expansion timelines and minoxidil regulatory reclassification proceedings. Revision becomes warranted when professional salon channel penetration crosses mass-market volume thresholds or preservative approval divergences trigger SKU proliferation beyond inventory planning tolerance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Europe Hair Care Market
Hair Care
France Haircare Market
Hair Care
Protein Shampoo Market
Hair Care
Australia Hair Removal Market
Hair Care
China Hair Care Products Market
Hair Care
Hair Care Appliances Market
Hair Care
United States Hair Care Market
Hair Care
Hair Spray Market
Hair Care
Organic Hair Care Market
Hair Care
Men's Hairspray Market
Hair Care
Hair Dye Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Germany Hair Care Market
Hair Care
Asia Pacific Hair Care Market