
 Asia Pacific Hair Care Market | 2026-2036
Asia Pacific Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hair Care Market Outlook
Market Context
Multi-source ingredient procurement is rebalancing toward regional suppliers as Asian formulators reduce European chemical dependencies. Unilever sustains manufacturing scale through distributed production networks across Southeast Asia. L'Oréal S.A. dominates premium positioning in China's urban centers with dedicated R&D facilities in Shanghai. Marico Limited anchors mass-market penetration through deep distribution into India's tier-two and tier-three cities.
Technical Definition and Segments
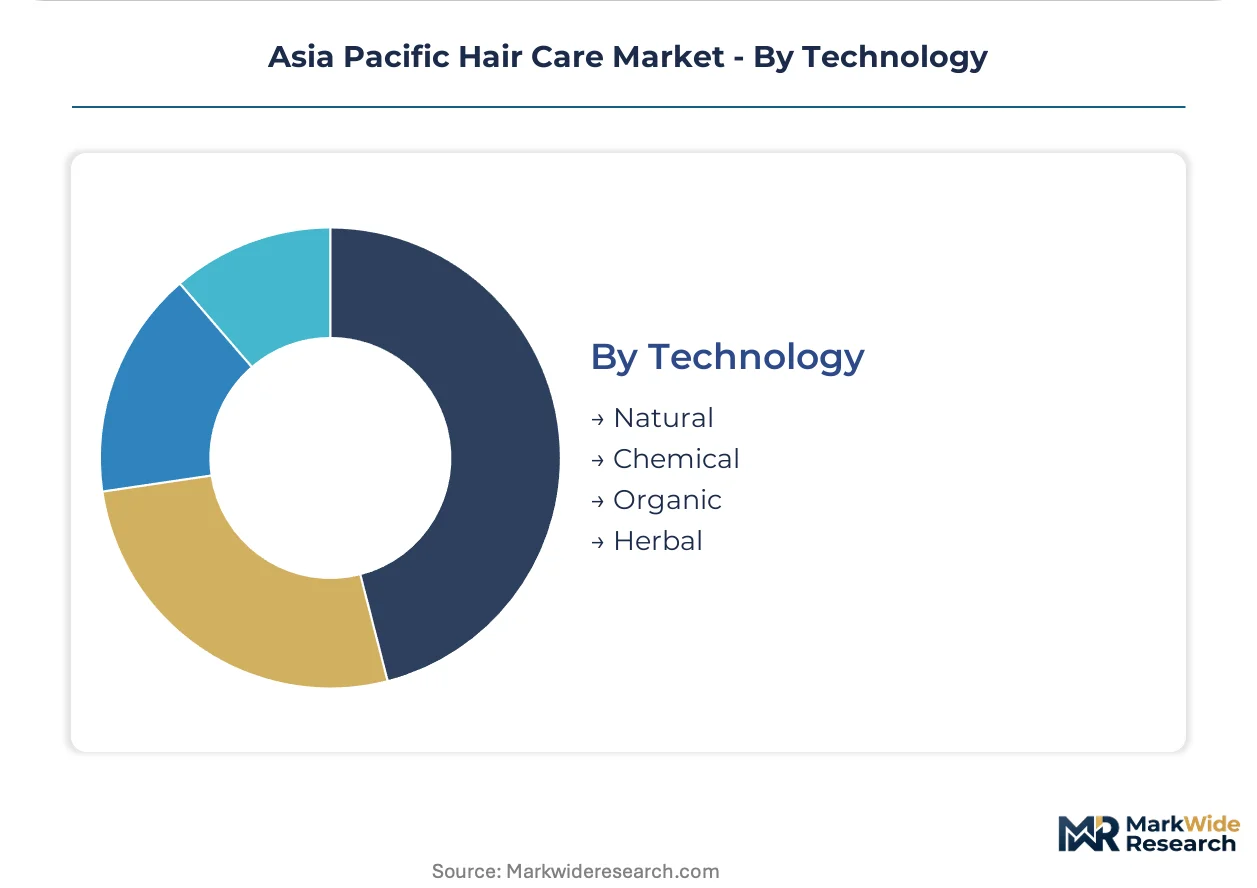
Asia Pacific hair care encompasses surfactant-based cleansing systems, lipid conditioners, active serum formulations, and botanical oil blends engineered for diverse hair textures across tropical and temperate climates, serving both daily consumer maintenance and professional salon treatment protocols. Shampoos and hair oils occupy the largest volume positions, reflecting sustained traditional oiling practices in India and Indonesia alongside modern cleansing habits in East Asian markets. The technology dimension shows natural and herbal segments expanding fastest as consumers reject sulfates and parabens, while chemical-based colorants retain professional salon loyalty for performance reliability.
Regulatory Frame
China's NMPA and SAMR enforce pre-market registration and ingredient disclosure rules that determine which formulations enter the world's second-largest beauty market. India's BIS and CDSCO regulate cosmetic safety standards and herbal claim substantiation, creating compliance layers for ayurveda-positioned products. Japan's MHLW through METI coordination maintains stringent quasi-drug classifications for anti-hair-loss and scalp treatment claims. Stakeholders must monitor diverging national ingredient approval lists that fragment formulation strategies across the region.
Market Dynamics
Scalp microbiome science is restructuring formulation priorities across Asia Pacific, forcing manufacturers to revalidate surfactant systems and preservative choices against emerging clinical evidence on barrier function.
Growth Catalysts
- China's NMPA pre-market registration pathway:Streamlined herbal claim categories accelerate ayurveda-positioned entrants from India and Southeast Asian botanical suppliers.
- Professional salon channel expansion:Tier-one urban centers in China and South Korea drive uptake of treatment-grade home care protocols.
- Biotechnology-derived actives:Fermentation-based ceramides and peptides replace petrochemical conditioning agents in premium formulations.
Market Restraints
- Palm oil and coconut fatty acid volatility:Base surfactant costs fluctuate with Indonesian and Malaysian feedstock availability.
- European chemical dependency reduction:Asian formulators face reformulation costs as specialty ester suppliers consolidate in Germany and Switzerland.
- Japan's MHLW quasi-drug classification delays:Anti-hair-loss claim approvals extend commercialization timelines by 18-24 months.
Strategic Opportunities
- Vietnam and Philippines mass-market penetration:Modern trade expansion in secondary cities creates distribution white space for sachet-format conditioners.
- India's BIS tightening:Stricter heavy metal limits for herbal products favor GMP-certified domestic manufacturers over informal competitors.
- AI-driven scalp diagnostic devices:Hardware-software convergence enables personalized serum recommendations in retail and salon channels.
Industry Challenges
- Cosmetic chemist specialization gap:Formulation expertise in microbiome-compatible preservation systems remains concentrated in Japan and South Korea.
- Multi-jurisdiction dossier management:Divergent preservative approval lists between China's NMPA, India's CDSCO, and ASEAN cosmetic directives multiply compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hair Care Market |
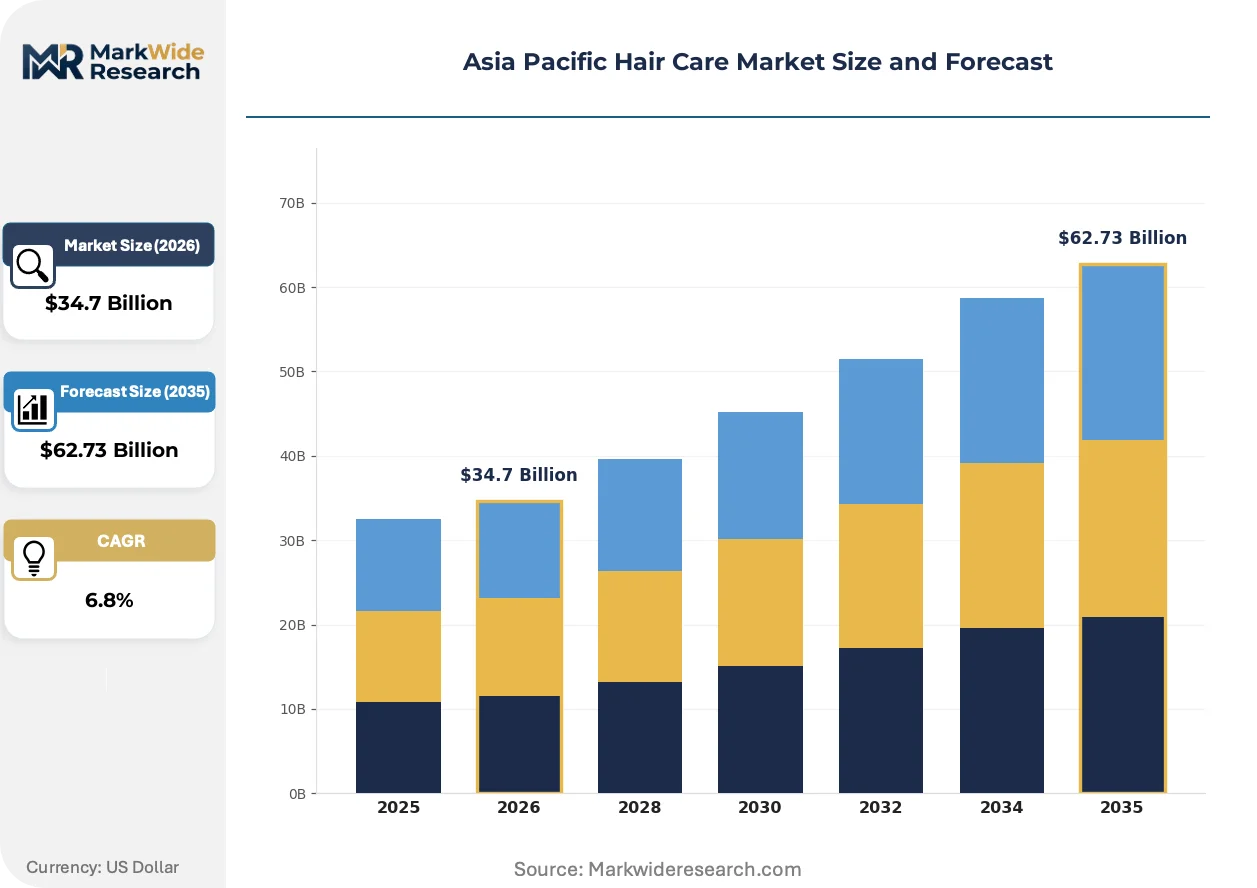
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Serums, Hair Oils Application: Salon, Household, Institutional, Professional Customer Type: Men, Women, Children, Salons Technology: Natural, Chemical, Organic, Herbal |
| Companies Covered | Unilever, Marico Limited, L'Oréal S.A., Mandom Corporation, Dabur India Ltd, Kao Corporation, Henkel AG & Co. KGaA, Hoyu Co. Ltd, Procter & Gamble, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hair Care Market Strategic Shifts
Biotechnology and digital diagnostics are compressing product development cycles while fragmenting consumer expectations across performance, sustainability, and personalization axes.
Fermentation-derived postbiotics is integrating into scalp treatment formulations as a functional alternative to traditional antifungal actives. South Korean and Japanese manufacturers lead adoption, with clinical substantiation timelines shortening from 36 to 18 months. This shift is integrating microbiome science into mainstream mass-market positioning previously reserved for dermatological brands.
India's BIS cosmetic safety standards revision is eliminating informal ayurveda suppliers lacking heavy metal testing infrastructure. The regulation mandates third-party certification for lead and arsenic in herbal hair oils. Mass-market brands with captive laboratory capacity in Mumbai and Bangalore capture shelf space as uncertified competitors exit modern trade.
Subscription-based personalized hair care is displacing conventional trial-and-repeat purchasing in China's tier-one cities. Algorithmic matching of scalp diagnostic data to evolving serum formulations locks consumers into 6-month replenishment cycles. This pattern concentrates customer lifetime value with direct-to-consumer platforms at the expense of traditional retail margins.
Asia Pacific Hair Care Market Segmentation
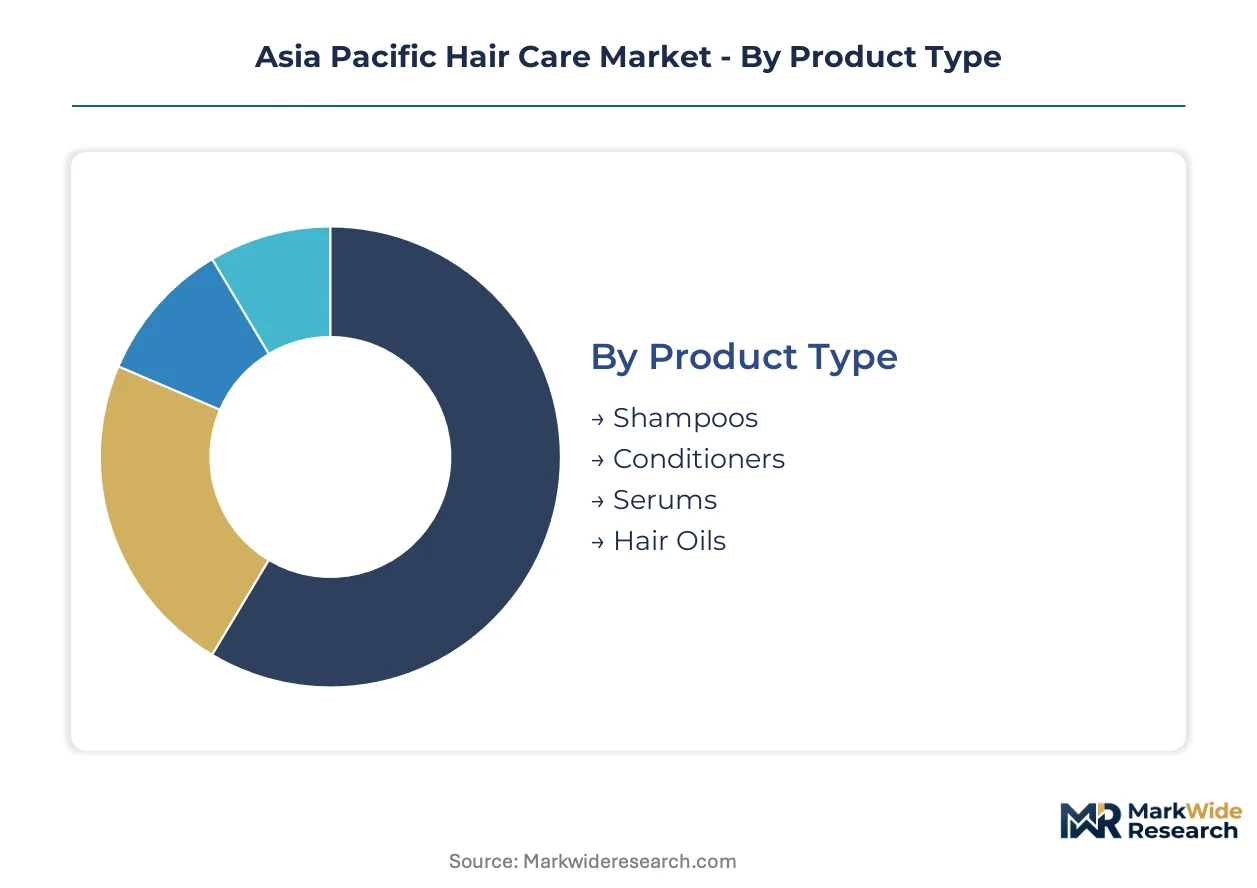
Segmentation in Asia Pacific hair care reveals how formulation technology, distribution channel, and demographic targeting intersect to create distinct competitive arenas. Manufacturers must align R&D investment and regulatory compliance strategies against these axes to capture value across divergent consumer expectations.
Product Type:
Surfactant chemistry and delivery format determine manufacturing infrastructure requirements and margin profiles across this axis.
- Shampoos:Anionic and amphoteric surfactant systems dominate volume production, with sulfate-free variants commanding premium shelf positioning in China's tier-one cities. India's mass-market sachet economy sustains penetration into rural households where per-wash cost sensitivity remains acute.
- Conditioners:Cationic quaternary ammonium compounds and silicone emulsions address damage repair positioning. South Korean consumers in Seoul and Busan drive uptake of rinse-off treatments with scalp-soothing actives, reflecting dual-function expectations.
- Serums:Concentrated active delivery systems target specific concerns through leave-in formats. Penetration concentrates in professional salon channels and premium direct-to-consumer platforms.
- Hair Oils:Traditional coconut, amla, and argan-based formulations retain cultural resonance across India and Indonesia. India's BIS heavy metal testing mandates are restructuring supplier bases toward GMP-certified domestic manufacturers.
Mature deployment sits with shampoos. Newer deployment is concentrated in serums.
Application:
Channel selection dictates formulation performance standards, packaging specifications, and service integration requirements.
- Salon:Treatment-grade protocols demand professional-only SKUs with higher active concentrations. China's urban salon density in Shanghai and Guangzhou supports backbar-sized formats with specialized application training.
- Household:Mass-market retail and e-commerce platforms serve daily maintenance routines. Volume concentrates in multi-use family sizes across Southeast Asian modern trade expansion.
- Institutional:Hospitality and healthcare procurement specifications prioritize bulk formats and hypoallergenic positioning. Compliance with Japan's MHLW standards opens access to premium facility contracts.
- Professional:Stylist-exclusive lines with diagnostic protocols and customized mixing systems. South Korean manufacturers lead hardware-software integration for scalp analysis tools.
Volume leadership rests with household. Margin expansion concentrates in professional.
Customer Type:
Demographic targeting shapes fragrance profiles, packaging aesthetics, and claim substantiation pathways.
- Men:Simplified routines with dual-purpose cleansing and styling functions. Scalp health positioning gains traction among younger cohorts in South Korea and urban China.
- Women:Multi-step regimens spanning cleansing, treatment, and styling categories. Premiumization trends in India's metropolitan centers drive ayurveda-positioned brand equity.
- Children:Mild surfactant systems with tear-free formulations. Regulatory scrutiny of preservative systems intensifies under China's NMPA and India's BIS frameworks.
- Salons:B2B procurement relationships with technical training and equipment bundling. Professional loyalty programs sustain recurring revenue in Japan's mature service market.
Value capture concentrates with women. Fastest share gains are emerging in men.
Technology:
Ingredient sourcing and claim architecture determine regulatory pathway complexity and consumer trust positioning.
- Natural:Plant-derived surfactants and conditioning agents with limited processing claims. Supply volatility in Indonesian and Malaysian palm oil derivatives constrains formulation consistency.
- Chemical:Synthetic actives with established efficacy profiles and predictable stability. Professional colorant and perming systems retain performance loyalty despite clean beauty pressures.
- Organic:Certified supply chains with third-party verification of agricultural inputs. Premium pricing acceptance in Australia's urban centers supports import-dependent distribution models.
- Herbal:Traditional medicine system positioning with ayurveda, TCM, and jamu heritage claims. India's BIS revision mandates heavy metal documentation, eliminating uncertified competitors from modern trade.
Regulatory friction is highest for herbal. Biotechnology integration is accelerating fastest in natural.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian and Malaysian palm oil plantations supply the fatty alcohol feedstocks that anchor Asia Pacific surfactant production. This raw material geography shapes formulation economics across the region's diverse climate zones and hair care traditions.
China
Tier-one cities Shanghai and Guangzhou drive premium salon service uptake alongside direct-to-consumer serum subscriptions. NMPA pre-market registration rules enforce ingredient disclosure standards that determine which formulations enter domestic distribution. The Yangtze River Delta manufacturing corridor hosts concentrated R&D facilities serving both mass-market retail and professional backbar channels.
India
Traditional coconut and amla oiling practices sustain volume demand in rural households while metropolitan centers premiumize ayurveda-positioned brands. BIS cosmetic safety standards mandate third-party heavy metal certification, eliminating uncertified herbal competitors from modern trade. Maharashtra and Karnataka laboratory clusters capture shelf space as GMP compliance becomes mandatory.
Japan
Aging demographics sustain anti-hair-loss claim demand requiring MHLW quasi-drug classification. METI-coordinated standards extend commercialization timelines by 18-24 months but preserve premium positioning for substantiated scalp treatments. The Kanto region concentrates microbiome-compatible formulation expertise unavailable elsewhere in Asia Pacific.
South Korea
Younger consumers in Seoul and Busan expand scalp-specific treatment routines beyond basic cleansing. MFDS regulatory frameworks support rapid fermentation-derived active adoption with shortened clinical substantiation cycles. Hardware-software convergence for scalp diagnostic devices originates in the Seoul Capital Area before regional export.
Vietnam
Modern trade expansion into Ho Chi Minh City and Hanoi secondary districts creates distribution white space for sachet-format conditioners. ASEAN cosmetic directive alignment simplifies multi-country dossier management compared to divergent national regimes elsewhere. Domestic manufacturing scales to serve emerging middle-class daily maintenance routines.
Asia Pacific Hair Care Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents balance mass-market scale against premium positioning. The vendor base separates into three tiers: multinational conglomerates with distributed production networks, regional specialists with deep distribution into secondary cities, and fermentation-technology leaders with microbiome claim substantiation. Strategic archetypes include scale-driven surfactant manufacturers, ayurveda-heritage herbal positioners, and biotechnology-derived active suppliers. M&A activity and capacity expansion in Southeast Asian manufacturing clusters represent the dominant competitive moves.
Within the multinational tier, Unilever and L'Oréal S.A. exemplify divergent geographic strategies—Unilever through distributed production networks across Southeast Asia, L'Oréal S.A. through dedicated Shanghai R&D serving China's urban premium segment. Marico Limited occupies a position anchoring mass-market penetration via tier-two and tier-three Indian city distribution. These three entities represent the structural tension between global scale and regional adaptation that defines competitive positioning across shampoo, conditioner, and serum categories.
| Leading Market Players |
|---|
| Unilever |
| Marico Limited |
| L'Oréal S.A. |
| Mandom Corporation |
| Dabur India Ltd |
| Kao Corporation |
| Henkel AG & Co. KGaA |
| Hoyu Co. Ltd |
| Procter & Gamble |
| Others |
Value Chain & Pricing Dynamics
Captive production of fatty alcohol feedstocks across Indonesian and Malaysian plantation networks anchors both supply security and pricing power for Asia Pacific surfactant manufacturers. This upstream control insulates formulators from palm oil volatility while enabling premium positioning for sulfate-free variants in China's tier-one cities.
Pricing Analysis
Warranty and technical service bundling separates professional salon-grade SKUs from unbundled mass-market retail formats. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and active concentration, with BIS-compliant herbal oils commanding shelf premiums over uncertified competitors. Cost compression in sachet-format conditioners is intensifying because of feedstock volatility, while household consumers in India's rural districts exhibit acute per-wash price sensitivity and salon procurement managers show minimal elasticity for treatment-grade protocols.
Supply Chain Analysis
India's BIS domestic-content mandates for heavy metal testing infrastructure are restructuring supplier bases toward GMP-certified domestic manufacturers. Feedstock concentration centers on Indonesia, Malaysia, and India for palm oil derivatives, coconut fatty acids, and ayurveda botanicals respectively. Single-source vulnerability runs through European specialty ester suppliers in Germany and Switzerland. Distribution runs through modern trade expansion in Vietnam and Philippines secondary cities, professional salon backbar channels in China and South Korea, and direct-to-consumer subscription platforms in urban Chinese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific hair care operates as a supply-constrained market where fermentation-technology capacity bottlenecks prop pricing for microbiome-compatible actives. Scarce formulation expertise in Japan and South Korea limits rapid competitor replication.
For Market Incumbents: Acquire fermentation-technology assets and captive laboratory capacity in Mumbai or Bangalore to preempt BIS compliance advantages. Deepen backward integration into Indonesian fatty alcohol supply to offset European chemical dependency. Secure scalp diagnostic device partnerships before hardware-software convergence locks in salon channel loyalty. For New Entrants and Emerging Players: Direct-to-consumer platforms in China's tier-one cities offer the most penetrable white space for algorithmic personalization models. Vietnam's modern trade expansion into Ho Chi Minh City secondary districts presents sachet-format conditioner distribution gaps. Pursue ayurveda-positioning with third-party heavy metal certification to exploit India's BIS restructuring. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational conglomerates seeking fermentation-technology capabilities. Long-term viability favors targets with microbiome claim substantiation and GMP-certified manufacturing infrastructure. Monitor Japan's MHLW quasi-drug approval timelines as inflection indicator for anti-hair-loss category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Acquisition | Microbiome-compatible actives from South Korean suppliers shorten clinical substantiation cycles. |
| GMP Certification Investment | BIS heavy metal mandates in India eliminate uncertified competitors from modern trade. |
| Direct-to-Consumer Platform Launch | Algorithmic serum matching in Shanghai and Guangzhou locks 6-month replenishment cycles. |
| Professional Salon Channel Expansion | Treatment-grade backbar formats in China's urban centers capture premium margin pools. |
| Regional Manufacturing Scale-Up | Distributed production across Southeast Asia reduces palm oil logistics exposure. |
Study Parameters
Document review covered NMPA registration filings, BIS cosmetic safety standards, and ASEAN cosmetic directives, complemented by interviews with formulation chemists, salon procurement managers, and modern trade category buyers. Secondary validation drew from customs trade data, Nielsen retail audit records, and company SEC disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, application channel, and technology segments.
Segment-level outputs across shampoo, conditioner, serum, and hair oil categories combined with geographic clustering by regulatory framework. CAGRs derived from weighted average of historical trajectory and penetration-adjusted growth rates. Forecast inputs incorporated NMPA pre-market registration timelines, BIS compliance rollout schedules, and fermentation-technology adoption curves.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals, palm oil supply disruptions from climate events, and MHLW quasi-drug reclassification. Forecasts reflect documented assumptions about continued urban premiumization and modern trade expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Anti Pollution Hair Care Products Market
Hair Care
Argentina Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
South Africa Hair Care Market
Hair Care
Hair and Scalp Care Market
Hair Care
Russia Hair Care Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Hair Spray Market
Hair Care
Rice Water Shampoo Market
Hair Care
Italy Hair Care Market
Hair Care
Japan Hair Care Market
Hair Care
Global Hair Color Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Hair Serum Market
Hair Care
Global Shampoo Market