
 United Arab Emirates Hair Care Market | 2026-2036
United Arab Emirates Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Hair Care Market Analytics
Salon procurement consolidation across Dubai and Abu Dhabi is pivoting professional-grade purchasing toward volume-contract arrangements. Unilever PLC leverages its broad distribution infrastructure to supply both retail shelves and institutional salon channels. Loreal S.A dominates professional hair color and treatment lines through specialized salon partnerships. Procter & Gamble Company competes aggressively in mass-market shampoo and conditioner segments with frequent promotional cycles.
Hair care encompasses formulations designed to cleanse, condition, color, or treat human hair through surfactant-based, emollient, or pigment-delivery systems with pH ranges typically calibrated between 4.5 and 6.5 to maintain cuticle integrity. These products serve consumer grooming needs and professional styling services across residential and commercial settings. Shampoo and conditioner together anchor the largest revenue pool, though hair color generates superior per-unit margins particularly in salon channels. Organic and natural formulation segments are expanding fastest as MOHAP tightens cosmetic ingredient monitoring and consumers shift toward SLS-free and paraben-free alternatives.
MOHAP oversees cosmetic product registration and safety assessment requirements for all hair care items entering UAE distribution channels. The Emirates Authority for Standardization and Metrology mandates labeling compliance including halal certification indicators and full ingredient disclosure. Dubai Municipality conducts periodic market surveillance testing for heavy metals and microbial contamination in imported formulations. Stakeholders must monitor evolving halal certification protocols and adapt supply chains to maintain uninterrupted market access.
Market Dynamics
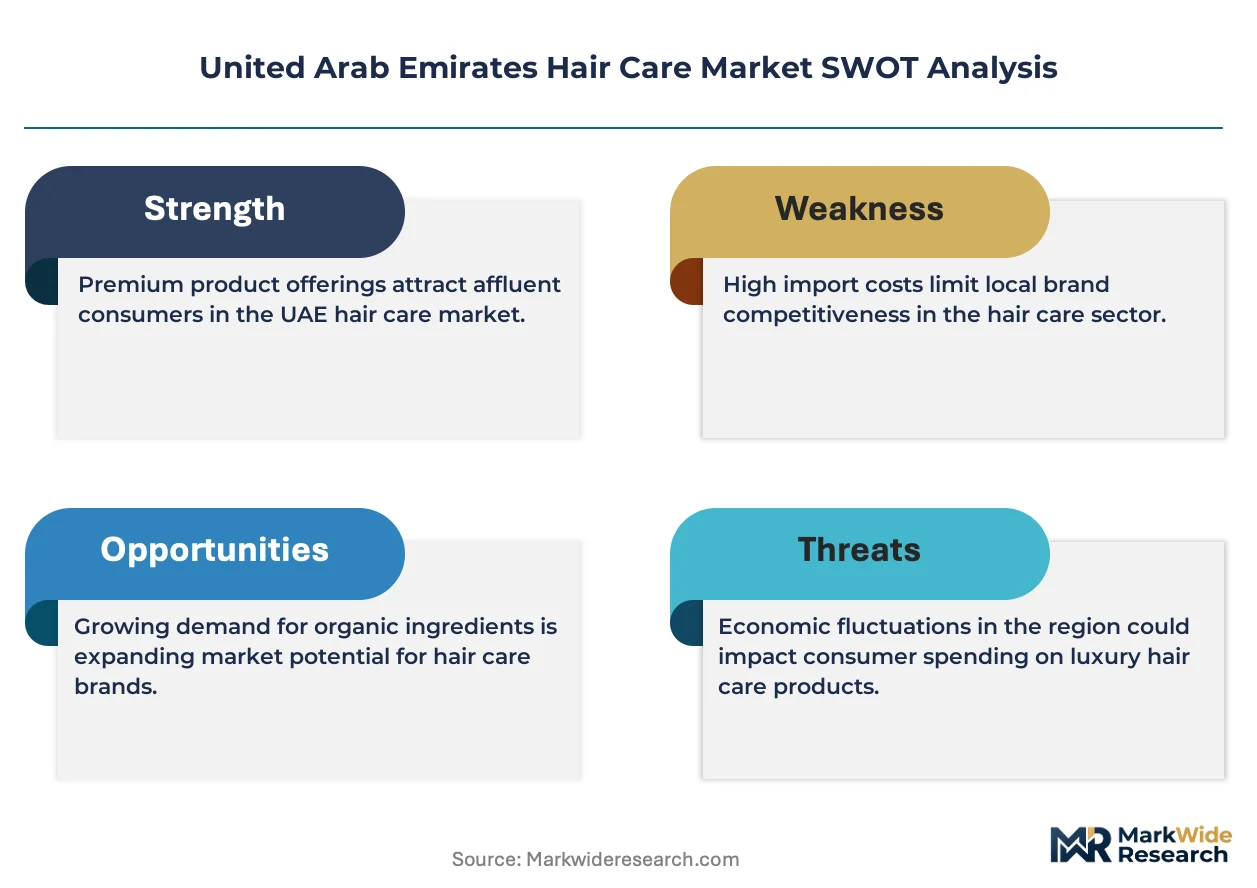
Salon procurement consolidation across Dubai and Abu Dhabi is compressing distributor margins while elevating volume-contract leverage among professional-grade suppliers.
Growth Catalysts
- MOHAP cosmetic safety notifications:Mandatory ingredient disclosure requirements are accelerating reformulation toward clean-label profiles and expanding the addressable market for SLS-free and paraben-free alternatives.
- Halal certification standardization:Emirates Authority for Standardization and Metrology labeling mandates are creating competitive moats for compliant manufacturers while filtering non-compliant imports.
- Salon channel premiumization:Professional service spending in Dubai and Abu Dhabi is absorbing rising consumer budgets, pulling high-margin color and treatment formulations through institutional procurement.
Market Restraints
- Import dependency concentration:Heavy reliance on European and Asian formulation suppliers exposes distributors to freight cost volatility and currency fluctuation risks.
- Technical formulation barriers:pH calibration between 4.5 and 6.5 for cuticle integrity requires specialized emollient chemistry that limits local manufacturing scale-up.
- Regulatory friction from dual certification:Parallel MOHAP registration and Dubai Municipality surveillance testing extends product launch timelines and elevates compliance overhead.
Strategic Opportunities
- Ras Al Khaimah and Sharjah salon network expansion:Underpenetrated emirates outside the Dubai-Abu Dhabi axis present whitespace for professional-grade distribution partnerships.
- Organic formulation convergence:Plant-derived surfactant technology combined with biotechnology-derived actives enables premium positioning against conventional petrochemical alternatives.
- E-commerce direct-to-consumer channels:Digital-native subscription models for personalized hair care regimens bypass traditional retail margin structures.
Industry Challenges
- Trichology specialist talent scarcity:Professional salon channels face recruitment bottlenecks for certified colorists capable of executing complex treatment protocols.
- Halal certification timeline compression:Accelerated MOHAP review cycles strain documentation preparation capacity while competitors race for shelf positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Hair Care Market |
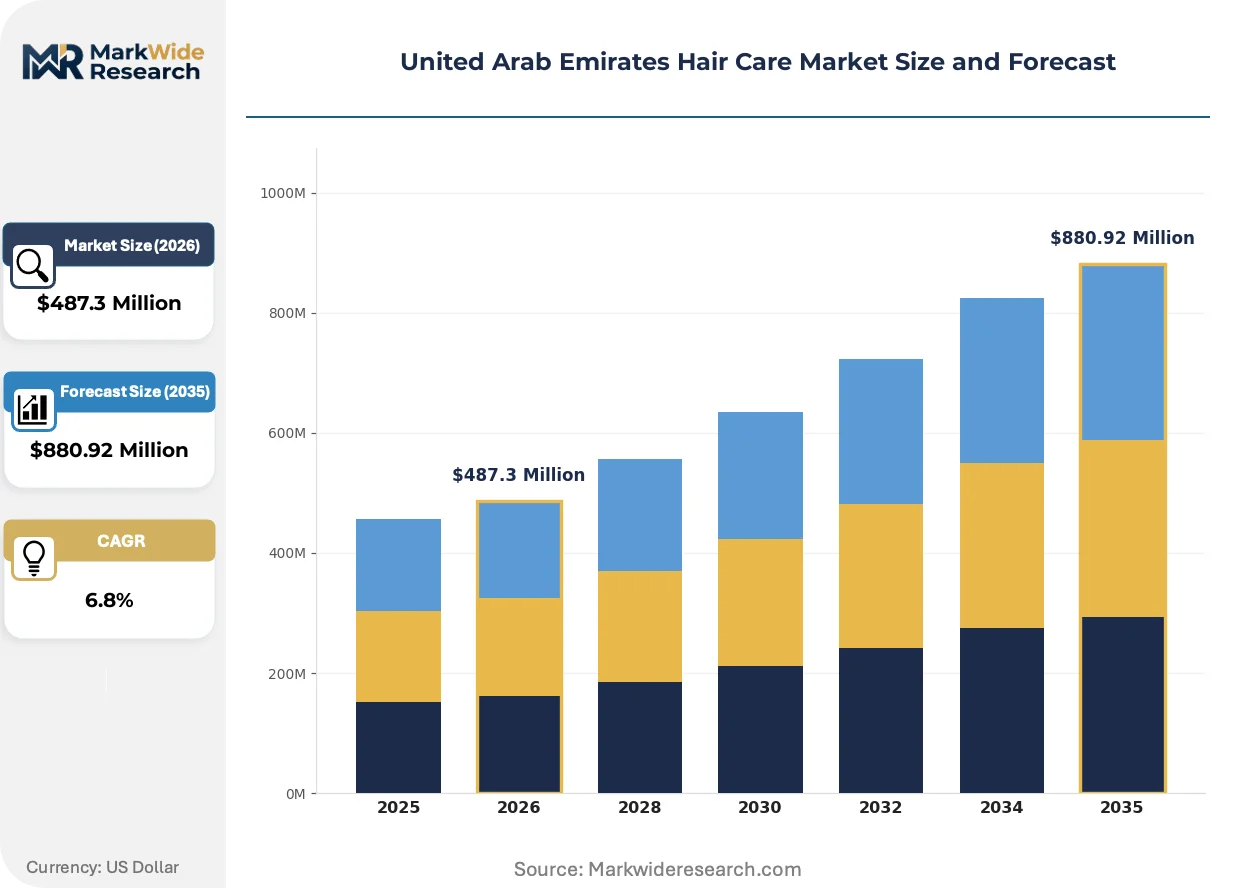
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Hair Color End User: Women, Men, Children, Salons Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Formulation: Organic, Natural, SLS-Free, Paraben-Free |
| Companies Covered | Henkel AG & Co. KGaA, Kao Corporation, Unilever PLC, Beiersdorf AG, Shiseido Company, Limited, Loreal S.A, The Estée Lauder Companies Inc., Kenvue Inc., Procter & Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Hair Care Market Evolving Landscape
Formulation science and distribution architecture are undergoing simultaneous transformation as regulatory stringency intersects with professional channel consolidation.
Biotechnology-derived active ingredients are penetrating professional treatment lines through fermentation-based keratin analogs and microbiome-targeted scalp therapies. High-end Dubai salons are adopting these actives at accelerated replacement cycles for premium service menus. This ingredient migration is converging with clean-label positioning to compress market share for conventional petrochemical formulations.
MOHAP's tightened cosmetic safety notification framework now mandates full ingredient disclosure and heavy metals testing documentation prior to market entry. The industrial consequence is elevated barrier-to-entry for new import brands and accelerated exit of non-compliant legacy formulations. Professional salon channels are most affected, as institutional buyers demand batch-level traceability certificates to satisfy Dubai Municipality audit protocols.
Subscription-based personalized regimens are displacing transactional retail purchases among affluent Emirati consumers and expatriate professionals. Traditional hypermarket and pharmacy shelf space is losing traffic to algorithm-driven consultation platforms that blend diagnostic tools with recurring delivery. This behavioral pivot is most visible in Dubai's premium residential zones where convenience-oriented consumption patterns dominate.
United Arab Emirates Hair Care Market Segmentation
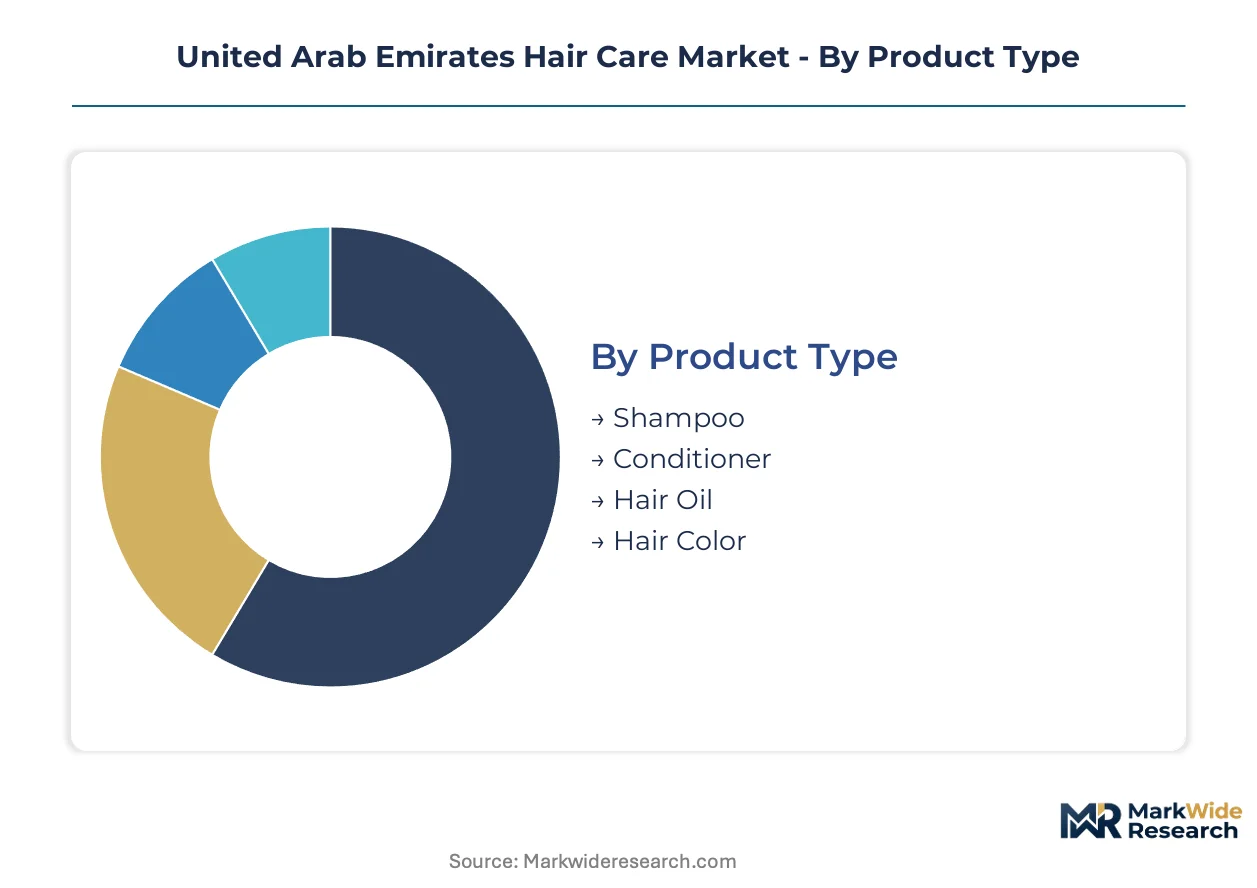
Hair care purchasing patterns in the UAE diverge sharply between mass retail consumption and institutional salon procurement, with regulatory compliance acting as a segmentation filter across all categories. Understanding these divides reveals where margin pools concentrate and which channels absorb compliance overhead.
Product Type:
Buyers differentiate primarily by usage frequency versus treatment intensity, separating daily maintenance from periodic color services.
- Shampoo:Surfactant-based cleansing formulations typically pH-balanced between 4.5 and 6.5 to preserve cuticle integrity. Volume concentrates in Dubai and Abu Dhabi hypermarkets where promotional cycles drive stock-up behavior among expatriate households.
- Conditioner:Emollient-rich formulations delivering cationic conditioning agents to neutralize static and improve combability. Salon channels in Dubai's premium districts pull professional-grade variants through volume-contract arrangements with institutional buyers.
- Hair Oil:Traditional nourishing formulations penetrating the cortex to reduce protein loss. Demand clusters among South Asian expatriate communities in Sharjah and Ajman.
- Hair Color:Oxidative and direct pigment-delivery systems with ammonia-free variants gaining professional preference. Per-unit margins exceed maintenance categories, with MOHAP batch-level traceability requirements elevating compliance costs for import brands.
Volume sits with Shampoo; growth tilts toward Hair Color.
End User:
Service modality separates the segments, distinguishing at-home application from professional execution.
- Women:Primary decision-makers across retail and professional channels, driving conditioner and treatment category velocity. Dubai-based working professionals increasingly subscribe to personalized regimen platforms.
- Men:Grooming routines expanding beyond basic cleansing into scalp health and gray coverage. Barbershop channels in Abu Dhabi absorb specialized men's color services.
- Children:Mild formulation demand with tear-free specifications dominating parental selection criteria. Pharmacies capture disproportionate share through pharmacist recommendation.
- Salons:Institutional procurement consolidating across Dubai and Abu Dhabi, compressing distributor margins while elevating volume-contract leverage. MOHAP documentation requirements filter smaller import brands from professional supply chains.
Women anchor current revenue; Salons deliver the steepest expansion trajectory.
Distribution Channel:
Margin structure and regulatory touchpoint density separate these pathways.
- Online Retail:Algorithm-driven personalization platforms bypass traditional retail markups, concentrated in Dubai's premium residential zones. Subscription models displace transactional purchasing among affluent Emirati consumers.
- Supermarkets:Hypermarket chains dominate mass-market shampoo and conditioner volume through promotional cycling. Shelf space allocation favors established brands with MOHAP registration histories.
- Specialty Stores:Curated assortment environments emphasizing clean-label and halal-certified positioning. Dubai Mall and Mall of the Emirates locations capture tourist and high-net-worth resident traffic.
- Pharmacies:Trichology-adjacent positioning with pharmacist consultation driving treatment and scalp therapy selection. MOHAP cosmetic safety notifications elevate documentation requirements for pharmacy stockists.
Supermarkets hold volume dominance; Online Retail gains share fastest.
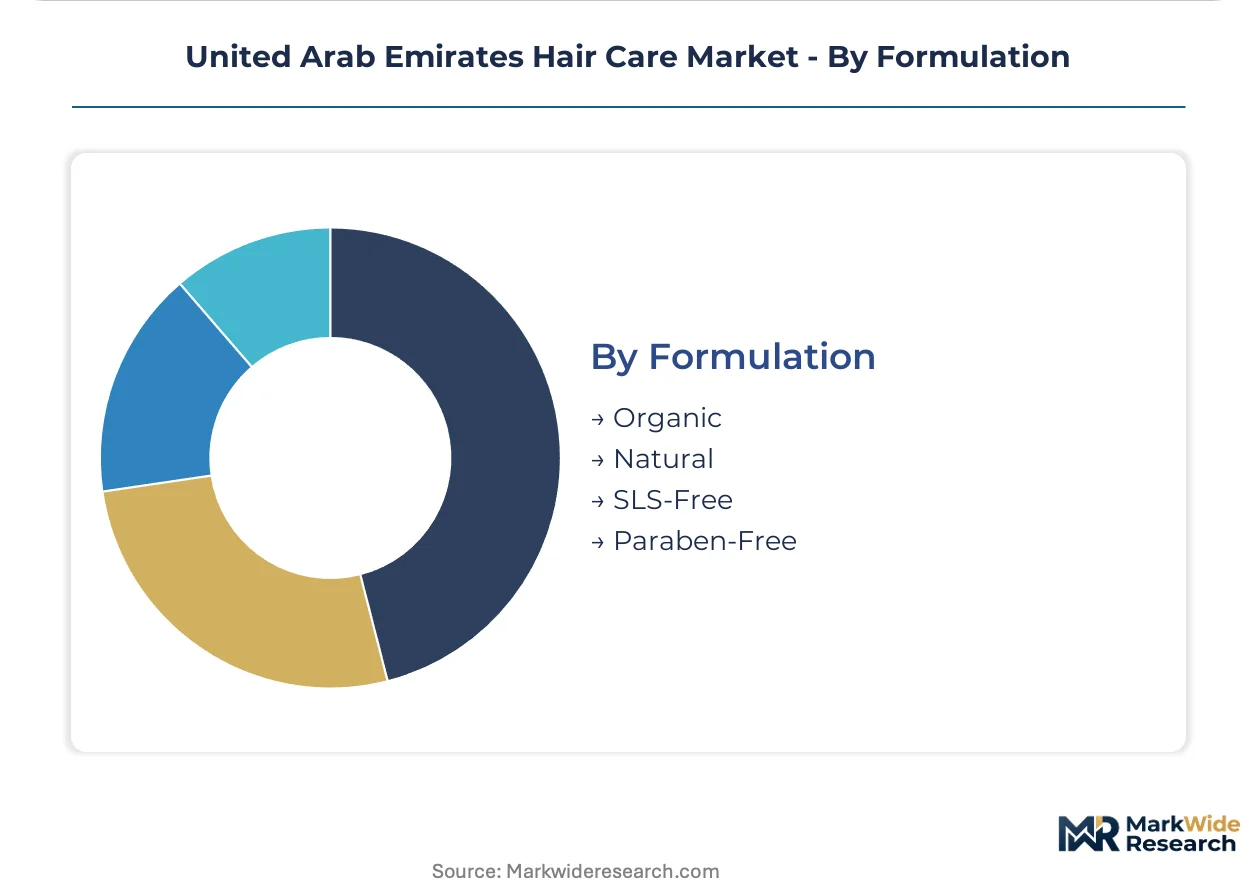
Formulation:
Regulatory compliance tier and ingredient sourcing transparency define buyer selection.
- Organic:Plant-derived surfactant systems with certified agricultural sourcing. Biotechnology-derived actives enable premium positioning against petrochemical alternatives in Dubai salon channels.
- Natural:Minimally processed botanical extracts without synthetic fragrance or dye. Emirates Authority for Standardization and Metrology labeling mandates create competitive moats for compliant manufacturers.
- SLS-Free:Alternative surfactant chemistry using glucoside or isethionate bases. MOHAP tightened cosmetic safety notifications accelerate reformulation toward these profiles.
- Paraben-Free:Preservation systems relying on phenoxyethanol, ethylhexylglycerin, or organic acids. Dubai Municipality surveillance testing for microbial contamination elevates formulation complexity for this segment.
Natural formulations command current premium positioning; SLS-Free alternatives are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer spending on professional hair services clusters overwhelmingly in Dubai and Abu Dhabi, with salon procurement consolidation reshaping distribution economics across the emirates. Sharjah and the Northern Emirates present underpenetrated expansion corridors where volume-contract leverage remains weaker. Regulatory enforcement from MOHAP and Dubai Municipality tightens compliance thresholds uniformly but lands hardest on import-dependent distributors in secondary markets.
Dubai
Salon-grade color and treatment services absorb the highest per-capita professional spending in the UAE, driven by affluent Emirati households and expatriate professionals. Dubai Municipality conducts intensive market surveillance testing for heavy metals and microbial contamination, elevating documentation burdens for stockists. The Dubai Mall and Mall of the Emirates anchor premium retail distribution, while Jumeirah and Downtown salon clusters pull biotechnology-derived actives through institutional procurement channels.
Abu Dhabi
Barbershop channels specializing in men's grooming and gray coverage services are expanding rapidly, complementing established women's salon networks. MOHAP cosmetic safety notifications mandate full ingredient disclosure prior to market entry, filtering smaller import brands from professional supply chains. The Corniche and Saadiyat Island districts concentrate high-margin treatment demand, with institutional buyers demanding batch-level traceability certificates.
Sharjah
South Asian expatriate communities sustain robust demand for traditional hair oil formulations, creating a distinct product mix from the premium-oriented Dubai-Abu Dhabi axis. The Emirates Authority for Standardization and Metrology mandates halal certification indicators on all labeling, compressing launch timelines for new entrants. Industrial zones near the Dubai border host distributors serving price-sensitive segments with SLS-free and paraben-free alternatives.
Northern Emirates
Ras Al Khaimah and Ajman salon networks remain fragmented, offering whitespace for professional-grade distribution partnerships without volume-contract leverage. Dual certification requirements from MOHAP registration and Dubai Municipality surveillance testing extend product launch timelines disproportionately for smaller operators. Tourist corridor development in Ras Al Khaimah is gradually pulling premium service spending northward from Dubai.
United Arab Emirates Hair Care Market Competitive Landscape
European producers anchor the premium salon-grade tier; Asian specialists hold mass-market formulation supply. Market structure tilts toward consolidated multinational control in professional channels while retail shelves accommodate broader brand diversity. Three archetypes dominate: diversified personal care conglomerates with institutional distribution infrastructure, specialized professional color houses with salon-exclusive partnerships, and digital-native direct-to-consumer entrants. Competitive moves center on strategic partnerships with salon procurement consortia and portfolio diversification into biotechnology-derived actives.
Within the diversified conglomerate tier, Unilever PLC and Procter & Gamble Company exemplify mass-market scale players leveraging broad distribution infrastructure across retail and institutional channels. Loreal S.A occupies a position representing the professional-specialist archetype, with salon-exclusive color and treatment lines concentrated in Dubai and Abu Dhabi premium districts. These three companies collectively illustrate how regulatory compliance capacity and volume-contract negotiation strength are separating viable market participants from filtered non-compliant imports.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Unilever PLC |
| Beiersdorf AG |
| Shiseido Company, Limited |
| Loreal S.A |
| The Estée Lauder Companies Inc. |
| Kenvue Inc. |
| Procter & Gamble Company |
| Others |
Value Network & Pricing Analysis
Certified colorist talent clustering in Dubai and Abu Dhabi creates labor-cost differentials that widen pricing spreads between premium salon services and mass-market retail tiers. This workforce concentration allows institutional buyers to extract volume-contract leverage while secondary emirates absorb higher per-unit logistics overhead.
Pricing Analysis
Volume concentrates in mass-market shampoo and conditioner through hypermarket promotional cycles, while margins concentrate in professional hair color and treatment services delivered through Dubai and Abu Dhabi salon channels. Price differentiation rests on halal certification grade and volume scale, with MOHAP-registered formulations commanding shelf-access premiums. Pricing pressure intensifies in distributor tiers as salon procurement consolidation compresses intermediary margins. Expatriate households in Sharjah and Ajman exhibit highest price sensitivity, whereas affluent Emirati consumers in Jumeirah and Downtown Dubai demonstrate lowest sensitivity to per-service premiums.
Supply Chain Analysis
Freight cost volatility from European and Asian formulation hubs elevates landed costs for UAE distributors serving secondary emirates. Manufacturing concentrates in France, Germany, and South Korea for professional-grade color lines, while mass-market surfactant formulations draw from China and India. Raw material dependencies include palm-derived surfactants, fermentation-based keratin analogs, and ammonia-free oxidative precursors. Single-source vulnerability runs through specialized emollient chemistry suppliers capable of pH calibration between 4.5 and 6.5. Distribution runs through consolidated salon procurement consortia in Dubai and Abu Dhabi alongside fragmented retail networks in Northern Emirates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE hair care sector sits in a biotechnology-transition phase, with fermentation-derived actives displacing conventional petrochemical formulations across professional treatment lines.
For Market Incumbents: Lock in salon-exclusive partnerships through batch-level traceability certificates that satisfy Dubai Municipality audit protocols. Deepen backward integration into biotechnology-derived active ingredient supply to defend margin position against clean-label entrants. Prioritize MOHAP registration capacity expansion to filter non-compliant import competitors from professional supply chains. For New Entrants and Emerging Players: Independent salon networks in Ras Al Khaimah and Ajman represent the most penetrable channel partner type for volume-contract arrangements without incumbent consolidation leverage. Target underpenetrated barbershop channels in Abu Dhabi's Corniche district for men's grooming and gray coverage services. Pursue direct-to-consumer subscription models bypassing traditional retail margin structures in Dubai's premium residential zones. For Investors and Strategic Acquirers: Re-rating potential sits with specialized professional color houses given MOHAP's tightened cosmetic safety notification framework accelerating compliant manufacturer concentration. Long-term viability favors archetypes with established halal certification protocols and salon-exclusive distribution infrastructure. Monitor biotechnology-derived active ingredient adoption rates in high-end Dubai salons as inflection indicator for formulation premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | MOHAP registration timelines compress competitive moats for compliant manufacturers against non-compliant imports. |
| Salon Procurement Consolidation | Volume-contract arrangements with Dubai and Abu Dhabi institutional buyers displace fragmented distributor networks. |
| Biotechnology Actives Integration | Fermentation-based keratin analogs enable premium positioning against petrochemical alternatives in treatment lines. |
| E-commerce Subscription Launch | Algorithm-driven personalization platforms capture affluent Emirati consumers abandoning transactional retail purchasing. |
| Northern Emirates Distribution Expansion | Ras Al Khaimah and Ajman salon networks offer whitespace partnerships without incumbent volume leverage. |
Research Methodology
Independent corroboration across salon procurement managers, cosmetic regulatory affairs specialists, and distribution channel partners underwrites the qualitative findings. Primary interviews with institutional buyers at Dubai and Abu Dhabi salon consortia, MOHAP registration consultants, and trichology clinic operators combined with secondary validation from Emirates Authority for Standardization and Metrology labeling directives, Dubai Municipality surveillance testing protocols, and customs import records. Bottom-up demand modeling triangulates against top-down market sizing across product type, end user, distribution channel, and formulation segmentation dimensions.
Rate-of-change decomposition separates volume growth from value expansion across shampoo, conditioner, hair oil, and hair color categories throughout the projection horizon. Segmentation dimensions modeled include product type, end user archetype, distribution channel, and formulation compliance tier alongside regional emirate penetration patterns. CAGRs derive from historical trajectory analysis adjusted for regulatory catalysts and channel consolidation dynamics. Forecast inputs incorporate salon service spending absorption rates and biotechnology-derived active ingredient replacement cycles.
Several conditions sit outside the modeled scope, including abrupt shifts in MOHAP review timelines, currency devaluation events affecting import-dependent supply chains, and unforeseen Dubai Municipality enforcement intensity variations. Forecasts reflect documented assumptions around halal certification standardization velocity and professional channel consolidation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Extension Market
Hair Care
Israel Hair Care Market
Hair Care
Professional Hair Care Products Market
Hair Care
China Hair Care Products Market
Hair Care
Hair Care Products Market
Hair Care
Global Hair Color Market
Hair Care
Hair Care Market
Hair Care
Hair Clay Market
Hair Care
India Hair Care Market
Hair Care
North America Hair Care Market
Hair Care
Men's Hairspray Market
Hair Care
Hair Serum Market
Hair Care
South Africa Hair Care Market
Hair Care
Qatar Hair Care Market
Hair Care
Global Professional Hair Care Market
Hair Care
Hair Texturizer Products Market