
 France Haircare Market | 2026-2036
France Haircare Market Size, Share, and Industry Trends Forecast 2026-2036
France Haircare Market Insights
The EU Green Deal is shifting ingredient sourcing priorities across French haircare, compelling brands to reformulate around biobased and biodegradable alternatives. L'Oréal S.A. leverages its Clichy-based research infrastructure to accelerate green chemistry pipelines, while Pierre Fabre Group anchors its position through botanical extraction expertise tied to southern France cultivation networks. Unilever PLC competes via concentrated formats that reduce water and packaging intensity in mainstream retail channels.
France haircare encompasses formulations designed to cleanse, condition, treat, or style human hair, typically incorporating surfactant systems, emollients, active botanicals, or color-protecting polymers at pH ranges between 4.5 and 6.5 to maintain cuticle integrity. Shampoo and conditioner together constitute the volume core, though hair mask and treatment segments command disproportionate margin pools as consumers trade up from basic cleansing to repair-oriented rituals. The salon end-user channel sustains premium pricing power, while online retail captures the fastest expansion in customer acquisition and subscription-based replenishment models.
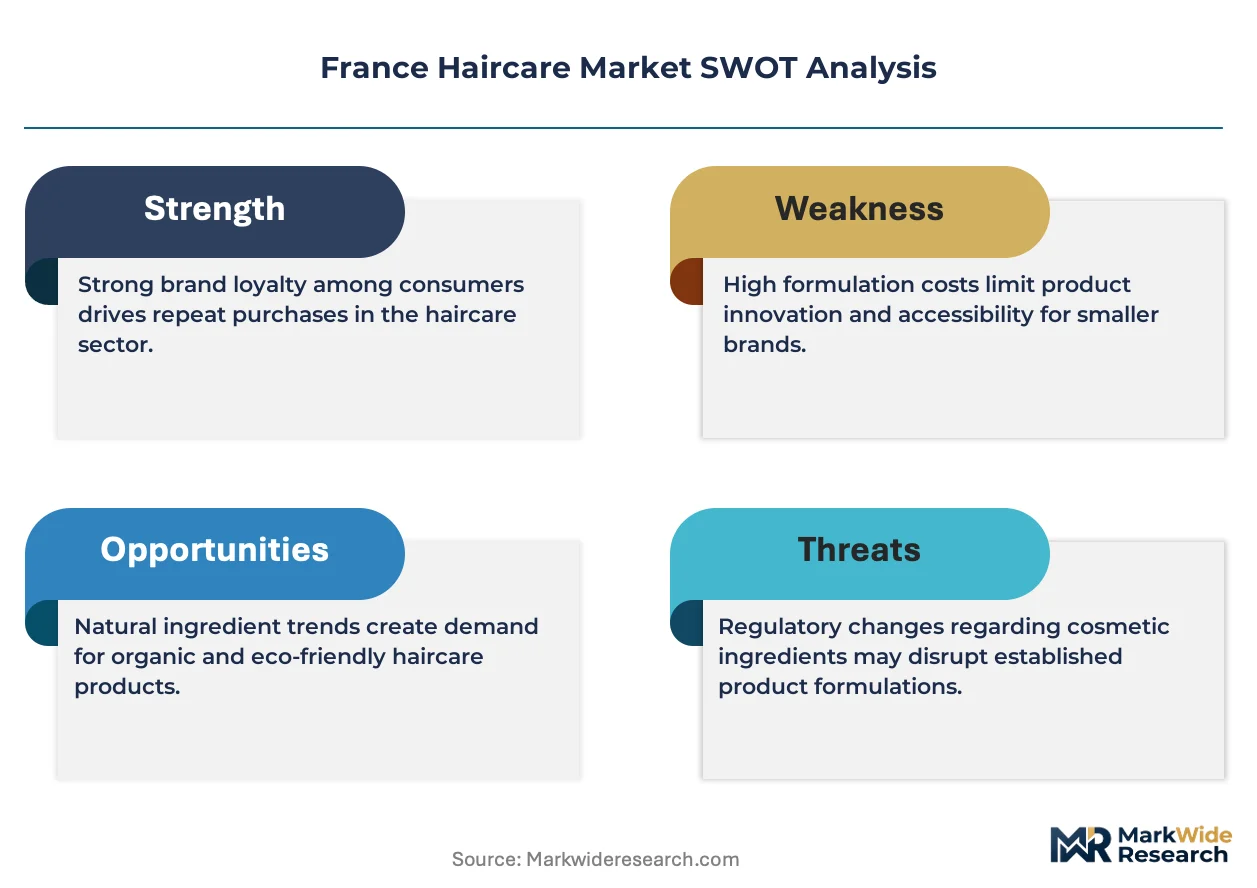
ANSM oversees cosmetic safety assessments and ingredient restrictions under EU Cosmetics Regulation frameworks, while ECHA enforces REACH compliance for chemical substances used in manufacturing. These bodies collectively elevate compliance costs for imported formulations and create preferential conditions for domestic producers with established regulatory navigation capabilities. Stakeholders must monitor evolving microplastic restrictions and biodegradability testing protocols that will determine which product architectures retain market access in the decade ahead.
Market Dynamics
EU Green Deal chemical sustainability mandates are forcing wholesale reformulation across French haircare, eliminating petrochemical surfactants and microplastic additives while elevating compliance costs for imported formulations.
Growth Catalysts
- ANSM cosmetic safety frameworks:Domestic producers leverage established regulatory navigation capabilities to accelerate product approval timelines versus importers facing documentation barriers.
- Botanical extraction infrastructure:Southern France cultivation networks supply regionally certified active ingredients that command premium positioning in treatment-focused product lines.
- Paris metropolitan demand concentration:Urban consumers in the capital cluster drive disproportionate adoption of repair-oriented hair masks and salon-channel premium formats.
Market Restraints
- Biobased surfactant input costs:Coconut-derived and sugar-based cleansing agents trade at significant premiums versus petrochemical alternatives, compressing margin on mass-market shampoo formulations.
- ECHA REACH compliance timelines:Extended substance evaluation periods delay new ingredient market entry and elevate R&D carrying costs for reformulation cycles.
- Waterless format substitution threat:Concentrated solid bars and powder formats from adjacent personal care categories capture environmentally motivated consumers seeking plastic-free alternatives.
Strategic Opportunities
- Lyon-Grenoble corridor expansion:Secondary urban clusters outside Paris exhibit underpenetrated professional salon density relative to per-capita disposable income levels.
- EU Green Deal biobased procurement mandates:Public-sector and corporate bulk purchasing preferences create preferential contracting channels for certified-sustainable domestic producers.
- Subscription replenishment channel innovation:Direct-to-consumer auto-replenishment models bypass traditional retail slotting fees while capturing recurring revenue streams in conditioner and treatment segments.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with combined expertise in botanical extraction and surfactant stability command premium compensation, constraining mid-tier brand R&D scaling.
- Microplastic-free certification complexity:Third-party biodegradability testing protocols lack harmonization across EU member states, creating documentation duplication for multi-market distribution.
- Legacy manufacturing asset retrofitting:Existing compounding equipment requires capital-intensive modification to handle high-viscosity botanical bases and cold-process emulsion systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Haircare Market |
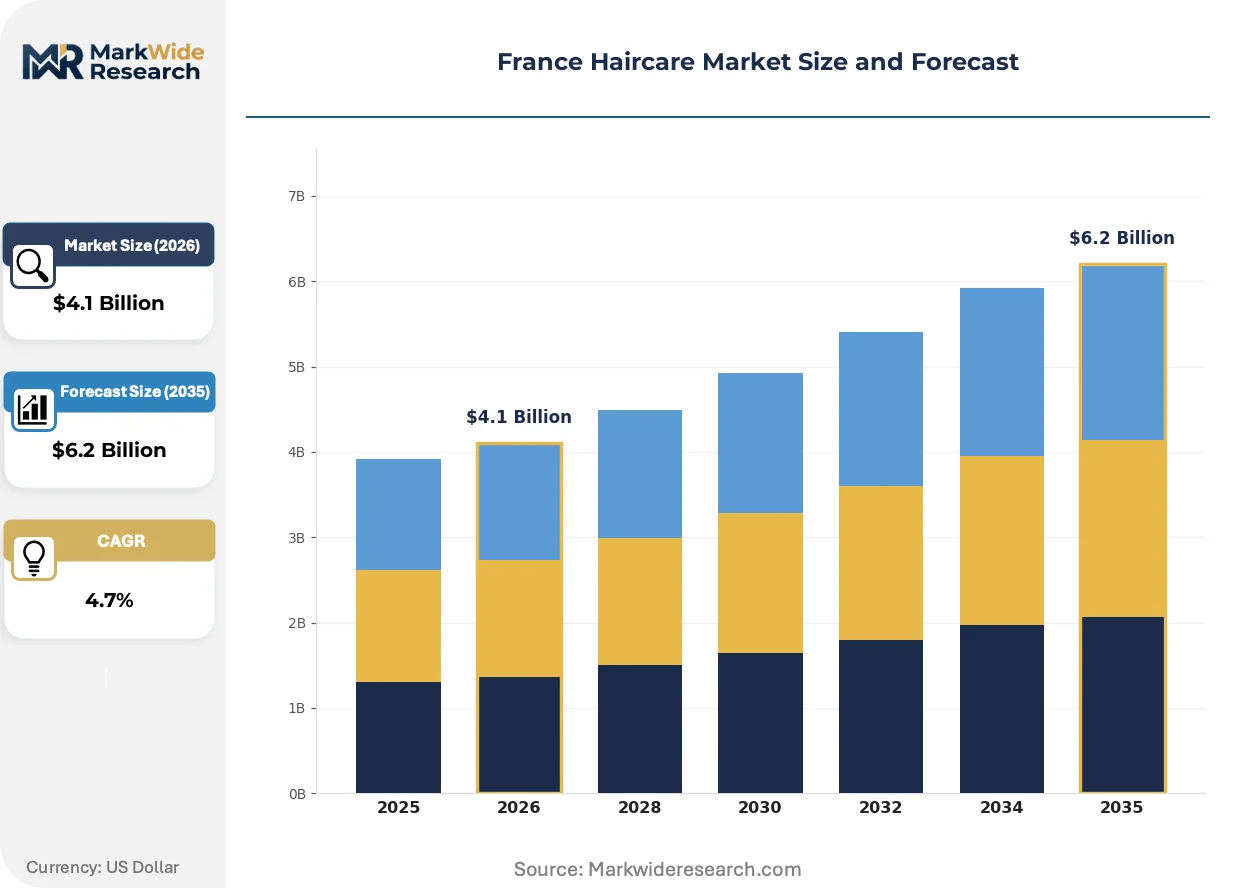
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.2 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Hair Mask Application: Daily Use, Treatment, Styling, Color Protection End User: Women, Men, Teens, Salons Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Drugstores |
| Companies Covered | L'Oréal S.A., Unilever PLC, Procter and Gamble Company, Pierre Fabre Group, Beiersdorf AG, Henkel AG & Co. KGaA, The Estée Lauder Companies Inc., Coty Inc., Shiseido Company, Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Haircare Market Trends and Innovations
Biotechnology-derived actives and circular packaging systems are displacing conventional petrochemical formulations across French haircare, while regulatory pressure accelerates transparency requirements throughout supply chains.
Fermentation-produced ceramides and hyaluronic acid variants are expanding into professional treatment lines and premium consumer masks, offering biomimetic repair mechanisms without animal-derived sourcing. Salon channels in Paris and Bordeaux adopt these actives at accelerated pace versus mass retail. Biotechnology platforms are expanding into previously inaccessible performance claims around scalp barrier restoration and fiber cortex penetration.
EU Green Deal chemical sustainability requirements are eliminating microplastic glitter, acrylate copolymers, and non-biodegradable conditioning agents from rinse-off formulations. ECHA enforcement of REACH substance restrictions compels brands to rebuild supply chains around certified-biodegradable alternatives. Treatment and styling segments face the steepest reformulation burden, with smaller import-dependent brands disproportionately exposed to compliance failure risk.
Consumers are unbundling basic cleansing from specialized treatment rituals, maintaining commodity shampoo usage while trading up to premium masks and scalp serums. Pharmacy and apothecary channels capture this bifurcation, displacing supermarket dominance in conditioner and treatment categories. This pattern concentrates in the Île-de-France and Provence-Alpes-Côte d'Azur regions, where per-capita spending on dermatologist-recommended haircare exceeds national averages.
France Haircare Market Segmentation
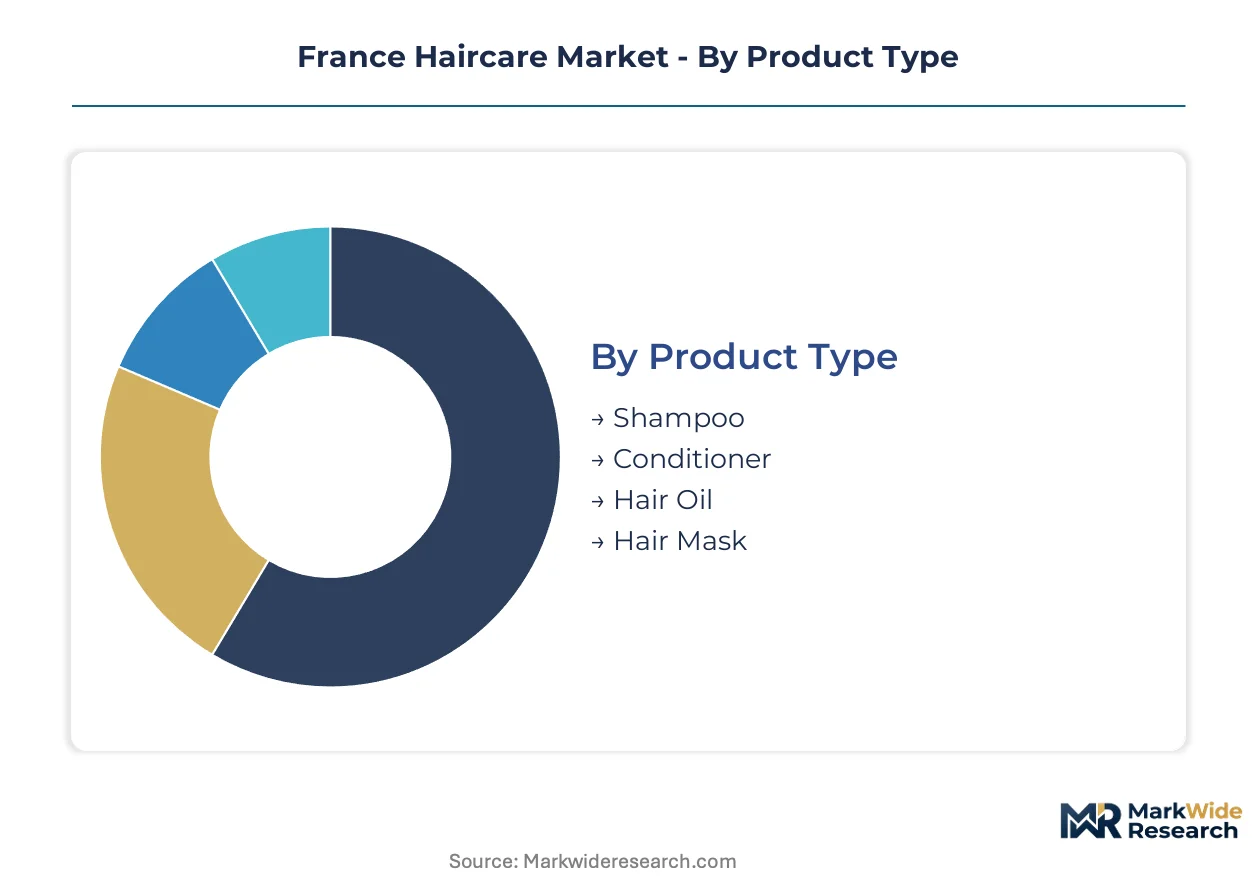
Segmentation in French haircare reveals divergent margin structures across product architectures and channel economics. Treatment-oriented formats command premium positioning versus basic cleansing, while salon and pharmacy channels sustain price premiums that supermarket distribution cannot replicate.
Product Type:
Standalone cleansing products dominate volume throughput, while embedded treatment systems drive margin expansion through ritual bundling.
- Shampoo:Surfactant-based formulations at pH 4.5-6.5 maintain cuticle integrity through anionic and amphoteric cleansing systems. Mass-market adoption concentrates in supermarket channels across Île-de-France and Provence-Alpes-Côte d'Azur, though biobased surfactant input costs compress margins on standard formats.
- Conditioner:Cationic conditioning agents and silicone emollients deliver detangling and surface smoothness. Pharmacy and apothecary channels in Paris capture disproportionate trade-up demand as consumers unbundle basic cleansing from specialized care rituals.
- Hair Oil:Lipid-rich formulations incorporating argan, jojoba, or camellia seed extracts for pre-shampoo treatments and finishing gloss.
- Hair Mask:High-viscosity treatment systems with concentrated ceramides, proteins, and botanical actives for weekly intensive repair protocols.
Shampoo leads volumes today; hair mask is gaining share fastest.
Application:
Usage context determines formulation complexity and pricing architecture across the French market.
- Daily Use:Mild surfactant systems designed for frequent application without cumulative irritation. Volume concentrates in family-sized formats through supermarket and online subscription channels, with EU Green Deal mandates accelerating biodegradable surfactant adoption.
- Treatment:Targeted repair and scalp health formulations with elevated active concentrations. Salon channels in Paris and Bordeaux drive professional adoption of biotechnology-derived ceramides and hyaluronic acid variants.
- Styling:Fixative polymers, thermal protectants, and texturizing agents for active shaping and hold.
- Color Protection:UV filters, antioxidant complexes, and pH-stabilizing systems to extend artificial pigment longevity.
Daily use commands absolute volume; treatment applications show steepest expansion trajectory.
End User:
Demographic targeting shapes product positioning and channel strategy across French retail.
- Women:Primary demand segment spanning full product spectrum from basic cleansing to premium treatment rituals. Per-capita spending in Paris metropolitan area exceeds national averages, with concentrated adoption of dermatologist-recommended pharmacy formats.
- Men:Simplified routines with growing adoption of specialized scalp care and grey coverage solutions. Online retail captures fastest customer acquisition through subscription replenishment models.
- Teens:Price-sensitive segment with elevated sensitivity to social media trend cycles and sustainability credentials.
- Salons:Professional-only formats with service-embedded application and premium pricing power sustained by technical expertise.
Women anchor volume concentration; salon end user expands most quickly.
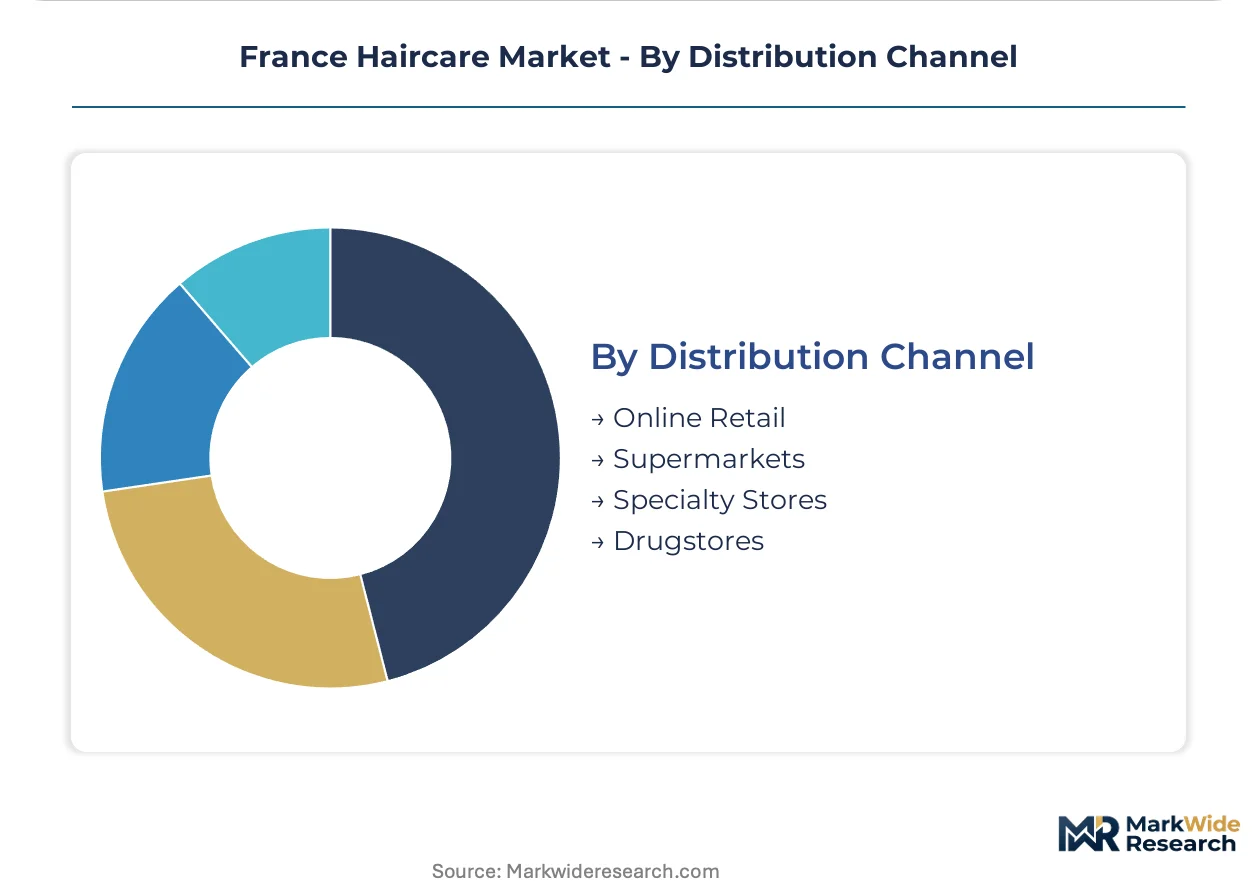
Distribution Channel:
Channel selection determines margin capture and customer relationship depth.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators bypass traditional slotting fees. Subscription auto-replenishment models in conditioner and treatment segments capture recurring revenue streams with superior customer lifetime value metrics.
- Supermarkets:Mass-volume shampoo and basic conditioner distribution with compressed margins and high promotional intensity. EU Green Deal compliance costs disproportionately burden imported formulations in this price-sensitive channel.
- Specialty Stores:Curated assortments with educated staff and experiential testing environments.
- Drugstores:Pharmacy-affiliated channels capturing treatment and scalp health trade-up demand through dermatologist recommendation networks.
Supermarkets retain volume leadership; online retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemists and formulation specialists concentrate in the Île-de-France research corridor, anchoring France's haircare innovation infrastructure. This talent density shapes regional demand patterns and manufacturing investment flows across metropolitan and secondary clusters.
Île-de-France
Paris metropolitan consumers drive disproportionate adoption of premium treatment masks and scalp serums through pharmacy and salon channels. ANSM regulatory frameworks accelerate product approval timelines for domestic producers with established safety documentation. Clichy-based research facilities anchor green chemistry pipelines serving both professional and consumer segments.
Auvergne-Rhône-Alpes
Lyon-Grenoble corridor exhibits underpenetrated professional salon density relative to per-capita disposable income levels. EU Green Deal biobased procurement mandates create preferential contracting channels for certified-sustainable producers targeting corporate bulk purchasing. Grenoble's biotechnology cluster feeds fermentation-derived active ingredient supply chains.
Provence-Alpes-Côte d'Azur
Per-capita spending on dermatologist-recommended haircare exceeds national averages in this coastal region. ECHA REACH compliance timelines delay new ingredient market entry for import-dependent brands attempting pharmacy channel placement. Grasse-centered botanical extraction networks supply regionally certified actives to treatment-focused product lines.
Nouvelle-Aquitaine
Bordeaux salon channels adopt biotechnology-derived ceramides at accelerated pace versus mass retail formats. Microplastic-free certification complexity creates documentation duplication for multi-market distribution from this Atlantic-facing logistics hub. Regional cultivation cooperatives expand jojoba and camellia seed supply for hair oil formulations.
Hauts-de-France
Secondary urban clusters around Lille demonstrate growing subscription replenishment adoption in conditioner segments. Legacy manufacturing asset retrofitting requirements constrain mid-tier brand R&D scaling in this former industrial zone. E-commerce fulfillment infrastructure expansion supports direct-to-consumer auto-replenishment model growth.
France Haircare Market Competitive Landscape
Capital-heavy producers with captive manufacturing assets compete with asset-light brand designers relying on contract manufacturing networks. The market structure consolidates around three dominant archetypes: integrated beauty conglomerates with research infrastructure, specialist dermatological houses with botanical extraction capabilities, and multinational FMCG operators with mass retail distribution scale. Competitive moves concentrate on green chemistry pipeline development and subscription channel infrastructure buildout.
Within the integrated conglomerate tier, L'Oréal S.A. and Unilever PLC exemplify divergent strategic positioning—one anchored in domestic research infrastructure, the other in concentrated format innovation for mainstream channels. Pierre Fabre Group occupies a specialist position tied to southern France cultivation networks. These three entities represent distinct archetypes: research-integrated domestic incumbent, multinational mass-market operator, and botanical-extraction-focused regional specialist.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever PLC |
| Procter and Gamble Company |
| Pierre Fabre Group |
| Beiersdorf AG |
| Henkel AG & Co. KGaA |
| The Estée Lauder Companies Inc. |
| Coty Inc. |
| Shiseido Company, Limited |
| Others |
Pricing and Supply Chain Analysis
Biobased surfactant input costs originating in Southeast Asian coconut and palm kernel supply chains cascade through French haircare pricing tiers, elevating mass-market shampoo manufacturing expenses while salon-channel treatment formats absorb premiums through service bundling. This cost structure bifurcation rewards domestic producers with backward integration into southern France botanical cultivation networks.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across French haircare channels. Salon-embedded professional treatments command three-tier pricing structure across premium, standard, and economy levels through technical expertise and service duration, while standalone retail formats compete on volume scale and promotional intensity. Price differentiation stems from certification grade under EU Green Deal biobased mandates and geographic delivery cost to Paris versus secondary clusters. Pricing pressure stems from waterless format substitution in environmentally motivated consumer segments. Mass-market supermarket buyers exhibit highest price sensitivity; salon end users show lowest.
Supply Chain Analysis
Regional distribution centers in Île-de-France and Nouvelle-Aquitaine operate hub-and-spoke patterns radiating toward pharmacy and specialty retail networks. Geographic supply concentration centers on France for botanical extraction, Spain and Italy for olive-derived emollients, and Southeast Asia for coconut surfactant feedstocks. Raw material dependencies include ceramide actives from fermentation facilities, argan oil from Moroccan cooperatives, and sugar-based cleansers from European beet processing. Single-source vulnerability in biotechnology-derived active ingredient platforms poses structural risk. Distribution runs through multi-tier wholesale networks serving differentiated channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Haircare Market functions as a stable compounder anchored by regulatory-driven reformulation cycles that perpetually refresh demand for compliant ingredient alternatives and certified-sustainable formats.
For Market Incumbents: To counter waterless format substitution from adjacent personal care categories, prioritize captive supply of Grasse-centered botanical extraction capacity and accelerate green chemistry pipeline development at Clichy-based research facilities. Channel control through pharmacy recommendation networks defends margin position against mass-market promotional intensity.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for conditioner and treatment segment entry, bypassing supermarket slotting fee barriers. Target the Lyon-Grenoble corridor's underpenetrated professional salon density relative to disposable income levels. Position through dermatologist-affiliated pharmacy channels leveraging ANSM regulatory credibility.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier brands lack captive manufacturing assets and green chemistry formulation expertise. The market supports long-term viability for vertically integrated specialists with botanical cultivation ties and subscription infrastructure. Monitor ECHA REACH substance evaluation timelines as inflection indicator for import-dependent brand distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Cultivation Backward Integration | Captive supply from southern France networks secures EU Green Deal biobased certification and margin protection. |
| Subscription Replenishment Platform Launch | Direct-to-consumer auto-replenishment captures recurring revenue in high-margin treatment segments. |
| Green Chemistry R&D Facility Expansion | Clichy-based infrastructure accelerates fermentation-derived active development for professional channels. |
| Pharmacy Channel Distribution Partnership | Dermatologist recommendation networks displace supermarket dominance in scalp health categories. |
| Waterless Format Product Line Introduction | Solid bar and powder alternatives capture environmentally motivated consumers seeking plastic-free options. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation chemists, pharmacy category buyers, salon distribution managers, and ANSM regulatory affairs specialists with secondary validation against EU Cosmetics Regulation filings, ECHA REACH substance databases, French customs trade records, and retail audit data from Nielsen and Circana. Bottom-up segment sizing and top-down macroeconomic triangulation cross-validated volume and value estimates.
Segment-weighting approaches distributed growth assumptions across product type, application context, end-user demographic, and distribution channel dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact modeling incorporated biotechnology adoption curves, EU Green Deal compliance timelines, and subscription channel penetration rates as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for fermentation-derived ceramide and hyaluronic acid production would alter the outlook for professional treatment segment growth. Forecasts reflect documented assumptions around regulatory enforcement intensity and consumer willingness-to-pay for certified-sustainable formats. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Serum Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Sweden Hair Care Market
Hair Care
Qatar Hair Care Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
China Hair Care Products Market
Hair Care
Latin America Hair Care Market
Hair Care
Artificial Hair Integration Market
Hair Care
South Korea Hair Care Market
Hair Care
Hair Dye Market
Hair Care
Brazil Hair Care Market
Hair Care
Japan Hair Care Market
Hair Care
India Hair Care Market
Hair Care
Hair Relaxer Market
Hair Care
Chile Hair Care Market
Hair Care
North America Hair Care Market