
 Anti-Pollution Hair Care Market | 2026-2036
Anti-Pollution Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Pollution Hair Care Market Outlook
Professional salon channels is expanding as stylists recommend protective pre-treatments to clients exposed to urban particulate matter. L'Oreal S.A. leverages its dermatological research infrastructure to develop barrier-forming polymers that shield hair cuticles from heavy metal deposits. Unilever sustains mass-market penetration with affordable anti-pollution shampoo lines distributed through supermarket networks across South Asia. Kao Corporation anchors its positioning in Japan through advanced ceramide-based formulations that address ozone-induced hair brittleness.
Anti-pollution hair care encompasses topical preparations engineered with chelating agents, antioxidant complexes, and cationic polymers that neutralize free radicals and remove particulate buildup from the hair shaft and scalp surface. These products typically incorporate ascorbic acid derivatives or ferulic acid at functional concentrations to interrupt oxidative cascade reactions triggered by polycyclic aromatic hydrocarbons. Shampoo and serum categories dominate current revenue flows, with serum formats capturing premium price positions due to concentrated active delivery systems. The organic formulation segment is gaining velocity as consumers reject synthetic chelators in favor of plant-derived alternatives, though paraben-free claims now function as baseline hygiene rather than differentiation.
REACH in Europe and FDA cosmetic safety guidelines in the United States impose strict substantiation requirements for anti-pollution efficacy claims, compelling manufacturers to invest in clinical testing protocols. China's NMPA and GB standards for cosmetics mandate safety assessments for novel barrier-forming ingredients entering the domestic market. Stakeholders must monitor evolving regulatory definitions of "anti-pollution" as distinct from general cosmetic claims to avoid enforcement actions and reformulation costs.
Market Dynamics
Urban particulate matter accumulation on hair and scalp surfaces is forcing manufacturers to reformulate around chelating agents and barrier polymers that neutralize heavy metal deposits from traffic emissions.
Growth Catalysts
- REACH Substantiation Requirements:ECHA's tightened cosmetic claim verification is elevating clinical testing standards across European formulations. Manufacturers now invest in controlled exposure studies to validate pollutant-blocking efficacy.
- Commuter Scalp Protection Demand:Daily transit exposure to PM2.5 and ozone in megacities is creating sustained pull for pre-treatment serums among office workers. This segment prioritizes portable, fast-absorbing formats.
- Ceramide Barrier Technology:Advanced lipid-replacement systems that seal cuticle layers against oxidative stress are expanding application from salon treatments to at-home maintenance protocols.
Market Restraints
- Plant-Derived Chelator Supply Volatility:Organic phytic acid and tannin sourcing from Indian and Brazilian agricultural processors faces seasonal yield fluctuations. This concentrates input cost risk among clean-label formulators.
- Clinical Validation Cost Burden:FDA cosmetic safety guidelines and ECHA REACH protocols require extensive in-vitro and human panel testing. Smaller manufacturers lack capital to generate compliant efficacy dossiers.
- Conventional Antioxidant Substitution:Standard vitamin E and BHT formulations at mass price points satisfy basic consumer expectations. Premium anti-pollution positioning struggles to demonstrate visible differentiation.
Strategic Opportunities
- Secondary City Penetration in China:Tier-2 and Tier-3 urban centers with deteriorating air quality indices remain underserved by premium protective hair care. Local e-commerce platforms enable direct-to-consumer distribution bypassing tier-1 retail saturation.
- Prebiotic Scalp Microbiome Positioning:Convergence of pollution defense with microbiome-balancing actives opens formulation white space. This hybrid claim addresses both environmental and biological scalp stressors.
- EU Green Deal Ingredient Incentives:Biodegradable polymer research funding and green chemistry certification pathways accelerate sustainable barrier technology development. Early certification captures preferential retail placement.
Industry Challenges
- Cosmetic Chemist Specialization Gap:Formulation expertise at the intersection of atmospheric chemistry and hair fiber mechanics remains scarce. Recruitment competition intensifies between dermatological and consumer goods divisions.
- Multi-Market Registration Complexity:Divergent definitions of "anti-pollution" as cosmetic versus quasi-drug claims across NMPA China, FDA United States, and ECHA Europe force parallel dossier preparation. Registration timelines extend 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Pollution Hair Care Market |
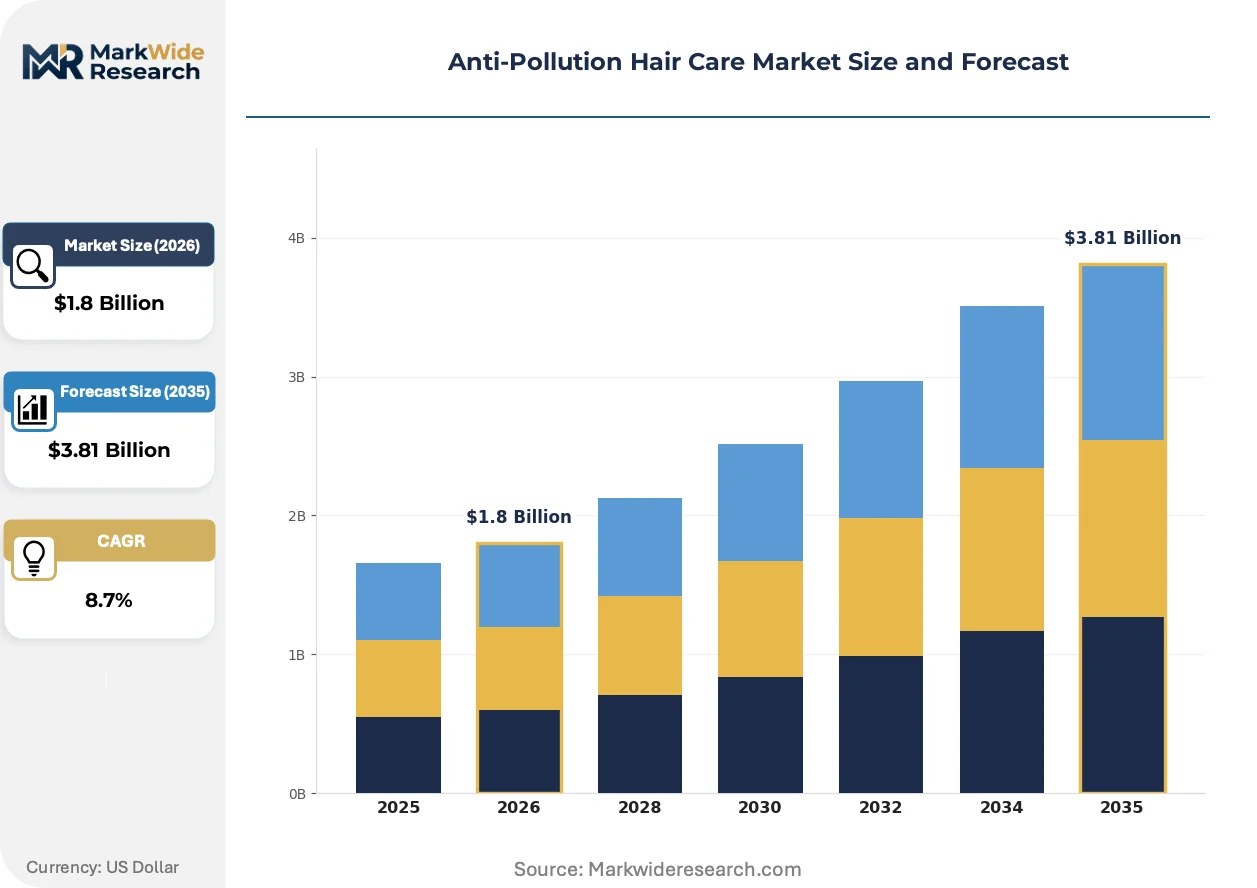
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Serum, Mask Formulation: Organic, Synthetic, Herbal, Paraben-Free End User: Women, Men, Children, Unisex Distribution Channel: Online, Supermarket, Beauty Stores, Salons |
| Companies Covered | L'Oreal S.A., Procter & Gamble, Unilever, Beiersdorf AG, Shiseido Company, Kao Corporation, Henkel, Coty Inc., De Lorenzo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Pollution Hair Care Market Strategic Shifts
Formulation science is pivoting from reactive cleansing to preventive shielding architectures, with sensorial delivery systems and biomimetic materials commanding development resources.
Encapsulated ferulic acid systems with time-release kinetics are automating antioxidant replenishment across extended urban exposure periods. Professional salon chains in Seoul and Shanghai are adopting these formats for express pre-styling treatments. The technology is automating labor-intensive reapplication protocols while compressing service duration requirements.
China's NMPA has issued draft guidelines distinguishing environmental protection claims from general cosmetic benefits, mandating specific pollutant-type substantiation. Domestic manufacturers must now document efficacy against named contaminants rather than generic "anti-pollution" language. Premium serum categories face the steepest compliance recalibration as existing portfolios lack particulate-specific testing.
Subscription-based personalized regimen services are displacing single-SKU purchasing among urban professionals with documented scalp sensitivity. Direct-to-consumer platforms in London and New York bundle quarterly diagnostic testing with adaptive formula adjustments. This pattern concentrates highest adoption among consumers with verified dermatologist referrals.
Anti-Pollution Hair Care Market Segmentation
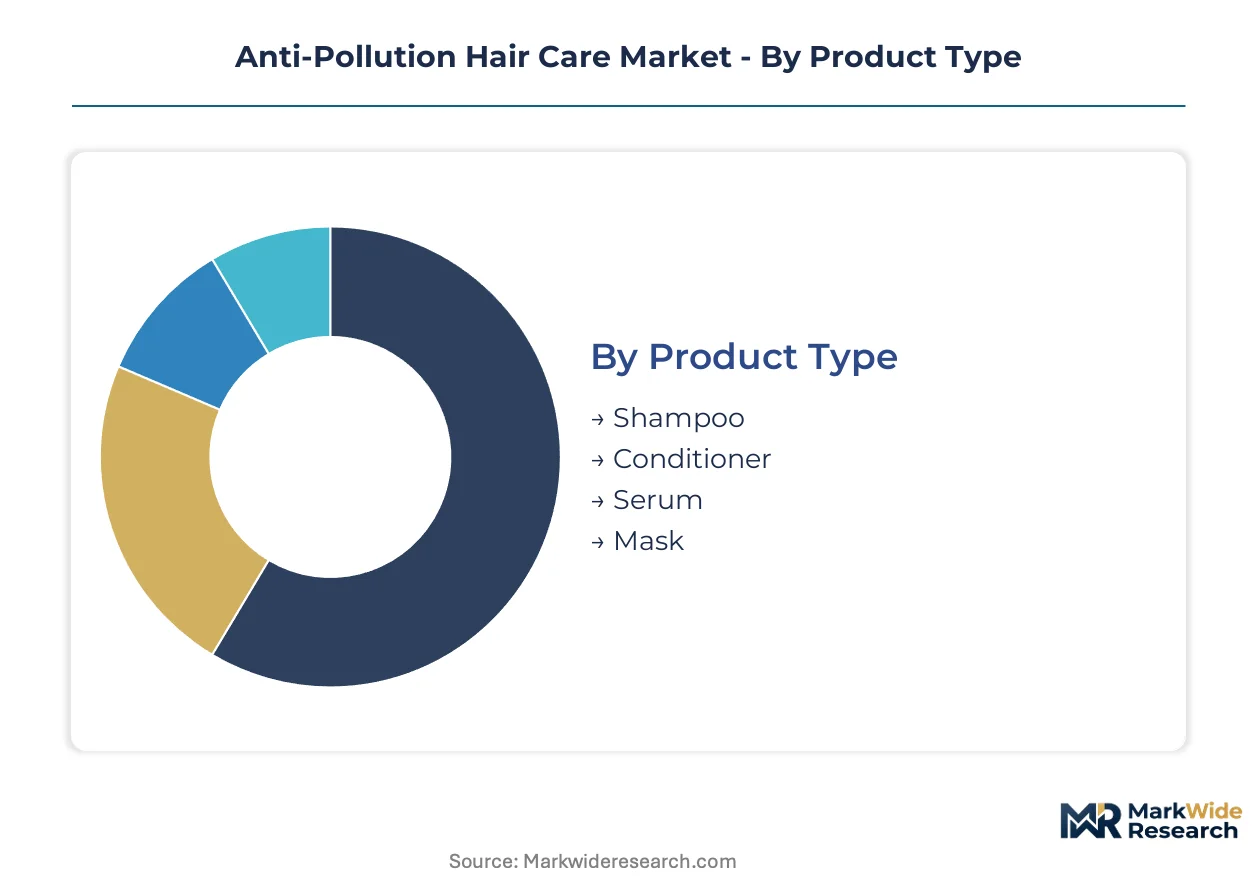
Anti-pollution hair care manufacturers configure production assets around formulation complexity and clinical substantiation requirements. Segment-specific capital allocation determines which product architectures capture margin in regulated markets.
Product Type:
Serum and mask formats demand disproportionate R&D investment due to concentrated active delivery systems and barrier-forming polymer development.
- Shampoo:Mass-market workhorse formulations incorporate chelating agents at functional concentrations to remove particulate buildup from daily urban exposure. Volume concentrates in South Asian supermarket networks where unit economics favor large-format packaging.
- Conditioner:Cationic polymer systems deposit protective films that seal cuticle layers against ozone-induced brittleness. Salon channels in Seoul and Tokyo drive premium positioning for express rinse-out treatments.
- Serum:Encapsulated ferulic acid and time-release antioxidant complexes command the highest price points due to clinical validation requirements for substantiated anti-pollution claims. Commuter demand in Chinese megacities prioritizes portable, fast-absorbing formats for pre-styling application.
- Mask:Intensive weekly treatments leverage ceramide barrier technology and lipid-replacement systems for oxidative stress recovery. Professional salon adoption in London and New York supports premium service bundling with diagnostic scalp analysis.
Shampoo absorbs the bulk of installed capacity; serum is expanding most quickly.
Formulation:
Raw material sourcing strategies diverge sharply between petroleum-derived synthetics and agricultural-dependent organic supply chains.
- Organic:Plant-derived phytic acid and tannin chelators require vertical integration with Indian and Brazilian agricultural processors to manage seasonal yield volatility. Clean-label positioning captures price premiums in EU Green Deal-aligned retail channels.
- Synthetic:Laboratory-engineered barrier polymers and EDTA derivatives offer consistent quality and scalable manufacturing. REACH compliance documentation is streamlined due to established safety dossiers.
- Herbal:Traditional botanical extracts from Ayurvedic and TCM pharmacopeias address ozone-induced inflammation through multi-compound synergies. Domestic manufacturers in India leverage BIS certification for export positioning.
- Paraben-Free:Preservative system reformulation using phenoxyethanol or sodium benzoate has become baseline hygiene rather than differentiation. Mass-market penetration across all distribution channels now mandates this specification.
Synthetic formulations retain dominant production share; organic is climbing the fastest amid clean-label procurement shifts.
End User:
Gender-targeted marketing architectures reflect divergent scalp biology and styling routine integration points.
- Women:Multi-step regimen adherence supports serum-and-mask combination protocols with quarterly diagnostic testing subscriptions. Direct-to-consumer platforms in London and New York concentrate highest lifetime value customers.
- Men:Simplified shampoo-plus-styling product architectures prioritize speed of application and neutral scent profiles. E-commerce penetration in Chinese tier-2 cities outpaces traditional retail for this segment.
- Children:Mild surfactant systems with tear-free claims address parental concerns about urban playground exposure to particulate matter. Pediatric dermatologist endorsement requirements elevate clinical testing burdens.
- Unisex:Fragrance-neutral formulations and minimalist packaging architectures reduce SKU complexity for multi-user households. Salon professional recommendation drives trial conversion.
Women's segments command the majority of marketing expenditure; men's is gaining share fastest through digital-native brand launches.
Distribution Channel:
Channel selection determines margin structure through regulatory compliance cost allocation and customer education requirements.
- Online:Subscription-based personalized regimen services with adaptive formula adjustments require substantial backend algorithmic investment. Direct-to-consumer platforms bypass tier-1 retail saturation in Chinese secondary cities.
- Supermarket:Mass-market shampoo and conditioner formats compete on shelf-space economics and promotional frequency. Unilever's South Asian network demonstrates scale advantages in this channel.
- Beauty Stores:Assisted selling environments enable ingredient education and diagnostic tool deployment for serum and mask categories. Sephora and Ulta locations in US metropolitan areas concentrate premium trial.
- Salons:Professional pre-treatment service integration demands field education infrastructure and stylist certification programs. Kao Corporation's Japanese network anchors ceramide-based protocol adoption.
Supermarket channels handle the greatest unit volume; online is expanding most quickly through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation manufacturing clusters concentrate in Germany and Japan, while consumption volume concentrates in Chinese megacities and Indian urban corridors where particulate exposure drives protective product uptake.
China
Commuter scalp protection demand in Beijing and Shanghai sustains premium serum uptake among office workers exposed to PM2.5. NMPA draft guidelines now mandate pollutant-specific efficacy documentation for environmental protection claims. Guangzhou-based e-commerce platforms enable direct-to-consumer distribution bypassing tier-1 retail saturation.
Japan
Ozone-induced hair brittleness drives ceramide-based formulation adoption in Tokyo and Osaka metropolitan areas. METI green chemistry certification pathways accelerate sustainable barrier technology development. Kao Corporation anchors professional salon network penetration through stylist certification programs.
India
Mass-market shampoo volume concentrates in Mumbai and Delhi supermarket networks where unit economics favor large-format packaging. BIS certification requirements for Ayurvedic botanical exports elevate quality documentation burdens. Bangalore-based agricultural processors supply plant-derived phytic acid chelators to clean-label formulators.
Germany
REACH substantiation requirements compel clinical testing investment for barrier-forming polymer validation. ECHA tightened cosmetic claim verification elevates formulation standards across European markets. Hamburg and Düsseldorf host dermatological research infrastructure serving regional manufacturers.
United States
Subscription-based personalized regimen services concentrate in New York and Los Angeles among urban professionals with verified dermatologist referrals. FDA cosmetic safety guidelines impose extensive in-vitro and human panel testing requirements. Sephora and Ulta locations in metropolitan areas drive premium serum trial conversion.
Anti-Pollution Hair Care Market Competitive Environment
Top-tier vendors anchor premium serum and salon protocol segments, while mass-market specialists compete on supermarket shelf-space economics and promotional frequency. Mid-tier players occupy clean-label positioning with organic certification differentiation. Strategic archetypes include dermatological research conglomerates, mass-market FMCG networks, and regional botanical specialists. Competitive moves concentrate on M&A for ceramide technology access and strategic partnerships for Chinese e-commerce distribution.
Among research-intensive conglomerates, L'Oreal S.A. and Shiseido Company exemplify the dermatological-architecture archetype through barrier-forming polymer development. Unilever occupies a position within mass-market penetration strategies across South Asian supermarket networks. Kao Corporation represents the regional-salon-integration model through professional certification infrastructure in Japan.
| Leading Market Players |
|---|
| L'Oreal S.A. |
| Procter & Gamble |
| Unilever |
| Beiersdorf AG |
| Shiseido Company |
| Kao Corporation |
| Henkel |
| Coty Inc. |
| De Lorenzo |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between REACH-validated barrier polymers and commodity chelating agents manifests in both pricing premiums and supply chain sourcing strategies. Premium serum manufacturers absorb extended lead times for ECHA-compliant clinical dossiers, while mass-market shampoo formulators exploit spot purchasing of EDTA derivatives from South Asian chemical processors.
Pricing Analysis
Expedited lead-time premiums dominate contract negotiations for ceramide barrier technologies sourced from Japanese specialty chemical houses. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with NMPA-substantiated formulations commanding the widest spreads. Cost compression in the organic phytic acid tier is intensifying because Indian agricultural processors face monsoon-driven yield volatility. Mass-market supermarket buyers exhibit highest price sensitivity, while subscription-based direct-to-consumer platforms absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Returns and refurbishment flows remain negligible given cosmetic shelf-life constraints, though professional salon channels manage expired inventory through stylist sampling programs. Manufacturing gravity centers on Germany, Japan, and China, with Hamburg hosting dermatological research infrastructure and Guangzhou anchoring e-commerce fulfillment. Raw material procurement draws from Brazilian tannin extractors, Indian phytic acid processors, and South Korean encapsulated ferulic acid specialists. Single-source vulnerability concentrates in Japanese ceramide suppliers serving Tokyo salon networks. Distribution runs through supermarket chains for volume, direct-to-consumer platforms for premium serums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around clinical validation capabilities as ECHA and NMPA documentation burdens force subscale formulators toward private-label exits.
For Market Incumbents: Anticipate margin compression from clean-label entrants by securing captive supply of plant-derived chelators through backward integration with Indian agricultural processors. Accelerate REACH dossier recycling across multiple product architectures to amortize clinical testing costs. Defend salon channel positioning through exclusive ceramide technology licensing from Japanese research houses. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms in Chinese tier-2 cities offer the most penetrable white space, bypassing tier-1 retail saturation and Sephora's assisted-selling economics. Target men's simplified shampoo-plus-styling architectures where digital-native brands outpace legacy FMCG digital competence. Prioritize microbiome-pollution hybrid claims to differentiate from established antioxidant positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to dermatological research conglomerates seeking barrier polymer IP portfolios. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Acquisition target archetype: mid-tier organic formulators with BIS certification and established Indian agricultural processor relationships. Monitor NMPA finalization of pollutant-specific claim guidelines as inflection indicator for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Polymer IP Acquisition | Captures ECHA-validated clinical dossiers that accelerate NMPA registration timelines. |
| Direct-to-Consumer Platform Launch | Bypasses tier-1 retail saturation in Beijing and Shanghai through Guangzhou e-commerce infrastructure. |
| Ceramide Technology Licensing | Secures exclusive salon protocol adoption through Kao Corporation's stylist certification network. |
| Organic Certification Investment | Unlocks EU Green Deal-aligned retail placement and premium price positioning. |
| Subscription Personalization Buildout | Concentrates highest lifetime value customers through quarterly diagnostic testing bundles. |
Study Parameters
Multi-period observation of NMPA regulatory filings, REACH registration volumes, and Chinese e-commerce platform SKU proliferation anchored the trend analysis, supplemented by interviews with cosmetic formulators, salon chain procurement directors, and dermatological research leads. Secondary validation drew from ECHA substance databases, BIS certification registries, customs trade data for phytic acid imports, and SEC filings of listed personal care conglomerates. Bottom-up channel volume estimates triangulated against top-down market sizing from macroeconomic exposure indices.
Input-output matrices modeled demand drivers across formulation complexity tiers, distribution channel economics, and regional regulatory clusters throughout the forecast period. Segmentation dimensions included product architecture, certification grade, end-user gender targeting, and geographic adoption pattern. CAGRs derived from regression analysis of historical premium-mass price spread evolution and clinical validation cost trajectories. Forecast inputs incorporated urban particulate matter exposure indices and commuter population density projections.
The model holds under stable regulatory definitions of anti-pollution claims; deviation in NMPA final guidelines or ECHA enforcement intensity would shift premium tier volume assumptions. Practitioners should monitor draft guideline publication timelines and agricultural processor yield reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Australia Hair Removal Market
Hair Care
Qatar Hair Care Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
China Hair Care Products Market
Hair Care
Brazil Hair Care Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Hair Bond Multiplier Market
Hair Care
Men's Hairspray Market
Hair Care
Hair Tonic Market
Hair Care
Global Professional Hair Care Market
Hair Care
Hair Relaxer Market
Hair Care
India Hair Care Market
Hair Care
Hair Extension Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Sweden Hair Care Market
Hair Care
Hair Edge Tamer Market