
 China Hair Care Products Market | 2026-2036
China Hair Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
China Hair Care Products Market Insights
Urban male grooming routines is recalibrating demand toward specialized scalp treatments and styling formats. Procter & Gamble leverages its mass-market distribution depth across tier-one cities. Guangzhou Adolph anchors its position through herbal-positioned formulations that resonate with regional ingredient preferences. L'Oréal competes on salon-grade professional lines that command premium shelf placement in specialty retail.
Hair care products encompass cleansers, conditioners, styling agents, and therapeutic treatments formulated with surfactant bases, active botanical extracts, or silicone conditioning polymers designed to maintain scalp health and hair fiber integrity. The category serves consumer daily hygiene, aesthetic styling, and dermatological maintenance needs across household and professional service contexts. Shampoos and conditioners occupy the volume core, while treatments capture expanding margin pools as consumers prioritize scalp health solutions. Organic and natural formulation types attract ingredient-conscious buyers, though chemical-based variants sustain manufacturing scale advantages. Online distribution channels are displacing traditional supermarket dominance, particularly for direct-to-consumer brand building.
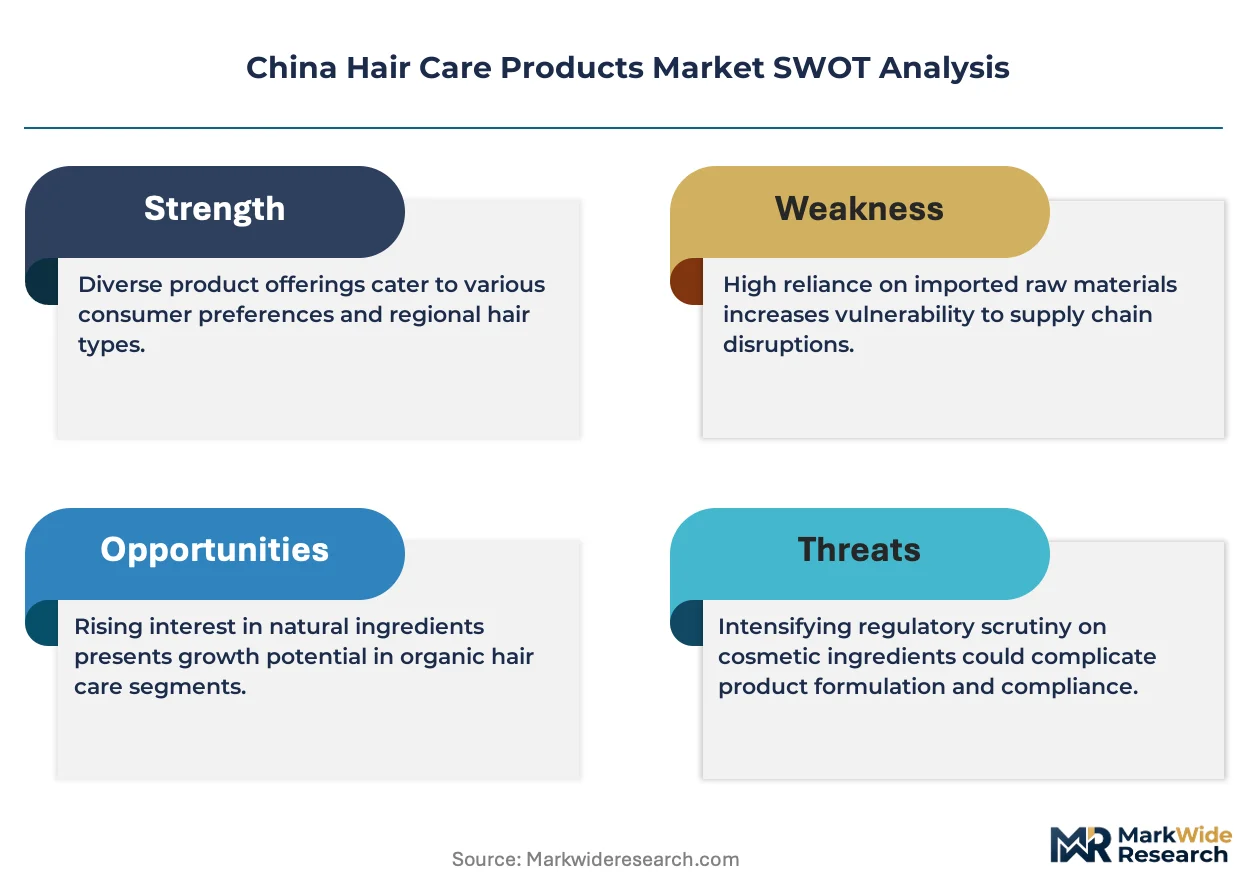
NMPA cosmetic registration requirements and GB standards govern ingredient safety disclosures, labeling protocols, and manufacturing facility certifications across domestic production and import channels. SAMR advertising enforcement constrains functional claims, pushing brands toward clinical validation investments. MEE environmental compliance adds wastewater and packaging recycling obligations that elevate operational costs for chemical-based producers. Stakeholders must monitor regulatory tightening on per- and polyfluoroalkyl substance restrictions and decide between reformulation investments or portfolio pruning of affected SKUs.
Market Dynamics
Salon professional channels are reconfiguring distribution economics as service providers demand bulk formulations with ingredient transparency that household retail cannot accommodate. This shift compresses margin structures for mass-market incumbents while elevating specialized B2B suppliers.
Growth Catalysts
- Urban male grooming normalization:Specialized scalp treatments and styling formats penetrate tier-one metropolitan routines, expanding addressable demand beyond traditional female-centric positioning.
- NMPA cosmetic registration enforcement:Tightened ingredient compliance requirements favor domestic manufacturers with established GB standards certification over import-dependent competitors facing extended approval timelines.
- Salon-grade professional adoption:Licensed service providers integrate therapeutic treatments into service menus, creating recurring B2B volume that stabilizes revenue against retail cyclicality.
Market Restraints
- Surfactant input cost volatility:Petroleum-derived cleansing bases expose formulators to crude-linked price swings that compress gross margins during energy market dislocations.
- Guangzhou manufacturing cluster concentration:Overreliance on Pearl River Delta production creates geographic vulnerability to regional logistics disruptions or environmental compliance shutdowns.
- Silicone polymer substitution limitations:Natural-positioned alternatives fail to replicate conditioning performance at equivalent cost, constraining premium pricing power for clean-label variants.
Strategic Opportunities
- Lower-tier city penetration:Chengdu and Xi'an beauty corridors demonstrate underdeveloped professional service density relative to disposable income growth, offering first-mover positioning for salon-format expansion.
- MEE packaging recycling mandates:Circular economy compliance obligations create competitive differentiation for producers investing in mono-material packaging systems ahead of enforcement deadlines.
- Live commerce channel integration:Douyin and Xiaohongshu creator ecosystems enable direct-to-consumer education on scalp health, bypassing traditional supermarket gatekeepers for niche therapeutic launches.
Industry Challenges
- Cosmetology-chemistry skill convergence:Formulation teams lack dermatological expertise to validate clinical claims under SAMR advertising scrutiny, forcing external laboratory partnerships that extend development cycles.
- Dual carbon goal capex requirements:Manufacturing facility retrofits for wastewater treatment and renewable energy integration demand capital allocation that strains mid-tier producers with limited balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Hair Care Products Market |
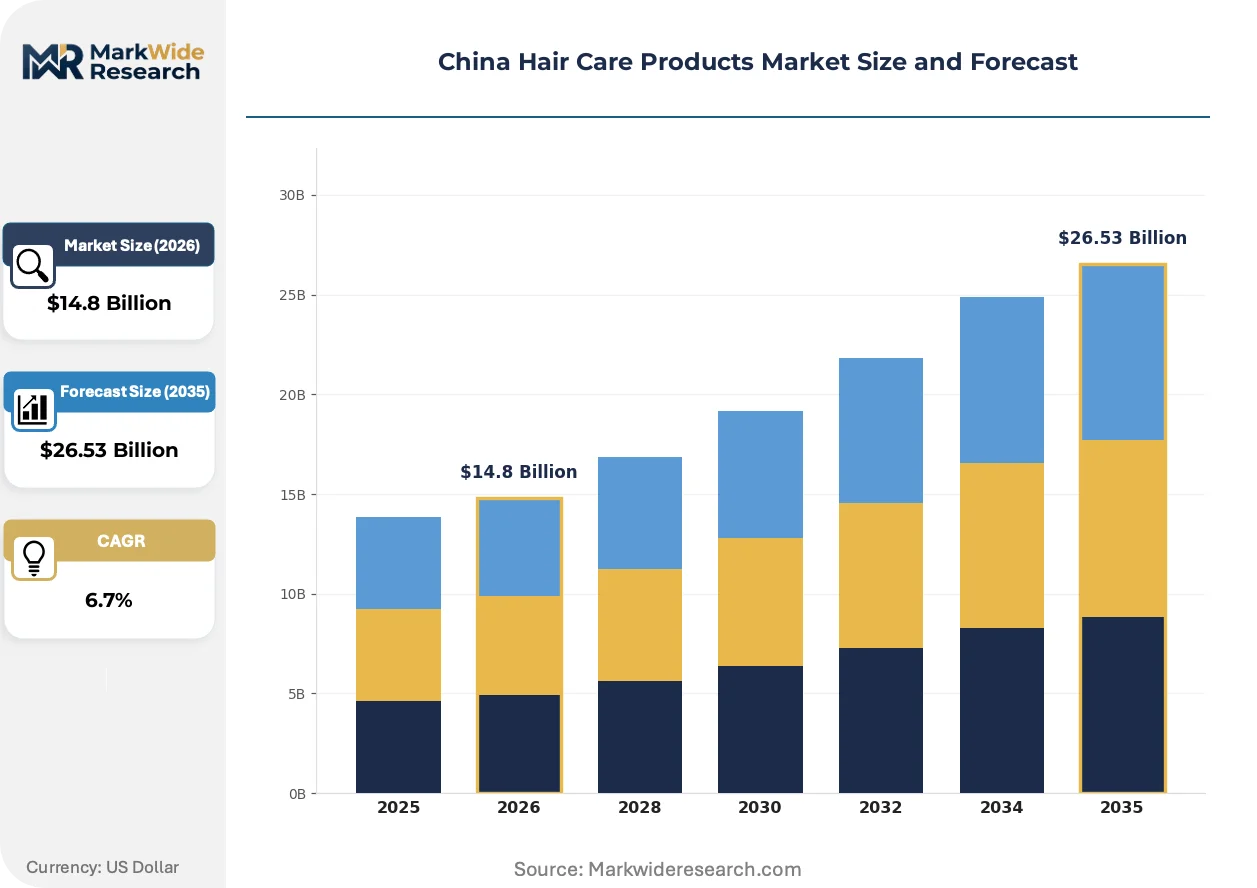
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Styling Products, Treatments Target Audience: Men, Women, Children, Salon Professionals Formulation Type: Organic, Natural, Chemical-Based, Hypoallergenic Distribution Channel: Online, Supermarkets, Specialty Stores, Drugstores |
| Companies Covered | Procter & Gamble, Unilever, Guangzhou Adolph, L'Oréal, Henkel, Beiersdorf, Kao Corporation, Shiseido Company, Shanghai Pechoin Daily Chemical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Hair Care Products Market Trends and Innovations
Biotechnology-derived actives and precision scalp diagnostics are displacing commodity conditioning approaches, while regulatory pressure on per- and polyfluoroalkyl substances accelerates reformulation investment cycles across the competitive landscape.
Scalp microbiome analysis technology is consolidating diagnostic capability into at-home testing formats that match consumer-specific bacterial profiles to customized treatment regimens. Tier-one urban professionals adopt these systems at accelerating velocity, compressing the traditional trial-and-error purchase pattern into data-driven subscription models. This consolidation is enabling direct-to-consumer brands to bypass conventional retail shelf competition entirely.
NMPA's tightening oversight of functional cosmetic claims under SAMR coordination is forcing manufacturers toward dermatological validation investments. The industrial consequence elevates R&D expenditure thresholds that disadvantage import-dependent competitors lacking domestic clinical trial infrastructure. Color-treated hair repair segments face the most acute compliance pressure, with brands accelerating GB standards-aligned safety documentation.
Beauty service unbundling disrupts traditional product-channel relationships as independent stylists source professional-grade formulations through WeChat commerce rather than licensed distributor networks. Individual practitioners in Shanghai and Guangzhou corridors replace institutional procurement with flexible small-batch purchasing that prioritizes ingredient transparency over brand heritage. This behavioral rotation is most visible among freelance colorists building personal reputation through social media-verified product choices.
China Hair Care Products Market Segmentation
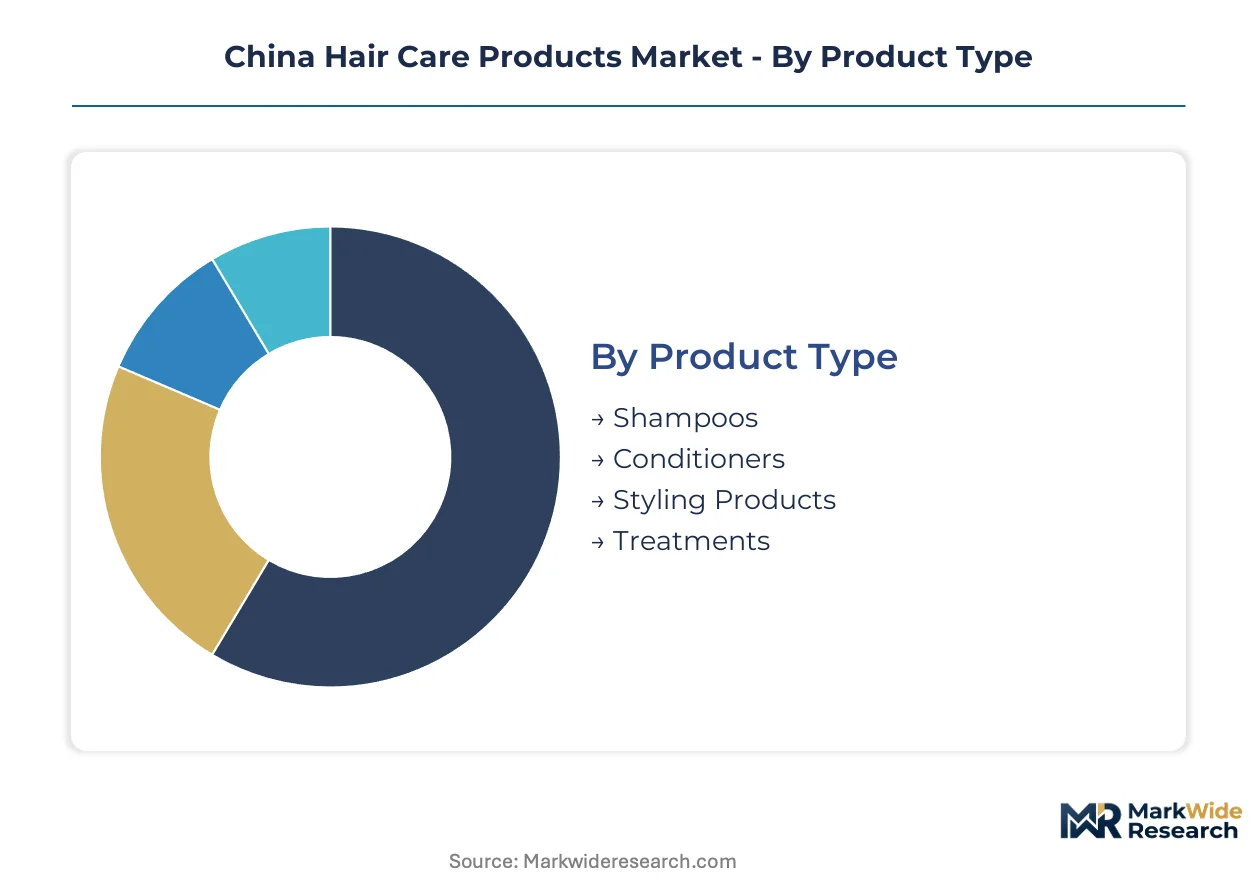
Segmentation reveals where capital deployment concentrates and where margin structures diverge most sharply. Formulation chemistry and channel access create distinct competitive moats that reshape entry economics for new participants.
Product Type:
Capital intensity peaks where manufacturing complexity meets regulatory validation burdens, separating commodity producers from clinical-grade specialists.
- Treatments:Therapeutic formulations incorporate active botanical extracts and silicone conditioning polymers requiring dermatological testing under NMPA cosmetic registration protocols. Shanghai beauty corridors concentrate demand as scalp health prioritization drives premium positioning among tier-one urban professionals.
- Shampoos:Surfactant-based cleansers dominate volume throughput with petroleum-derived cleansing bases that expose manufacturers to crude-linked input volatility. Guangzhou manufacturing clusters sustain scale advantages through Pearl River Delta chemical supply integration.
- Conditioners:Silicone polymer formulations maintain household penetration despite natural-positioned substitution pressures.
- Styling Products:Aerosol and cream formats serve male grooming normalization trends in metropolitan corridors.
Shampoos absorb the bulk of installed capacity; treatments are expanding most quickly.
Target Audience:
Customer-type stratification determines pricing power and channel strategy, with professional service integration commanding fundamentally different economics than household retail.
- Salon Professionals:Licensed service providers demand bulk formulations with ingredient transparency and GB standards certification that household retail SKUs cannot accommodate. B2B procurement through WeChat commerce channels is displacing traditional distributor relationships in Shanghai and Guangzhou corridors.
- Men:Specialized scalp treatments and styling formats penetrate tier-one metropolitan routines as grooming normalization expands addressable demand beyond traditional female-centric positioning.
- Women:Volume foundation sustaining mass-market distribution depth across supermarket and online channels.
- Children:Hypoallergenic specification requirements elevate formulation and safety documentation costs.
Women retain the largest revenue base; salon professionals are climbing the fastest as service unbundling accelerates.
Formulation Type:
Raw material sourcing and certification burden create tiered cost structures that constrain clean-label pricing power.
- Chemical-Based:Petroleum-derived surfactants and silicone polymers sustain manufacturing scale advantages and conditioning performance benchmarks that natural alternatives fail to replicate at equivalent cost. MEE environmental compliance adds wastewater and packaging recycling obligations that elevate operational costs.
- Natural:Herbal-positioned formulations resonate with regional ingredient preferences in Guangzhou and surrounding Pearl River Delta markets.
- Organic:Certification requirements and agricultural input sourcing constrain supply elasticity.
- Hypoallergenic:Dermatological validation investments under SAMR advertising enforcement extend development cycles.
Chemical-based formulations command the majority of production volume; natural variants are gaining share fastest as regional ingredient preferences harden.
Distribution Channel:
Channel economics determine customer acquisition cost and brand-building velocity, with digital platforms eroding traditional gatekeeper dominance.
- Online:Douyin and Xiaohongshu creator ecosystems enable direct-to-consumer education on scalp health, bypassing supermarket gatekeepers for niche therapeutic launches. Live commerce integration compresses traditional trial-and-error purchase patterns into data-driven subscription models.
- Supermarkets:Mass-market distribution depth across tier-one cities sustains volume for established incumbents facing share erosion to digital channels.
- Specialty Stores:Salon-grade professional lines command premium shelf placement in beauty corridors.
- Drugstores:Therapeutic treatment positioning aligns with dermocosmetic retail formats.
Supermarkets still handle the largest transaction volume; online channels are expanding most quickly as creator commerce matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hainan Free Trade Port's duty-free retail incentives concentrate premium beauty distribution, reshaping coastal logistics patterns for imported formulations.
Shanghai
Scalp health prioritization among tier-one urban professionals drives therapeutic treatment demand through specialty retail channels. SAMR advertising enforcement constrains functional claims, pushing brands toward domestic clinical validation investments. The Yangtze River Delta manufacturing corridor anchors formulation R&D facilities serving eastern consumption density.
Guangzhou
Pearl River Delta production clusters sustain chemical-based manufacturing scale through integrated surfactant supply chains. MEE environmental compliance adds wastewater treatment obligations that elevate operational costs for local producers. The city's beauty corridors demonstrate accelerating salon professional adoption of bulk therapeutic formulations.
Beijing
Regulatory headquarters proximity shapes NMPA cosmetic registration strategy for domestic and import brands navigating approval timelines. Dual carbon goal mandates accelerate manufacturing facility retrofit requirements across northern production assets. The Beijing-Tianjin-Hebei corridor concentrates dermocosmetic retail expansion targeting ingredient-conscious metropolitan consumers.
Sichuan-Chongqing
Chengdu's underdeveloped professional service density relative to disposable income growth offers first-mover positioning for salon-format expansion. Regional ingredient preferences favor herbal-positioned formulations that resonate with southwestern consumer bases. Live commerce creator ecosystems on Douyin enable direct-to-consumer education bypassing traditional supermarket gatekeepers.
China Hair Care Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with mass-market distribution depth commanding volume leadership while professional-grade lines capture premium positioning. The vendor base organizes around three strategic archetypes: multinational incumbents with tier-one city penetration, domestic herbal-positioned specialists leveraging regional ingredient preferences, and salon-grade professional suppliers serving licensed service providers. Competitive moves concentrate on M&A for distribution network consolidation and strategic partnerships for clinical validation infrastructure.
Within the multinational tier, Procter & Gamble and L'Oréal exemplify divergent positioning strategies—mass-market breadth against salon-grade premium placement. Guangzhou Adolph occupies a position among domestic specialists capitalizing on Pearl River Delta manufacturing integration and herbal formulation resonance. These three anchors represent the structural split between import-dependent scale advantages and domestic regulatory compliance agility.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Guangzhou Adolph |
| L'Oréal |
| Henkel |
| Beiersdorf |
| Kao Corporation |
| Shiseido Company |
| Shanghai Pechoin Daily Chemical |
| Others |
Pricing and Supply Chain Analysis
Biotechnology-derived active ingredient manufacturing is compressing formulation cost curves while concentrating procurement leverage among Pearl River Delta producers with GB standards certification. This dual shift simultaneously elevates margin pressure on import-dependent brands and rewards domestic manufacturers with integrated surfactant supply chains.
Pricing Analysis
Short lead-time premiums command shelf-space allocation in Shanghai and Guangzhou beauty corridors where salon professionals demand rapid replenishment cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by NMPA registration tier and clinical validation depth. Pricing pressure stems from petroleum-derived surfactant input volatility that compresses gross margins for chemical-based producers. Household retail buyers exhibit highest price sensitivity while licensed salon professionals prioritize ingredient transparency over per-unit cost.
Supply Chain Analysis
GB standards certification gates supplier qualification, limiting bulk therapeutic formulation sourcing to domestic manufacturers with verified facility audits. Production concentrates in China, South Korea, and Japan where silicone polymer and surfactant feedstock integration sustains scale economics. Raw material dependencies center on petroleum-derived cleansing bases, botanical extract agricultural inputs, and specialty conditioning polymers. Single-source vulnerability runs through Guangzhou manufacturing cluster concentration exposed to MEE environmental compliance shutdowns. Distribution runs through licensed distributor networks, WeChat commerce channels, and direct-to-consumer live commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA cosmetic registration requirements function as a cost-of-compliance moat that advantages domestic manufacturers with established GB standards infrastructure over import-dependent competitors facing extended approval timelines.
For Market Incumbents: Deploy clinical validation infrastructure investments to defend positioning against SAMR advertising enforcement tightening. Incorporate scalp microbiome diagnostic technology into service menus to lock in recurring B2B volume from unbundled freelance stylists. Backward integration into captive botanical extract sourcing secures margin against agricultural input price swings.
For New Entrants and Emerging Players: Capture underdeveloped professional service density in Chengdu and Xi'an corridors where disposable income growth outpaces salon-format supply. Prioritize Douyin creator ecosystem partnerships for direct-to-consumer scalp health education bypassing supermarket gatekeepers. Anchor initial positioning through mono-material packaging systems that preempt MEE circular economy mandates.
For Investors and Strategic Acquirers: Exit pathways concentrate in domestic herbal-positioned specialists with Pearl River Delta manufacturing integration and established NMPA registration portfolios. Long-term viability favors producers with dermatological validation capabilities and salon-grade professional line revenue diversification. Monitor SAMR enforcement intensity on functional cosmetic claims as inflection indicator for clinical validation investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Infrastructure Investment | GB standards-aligned safety documentation satisfies SAMR advertising enforcement requirements for therapeutic treatment launches. |
| Salon-Grade Professional Line Expansion | B2B volume from licensed service providers stabilizes revenue against retail cyclicality in tier-one metropolitan corridors. |
| Mono-Material Packaging Transition | MEE circular economy compliance creates competitive differentiation ahead of enforcement deadline acceleration. |
| Live Commerce Channel Integration | Douyin and Xiaohongshu creator ecosystems enable direct-to-consumer education bypassing traditional supermarket gatekeepers. |
| Botanical Extract Supply Integration | Pearl River Delta agricultural input sourcing secures cost position for herbal-positioned formulations resonating with regional preferences. |
Research Methodology
Multi-period observation of NMPA registration approval timelines, SAMR enforcement actions, and salon professional procurement patterns anchored the trend analysis, supplemented by interviews with formulation R&D directors, licensed salon operators, retail category buyers, and MEE compliance officers. Secondary validation drew from customs import records, GB standards documentation, NMPA cosmetic registration databases, and Pearl River Delta manufacturing facility audit disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Input-output matrices mapped surfactant feedstock costs, clinical validation expenditure tiers, and channel-specific margin structures across the projection horizon. Segmentation dimensions modeled include product type, target audience, formulation chemistry, and distribution channel, with geographic regulatory cluster as an additional industry-specific layer. CAGRs were derived from trend extrapolation of observed adoption velocities calibrated against disposable income elasticity estimates. Forecast inputs incorporated MEE environmental compliance cost trajectories and live commerce penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA registration rule amendments and petroleum price volatility assumptions. A model refresh is warranted upon material change in SAMR advertising enforcement intensity or dual carbon goal implementation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Artificial Hair Integration Market
Hair Care
Hair Serum Market
Hair Care
Hair Edge Tamer Market
Hair Care
Hair Spray Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Hair Tonic Market
Hair Care
Hair Texturizer Products Market
Hair Care
Israel Hair Care Market
Hair Care
Hair Clay Market
Hair Care
Organic Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Global Professional Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Brazil Hair Care Market
Hair Care
France Haircare Market
Hair Care
Rice Water Shampoo Market