
 Hair Care Appliances Market | 2026-2036
Hair Care Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Care Appliances Market Insights
Electrical engineering talent scarcity in consumer appliance design is reorganizing how manufacturers allocate R&D resources across product lines. Dyson leverages proprietary motor technology to dominate premium hair dryer positioning. Panasonic anchors Asian supply chains through integrated component manufacturing. Conair competes across mass-market distribution with broad SKU coverage spanning multiple price tiers.
Hair care appliances encompass electrically powered devices engineered to apply controlled thermal energy, typically between 80°C and 230°C, or directed airflow to modify hair fiber hydrogen bonds for temporary styling. These products serve commercial salons and individual consumers seeking reproducible aesthetic outcomes without permanent chemical alteration. Hair dryers represent the most mature product category with established replacement cycles, while hair stylers capture expanding margin pools as multi-function designs reduce consumer tool counts. Ionic technology leads professional preference for frizz reduction, though ceramic heating elements gain share in home-use segments due to even heat distribution and reduced thermal damage claims.
EU REACH regulations restrict substance use in appliance coatings and polymer housings, while CE marking mandates electrical safety compliance for all products entering European commerce. The US Consumer Product Safety Commission enforces recall protocols for overheating hazards, directly influencing manufacturer warranty and thermal cutoff design investments. Stakeholders must monitor evolving efficiency standards in major economies and assess whether local certification requirements warrant dedicated product variants or unified global platforms.
Market Dynamics
The EU Ecodesign Directive is tightening energy efficiency requirements for electrical personal care devices, forcing manufacturers to redesign thermal management systems and motor architectures ahead of compliance deadlines.
Growth Catalysts
- Professional salon expansion:Commercial styling service demand in China and the United States is accelerating appliance procurement cycles as independent operators upgrade equipment portfolios.
- REACH substance restrictions:European coating and polymer housing regulations are stimulating reformulation R&D that yields safer, differentiated product lines for export markets.
- Ionic technology preference:Frizz-reduction performance claims in professional channels are pulling premium-tier adoption across North American and European salon networks.
Market Restraints
- Rare earth magnet supply concentration:Neodymium sourcing dependence on Chinese processing facilities creates motor cost volatility for high-efficiency dryer production.
- CE marking compliance friction:Electrical safety certification timelines for European market entry extend product launch windows by four to six months versus domestic Chinese certification.
- Ceramic heating substitution pressure:Even heat distribution claims in home-use segments are compressing traditional metal-element market position without full performance parity.
Strategic Opportunities
- Underpenetrated Indian grooming equipment:Rising consumer spending on personal care appliances in tier-two cities offers first-mover positioning ahead of organized retail expansion.
- Dual carbon goal alignment:China's MEE efficiency mandates create regulatory tailwinds for low-wattage motor designs that qualify for domestic green procurement preferences.
- Multi-function tool convergence:Combination styler-dryer platforms are reducing consumer tool counts and capturing margin pools previously fragmented across separate device purchases.
Industry Challenges
- Electrical engineering talent scarcity:Consumer appliance design expertise shortages are forcing manufacturers to concentrate R&D resources on fewer product lines.
- Thermal cutoff redesign capex:US CPSC recall protocol compliance requires warranty and safety system investments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Care Appliances Market |
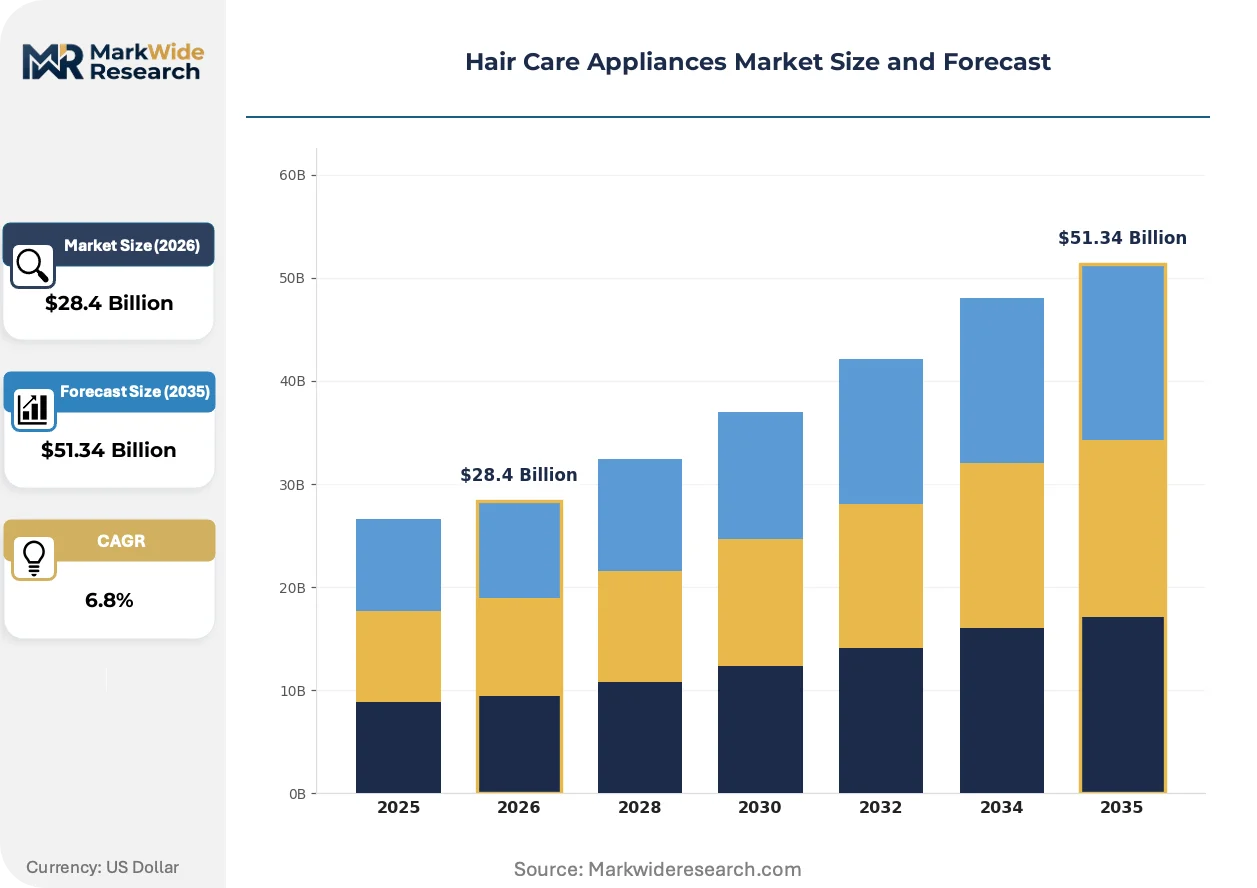
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dryers, Flat Irons, Curling Irons, Hair Stylers Technology: Infrared, Ionic, Ceramic, Tourmaline End User: Professional Salons, Individual Consumers, Hotels, Spas Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Salon Supply Shops |
| Companies Covered | Panasonic, Revlon, Dyson, Remington, Braun, Conair, GHD, Flyco, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Care Appliances Market Trends and Innovations
Product architecture is compressing as thermal efficiency and motor miniaturization converge, while regulatory pressure on energy consumption and material safety accelerates design cycle turnover across all price tiers.
Brushless DC motor technology is miniaturizing. These compact, high-speed designs generate airflow velocity previously requiring larger induction motors. Professional stylists in London and New York are adopting portable units that reduce station clutter. Component footprint reduction is miniaturizing entire appliance chassis dimensions while maintaining thermal output specifications.
REACH substance restrictions are tightening coating and polymer housing requirements. ECHA enforcement is eliminating legacy flame retardants and phthalate plasticizers from European-bound production. Manufacturers serving Germany and France are accelerating water-based coating transitions and bio-polymer trials to maintain market access.
Salon procurement is consolidating through equipment leasing programs. Independent operators in California and Texas are shifting from outright purchase to monthly subscription models that bundle maintenance and replacement guarantees. This financing shift is compressing replacement cycles and locking distributors into longer-term service relationships.
Hair Care Appliances Market Segmentation
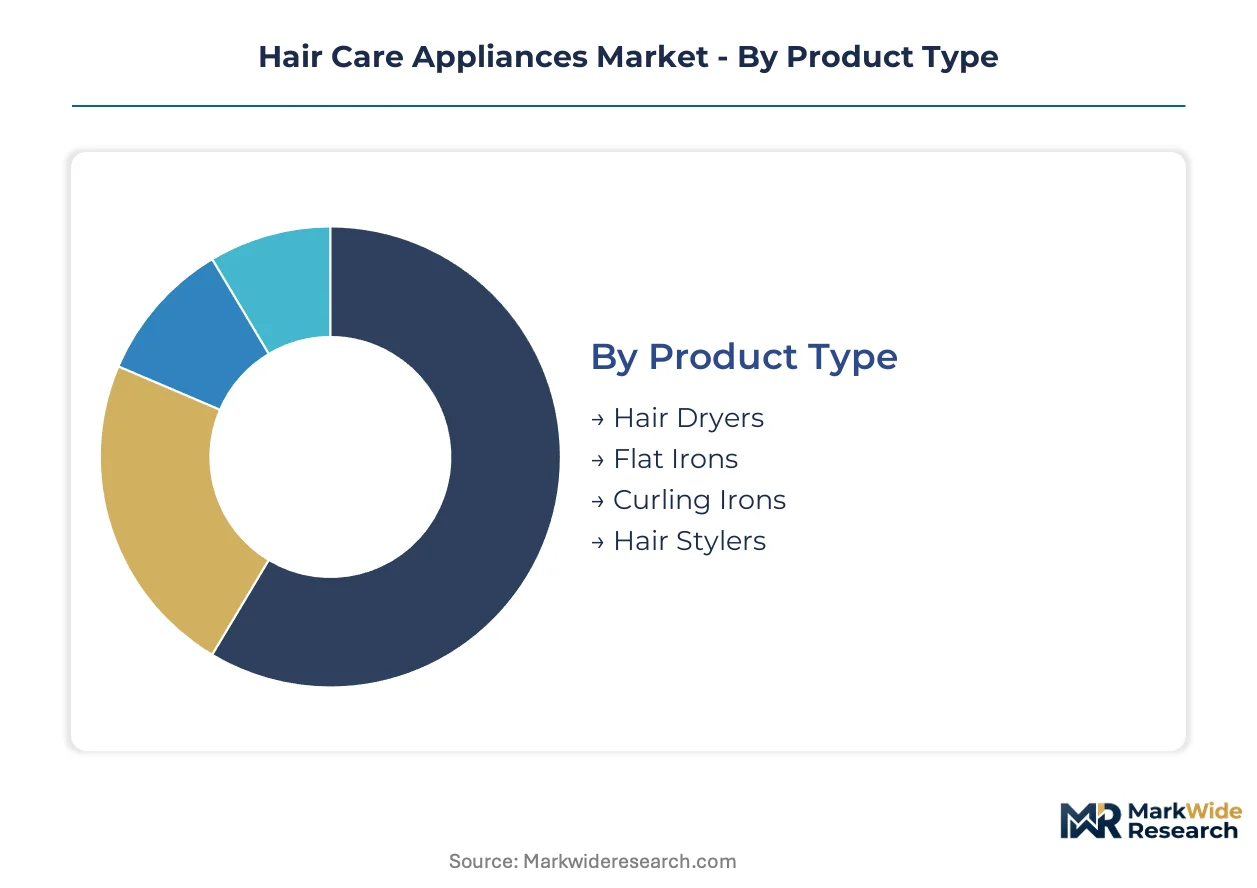
Hair care appliance manufacturers prioritize segment-specific thermal specifications and certification requirements when allocating engineering resources. Product architecture decisions cascade through motor selection, coating chemistry, and distribution partnerships.
Product Type:
Margin pools concentrate in multi-function platforms that collapse separate device categories into unified thermal systems.
- Hair Dryers:These devices generate directed airflow between 80°C and 120°C through brushless DC or conventional induction motors. Demand concentrates in Chinese manufacturing clusters where domestic brands and export OEMs share component suppliers. Replacement cycles drive volume stability in North American and European retail channels.
- Hair Stylers:Multi-function platforms combining drying, straightening, and curling capabilities in single chassis designs. Professional salons in London and New York are consolidating tool inventories around these convergent products. Premium positioning captures margin previously fragmented across separate purchases.
- Flat Irons:Ceramic and tourmaline plate configurations dominate home-use specifications.
- Curling Irons:Barrel diameter variations segment by styling outcome preference.
Hair dryers hold installed capacity. Hair stylers are rotating up the share rankings.
Technology:
Professional channel procurement patterns favor performance claims with measurable frizz reduction and thermal damage mitigation.
- Ionic:Negative ion generation systems neutralize static charge for frizz reduction in humid climates. Salons across Germany and France specify ionic dryers as baseline professional equipment. ECHA coating compliance requirements are accelerating water-based formulation transitions for European-bound production.
- Ceramic:Aluminum oxide or clay-based heating elements distribute thermal energy more evenly than metal coils. Home-use segments in the United States and United Kingdom favor ceramic claims for reduced damage perception. Even heat distribution specifications compress traditional metal-element positioning.
- Tourmaline:Crushed mineral infusion generates infrared heat and negative ions simultaneously.
- Infrared:Longer wavelength thermal penetration targets styling at lower surface temperatures.
Ionic technology anchors professional preference. Ceramic specifications are climbing the fastest in home-use adoption curves.
End User:
Procurement authority and volume scale diverge sharply between commercial operators and individual purchasers.
- Professional Salons:Commercial styling operations require IEC-certified equipment with extended duty cycles and rapid thermal recovery. Independent operators in California and Texas are shifting toward equipment leasing models that bundle maintenance guarantees. Subscription financing compresses replacement cycles versus outright purchase patterns.
- Individual Consumers:Home-use purchasers prioritize portability, storage footprint, and price accessibility. Chinese e-commerce platforms and US mass retailers compete for this volume through promotional pricing and SKU breadth. Replacement cycles extend to three-to-five years for reliable units.
- Hotels:Amenity programs specify compact, low-wattage units for guest room installation.
- Spas:Wellness positioning demands premium industrial design and quiet operation specifications.
Professional salons command specification authority. Individual consumers represent the steepest volume base.
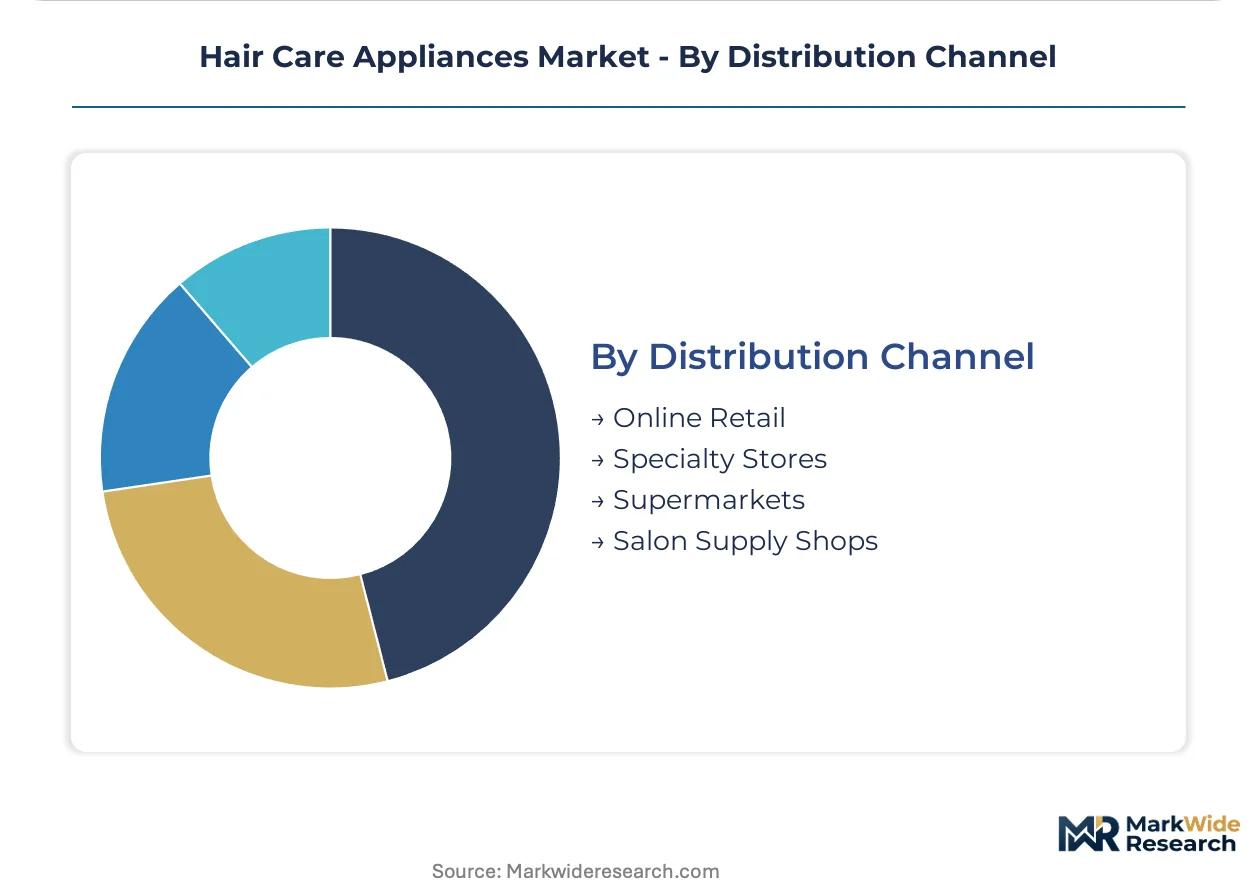
Distribution Channel:
Channel selection determines warranty structure, margin retention, and regulatory documentation requirements.
- Online Retail:Direct-to-consumer platforms require CE marking documentation and localized plug configurations for cross-border fulfillment. Amazon and Tmall capture appliance volume through search-optimized listings and review aggregation. Return logistics and thermal safety compliance documentation strain mid-tier seller operations.
- Specialty Stores:Beauty-focused retailers provide tactile evaluation and staff consultation for premium-tier positioning. Sephora and Ulta Beauty curate appliance assortments around brand heat reputation and influencer validation. Staff training investments justify higher retail margins versus mass channels.
- Supermarkets:Mass-market placement prioritizes price accessibility and impulse purchase packaging.
- Salon Supply Shops:Professional distributors maintain relationships with independent operators through credit terms and equipment servicing.
Online retail holds transaction volume leadership. Specialty stores are rotating up the premium-tier share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE efficiency mandates are reshaping manufacturing investment patterns across the hair care appliance sector. Domestic procurement and export production concentrate in eastern manufacturing corridors. Regulatory divergence between major economies is fragmenting product platform strategies.
China
Domestic grooming equipment spending and salon service expansion drive appliance volume. The MEE dual carbon goals incentivize low-wattage motor designs for green procurement preferences. Manufacturing clusters in Guangdong and Zhejiang provinces export OEM components while serving rising domestic e-commerce demand.
United States
Professional salon equipment leasing and independent operator upgrades accelerate replacement cycles. The CPSC enforces thermal cutoff and overheating recall protocols that shape warranty system investments. California and Texas operators lead the shift toward subscription-based equipment financing models.
Germany
Professional salon ionic technology specifications and frizz-reduction performance claims anchor premium-tier procurement. The ECHA REACH regulations restrict coating substances and polymer housing formulations. Beauty distributors in North Rhine-Westphalia maintain equipment servicing relationships with independent stylists.
India
Tier-two city personal care appliance spending and organized retail expansion create first-mover positioning opportunities. The BIS certification requirements govern electrical safety compliance for domestic market entry. Maharashtra and Gujarat distribution networks are scaling grooming equipment availability ahead of demand maturation.
United Kingdom
Home-use ceramic heating element preference and reduced thermal damage claims drive specification shifts. The CE marking mandates extend product launch timelines versus domestic certification. London salon networks consolidate tool inventories around multi-function platforms that collapse separate device categories.
Hair Care Appliances Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hair care appliance sector. The vendor base spans integrated electronics conglomerates, specialized grooming equipment manufacturers, and regional OEM fabricators. Premium positioning archetypes emphasize proprietary motor architectures and industrial design differentiation. Mass-market archetypes compete through SKU breadth and distribution density. Competitive moves concentrate on portfolio diversification into multi-function platforms and strategic partnerships for component sourcing security.
Among integrated electronics manufacturers, Panasonic and Philips occupy positions spanning professional and consumer segments through component manufacturing depth. Dyson exemplifies the technology-differentiated archetype with proprietary high-speed motor positioning. Conair represents the mass-market coverage model with broad retail distribution across multiple price tiers. Chinese manufacturers including Flyco anchor regional supply chain integration for domestic and export volume.
| Leading Market Players |
|---|
| Panasonic |
| Revlon |
| Dyson |
| Remington |
| Braun |
| Conair |
| GHD |
| Flyco |
| Philips |
| Others |
Pricing and Supply Chain Analysis
Ceramic heating element substitution for traditional metal coils is simultaneously relocating component sourcing toward Guangdong manufacturing clusters and compressing margin structures across mid-tier hair dryer production. This materials transition rewards suppliers with integrated ceramic sintering capabilities while penalizing legacy metal-element assemblers facing price erosion from simplified thermal architectures.
Pricing Analysis
Price spreads between German salon-grade ionic dryers and Chinese mass-market units exceed threefold when landed cost adjustments factor CE marking compliance and warranty provisioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor technology tier and certification grade, with brushless DC architectures commanding substantial premiums over induction motor alternatives. Cost compression in standard-tier segments is intensifying because ceramic heating platform commoditization erodes differentiation leverage. Individual consumers in tier-two Indian cities exhibit highest price sensitivity, while London professional stylists prioritize thermal recovery specifications over unit economics.
Supply Chain Analysis
Inventory buffers for neodymium magnet stockpiles have compressed to six-week coverage as procurement teams navigate Chinese rare earth processing bottlenecks. Motor assembly draws from China, Vietnam, and Malaysia manufacturing bases, with Guangdong province anchoring finished goods output for both domestic consumption and European export. Neodymium, copper windings, and polymer housing resins constitute critical input dependencies. Single-source vulnerability concentrates in Chinese rare earth magnet refining capacity. Distribution runs through Alibaba's Tmall for domestic Chinese volume, Amazon for North American direct-to-consumer fulfillment, and Sephora's specialty retail network for premium salon-grade positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hair care appliance penetration in Indian tier-two cities and professional salon equipment leasing adoption in California and Texas signal early-cycle expansion dynamics with substantial runway ahead of saturation thresholds.
For Market Incumbents: Compound proprietary motor technology advantages through backward integration into brushless DC controller semiconductor sourcing, insulating against rare earth cost volatility while extending performance differentiation gaps against emerging Chinese OEMs. Defend salon channel positioning by embedding predictive maintenance telemetry into leased equipment fleets, converting transactional hardware relationships into recurring service revenue streams that raise switching costs for independent operators. For New Entrants and Emerging Players: Anchor in Maharashtra and Gujarat distribution networks ahead of organized retail infrastructure maturation, capturing first-mover shelf space relationships before incumbent brands localize Indian market strategies. Target underpenetrated spa and hotel amenity segments with compact, low-decibel industrial designs that satisfy wellness positioning requirements without competing directly against established professional salon equipment suppliers. Pursue white-label OEM partnerships with Guangdong fabricators to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated component manufacturers with captive ceramic heating element production and established MEE efficiency certification pathways. Long-term viability favors suppliers combining motor miniaturization IP with regulatory compliance infrastructure spanning REACH, CE marking, and CPSC thermal cutoff mandates. Monitor Indian BIS certification acceleration timelines as the inflection signal indicating when mass-market penetration shifts from aspirational to mainstream adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Function Platform Development | Convergent styler-dryer designs capture margin pools previously fragmented across separate device purchases in London and New York salons. |
| Water-Based Coating Transition | REACH-compliant formulation shifts preserve European market access for German and French-bound production volumes. |
| Equipment Leasing Program Launch | Subscription financing models in California and Texas compress replacement cycles while locking distributors into extended service relationships. |
| Neodymium Sourcing Diversification | Dual-source magnet procurement mitigates Chinese processing concentration risk for high-efficiency motor production. |
| Tier-Two City Distribution Expansion | Maharashtra and Gujarat network scaling captures rising grooming equipment spending ahead of demand maturation. |
Research Methodology
Operator-level perspectives from salon equipment procurement managers, ceramic heating element R&D directors, beauty distributor sales heads, and MEE compliance officers anchored the qualitative base for this study. Primary interview findings combined with secondary validation from customs trade records, SEC 10-K appliance segment disclosures, ECHA REACH substance restriction databases, and Tmall category sales analytics. Bottom-up channel volume estimates and top-down manufacturing capacity assessments were triangulated to reconcile demand-side and supply-side perspectives.
Sensitivity analysis across neodymium price volatility scenarios, REACH compliance timeline assumptions, and Indian retail infrastructure build-out rates tested forecast robustness. Segmentation dimensions modeled include product type, motor technology tier, end-user archetype, and regional regulatory cluster. CAGRs were derived from installed base replacement cycle analysis and penetration rate trajectory fitting. Brushless DC motor adoption curves and salon leasing program diffusion rates constituted industry-specific forecast inputs across the projection horizon.
Material uncertainties — rare earth export restriction escalations, ECHA substance list expansions, and Indian BIS enforcement intensity variations — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued MEE efficiency mandate enforcement and stable US-EU trade corridor access for Chinese-manufactured components. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Australia Hair Removal Market
Hair Care
Malaysia Shampoo Market
Hair Care
India Hair Care Market
Hair Care
Hair Oil Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Argentina Hair Care Market
Hair Care
Hair Dye Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Europe Hair Care Market
Hair Care
Protein Shampoo Market
Hair Care
Germany Hair Care Market
Hair Care
Hair Texturizer Products Market
Hair Care
Hair Bond Multiplier Market
Hair Care
Artificial Hair Integration Market
Hair Care
Global Premium Hair Care Market