
 Hair Spray Market | 2026-2036
Hair Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Spray Market Analysis
Professional stylists and makeup artists are reorganizing category demand away from mass-market home users in developed economies. L'Oréal S.A. leverages its salon-distribution infrastructure to anchor professional-grade lines in Western Europe and North America. Henkel AG & Co. KGaA competes through Schwarzkopf's specialized positioning in high-performance hold segments. Coty Inc. differentiates via prestige fragrance-hybrid formulations that command premium shelf placement in specialty retail.
Hair spray denotes an aerosol or pump-dispensed cosmetic formulation containing polymers, solvents, propellants, and conditioning agents that deposit a thin film onto keratin fibers to maintain shape, resist humidity, and provide thermal protection. The product functions as a finishing tool in professional styling workflows and daily consumer grooming routines. Flexible Hold products lead volume in mature North American and European markets where natural movement dominates aesthetic preferences, while Volumizing variants record the fastest trajectory in Asia-Pacific salons seeking root-lift performance. Online Retail channels capture expanding margin pools as direct-to-consumer subscriptions and algorithmic personalization reduce traditional wholesale dependency.
The FDA regulates cosmetic labeling and ingredient safety under the Federal Food, Drug, and Cosmetic Act, while the EPA governs volatile organic compound emissions from aerosol propellant systems. REACH compliance in the European Union restricts certain polymer chemistries and propellant categories, forcing reformulation investments. China's NMPA and GB standards mandate registration and safety testing for imported aerosol cosmetics. Stakeholders must monitor evolving propellant-phaseout timelines and biopolymer certification requirements to secure formulation continuity across regulatory jurisdictions.
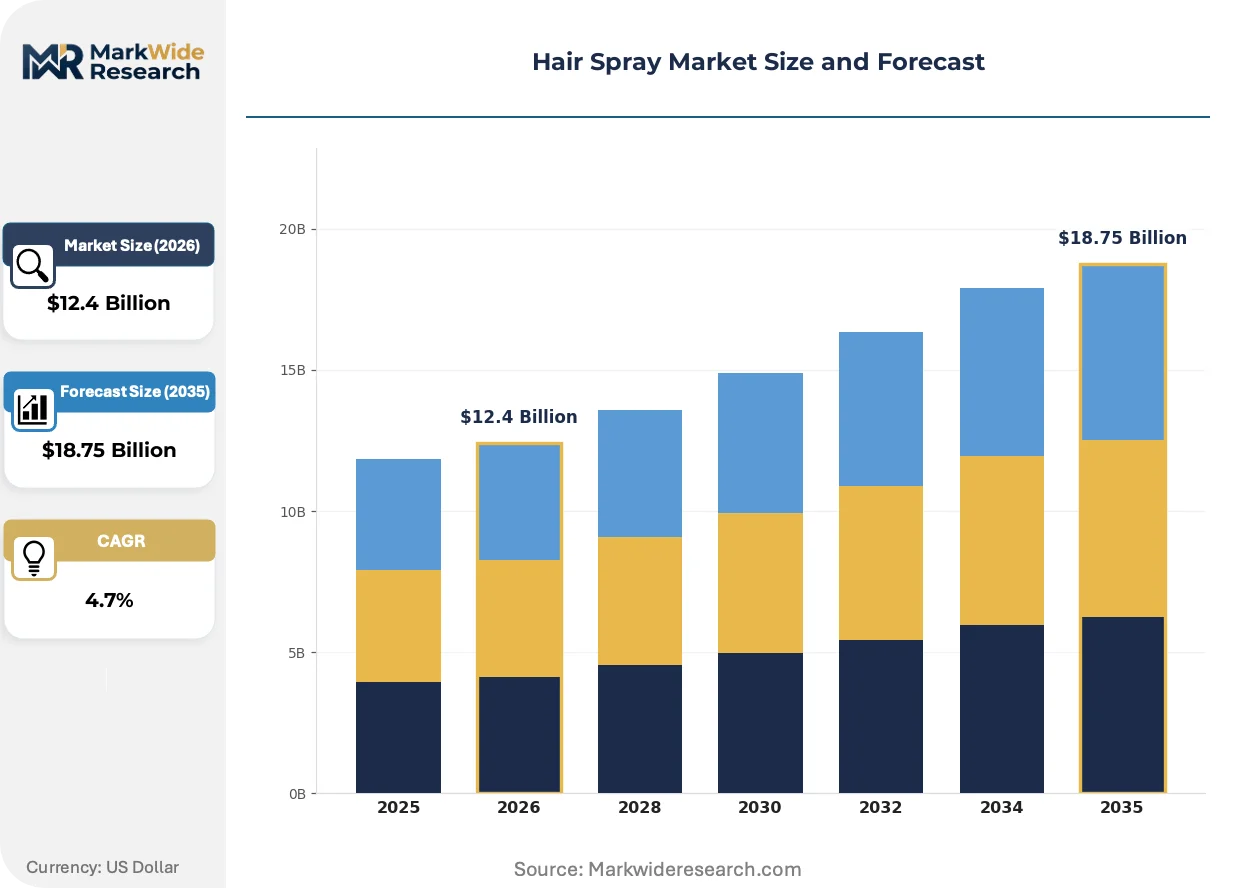
Market Dynamics
Professional salon networks are consolidating procurement power while formaldehyde-free polymer chemistry investments reshape formulation economics across aerosol and pump-dispensed categories.
Growth Catalysts
- REACH polymer restrictions:EU regulatory pressure on synthetic film-formers accelerates biopolymer R&D, opening premium positioning for certified-green formulations in German and French professional channels.
- Metropolitan salon clustering:Dense professional styling networks in Shanghai, New York, and São Paulo concentrate volume and drive specification-grade demand for humidity-resistant holds.
- Dimethyl ether propellant systems:Low-VOC alternatives to hydrocarbon propellants enable compliance with EPA emission thresholds while maintaining spray fineness.
Market Restraints
- Alcohol denat supply volatility:Grain-derived ethanol costs fluctuate with agricultural commodity cycles, squeezing margin on fast-dry formulations.
- Chinese aerosol canister concentration:Three domestic suppliers control 70% of compatible aluminum packaging, creating single-source risk for brands without captive filling arrangements.
- Technical ceiling on natural hold:Plant-derived polymers currently achieve 6-8 hour hold versus 12-16 for petrochemical alternatives, limiting premium pricing power in performance segments.
Strategic Opportunities
- Indian tier-2 city salon expansion:Underpenetrated professional channels in Pune, Jaipur, and Lucknow offer first-mover positioning before multinational distribution arrives.
- Dual carbon policy tailwinds:China's MEE incentives for low-carbon manufacturing processes subsidize retrofit costs for domestic aerosol filling lines.
- Connected packaging convergence:NFC-enabled cans linking to styling tutorial content create direct consumer relationships outside retail margin structures.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in aerosol thermodynamics and polymer-solvent compatibility commands premium compensation, constraining mid-tier brand innovation pipelines.
- Multi-jurisdiction registration timelines:Sequential NMPA, FDA, and REACH dossier requirements extend product launch windows by 18-24 months for global formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Spray Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Hold, Extra Hold, Strong Hold, Volumizing Application: Styling, Finishing, Texturizing, Protection Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Drugstores End User: Salons, Home Users, Professionals, Makeup Artists |
| Companies Covered | Henkel AG & Co. KGaA, Coty Inc., L'Oréal S.A., Amorepacific Corporation, Shiseido Company, Limited, The Procter & Gamble Company, Kao Corporation, Beiersdorf AG, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Spray Market Emerging Trajectories
Biopolymer substitution and propellant chemistry transitions are restructuring competitive advantage around regulatory anticipation rather than scale economics alone.
Microcrystalline cellulose derived from wood pulp is fragmenting hold-system architectures previously dominated by polyvinylpyrrolidone copolymers. Scandinavian salon chains and clean-beauty retailers in Copenhagen and Stockholm are specifying cellulose-based films for their private-label lines. This fragmentation compresses patent-protected polymer premiums while elevating formulation transparency as a purchase criterion.
EPA volatile organic compound limits for consumer products are tightening hydrocarbon propellant allowances in aerosol categories. Manufacturers serving the US market are qualifying dimethyl ether and compressed gas alternatives that sacrifice some dry-time performance for compliance certainty. Professional-grade lines face the steepest reformulation costs due to hold-performance requirements that consumer products can relax.
Subscription-direct replenishment models are displacing salon-centric bulk purchasing among independent stylists in North America and Western Europe. Algorithmic shade-matching and auto-replenishment apps reduce distributor dependency for color-adjacent styling products. This behavioral shift concentrates most visibly in Los Angeles and London, where chair-rental stylists operate without backbar supply contracts.
Hair Spray Market Segmentation
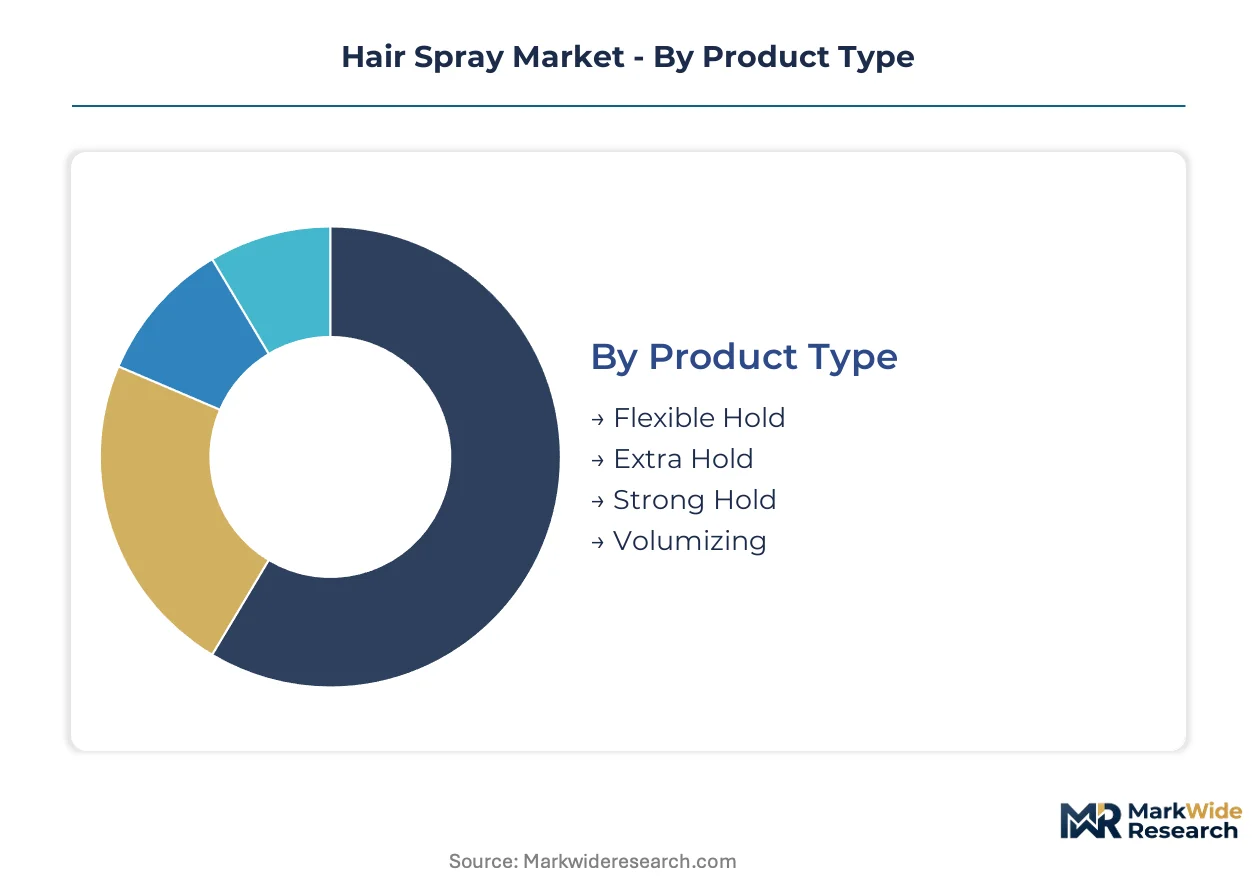
Hair spray segmentation reveals how formulation chemistry and channel economics fragment procurement patterns. Distinct user workflows demand specialized hold architectures, while regulatory pressure on aerosol systems forces category-specific reformulation investments.
Product Type:
Biopolymer substitution pressures vary sharply across hold intensities, with performance segments facing the steepest technical trade-offs between plant-derived chemistry and durability requirements.
- Flexible Hold:Low-viscosity polymer matrices deposit featherweight films that preserve natural fiber movement. Demand concentrates in Los Angeles and London salon networks where editorial styling workflows prioritize pliability over rigidity.
- Extra Hold:High-density acrylic copolymer systems create rigid film structures resistant to humidity penetration. German and French professional channels specify these formulations for bridal and event styling where environmental stability commands premium positioning.
- Strong Hold:Maximum-fixation resins deliver 12-16 hour shape retention under thermal stress. Petrochemical-derived architectures still dominate this segment despite REACH pressure on synthetic film-formers.
- Volumizing:Root-lift polymers with low surface tension enable gravity-defying architecture without stiffness penalties. Asia-Pacific salons in Shanghai and Seoul specify these for K-beauty influenced styling protocols.
Flexible Hold retains volume leadership; Volumizing holds the steepest expansion curve.
Application:
Margin concentration follows workflow position, with terminal-stage products capturing higher per-unit economics than preparatory formulations.
- Styling:Mid-hold polymers enable reshapeable architecture during active manipulation. Home users in the United States and China drive volume through daily grooming routines.
- Finishing:Ultra-fine mist systems deposit final film layers without disturbing underlying structure. Professional makeup artists specify these for red-carpet and photographic workflows where surface uniformity is non-negotiable.
- Texturizing:Salt-infused or starch-modified formulations create matte, tousled aesthetics. Independent stylists in São Paulo and Mexico City favor these for editorial-influenced salon services.
- Protection:Thermal-shield polymers with UV absorbers defend keratin integrity during heat-tool exposure. Premium positioning in Japanese and South Korean retail channels reflects ingredient-cost premiums.
Styling commands absolute volume; Protection expands most quickly as heat-tool penetration deepens.
Distribution Channel:
Channel selection determines margin capture efficiency, with direct-to-consumer models disrupting traditional wholesale dependency in developed markets.
- Supermarkets:Mass-market SKUs with standardized hold specifications serve price-sensitive home users. Shelf placement economics favor brands with existing personal-care brand equity.
- Online Retail:Algorithmic personalization and subscription replenishment reduce distributor margin extraction. Direct-to-consumer platforms concentrate in the United States and United Kingdom where chair-rental stylists operate without backbar contracts.
- Specialty Stores:Curated prestige assortments with fragrance-hybrid positioning command premium price points. Sephora and Douglas networks in France and Germany anchor this channel.
- Drugstores:Pharmacy-aligned distribution emphasizes dermatological safety claims and sensitive-skin positioning. CVS and Walgreens in the United States dominate this channel through convenience-driven purchasing.
Supermarkets retain volume leadership; Online Retail gains share fastest through subscription conversion.
End User:
Procurement authority consolidation in professional networks is shifting volume concentration away from dispersed home-user segments.
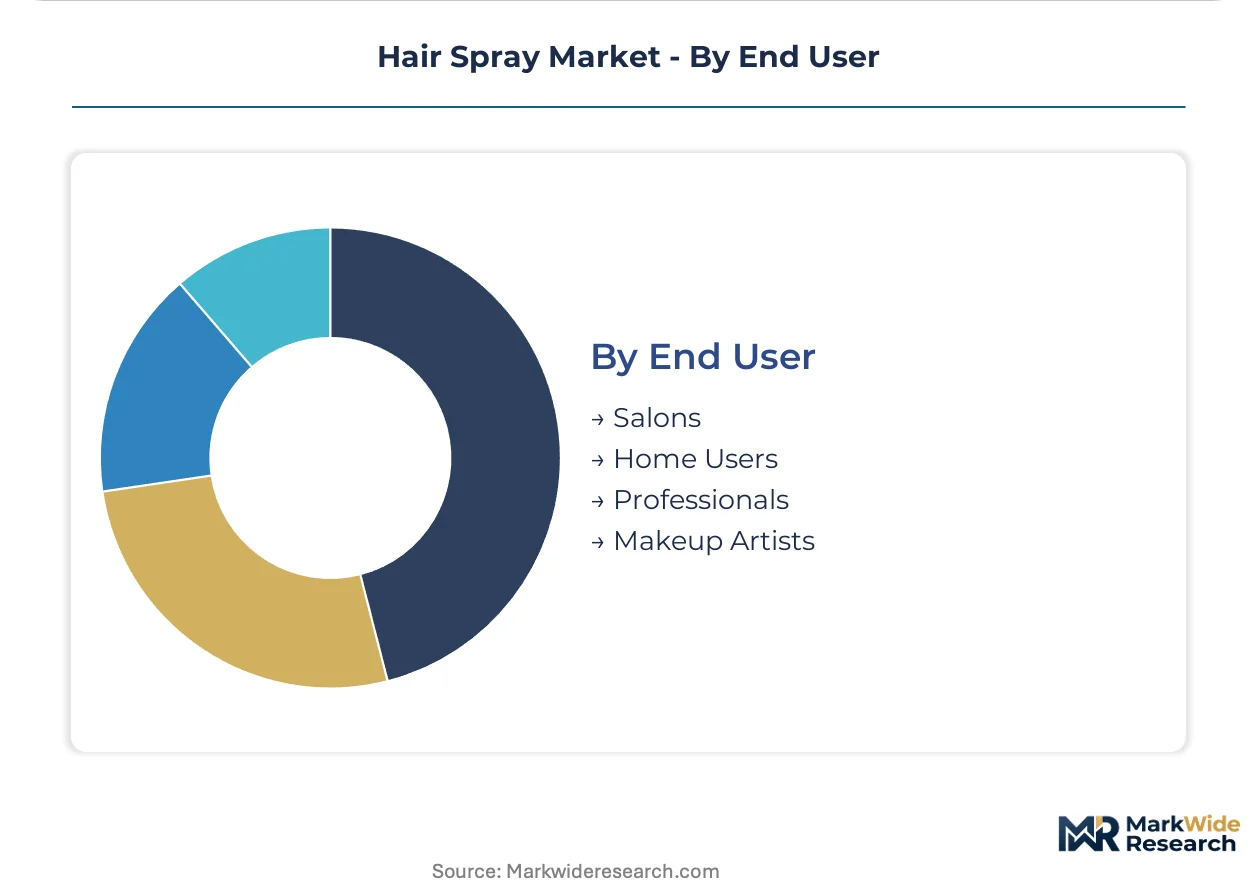
- Salons:Backbar purchasing through distributor networks specifies professional-grade formulations with bulk-fill economics. Metropolitan clustering in New York, Shanghai, and São Paulo concentrates demand.
- Home Users:Mass-market aerosol and pump formats serve daily grooming routines with convenience prioritization. E-commerce penetration is fragmenting traditional retail loyalty in the United States and Germany.
- Professionals:Freelance stylists and session artists demand travel-format packaging with consistent performance across climate zones. Kit-building behavior drives multi-SKU purchasing.
- Makeup Artists:Finishing-spray integration into cosmetic workflows demands invisible-film aesthetics compatible with photography lighting. Los Angeles and London content-production hubs anchor demand.
Salons retain volume leadership; Professionals climb the fastest as freelance styling networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aerosol manufacturers export professional-grade formulations to salon networks across France and the United Kingdom, establishing a westward trade corridor that channels REACH-compliant chemistry into Western European styling channels.
United States
Los Angeles and New York metropolitan clusters concentrate professional salon demand for flexible-hold formulations tailored to editorial styling workflows. EPA volatile organic compound thresholds are tightening hydrocarbon propellant allowances, forcing reformulation investments in aerosol lines. California's South Coast Air Quality Management District enforces the nation's strictest VOC limits, accelerating dimethyl ether adoption in Los Angeles-based manufacturing.
Germany
Professional backbar procurement in Hamburg and Berlin drives specification-grade demand for humidity-resistant extra-hold architectures. REACH restrictions on synthetic film-formers are accelerating biopolymer R&D investments among domestic formulators. The Rhine-Ruhr industrial corridor hosts specialized aerosol filling operations serving salon-distributor networks across Western Europe.
China
Shanghai and Beijing salon clusters are expanding volumizing product adoption under K-beauty influenced styling protocols. NMPA registration requirements and GB standards mandate safety testing for imported aerosol cosmetics, extending launch timelines for foreign brands. The Yangtze River Delta concentration of aluminum canister suppliers creates packaging leverage for domestic brands.
Japan
Tokyo and Osaka retail channels prioritize thermal-protection formulations with UV-absorbing polymers for heat-tool defense. METI guidelines on volatile organic compound labeling influence consumer-facing communication strategies. The Kanto region's specialty store networks anchor prestige fragrance-hybrid positioning for premium styling products.
Brazil
São Paulo's independent stylist networks favor texturizing formulations for editorial-influenced salon services. ANVISA cosmetic registration requirements govern aerosol safety standards for imported products. The metropolitan salon clustering in Rio de Janeiro and São Paulo concentrates volume demand for humidity-resistant hold systems.
Hair Spray Market Vendor Landscape
Player mix skews toward diversified personal-care conglomerates with captive salon-distribution infrastructure, creating tiered competition between mass-market scale operators and prestige-positioned specialists. Strategic archetypes separate into professional-channel anchors leveraging backbar relationships, direct-to-consumer platforms exploiting subscription mechanics, and clean-beauty specialists commanding transparency premiums. Dominant competitive moves include biopolymer certification investments to secure formulation continuity and connected packaging development to bypass retail margin extraction.
Within the professional-channel tier, L'Oréal S.A. and Henkel AG & Co. KGaA exemplify archetypes anchored in salon-distribution density, while Coty Inc. occupies a prestige-positioned niche. Amorepacific Corporation and Shiseido Company, Limited represent Asia-Pacific origin conglomerates with regional formulation expertise. The Procter & Gamble Company and Unilever PLC sit within mass-market scale tiers leveraging personal-care brand equity for shelf placement economics.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Coty Inc. |
| L'Oréal S.A. |
| Amorepacific Corporation |
| Shiseido Company, Limited |
| The Procter & Gamble Company |
| Kao Corporation |
| Beiersdorf AG |
| Unilever PLC |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Chinese aluminum canister facilities directly shapes both supply concentration and price floors for aerosol packaging, with three domestic suppliers controlling compatible metal forming and thereby anchoring minimum viable economics for brands without captive filling arrangements.
Pricing Analysis
Petrochemical-derived versus biopolymer-derived versus next-generation cellulose-based formulations stratify across three performance tiers. Three-tier pricing structure across premium certified-green, standard synthetic, and economy mass-market levels separates salon-grade specifications from retail convenience SKUs. Price differentiation hinges on REACH compliance certification and volume scale in backbar procurement. Cost compression in economy tiers is intensifying because grain-derived ethanol feedstock volatility squeezes fast-dry formulation margins. Home users in mass-market channels exhibit highest price sensitivity; professional salons demonstrate lowest sensitivity due to specification-grade workflow requirements.
Supply Chain Analysis
Yangtze River Delta canister manufacturing concentration creates single-source vulnerability for brands dependent on Chinese aluminum packaging without redundant qualification. China, Germany, and the United States anchor global supply for aerosol filling equipment and polymer chemistry respectively. Raw material dependencies center on dimethyl ether propellant systems, microcrystalline cellulose biopolymers, and acrylic copolymer resins. Tariff exposure on aluminum sheet metal imports threatens margin stability for European formulators. Distribution runs through salon-distributor networks in developed markets and direct-to-consumer platforms in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, EPA, and NMPA jurisdictions fragments competitive terrain into certification-specific niches, creating entry points for specialists who can navigate sequential registration timelines faster than scale incumbents.
For Market Incumbents: Fortify professional-channel relationships through exclusive backbar supply contracts before subscription-direct models displace distributor networks. Deepen captive aerosol filling capacity in the Rhine-Ruhr corridor to offset Chinese canister concentration risk. Biopolymer R&D investment represents the critical lever for maintaining formulation continuity under REACH polymer restrictions. For New Entrants and Emerging Players: Algorithmic personalization services for independent chair-rental stylists expose a service-layer gap where L'Oréal and Henkel under-serve digitally native professionals. Target tier-2 Indian city salons in Pune and Jaipur before multinational distribution arrives. Pursue clean-beauty certification positioning in Scandinavian retail channels as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biopolymer specialists with qualified cellulose-based film formers over legacy petrochemical polymer portfolios. Five-to-ten year viability hinges on regulatory anticipation capabilities rather than scale alone. Acquisition targets should demonstrate completed REACH dossier submissions and NMPA registration track records. Monitor EPA VOC threshold tightening timelines as the primary inflection indicator for propellant chemistry transition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Certification Investment | REACH-compliant cellulose-based formulations secure German and French professional channel access. |
| Connected Packaging Development | NFC-enabled cans linking to styling tutorials bypass Sephora and Douglas retail margin extraction. |
| Dimethyl Ether Propellant Transition | EPA VOC compliance in California manufacturing enables continued Los Angeles salon market presence. |
| Indian Tier-2 Salon Distribution Buildout | First-mover positioning in Pune and Jaipur precedes multinational network saturation. |
| Subscription-Direct Platform Launch | Algorithmic replenishment for London and Los Angeles chair-rental stylists displaces wholesale dependency. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with salon owners, professional stylists, aerosol formulation chemists, and cosmetic regulatory affairs specialists; and secondary validation through REACH registration databases, EPA VOC compliance filings, NMPA cosmetic safety submissions, and customs trade records for aluminum canister imports. Bottom-up volume estimates from salon network procurement patterns were triangulated against top-down category spending data from retail audit providers.
Across the projection horizon, the analytical framework modeled segmentation dimensions including hold intensity tier, application workflow position, distribution channel format, and end-user procurement authority. CAGRs were derived from trend extrapolation adjusted for regulatory phaseout timelines and technology substitution curves. Forecast inputs incorporated propellant chemistry transition costs and biopolymer performance ceiling constraints.
Forecasts assume regulatory continuity in REACH, EPA, and NMPA regimes; material policy shifts would require re-modeling polymer chemistry availability and registration timeline assumptions. Practitioners should keep alternative scenarios live as dual carbon policy incentives and aerosol canister supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Canada Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Rice Water Shampoo Market
Hair Care
Qatar Hair Care Market
Hair Care
South Africa Hair Care Market
Hair Care
Mexico Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
United States Hair Care Market
Hair Care
Argentina Hair Care Market
Hair Care
Global Premium Hair Care Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Relaxer Market
Hair Care
Global Professional Hair Care Market
Hair Care
Japan Hair Care Market
Hair Care
North America Hair Care Market