
 Organic Hair Care Market | 2026-2036
Organic Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Hair Care Market Outlook
REACH is decoupling conventional cosmetic chemistry from the organic hair care cost structure, compelling manufacturers to replace synthetic preservatives with plant-derived alternatives. Aveda anchors its market position through captive sourcing of botanical ingredients from certified organic farms. Estée Lauder leverages its prestige distribution network to sustain premium pricing across specialty retail channels.
Organic hair care comprises formulations that exclude synthetic pesticides, petrochemicals, and genetically modified organisms, relying instead on botanical extracts, essential oils, and plant proteins that retain functional efficacy through cold-press or steam-distillation processing. Shampoo and conditioner segments dominate current volume, while treatment products capture disproportionate margin pools due to concentrated active formulations and higher per-unit price realization. Specialty stores and online retail channels are expanding fastest, though supermarkets still control mass-market access for mainstream organic lines.
EMA cosmetic ingredient guidelines, USDA organic certification thresholds, and BIS standards for ayurvedic-derived products collectively determine market access and label credibility across major producing regions. These frameworks create compliance moats that favor scaled manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving preservative approval lists and bioprospecting disclosure rules to anticipate the next wave of formulation constraints.
Market Dynamics
REACH chemical footprint disclosure mandates are forcing wholesale reformulation across the value chain, decoupling conventional cosmetic chemistry from organic hair care economics and compelling manufacturers to rebuild supply networks around plant-derived alternatives.
Growth Catalysts
- EU Green Deal chemical mandates:Disclosure requirements are accelerating replacement of synthetic preservatives with botanical alternatives, creating competitive advantage for early reformulators.
- Professional salon channel expansion:Premium organic formulations are absorbing volume at pace as stylists seek differentiation through clean-label positioning.
- Germany:Demand gravity concentrates here alongside France and the United Kingdom, anchoring European volume pools for certified organic lines.
Market Restraints
- Certified organic farm supply concentration:Captive sourcing of botanical ingredients limits formulation flexibility and creates input dependency on specific agricultural geographies.
- Cold-press processing cost premiums:Steam-distillation and cold-press methods retain functional efficacy but compress margins versus conventional chemical synthesis.
- USDA organic certification thresholds:Stringent label requirements create compliance moats that disadvantage smaller manufacturers lacking dedicated regulatory affairs capabilities.
Strategic Opportunities
- Online retail channel expansion:E-commerce platforms are capturing fastest-growing distribution share for organic hair care, bypassing traditional supermarket gatekeepers.
- Treatment product segment:Concentrated active formulations command disproportionate margin pools through higher per-unit price realization versus commoditized shampoo volumes.
- BIS ayurvedic standards:Emerging regulatory frameworks for plant-derived products create label credibility pathways for botanical ingredient suppliers.
Industry Challenges
- Preservative approval list volatility:EMA cosmetic ingredient guidelines evolve unpredictably, forcing continuous reformulation cycles and inventory write-offs.
- Bioprospecting disclosure compliance:New rules require traceability documentation that strains legacy supply chain information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Hair Care Market |
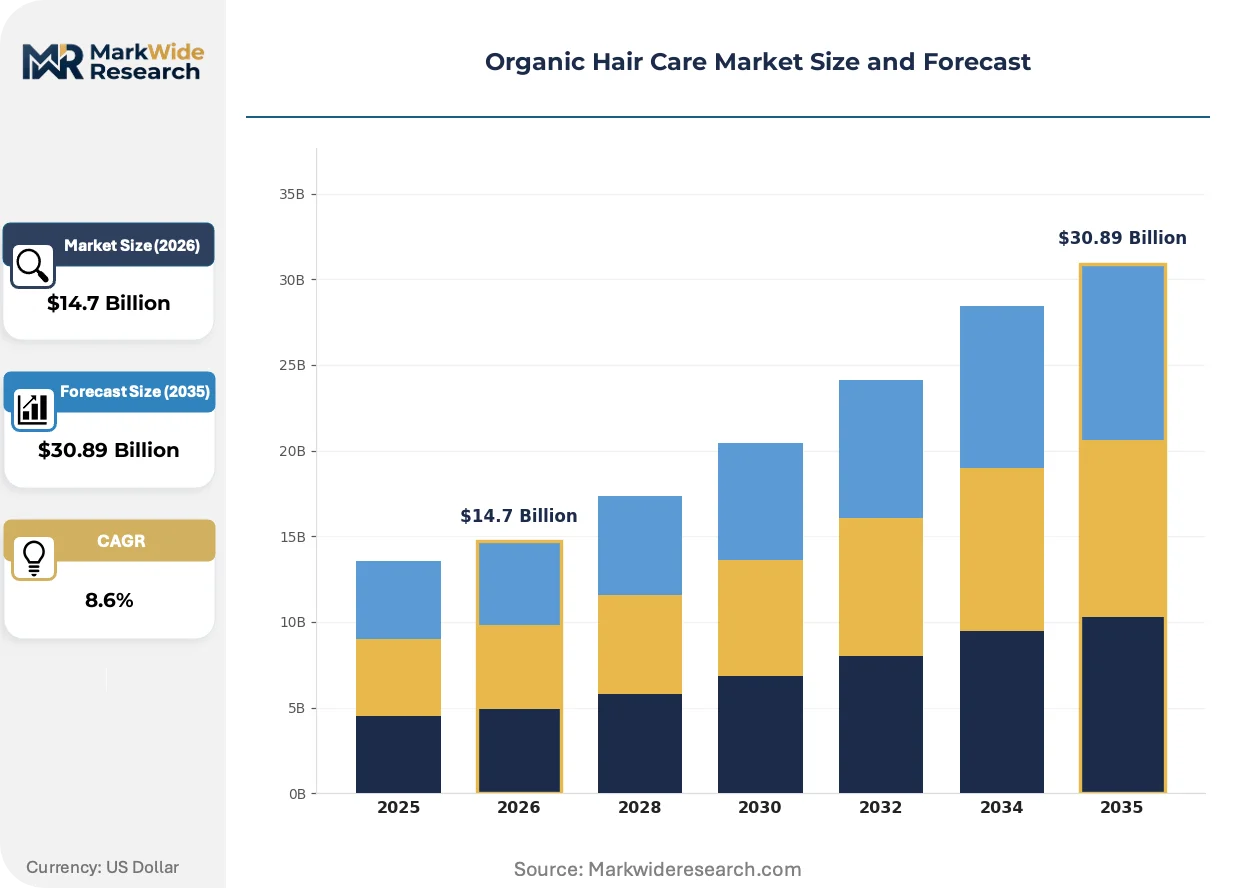
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Treatment Ingredient Type: Botanical Extracts, Essential Oils, Vitamins, Plant Proteins End User: Women, Men, Children, Salons Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Estée Lauder, Aveda, P&G, Giovanni Cosmetics, Colgate-Palmolive, Hindustan Unilever, Kao, Juicy Chemistry, The Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Hair Care Market Strategic Shifts
Formulation science is pivoting toward biotechnology-derived actives, regulatory disclosure frameworks are hardening around chemical provenance, and professional channel buying patterns are compressing traditional distribution hierarchies.
Biotechnology-derived plant proteins are rewriting functional efficacy standards in organic hair care. Professional salons are adopting these actives fastest as they seek performance parity with conventional chemistry. The technology is rewriting how manufacturers balance clean-label positioning with treatment efficacy claims.
REACH chemical footprint mandates are forcing ingredient-level transparency across European supply chains. Manufacturers must now document synthetic substance volumes from raw material through finished product. Treatment products face the steepest compliance burden due to concentrated active loads.
Certification-driven buying is displacing brand loyalty in specialty retail channels. Consumers now lead with USDA organic, EMA cosmetic, or BIS ayurvedic credentials rather than heritage brand names. Germany exhibits this pattern most acutely, where label credibility determines shelf placement.
Organic Hair Care Market Segmentation
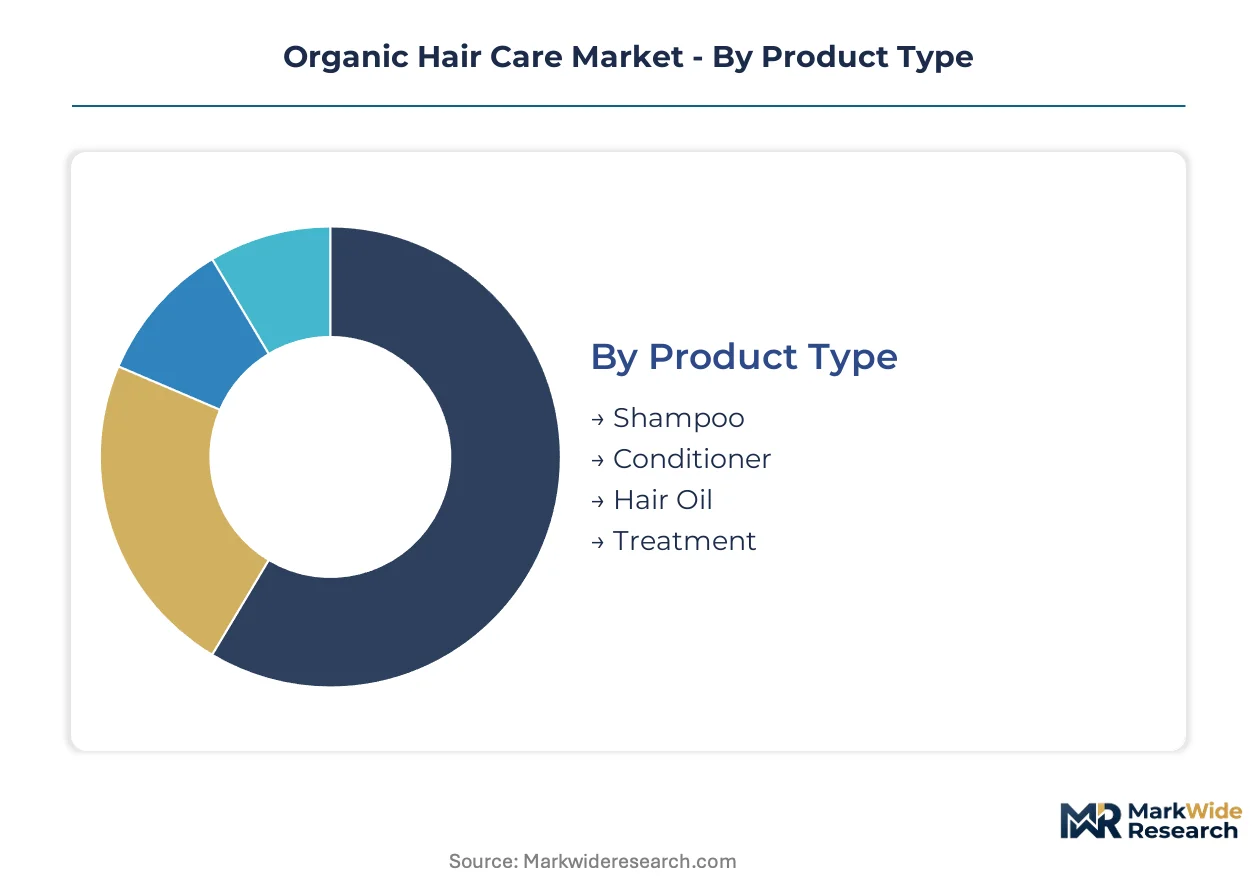
Organic hair care segmentation reveals how formulation complexity, channel access, and end-user sophistication create distinct margin architectures. Each category partitions the market into addressable pockets where regulatory compliance and sourcing strategy determine competitive viability.
Product Type:
Customization intensity varies sharply across this category, from mass-produced daily-use formats to precision-engineered treatment protocols demanding bespoke active loading.
- Shampoo:Water-based surfactant systems incorporating cold-pressed botanical cleansers that exclude sulfates and synthetic foaming agents. Volume concentrates in Germany and France where EU Green Deal disclosure mandates favor transparent ingredient sourcing over conventional chemical alternatives.
- Conditioner:Emulsion-based formulations leveraging plant-derived fatty alcohols and cationic polymers for cuticle sealing without silicones. Demand clusters in professional salon channels across the United Kingdom as stylists seek performance parity with conventional chemistry through clean-label positioning.
- Hair Oil:Lipid-dense anhydrous preparations using steam-distilled carrier oils for scalp nourishment and thermal protection.
- Treatment:Concentrated active serums and masks with elevated botanical extract loads targeting specific hair damage mechanisms.
Leading the category by volume: Shampoo. Growing fastest: Treatment.
Ingredient Type:
Cost tier separation drives this category, from commodity-grade plant derivatives to premium extracts commanding formulation premiums through certified organic provenance.
- Botanical Extracts:Water-soluble or ethanol-extracted phytochemical concentrates including aloe vera, chamomile, and nettle for scalp soothing and antioxidant protection. Supply concentrates on certified organic farms in France and Germany where REACH decoupling from conventional chemistry has accelerated captive sourcing investments.
- Essential Oils:Steam-distilled volatile aromatic compounds from lavender, rosemary, and tea tree providing antimicrobial and sensory properties. Procurement is shifting toward traceable bioprospecting documentation to satisfy emerging disclosure rules in European supply chains.
- Vitamins:Bioavailable forms of B-complex, vitamin E, and vitamin C incorporated for follicular health and oxidative stress reduction.
- Plant Proteins:Hydrolyzed wheat, soy, and quinoa fractions delivering film-forming and strengthening functionality comparable to synthetic polymers.
Capturing dominant margin share: Botanical Extracts. Expanding most quickly: Plant Proteins.
End User:
Application context separates this category, from individual household consumption to professional service environments with divergent performance expectations and purchase authorization structures.
- Women:Primary household purchasers across all product formats with elevated sensitivity to certification credentials and ingredient transparency. Certification-driven buying displaces brand loyalty most acutely in Germany where label credibility determines shelf placement in specialty retail channels.
- Men:Emerging segment concentrated in simplified multi-functional formats addressing scalp health and styling efficiency.
- Children:Formulations with minimized essential oil concentrations and hypoallergenic positioning for sensitive scalp conditions.
- Salons:Professional-grade volumes with concentrated active loads and back-bar sizing for service protocol integration.
Highest absolute spend: Women. Steepest expansion trajectory: Salons.
Distribution Channel:
Customer type and purchase journey complexity partition this category, from discovery-driven online environments to replenishment-oriented physical retail with distinct margin and working capital requirements.
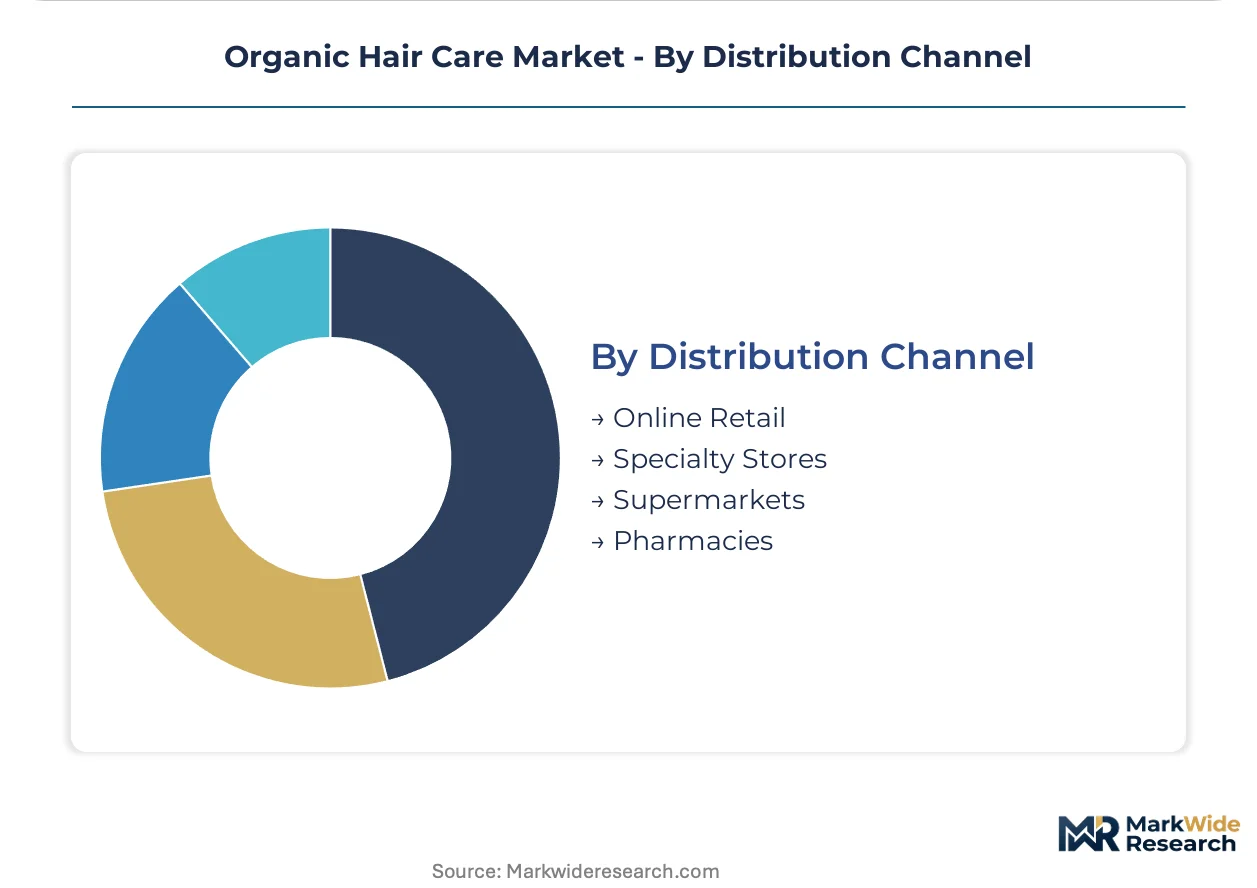
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing fastest-growing distribution share through subscription models and educational content. E-commerce expansion is bypassing traditional supermarket gatekeepers for mainstream organic lines across France and the United Kingdom.
- Specialty Stores:Curated beauty retailers and natural product boutiques where trained staff guide certification-driven purchase decisions. Germany exhibits this pattern most acutely with USDA organic and EMA cosmetic credentials leading over heritage brand names.
- Supermarkets:Mass-market access points controlling volume for mainstream organic lines with price-competitive positioning.
- Pharmacies:Clinical credibility channels emphasizing dermatologically tested formulations for sensitive scalp conditions.
Controlling mass-market volume: Supermarkets. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax-advantaged organic farming zones in southern France and certified cultivation corridors near Hamburg concentrate botanical ingredient supply for European formulators. REACH disclosure mandates and EU Green Deal chemical footprint rules are redrawing competitive maps across major demand centers.
Germany
Professional salon channels absorb premium organic formulations at pace across Berlin and Munich metropolitan clusters. ECHA chemical footprint disclosure mandates force continuous reformulation investments from manufacturers serving this market. Hamburg anchors northern supply concentration with cold-press processing facilities clustered near certified organic farm networks.
France
Specialty retail channels in Paris and Lyon exhibit certification-driven buying patterns that displace heritage brand loyalty. ANSM cosmetic ingredient guidelines create compliance moats favoring scaled manufacturers with dedicated regulatory affairs capabilities. Provence-Alpes-Côte d'Azur concentrates lavender and rosemary essential oil distillation for shampoo and treatment formulations.
United Kingdom
Stylists in London and Manchester seek performance parity with conventional chemistry through clean-label positioning in salon back-bar procurement. Post-Brexit regulatory divergence from EU cosmetic frameworks creates dual compliance burdens for cross-channel suppliers. Online retail expansion bypasses traditional supermarket gatekeepers for mainstream organic lines.
United States
USDA organic certification thresholds determine label credibility in specialty beauty retail across New York and Los Angeles. FDA cosmetic oversight focuses on safety substantiation rather than organic claim verification, creating enforcement gaps. Pacific Northwest clusters cold-press botanical processing near certified organic farm supply in Oregon and Washington.
India
BIS ayurvedic standards for plant-derived products create label credibility pathways for botanical ingredient suppliers serving Mumbai and Bangalore. FSSAI cosmetic safety requirements overlap with traditional medicine frameworks for hair oil and treatment formulations. Maharashtra concentrates contract manufacturing capacity for export-oriented organic hair care lines.
Organic Hair Care Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures concentrate among scaled manufacturers with captive sourcing networks and dedicated regulatory affairs capabilities. Three archetypes dominate: prestige beauty houses with prestige distribution infrastructure, natural-product pure-plays with certified organic supply chains, and mass-market consumer goods conglomerates with supermarket channel control. Competitive moves center on M&A for botanical ingredient access and strategic partnerships for cold-press processing capacity.
Within the prestige beauty tier, Estée Lauder and Aveda occupy positions anchored by premium distribution networks and captive organic farm sourcing. Among mass-market conglomerates, P&G and Hindustan Unilever exemplify scale-driven players leveraging supermarket channel control for mainstream organic line placement. Juicy Chemistry represents the emerging pure-play specialist archetype with concentrated focus on certified organic formulation and direct-to-consumer channel development.
| Leading Market Players |
|---|
| Estée Lauder |
| Aveda |
| P&G |
| Giovanni Cosmetics |
| Colgate-Palmolive |
| Hindustan Unilever |
| Kao |
| Juicy Chemistry |
| The Hain Celestial Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal chemical footprint disclosure mandates gate qualified supply and premium-tier pricing access by forcing manufacturers to rebuild formulation networks around certified organic botanical inputs. Cold-press processing cost premiums compress margins versus conventional chemistry, creating tiered pricing stratification that separates USDA-certified organic lines from transitional natural-positioned alternatives.
Pricing Analysis
Lead-time-driven pricing stratification rewards short lead times with premium realization while spot inventory clears at discounted rates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and captive sourcing depth, with EMA cosmetic credential tiers commanding formulation premiums. Pricing pressure stems from cold-press processing energy intensity and certified organic farm supply bottlenecks. Mass-market supermarket buyers exhibit highest price sensitivity, while professional salon channels absorb premium positioning with lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Hamburg, Paris, and London anchor hub-and-spoke patterns for finished goods fulfillment. Botanical ingredient supply concentrates in France, Germany, and India, drawing from certified organic lavender fields in Provence, cold-press processing clusters near Hamburg, and ayurvedic herb cultivation in Maharashtra. Raw material dependencies include steam-distilled essential oils, cold-pressed carrier oils, and hydrolyzed plant proteins. Single-source vulnerability in certified organic farm networks creates supply chain risk. Distribution runs through professional salon back-bar channels and specialty retail for premium tiers, with e-commerce platforms capturing fastest-growing downstream share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology-derived plant proteins are displacing conventional functional chemistry, creating a technology-transition phase where reformulation capability determines competitive survival. Stakeholders must position around this pivot to capture value from clean-label efficacy convergence.
For Market Incumbents: Deepen captive sourcing investments in certified organic farm networks to defend against supply concentration risk from REACH-driven botanical substitution. Secure cold-press processing capacity additions in Hamburg and Provence corridors. Build dedicated regulatory affairs capabilities to navigate EMA preservative approval list volatility.
For New Entrants and Emerging Players: BIS ayurvedic standards in India open a window for plant-derived treatment formulations targeting export-oriented premium channels. White-space concentrates in men's multi-functional formats and children's hypoallergenic positioning. Direct-to-consumer subscription models bypass supermarket gatekeeper control.
For Investors and Strategic Acquirers: Consolidation among scaled manufacturers with captive sourcing networks is the leading indicator that regulatory compliance moats are hardening around organic certification infrastructure. Acquisition targets should exhibit backward integration into certified organic cultivation and dedicated EMA regulatory capabilities. Monitor professional salon channel procurement shifts as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Organic Farm Sourcing | Secures REACH-compliant botanical supply chains in France and Germany. |
| Cold-Press Processing Scale-Up | Retains functional efficacy for treatment products under EU Green Deal mandates. |
| Professional Salon Channel Expansion | Captures premium pricing through clean-label positioning in Berlin and Munich clusters. |
| Direct-to-Consumer Platform Launch | Bypasses supermarket gatekeepers for mainstream organic lines in United Kingdom. |
| Biotechnology-Derived Actives R&D | Rewrites efficacy standards for performance parity with conventional chemistry. |
Study Parameters
Multi-period observation of certified organic farm supply expansion, professional salon procurement patterns, and EMA regulatory disclosure timelines anchored the trend analysis, supplemented by interviews with formulation scientists, regulatory affairs directors at scaled manufacturers, professional salon owners, specialty retail category buyers, and certified organic farm operators. Secondary validation drew from REACH substance registration databases, USDA organic certification records, BIS ayurvedic product standards, customs trade flows for botanical extracts, and EU Green Deal implementation guidance. Bottom-up volume modeling triangulated against top-down market sizing across product type, ingredient category, end-user segment, and distribution channel dimensions.
Input-output matrix framing connected raw material availability constraints to finished goods pricing realization through segmented elasticity modeling. CAGRs derived from fitted growth curves across shampoo, conditioner, hair oil, and treatment product lines, with biotechnology-derived actives penetration, professional channel absorption rates, and online retail share expansion as key forecast inputs. Segmentation dimensions spanned formulation complexity, certification tier, channel access mode, and end-user sophistication.
The model assumes a particular technology adoption path for biotechnology-derived plant proteins; alternative pathways for synthetic biology fermentation would alter the outlook for cold-press processing economics. Forecasts reflect documented assumptions around regulatory enforcement intensity and certified organic farm supply expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Middle East and Africa Hair Care Market
Hair Care
China Hair Care Products Market
Hair Care
Japan Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Australia Hair Care Market
Hair Care
Sweden Hair Care Market
Hair Care
Israel Hair Care Market
Hair Care
Hair Tonic Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Italy Hair Care Market
Hair Care
Hair Clay Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Australia Hair Removal Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Anti-Pollution Hair Care Market