
 Germany Hair Care Market | 2026-2036
Germany Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Hair Care Market Foresight
Buyer fragmentation across e-commerce platforms and specialty retailers is repositioning how brands allocate marketing spend and inventory. Henkel AG & Co. KGaA leverages its German manufacturing base to sustain proximity advantages with domestic distributors. L'Oreal SA competes through technology leadership in salon-grade formulations. Beiersdorf AG anchors its position with dermatologically tested product lines favored by pharmacy channels.
Germany hair care encompasses formulations designed to cleanse, condition, protect, or style human hair, typically comprising surfactant bases, emollients, active ingredients, and preservatives at pH ranges of 4.5 to 5.5 to maintain cuticle integrity. These products serve both cosmetic enhancement and scalp health functions across professional and at-home usage contexts. Shampoo and conditioner remain the volume core, though margin pools concentrate in hair serum and hair mask segments where ingredient premiums command higher unit economics. Application-based segmentation shows damage repair and scalp care categories outpacing legacy positioning, reflecting consumer prioritization of hair wellness over superficial styling.
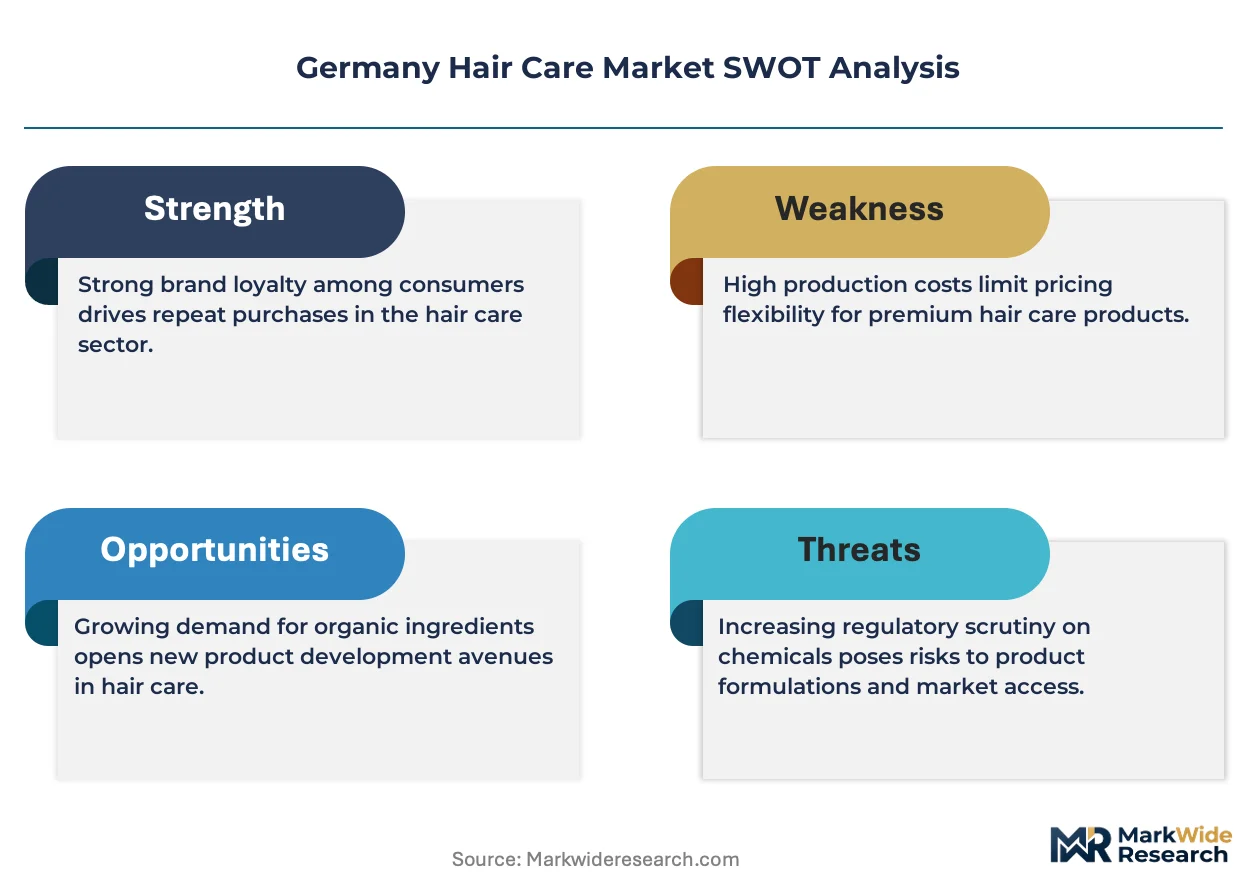
REACH registration requirements and the EU Green Deal sustainability mandates shape formulation chemistry, packaging material choices, and supply chain transparency obligations for manufacturers operating within Germany. KBA and German state-level environmental agencies enforce additional waste-reduction targets specific to cosmetic product distribution. Stakeholders must monitor evolving chemical restriction lists and circular economy implementation timelines to preempt compliance costs and secure market access.
Market Dynamics
REACH chemical safety standards and the EU Green Deal are forcing German manufacturers to reformulate entire product portfolios, reshaping competitive advantage around supply chain transparency and biodegradability credentials rather than brand heritage alone.
Growth Catalysts
- Salon professional expansion:German hairdressing salons are adding premium scalp treatment services, creating pull-through demand for professional-grade home maintenance products.
- REACH compliance as quality signal:Registration requirements under ECHA are filtering out low-cost imports, protecting domestic manufacturers with established chemical safety documentation.
- Metropolitan cluster concentration:Berlin, Munich, and Hamburg generate disproportionate volume through dense pharmacy and specialty retail networks.
Market Restraints
- Surfactant input volatility:Coconut-derived and petrochemical surfactant prices fluctuate with agricultural yields and crude oil benchmarks, compressing margin predictability for mass-market shampoos.
- Single-source packaging dependencies:German manufacturers rely on concentrated European suppliers for recycled PET and aluminum, creating vulnerability to regional energy cost spikes.
- Preservative restriction tightening:ECHA's evolving candidate list for endocrine disruptors is eliminating established preservation systems faster than alternatives achieve stability validation.
Strategic Opportunities
- Scalp microbiome science:Prebiotic and postbiotic active ingredients represent underdeveloped white space between cosmetic and dermatological positioning.
- Refill infrastructure buildout:KBA waste-reduction targets incentivize brands to deploy in-store refill stations, locking in retailer exclusivity and repeat purchase patterns.
- Pharmacy channel premiumization:German pharmacy chains seek differentiated hair wellness ranges to offset generic shampoo commoditization.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with combined expertise in biodegradability testing and sensory performance optimization command premium compensation.
- Dual certification timelines:Products claiming both dermatological testing and organic certification must navigate parallel review processes with divergent documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Hair Care Market |
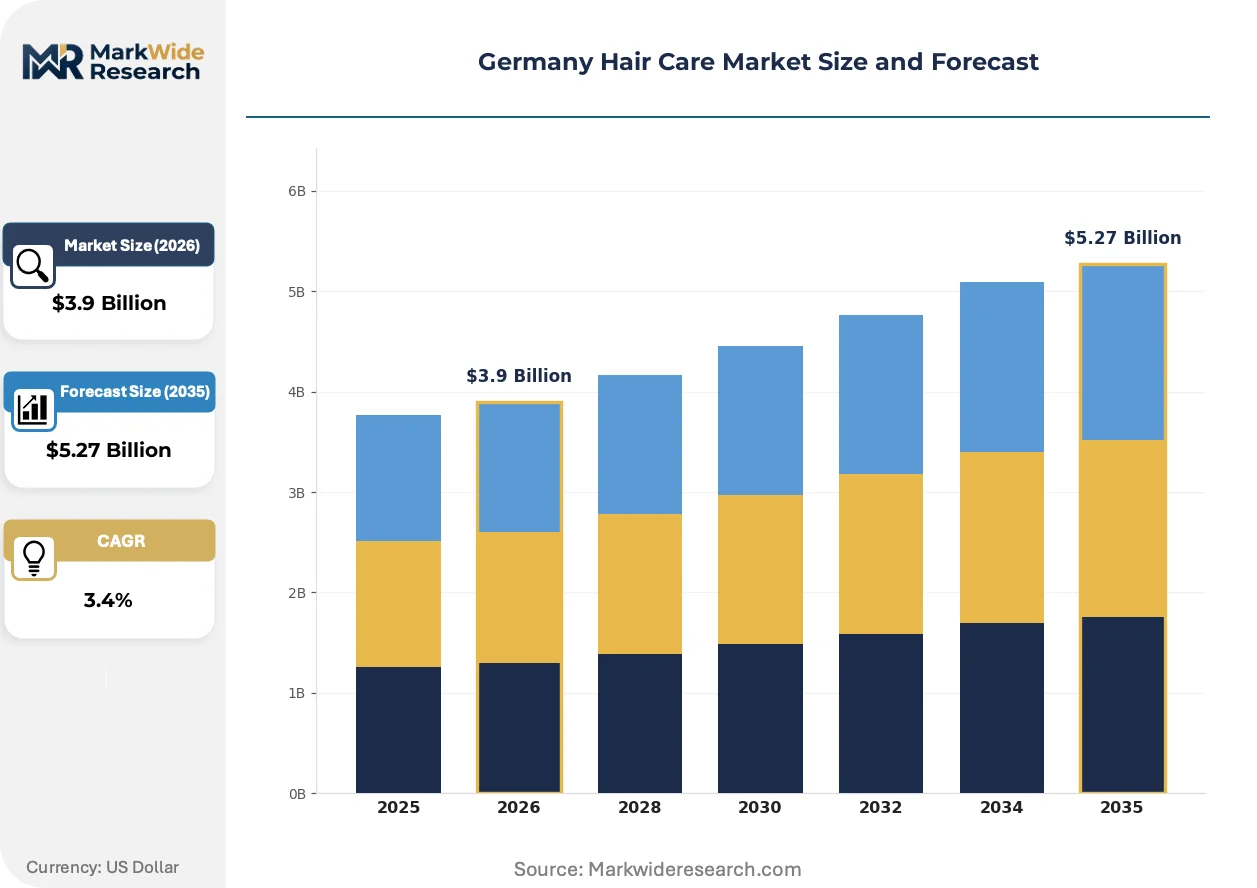
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Hair Serum, Hair Mask, Styling Products Hair Type: Curly, Straight, Wavy, Coily, Textured Application: Dandruff Control, Hair Growth, Damage Repair, Scalp Care, Color Protection, Volume Enhancement Customer Type: Salon Professionals, Individual Consumers, E-commerce Buyers, Specialty Store Shoppers, Drugstore Customers |
| Companies Covered | Procter & Gamble Co., Coty INC., Henkel AG & Co. KGaA, The Estee Lauder Companies, Shiseido Company Ltd, L'Oreal SA, Unilever PLC, Oriflame Group, Beiersdorf AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Hair Care Market Shifts & Advancements
Bioactive ingredient delivery systems and circular packaging models are displacing conventional formulation and distribution approaches, with regulatory pressure accelerating adoption timelines beyond typical consumer goods cycles.
Encapsulation technology for time-release active ingredients is integrating into salon-grade treatment products, enabling professional stylists in Hamburg and Munich to offer extended-benefit services that bridge appointment intervals. German manufacturers with in-house encapsulation capabilities are capturing margin premiums previously retained by ingredient suppliers.
REACH authorization procedures for novel preservatives are extending development timelines for brands seeking to replace restricted biocides, forcing smaller German formulators to license proven alternatives rather than innovate independently. This regulatory friction favors established players with dedicated regulatory affairs teams.
Consumer purchasing through pharmacy loyalty apps is fragmenting traditional brand discovery pathways, with Berlin shoppers increasingly selecting products based on algorithmic skin-type matching rather than shelf visibility. This behavioral shift compels brands to invest in first-party data infrastructure and pharmacist education programs.
Germany Hair Care Market Segmentation
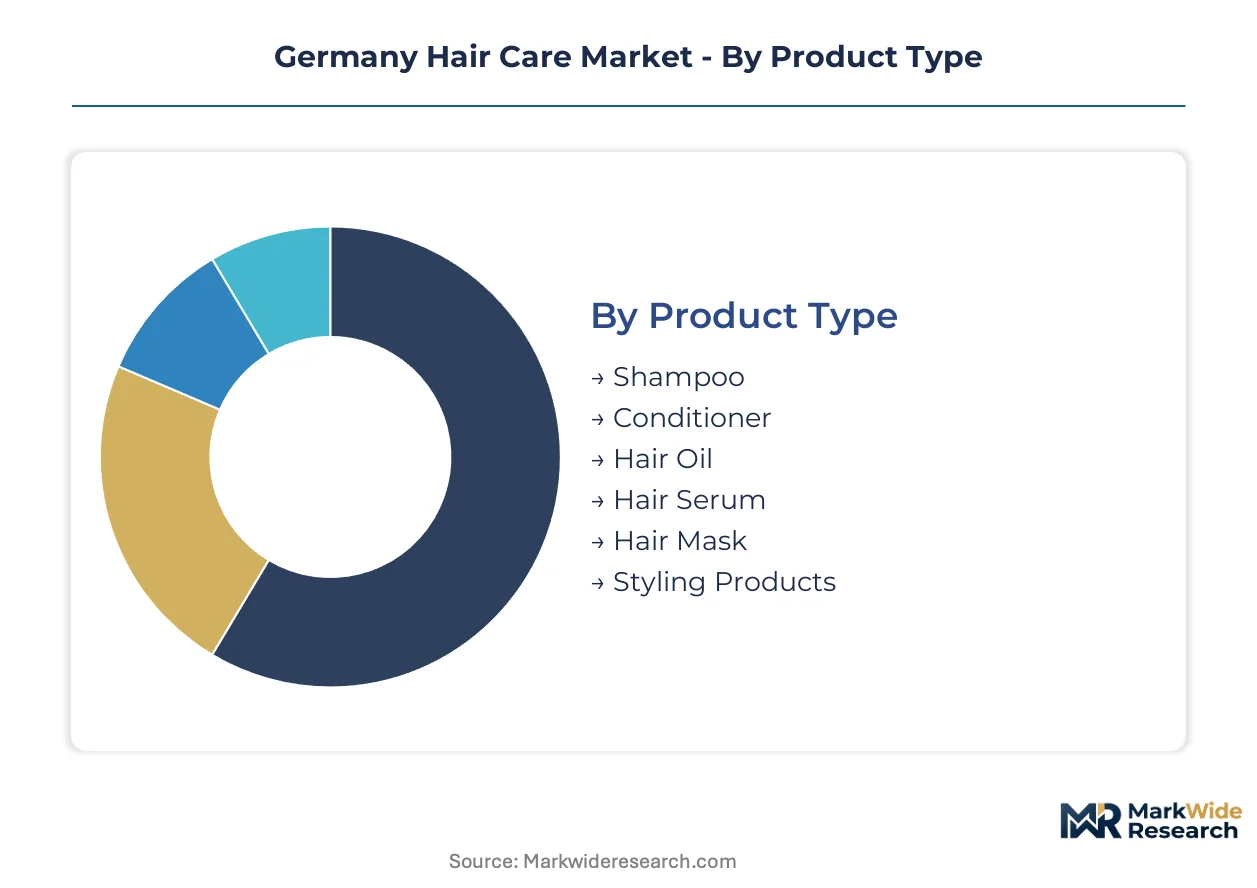
German hair care manufacturers align production capacity with distinct usage occasions and channel requirements rather than pursuing uniform distribution. Segment-specific formulation investments determine margin sustainability across REACH-regulated supply chains.
Product Type:
Supply concentration in surfactant manufacturing favors brands with captive production of cleansing bases over contract-dependent competitors.
- Shampoo:Surfactant-based cleansing formulations at pH 4.5-5.5 maintain cuticle integrity through mild anionic and amphoteric systems. Mass-market volumes concentrate in drugstore chains across Berlin and Hamburg, though margin compression from coconut-derived input volatility pressures private-label manufacturers.
- Conditioner:Cationic emulsion systems deposit fatty alcohols and silicones onto damaged cuticle layers. Salon professionals in Munich specify high-viscosity salon-grade variants, creating pull-through demand for matching home-use maintenance formats.
- Hair Oil:Silicone and botanical oil blends target frizz control in textured hair applications. Pharmacy channels favor dermatologically tested variants with documented comedogenic safety profiles.
- Hair Serum:Lightweight silicone-in-water emulsions with heat-activated polymers protect against thermal styling damage. E-commerce platforms drive discovery through algorithmic hair-type matching rather than traditional shelf placement.
- Hair Mask:High-viscosity treatments with elevated active ingredient loads deliver intensive conditioning. Specialty retailers command exclusivity on premium-positioned variants with extended leave-in protocols.
- Styling Products:Polymer-based hold systems range from flexible gels to high-fixation sprays. REACH restrictions on volatile organic compounds reshape aerosol formulation choices for domestic manufacturers.
Shampoo and conditioner absorb the bulk of installed capacity; hair serum is expanding most quickly.
Hair Type:
Cost tier differentiation separates mass-market generalist formulations from premium specialized ranges with elevated R&D amortization.
- Straight:Lightweight conditioning systems avoid excessive deposit that would flatten natural volume. Drugstore customers in Hamburg prioritize daily-wash compatibility and rapid rinse-out properties.
- Wavy:Balanced moisture-protein formulations address hybrid texture needs without defining curl or weighing down waves. Specialty store shoppers seek silicone-free options with sea salt and botanical extracts.
- Curly:High-emollience systems with film-forming humectants maintain curl definition and combat frizz. E-commerce buyers drive demand for CGM-compliant (Curly Girl Method) ranges excluding sulfates and silicones.
- Coily:Dense oil-in-water emulsions and butter-rich treatments address extreme dryness and mechanical fragility. Salon professionals in Berlin specify pre-shampoo treatments and protective styling products for this segment.
- Textured:Multi-ethnic hair formulations combining moisture retention with scalp health actives. Pharmacy channels favor dermatologically tested ranges addressing specific concerns like traction alopecia prevention.
Straight hair applications dominate current volume; curly and coily segments are gaining share fastest.
Application:
Volume concentration in legacy cleansing and conditioning applications contrasts with margin migration toward treatment-positioned specialties.
- Damage Repair:Protein-reconstruction and bond-building formulations target chemically treated or heat-damaged hair. Salon professionals in Munich prescribe intensive treatment protocols bridging appointment intervals with home maintenance.
- Scalp Care:Prebiotic, postbiotic, and antimicrobial actives address microbiome balance and irritation. ECHA's tightening preservative restrictions accelerate reformulation toward novel preservation systems in this fast-growing category.
- Dandruff Control:Zinc pyrithione, climbazole, and salicylic acid-based treatments target Malassezia overgrowth. Pharmacy loyalty programs drive repeat purchase capture for clinically positioned variants.
- Hair Growth:Caffeine, minoxidil, and peptide-based actives stimulate follicular activity. Regulatory boundary between cosmetic and pharmaceutical claims requires careful positioning for German market access.
- Color Protection:UV filters and antioxidant systems preserve artificial pigment integrity. Specialty retailers command premium positioning for salon-brand color care extensions.
- Volume Enhancement:Lightweight polymers and root-lift technologies create apparent fullness without residue buildup. Drugstore customers prioritize immediate visible effect and compatibility with daily styling routines.
Damage repair absorbs the bulk of installed capacity; scalp care is expanding most quickly.
Customer Type:
Channel-specific packaging formats and service bundling reshape how manufacturers allocate marketing investment and inventory positioning.
- Salon Professionals:Back-bar liters and retail-size home maintenance products sold through professional distributors. Hamburg and Munich salon density supports dedicated sales representative coverage and education programming.
- Individual Consumers:Standard retail formats purchased through primary household shopping channels. Berlin's dense urban population concentrates volume in convenience-oriented purchase occasions.
- E-commerce Buyers:Algorithm-driven discovery through marketplace platforms and direct-to-consumer subscriptions. First-party data infrastructure determines personalization capabilities and retention economics.
- Specialty Store Shoppers:Curated assortments in beauty-focused retailers with educated staff consultation. Premium positioning and exclusive SKUs defend margin against price-transparent alternatives.
- Drugstore Customers:High-frequency, promotion-sensitive purchasing in pharmacy and mass-market retail chains. KBA waste-reduction targets incentivize refill station deployment to lock retailer exclusivity.
Drugstore customers absorb the bulk of installed capacity; e-commerce buyers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan clusters concentrate Germany's hair care demand through dense pharmacy networks and salon infrastructure. REACH compliance requirements and KBA waste-reduction targets reshape regional competitive positioning. State-level environmental enforcement creates compliance cost differentials across manufacturing locations.
Bavaria
Munich's salon density drives professional-grade product consumption through education-linked distributor relationships. The Bavarian State Ministry of the Environment enforces packaging waste targets stricter than federal baselines. Ingolstadt manufacturing corridors host formulation facilities serving premium pharmacy chains.
North Rhine-Westphalia
Düsseldorf and Cologne retail clusters absorb mass-market shampoo volumes through drugstore concentration. ECHA's centralized registration database in Helsinki filters import competition entering through Rhine logistics corridors. Wuppertal specialty chemical suppliers provide surfactant inputs to domestic formulators.
Baden-Württemberg
Stuttgart's automotive-affluent consumer base sustains premium hair wellness positioning. The state's Environmental Protection Agency coordinates with KBA on circular economy implementation timelines. Freiburg's sustainability-focused retail ecosystem tests refill station concepts before national rollout.
Berlin-Brandenburg
Berlin's pharmacy loyalty apps fragment brand discovery through algorithmic matching rather than shelf visibility. Federal Ministry for the Environment, Nature Conservation and Nuclear Safety oversees REACH enforcement coordination with ECHA. Potsdam logistics hubs distribute e-commerce orders across eastern metropolitan zones.
Hamburg
Hamburg's port infrastructure positions the city as import gateway for coconut-derived surfactants and specialty actives. The city's Environmental Authority enforces marine protection standards affecting wastewater discharge from manufacturing. Altona's salon professional density supports dedicated sales representative coverage.
Germany Hair Care Market Competitive Landscape
German producers anchor the domestic tier; French and Japanese specialists hold premium positioning through technology licensing. The vendor base splits between consolidated multinational portfolios and mid-scale domestic formulators with captive regulatory affairs capabilities. Three archetypes dominate: vertically integrated chemical conglomerates with surfactant manufacturing, dermatology-focused pharmacy channel specialists, and salon-professional distributors with education infrastructure. Competitive moves concentrate on M&A for microbiome science capabilities and strategic partnerships with encapsulation technology providers.
Within the domestic manufacturing tier, Henkel AG & Co. KGaA and Beiersdorf AG occupy anchor positions through proximity advantages with German distributors. L'Oreal SA exemplifies the technology-licensing archetype competing through salon-grade formulation leadership. These three entities represent distinct competitive vectors: captive surfactant production, dermatological testing infrastructure, and professional channel education programming respectively.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| Coty INC. |
| Henkel AG & Co. KGaA |
| The Estee Lauder Companies |
| Shiseido Company Ltd |
| L'Oreal SA |
| Unilever PLC |
| Oriflame Group |
| Beiersdorf AG |
| Others |
Supply & Pricing Matrix
Formulation chemists with combined biodegradability and sensory expertise cluster in the Ingolstadt corridor, and their scarcity premium widens the spread between pharmacy-grade and mass-market price tiers. REACH documentation burdens fall heaviest on smaller domestic manufacturers, compressing their margin room against multinational competitors with dedicated regulatory affairs teams.
Pricing Analysis
Volume concentrates in mass-market shampoo and conditioner sold through drugstore chains, while margin pools shift toward hair serum and scalp care positioned through pharmacy channels. Three-tier pricing structure across premium salon-grade, standard retail, and economy private-label levels reflects certification grade and channel service bundling. Pricing pressure stems from coconut-derived surfactant volatility and single-source packaging dependencies. Drugstore customers exhibit highest price sensitivity; salon professionals and pharmacy shoppers accept ingredient premiums for documented efficacy.
Supply Chain Analysis
Surfactant supply rests on coconut processing facilities in Indonesia and the Philippines alongside petrochemical derivatives from Belgian and Dutch refiners. Specialty active ingredients draw from French botanical extractors and Japanese encapsulation technology providers. Single-source vulnerability concentrates in recycled PET and aluminum packaging from European suppliers exposed to regional energy cost spikes. Distribution runs through professional salon distributors, pharmacy chain logistics hubs, and e-commerce fulfillment centers anchored in Berlin-Brandenburg and Hamburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's hair care market operates as a cost-of-compliance arena where REACH registration requirements and ECHA chemical safety standards erect formidable barriers against low-documentation imports. Domestic incumbents with established regulatory infrastructure capture protected margin pools unavailable to unregistered competitors.
For Market Incumbents: Extend encapsulation technology capabilities through partnership with Japanese or German specialty chemical providers to capture margin premiums previously retained by ingredient suppliers. Deepen pharmacy channel control through dermatological testing infrastructure investment, countering algorithmic discovery fragmentation that erodes brand visibility in Berlin's loyalty-app environments.
For New Entrants and Emerging Players: E-commerce buyers seeking CGM-compliant curly and coily hair formulations represent the most penetrable white space between cosmetic and dermatological positioning. Target scalp microbiome science with prebiotic and postbiotic active ingredients, leveraging refill station partnerships with Freiburg and Munich retailers to secure exclusivity under KBA waste-reduction targets.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale domestic formulators possessing captive regulatory affairs capabilities given accelerating ECHA preservative restriction timelines. Long-term viability favors acquisition targets with parallel dermatological and organic certification navigation experience. Watch ECHA's evolving candidate list for endocrine disruptors as the signal indicating which preservation system transitions will command premium licensing values.
| Strategic Initiative | Industry Significance |
|---|---|
| Scalp Microbiome R&D Investment | Prebiotic and postbiotic capabilities unlock positioning between cosmetic and dermatological channels favored by German pharmacy chains. |
| Refill Infrastructure Deployment | In-store refill stations satisfy KBA waste-reduction targets while locking retailer exclusivity in Bavaria and Baden-Württemberg. |
| Encapsulation Technology Licensing | Time-release active delivery systems enable Munich and Hamburg salons to offer extended-benefit services bridging appointment intervals. |
| Dual Certification Navigation | Parallel dermatological testing and organic certification capabilities preempt compliance cost spikes from divergent documentation requirements. |
| Professional Education Programming | Salon distributor relationships in Hamburg and Munich create pull-through demand for matching home maintenance product formats. |
Research Methodology
Multi-period observation of surfactant input costs, ECHA registration timelines, and pharmacy channel assortment changes anchored the trend analysis, supplemented by interviews with formulation chemists at domestic manufacturers, procurement leads at German drugstore chains, salon distributor sales representatives, and regulatory affairs directors navigating REACH compliance. Secondary validation drew from ECHA candidate list updates, KBA waste-reduction target publications, customs records for coconut-derived imports, and Nielsen retail audit data. Bottom-up segment sizing and top-down market reconciliation ensured analytical robustness.
Input-output matrices mapped surfactant manufacturing capacity, active ingredient sourcing patterns, and channel-specific volume flows across the projection horizon. Segmentation dimensions modeled included product type, hair type, application focus, and customer channel. CAGRs derived from historical trajectory analysis adjusted for regulatory friction factors and metropolitan cluster demand concentration. Industry-specific forecast inputs incorporated ECHA authorization procedure timelines and KBA circular economy implementation schedules.
Revisions become necessary when ECHA accelerates preservative restriction timelines, energy cost spikes disrupt single-source packaging supply, or algorithmic discovery fragmentation in pharmacy loyalty apps accelerates beyond current trajectory assumptions. A small set of named triggers—regulatory acceleration, input cost volatility, and channel behavioral shift—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Australia Hair Removal Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
China Hair Care Products Market
Hair Care
Hair Care Appliances Market
Hair Care
Global Premium Hair Care Market
Hair Care
South Africa Hair Care Market
Hair Care
Artificial Hair Integration Market
Hair Care
Japan Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Hair Bond Multiplier Market
Hair Care
Chile Hair Care Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Russia Hair Care Market
Hair Care
Argentina Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
North America Hair Care Market