
 Men's Hairspray Market | 2026-2036
Men's Hairspray Market Size, Share, and Industry Trends Forecast 2026-2036
Men's Hairspray Market Insights
Aftermarket styling education revenue is fragmenting across digital tutorials, salon certification programs, and brand ambassador networks. Procter & Gamble leverages its mass-market distribution infrastructure to sustain shelf dominance in North American retail chains. L'Oréal anchors its professional division through salon-exclusive lines that command premium pricing. Unilever competes via specialized men's grooming sub-brands with targeted fitness and fashion positioning.
Men's hairspray comprises resin-based fixative polymers dissolved in alcohol or water carriers, delivered through pressurized aerosol or mechanical pump systems to provide temporary hair shaping with variable hold strength and finish characteristics. The product serves commercial purposes ranging from professional salon finishing to daily consumer grooming maintenance. Flexible hold formulations capture expanding share among everyday users seeking restylability without residue buildup. Aerosol delivery dominates volume through convenience preference, though pump spray and water-based alternatives gain traction among sustainability-oriented segments in European and Asian markets.
The EPA regulates volatile organic compound emissions under 40 CFR Part 59, constraining aerosol propellant formulations in the United States, while REACH and the EU F-Gas Regulation mandate chemical safety assessments and restrict fluorinated gas use in European manufacturing. These frameworks elevate compliance costs for multinational suppliers but simultaneously accelerate innovation in low-VOC and water-based delivery systems. Stakeholders must monitor evolving propellant chemistry standards and regional labeling requirements to maintain formulation agility across divergent regulatory environments.
Market Dynamics
Reformulation pressure from VOC regulations is fragmenting the aerosol supply base while water-based alternatives gain shelf space in premium retail channels. The EPA's 40 CFR Part 59 and REACH compliance timelines are forcing simultaneous multi-regional product redesign.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon propellants accelerates investment in compressed air and nitrogen delivery systems among contract manufacturers.
- Professional salon networks:Certification-driven product endorsement creates pull-through demand for salon-exclusive hold formulations in South Korea and Germany.
- Dimethyl ether (DME) propellant chemistry:Lower-VOC DME blends enable compliance without sacrificing spray performance, attracting formulation investment from aerosol specialists.
Market Restraints
- Alcohol carrier cost volatility:Ethanol price swings tied to biofuel policy uncertainty compress margin predictability for mass-market producers.
- Aerosol can supply concentration:Three European metal packaging groups control 70% of specialized lacquered can capacity, creating single-source vulnerability.
- Water-based dry time limitation:Extended setting periods versus alcohol carriers restrict adoption among time-pressed professional stylists.
Strategic Opportunities
- India men's grooming penetration:Current per-capita hairspray consumption sits at 12% of US levels, creating whitespace for mass-market entry.
- Subscription refill systems:Concentrate-to-pump formats bypass aerosol shipping restrictions while capturing recurring revenue.
- CSRD-aligned sustainability claims:Mandatory EU corporate sustainability reporting creates demand for verified lifecycle data from ingredient suppliers.
Industry Challenges
- Cross-regional formulation complexity:Divergent VOC limits between California Air Resources Board rules and EU directives require parallel product lines.
- Aerosol engineer scarcity:Specialized expertise in compressed gas rheology and valve design concentrates among retiring technicians at legacy suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Men's Hairspray Market |
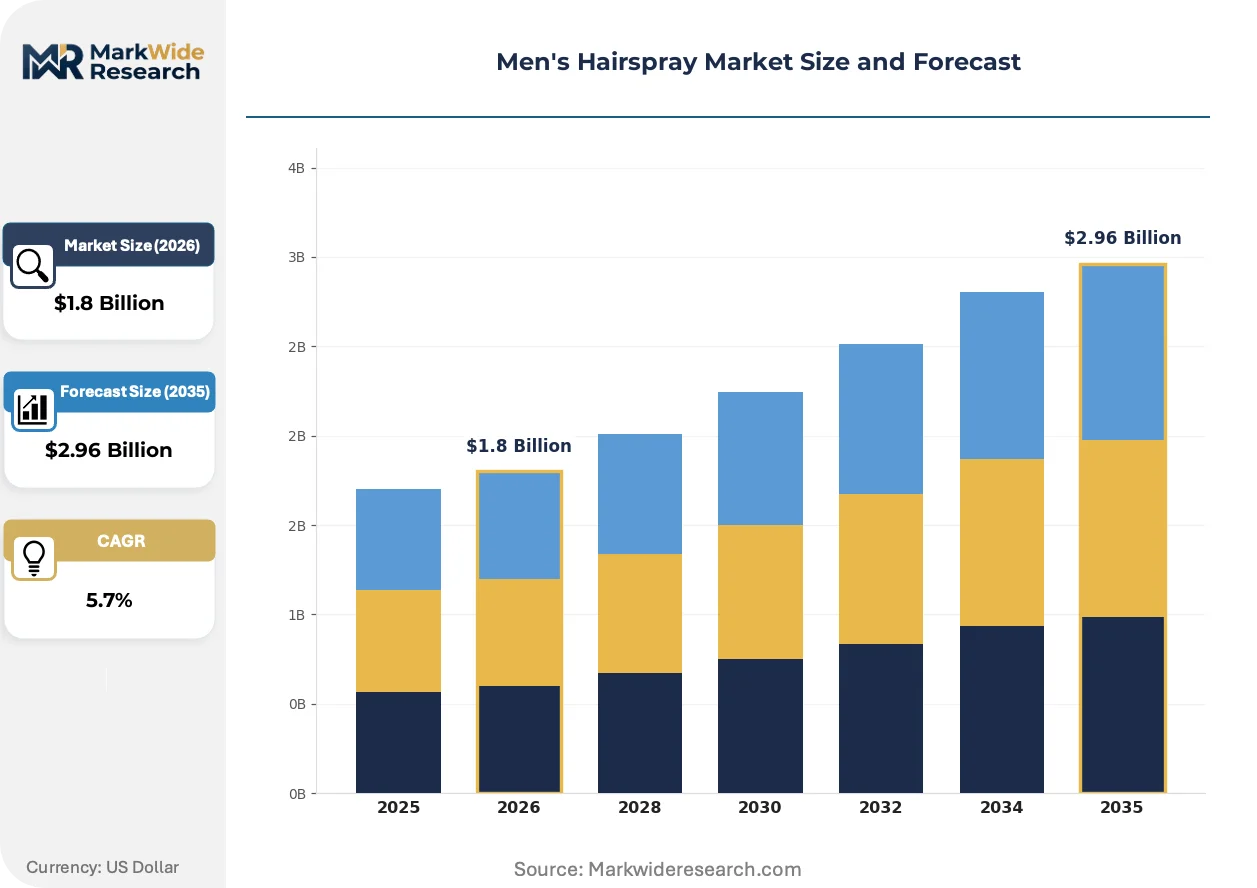
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Hairspray, Matte Finish, Flexible Hold, Extra Strong Formulation: Aerosol, Pump Spray, Gel-Based, Water-Based Target Audience: Professional Stylists, Everyday Users, Fitness Enthusiasts, Fashion Enthusiasts Distribution Channel: Online Retail, Beauty Salons, Specialty Stores, Supermarkets |
| Companies Covered | Procter & Gamble, Unilever, L'Oréal, Coty Inc., Henkel AG & Co. KGaA, Beiersdorf AG, The Estée Lauder Companies Inc., Church & Dwight Co., Inc., Shiseido Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Men's Hairspray Market Trends and Innovations
Delivery system innovation is compressing the traditional aerosol-pump dichotomy while regulatory chemistry constraints accelerate bio-based polymer development. These shifts are redrawing competitive boundaries between mass-market and professional positioning.
Water-soluble polyurethane resins are collapsing the performance gap between flexible-hold water-based sprays and traditional alcohol-aerosol systems. Premium salon brands in Germany and South Korea are adopting these polymers for restylable daytime formulations. The technology is collapsing the historical trade-off between environmental positioning and professional-grade hold duration.
REACH authorization requirements for synthetic polymers are forcing substitution toward bio-based fixative alternatives. The European Chemicals Agency's expanded substance evaluation list now covers several acrylate copolymers common in high-hold formulations. Professional lines targeting EU distribution are accelerating plant-derived resin qualification timelines.
Stylists are unbundling product recommendation from salon retail, driving direct-to-consumer sampling through social platform affiliate structures. This behavior is compressing traditional wholesale-salon channel margins while rewarding brands with authentic creator relationships. The shift is most visible in US and UK markets where male grooming content creators command seven-figure followings.
Men's Hairspray Market Segmentation
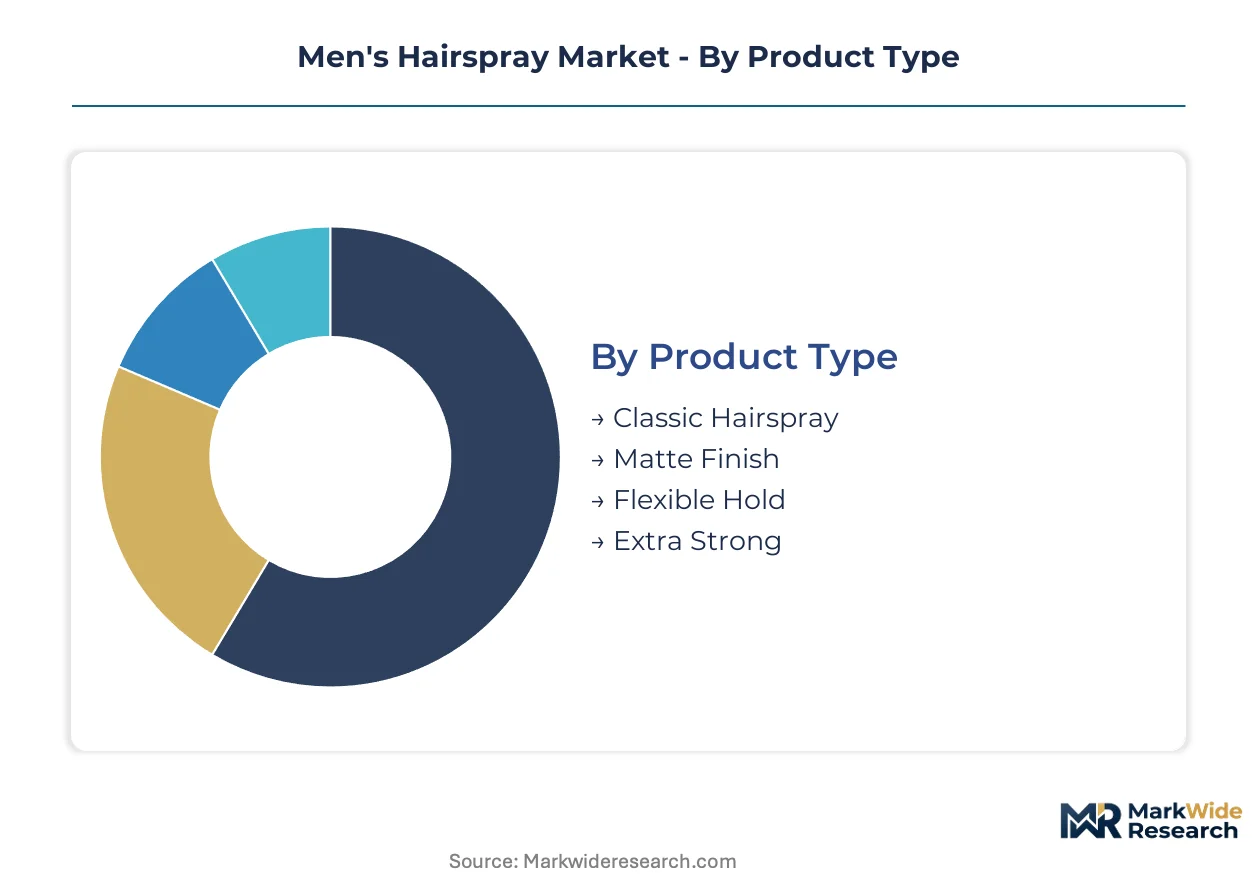
Segmentation in men's hairspray reveals how formulation chemistry, delivery mechanics, and channel economics create distinct competitive arenas. Each dimension carries different margin profiles, regulatory exposure, and customer lifetime value characteristics that reshape resource allocation.
Product Type:
Cost tier differentiation separates occasional users from daily grooming investment, with premium positioning commanding shelf space in professional channels.
- Classic Hairspray:Alcohol-dominant formulations with synthetic resin polymers deliver maximum hold duration for formal styling contexts. Demand concentrates among professional stylists in Germany and South Korea where salon certification programs mandate specific product endorsement, though VOC regulatory pressure is forcing gradual reformulation toward lower-emission carriers.
- Flexible Hold:Polyurethane-based flexible polymers enable daytime restyling without residue accumulation or stiffness. Everyday users in the United States and urban European markets drive adoption, with water-soluble resin technology collapsing the performance gap against traditional alcohol-aerosol systems.
- Matte Finish:Silica microsphere additives absorb surface oil for textured, non-reflective styling outcomes.
- Extra Strong:High-concentration acrylate copolymer formulations target performance athletes and stage performers requiring extreme humidity resistance.
Classic Hairspray holds installed capacity. Flexible Hold is rotating up the share rankings.
Formulation:
Delivery mechanism determines regulatory compliance pathway, carbon footprint positioning, and professional versus consumer channel suitability.
- Aerosol:Pressurized hydrocarbon or dimethyl ether propellant systems deliver fine particle distribution with rapid dry times. Convenience preference sustains volume leadership in mass-market retail, though EPA 40 CFR Part 59 and EU F-Gas Regulation timelines are forcing compressed air and nitrogen alternatives investment.
- Water-Based:Aqueous polymer dispersions eliminate volatile organic compound exposure entirely. Sustainability-oriented segments in European and Asian markets drive traction, with extended setting periods remaining the primary adoption barrier among time-pressed professional stylists.
- Pump Spray:Mechanical pressure generation avoids propellant chemistry entirely while sacrificing spray fineness.
- Gel-Based:Thixotropic polymer gels offer precise application control for detailed styling work.
Aerosol maintains manufacturing scale. Water-Based is climbing the fastest among sustainability-aligned distribution channels.
Target Audience:
Customer type governs purchase frequency, price elasticity, and susceptibility to influencer recommendation versus institutional certification.
- Professional Stylists:Salon-exclusive product lines with elevated resin concentrations and specialized finish characteristics. Certification-driven endorsement in South Korea and Germany creates pull-through demand that commands premium pricing, with brand switching costs reinforced by training program investment.
- Fashion Enthusiasts:Trend-responsive consumers prioritizing packaging aesthetics and creator affiliation over functional specification. Social platform affiliate structures in the United States and United Kingdom compress traditional wholesale-salon margins while rewarding authentic influencer relationships.
- Everyday Users:Mass-market consumers seeking reliable performance at accessible price points.
- Fitness Enthusiasts:Sweat-resistant hold requirements for active lifestyle contexts.
Professional Stylists anchor margin contribution. Fashion Enthusiasts are gaining share fastest through direct-to-consumer sampling acceleration.
Distribution Channel:
Channel selection determines margin capture, customer data access, and exposure to private label substitution pressure.
- Beauty Salons:Professional-only product lines with exclusive formulation variants and stylist education bundling. Germany and South Korea concentrate salon network density, with certification requirements creating defensible brand positioning against mass-market encroachment.
- Online Retail:Direct-to-consumer fulfillment enables subscription refill systems and concentrate-to-pump formats that bypass aerosol shipping restrictions. Digital tutorial integration and creator affiliate structures drive discovery in the United States and United Kingdom markets.
- Specialty Stores:Curated assortment with educated staff consultation for ingredient-conscious consumers.
- Supermarkets:High-velocity mass-market placement with promotional pricing sensitivity.
Beauty Salons defend premium positioning. Online Retail is expanding most quickly through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States consumers absorb premium salon-grade pricing with minimal volume contraction, while Indian buyers remain highly sensitive to per-gram cost differentials between aerosol and pump formats.
United States
Professional stylist certification programs and male grooming content creators on social platforms sustain demand for flexible-hold formulations. EPA 40 CFR Part 59 constrains VOC emissions, forcing compressed air propellant adoption among contract manufacturers. Los Angeles and New York concentrate salon network density where direct-to-consumer sampling through creator affiliate structures is compressing traditional wholesale margins.
Germany
REACH authorization timelines for synthetic polymers are accelerating bio-based resin qualification among professional product lines. EU F-Gas Regulation phases down hydrofluorocarbon propellants, elevating investment in dimethyl ether and nitrogen delivery systems. The Cologne-Düsseldorf corridor anchors salon-exclusive brand headquarters where certification-driven endorsement creates defensible positioning against mass-market encroachment.
South Korea
Beauty salon culture and K-pop influenced styling trends sustain premium positioning for extra-strong hold formulations. MFDS cosmetic safety assessments govern ingredient disclosure requirements, elevating compliance costs for imported lines. Seoul's Gangnam district concentrates high-end salon chains where stylist education bundling reinforces brand switching costs through training program investment.
India
Urban male grooming penetration in Mumbai and Bangalore is expanding addressable market beyond traditional fairness-product categories. BIS certification requirements for aerosol products create entry barriers for unorganized sector competitors. The Delhi-NCR corridor hosts contract manufacturing clusters serving mass-market brands with reformulated lower-VOC variants adapted to price-sensitive distribution.
United Kingdom
Fashion enthusiast segments and fitness-oriented styling needs are fragmenting demand across matte-finish and sweat-resistant product variants. CSRD-aligned sustainability reporting mandates are pressuring brands to verify lifecycle data from ingredient suppliers. London's Shoreditch and Manchester concentrate independent salon networks where social platform discovery is displacing traditional professional channel gatekeepers.
Men's Hairspray Market Competitive Landscape
Capability concentration sits with professional-formulation specialists; scale advantage sits with mass-market consumer goods conglomerates. The market structures around three tiers: multinational FMCG houses with shelf-dominant retail infrastructure, professional-division beauty groups with salon-exclusive lines, and regional specialists in propellant chemistry and compressed gas delivery. Dominant competitive moves include portfolio diversification into water-based alternatives and strategic partnerships with contract manufacturers to secure aerosol can supply.
Among the mass-market tier, Procter & Gamble and Unilever occupy positions defined by distribution infrastructure rather than formulation specialization. L'Oréal sits within the professional-division archetype, anchoring salon-exclusive positioning through certification-driven endorsement structures. These three exemplify how competitive advantage in men's hairspray increasingly separates between scale-driven retail capture and capability-driven professional channel loyalty.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| L'Oréal |
| Coty Inc. |
| Henkel AG & Co. KGaA |
| Beiersdorf AG |
| The Estée Lauder Companies Inc. |
| Church & Dwight Co., Inc. |
| Shiseido Company |
| Others |
Pricing and Supply Chain Analysis
European metal packaging groups controlling specialized lacquered can capacity concentrate upstream supply power, directing margin pools toward brands with locked-in contract manufacturing relationships and certified low-VOC formulation pipelines.
Pricing Analysis
Aftermarket styling education revenue from digital tutorials and salon certification programs drives lifetime value beyond the initial product transaction. Three-tier pricing structure across premium, standard, and economy levels separates salon-exclusive formulations with elevated resin concentrations from mass-market aerosol variants and entry-level pump sprays. Price differentiation rests on certification grade and stylist education bundling, with professional channels commanding premium positioning while mass-market tiers face cost compression from ethanol price volatility. Fashion enthusiasts show lowest price sensitivity, absorbing premium packaging and creator-affiliate markups, whereas Indian everyday users exhibit highest elasticity, resisting per-gram cost differentials between delivery formats.
Supply Chain Analysis
Contract manufacturers in Germany, South Korea, and the United States hold specialized capacity for compressed air and nitrogen delivery systems. The supply chain draws from ethanol carriers, dimethyl ether propellant blends, and water-soluble polyurethane resins as primary inputs. Single-source vulnerability concentrates in European aerosol can fabrication, where three metal packaging groups control dominant share. Distribution runs through professional salon networks, specialty retail, and direct-to-consumer subscription channels with varying margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription refill systems and concentrate-to-pump formats represent a service-attach opportunity expanding faster than hardware sales, capturing recurring revenue while bypassing aerosol shipping restrictions.
For Market Incumbents: Insulate professional channel positioning through exclusive stylist certification programs in Germany and South Korea, locking in brand switching costs via training investment. Deepen backward integration into dimethyl ether propellant supply to hedge against European metal packaging concentration. Water-based formulation pipelines must accelerate to preempt REACH authorization restrictions on synthetic polymers. For New Entrants and Emerging Players: Build out direct-to-consumer sampling infrastructure targeting fashion enthusiasts in the United States and United Kingdom, where social platform affiliate structures compress traditional wholesale margins. India's urban male grooming whitespace offers the most penetrable geography, with per-capita consumption sitting far below developed-market levels. A go-to-market angle anchored on verified lifecycle data for CSRD-aligned sustainability claims differentiates against established mass-market players. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across water-based formulation lines as scale economies emerge in compressed air delivery manufacturing. Long-term viability favors professional-division beauty groups with salon-exclusive certification networks over mass-market conglomerates dependent on retail shelf dominance. Acquisition targets should display locked-in contract manufacturing relationships with European or South Korean propellant specialists. The signal to watch is accelerated plant-derived resin qualification timelines among brands targeting EU distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Refill System Launch | Recurring revenue capture bypasses aerosol shipping restrictions while locking in customer lifetime value. |
| Backward Integration into Propellant Supply | In-house DME blending capacity hedges against European metal packaging group concentration and ethanol volatility. |
| Salon Certification Program Expansion | Training investment in Germany and South Korea creates defensible brand switching costs against mass-market encroachment. |
| Water-Based Formulation Pipeline Acceleration | REACH authorization timelines for synthetic polymers force bio-based resin substitution to maintain EU market access. |
| Direct-to-Consumer Sampling Infrastructure | Creator affiliate structures in US and UK markets compress traditional wholesale-salon channel margins. |
Research Methodology
A spread of perspectives from brand managers at professional beauty divisions, category buyers at mass-market retailers, contract manufacturing procurement leads, and regulatory affairs specialists converged on the working assumptions. Primary interviews triangulated with secondary validation from EPA 40 CFR Part 59 filings, ECHA REACH substance evaluation lists, EU F-Gas Regulation implementation timelines, and customs trade data on aerosol can imports. Bottom-up volume modeling across formulation types, delivery mechanisms, and channel economics reconciled with top-down market sizing from grooming expenditure surveys.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product type tier, formulation chemistry cluster, target audience archetype, and distribution channel format. CAGRs derived from historical trajectory analysis adjusted for regulatory phase-in schedules and propellant technology substitution curves. Inputs incorporated ethanol price elasticity coefficients and salon network density indices by metropolitan cluster.
Stress conditions across ethanol cost volatility, REACH authorization delays, and aerosol can supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory compliance timelines and consumer format switching propensity. Quarterly review of propellant chemistry patent filings and EU F-Gas Regulation implementation pace is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Professional Hair Care Products Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Hair Mask Market
Hair Care
Hair Dye Market
Hair Care
Hair Serum Market
Hair Care
Japan Hair Care Market
Hair Care
Global Shampoo Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Hair Care Market
Hair Care
Global Premium Hair Care Market
Hair Care
Organic Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
North America Hair Care Market
Hair Care
Hair and Scalp Care Market