
 United States Hair Care Market | 2026-2036
United States Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hair Care Market Outlook
Subscription-based replenishment services is realigning how consumers purchase hair care, shifting predictable reorder cycles into recurring revenue streams. Procter & Gamble Co. leverages its direct-to-consumer platforms to capture repeat purchase behavior. L'Oreal SA anchors its professional division with salon-exclusive distribution that resists mass-market erosion. Unilever PLC competes through sustainability-certified formulations that command shelf placement in premium retail channels.
United States hair care encompasses surfactant-based cleansers, emollient conditioners, lipid-rich oils, and polymer-hold styling preparations formulated to pH ranges between 4.5 and 6.5 to maintain cuticle integrity. Shampoos and conditioners constitute the volume core, though scalp care applications are expanding fastest as trichology-informed formulations attract consumers with dermatological concerns. Styling products concentrate margin pools through silicone and polymer technology differentiation, while hair oils sustain niche premiums among textured-hair segments underserved by conventional emulsions.
FDA oversight under MoCRA mandates adverse event reporting and facility registration, elevating compliance costs for smaller formulators while advantaging scaled manufacturers with established quality systems. The EPA regulates volatile organic compounds in aerosol styling products, constraining propellant chemistry and pressurized packaging formats. California's Proposition 65 warning requirements and the state's ban on certain preservatives create a bifurcated regulatory landscape that stakeholders must navigate when configuring national versus state-specific product lines. Monitoring state-level chemical restriction precedents will determine whether California's standards become the de facto national compliance floor.
Market Dynamics
MoCRA's adverse event reporting and facility registration mandates are restructuring competitive economics, elevating compliance costs for smaller formulators while consolidating advantage among scaled manufacturers with pre-existing quality infrastructure.
Growth Catalysts
- Scalp care specialization:Trichology-informed formulations targeting dermatological concerns are expanding application scope beyond conventional cleansing. This segment attracts consumers with specific scalp conditions underserved by standard emulsions.
- California's Proposition 65:Chemical transparency requirements are accelerating clean-label innovation as brands reformulate to avoid warning labels. This regulatory pressure is reshaping ingredient sourcing across national product lines.
- Subscription replenishment:Direct-to-consumer platforms are capturing repeat purchase behavior through predictable reorder cycles. This channel shift converts transactional sales into recurring revenue streams with higher lifetime value.
Market Restraints
- Silicone supply concentration:Key polymer inputs for styling products face sourcing risk from limited specialty chemical suppliers. This concentration creates vulnerability in margin-rich styling formulations.
- EPA VOC constraints:Volatile organic compound limits on aerosol propellants restrict pressurized packaging formats. These regulations compress innovation space in high-hold styling sprays.
- Preservative substitution costs:California's ban on certain preservatives forces parallel inventory systems. This bifurcation raises working capital requirements for national distribution.
Strategic Opportunities
- Textured-hair oil segments:Lipid-rich formulations for curl patterns remain underpenetrated by conventional emulsion technologies. This gap sustains niche premium pricing power.
- Professional salon exclusivity:Salon-grade distribution resists mass-market erosion through service-anchored purchase occasions. This channel maintains margin integrity against retail commoditization.
- Sustainability certification:Clean-label credentials command preferential shelf placement in premium retail channels. This positioning advantage accelerates trial among urban consumers.
Industry Challenges
- Trichology formulation expertise:Scalp care expansion requires dermatological science capabilities scarce among conventional cosmetic chemists. This talent gap constrains credible product development.
- Multi-state compliance architecture:California's chemical restrictions versus federal baselines demand dual formulation tracks. This complexity extends product development timelines and inventory costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hair Care Market |
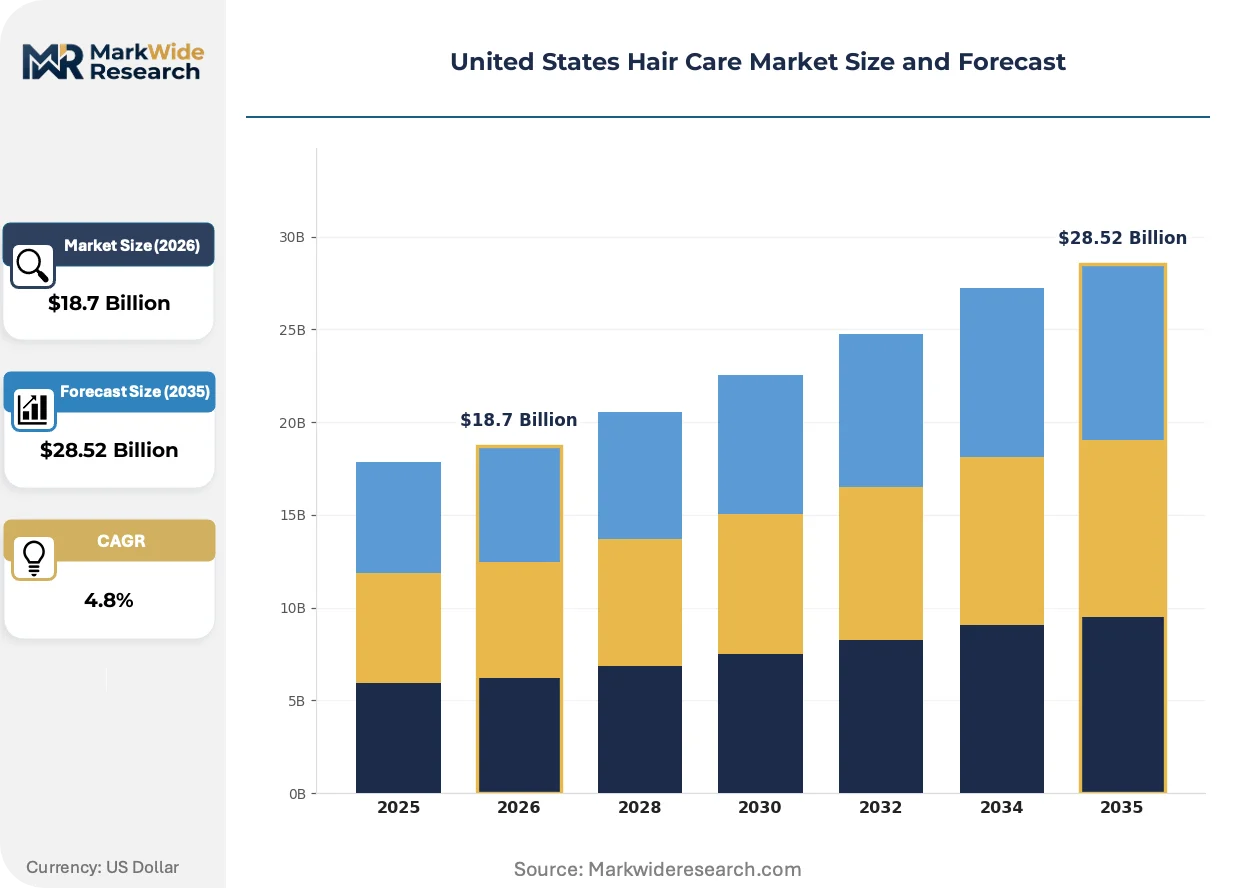
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products End User: Men, Women, Children, Salons Application: Daily Care, Damage Repair, Color Treatment, Scalp Care Distribution Channel: Supermarkets, Online, Specialty Stores, Drugstores |
| Companies Covered | Procter & Gamble Co., L'Oreal SA, Unilever PLC, Henkel AG & Co. KGaA, Kao Corporation, The Estee Lauder Companies Inc., Johnson & Johnson Services, Coty Inc., Revlon Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hair Care Market Strategic Shifts
Formulation science and distribution architecture are converging to redefine how hair care products reach consumers and deliver performance claims. Three developments are actively restructuring competitive positioning.
Artificial intelligence is automating ingredient compatibility screening and stability prediction in formulation development. Mid-sized laboratories are adopting machine learning platforms to compress R&D cycles from months to weeks. This capability compression is automating competitive parity between scaled incumbents and agile challengers.
FDA's Modernization of Cosmetics Regulation Act mandates facility registration and adverse event reporting with specific timelines. This oversight elevates documentation burdens while creating transparency advantages for early-compliant manufacturers. Professional salon brands with established quality systems are adapting fastest, converting compliance investment into channel credibility.
Urban consumers in California and New York are consolidating purchase decisions around clean-label credentials verified through third-party certification. Mass retailers are responding with dedicated shelf sets for preservative-free and silicone-free formulations. This preference rotation is most visible in premium urban markets where ingredient transparency commands price premiums.
United States Hair Care Market Segmentation
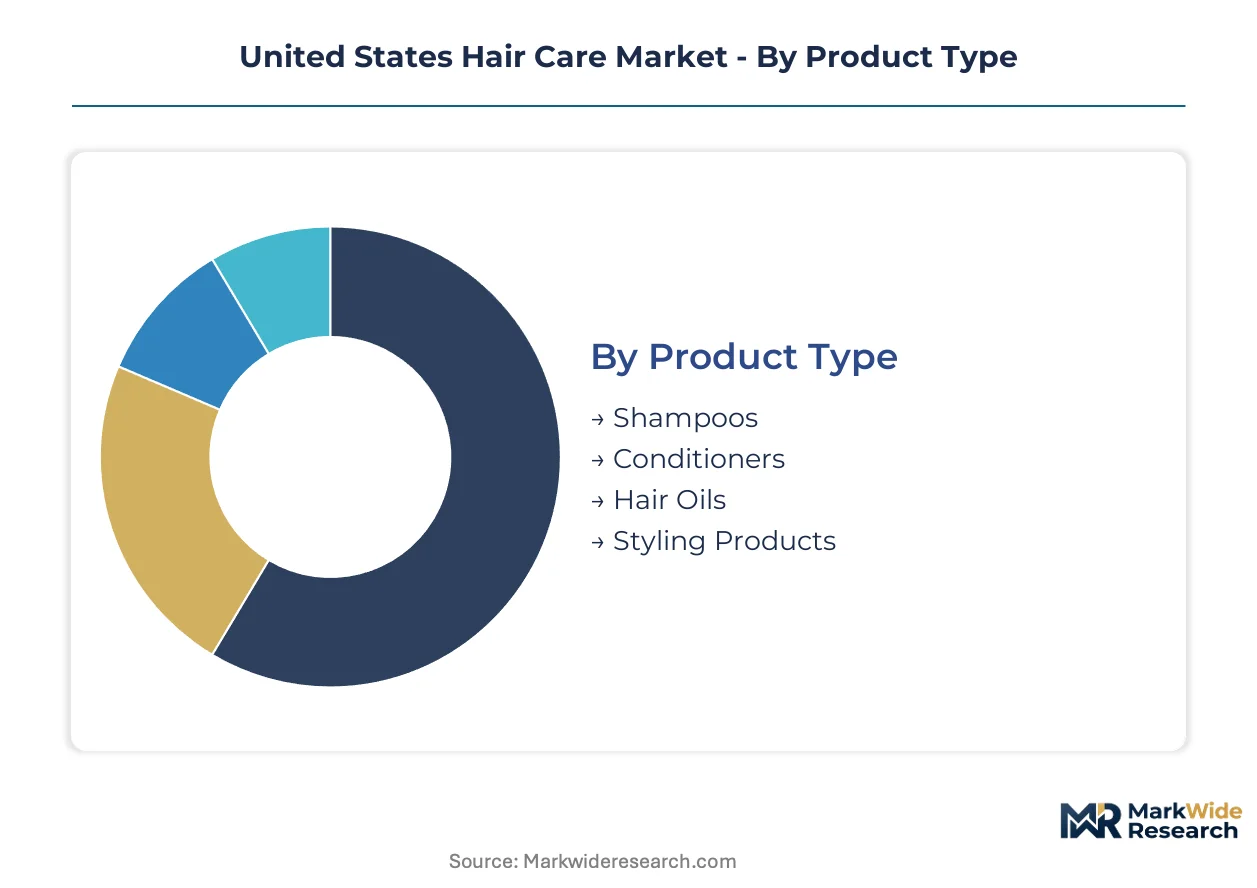
Hair care purchasing patterns fragment across four distinct axes in the United States. Product chemistry, user demographics, treatment purpose, and retail format each create separable demand pools with divergent margin profiles and loyalty mechanics.
Product Type:
Consumer willingness to pay separates most sharply across formulation categories, with functional complexity and ingredient transparency commanding tiered price points.
- Shampoos:Surfactant-based cleansers formulated to pH 4.5-6.5 maintain cuticle integrity during daily washing. Volume concentrates in mass retail channels across California and New York, where urban consumers drive sulfate-free and clean-label reformulations under Proposition 65 pressure.
- Conditioners:Emollient-rich formulations deposit lipids and silicones to restore combability and shine. Salon-exclusive distribution resists mass-market erosion through service-anchored purchase occasions, preserving margin integrity against retail commoditization.
- Hair Oils:Lipid-rich treatments for textured-hair curl patterns sustain niche premium pricing power where conventional emulsion technologies underpenetrate.
- Styling Products:Polymer-hold preparations face EPA VOC constraints on aerosol propellants that compress innovation space in high-hold sprays.
Volume sits with Shampoos; growth tilts toward Hair Oils.
End User:
Demographic targeting determines channel strategy and claim substantiation requirements, with professional versus household use creating divergent purchase frequencies.
- Women:The core purchasing constituency drives multi-step regimen adoption and premium price acceptance across scalp care and damage repair applications.
- Men:Simplified routines favor 2-in-1 formulations and grooming hybrids, with subscription replenishment capturing predictable reorder behavior.
- Children:Tear-free formulations and gentle surfactant systems face heightened FDA scrutiny under MoCRA adverse event reporting mandates.
- Salons:Professional-grade distribution anchors L'Oreal's exclusive channel strategy, resisting mass-market erosion through service-anchored purchase occasions.
Women carry volume density; salons expand margin contribution fastest.
Application:
Treatment purpose segments align with dermatological severity and purchase occasion frequency, from habitual maintenance to episodic intervention.
- Daily Care:Routine cleansing and conditioning cycles generate predictable replenishment demand captured through direct-to-consumer subscription platforms.
- Damage Repair:Keratin and bond-building formulations command premium pricing where heat styling and chemical processing create structural hair compromise.
- Color Treatment:Pigment-depositing and color-protecting formulations serve the permanent and semi-permanent dye user base with UV-filter and antioxidant technology.
- Scalp Care:Trichology-informed formulations targeting dermatological concerns attract consumers with specific conditions underserved by standard emulsions, though talent scarcity constrains credible product development.
Daily Care sustains volume baselines; scalp care climbs the fastest.
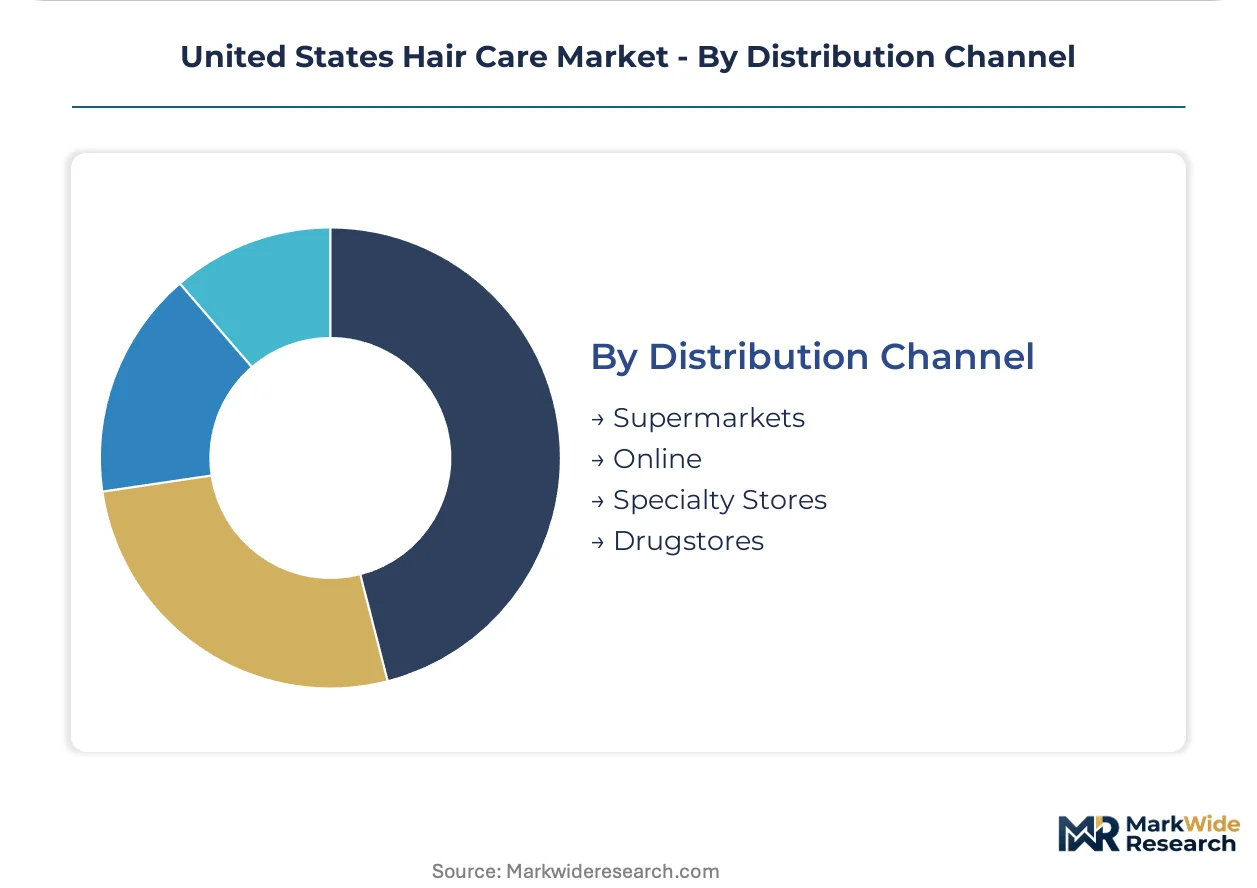
Distribution Channel:
Retail format determines margin capture and consumer education depth, with physical versus digital channels diverging on trial behavior and replenishment mechanics.
- Supermarkets:Mass-market shelf placement drives volume through promotional pricing and impulse purchase visibility, though clean-label credentials increasingly command preferential positioning.
- Online:Direct-to-consumer platforms convert transactional sales into recurring revenue streams with higher lifetime value through subscription replenishment.
- Specialty Stores:Curated assortments and trained staff enable ingredient education that supports premium pricing for sustainability-certified formulations.
- Drugstores:Accessible price points and pharmacist adjacency serve medicated and dermatologist-recommended scalp care segments.
Supermarkets retain volume dominance; online channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the Midwest and Southeast while consumption tilts toward coastal urban centers. This geographic split creates distinct logistics and formulation requirements across domestic supply chains.
California
Los Angeles and San Francisco anchor clean-label demand as Proposition 65 chemical transparency mandates reshape ingredient sourcing. The state's Office of Environmental Health Hazard Assessment enforces warning label requirements that force national brands into dual formulation tracks. Bay Area biotech clusters incubate scalp-care startups leveraging dermatological science partnerships.
New York
Manhattan and Brooklyn drive premium salon-grade consumption through service-anchored purchase occasions. New York State Department of Environmental Conservation regulations on volatile organic compounds constrain aerosol styling product distribution. Long Island manufacturing corridors supply professional-grade formulations to metropolitan salons.
Texas
Houston and Dallas-Fort Worth represent emerging demand for textured-hair oil segments among diverse urban populations. The Texas Commission on Environmental Quality regulates industrial chemical processing facilities serving downstream personal care manufacturing. Gulf Coast petrochemical corridors supply surfactant and silicone feedstocks to regional formulators.
Illinois
Chicago consolidates mass-market distribution infrastructure serving Midwest retail networks. Illinois EPA oversight of manufacturing emissions affects production economics for national brands operating regional facilities. Rockford industrial parks host contract manufacturers producing private-label hair care for supermarket and drugstore channels.
Florida
Miami and Tampa sustain humidity-specific styling product demand driven by climate-adapted consumer preferences. The Florida Department of Environmental Protection regulates wastewater discharge from cosmetic manufacturing facilities. Orlando logistics hubs enable rapid replenishment cycles for direct-to-consumer subscription services.
United States Hair Care Market Competitive Environment
Capital-heavy producers compete with asset-light designers across formulation and distribution. The market structures around three tiers: scaled multinationals with captive R&D infrastructure, mid-sized specialists with channel exclusivity arrangements, and agile challengers leveraging contract manufacturing. Consolidation pressure intensifies as FDA facility registration mandates under MoCRA elevate fixed compliance costs. Dominant competitive moves include portfolio diversification into scalp-care adjacencies and strategic partnerships with dermatology clinics for claim substantiation.
Among the scaled multinational tier, Procter & Gamble Co., L'Oreal SA, and Unilever PLC occupy positions defined by channel architecture rather than formulation differentiation. Cincinnati-based Procter & Gamble exemplifies direct-to-consumer platform investment converting transactional sales into recurring revenue. Paris-listed L'Oreal anchors professional salon exclusivity that resists mass-market price erosion. London-headquartered Unilever sits within sustainability-certified positioning that commands preferential retail placement.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| L'Oreal SA |
| Unilever PLC |
| Henkel AG & Co. KGaA |
| Kao Corporation |
| The Estee Lauder Companies Inc. |
| Johnson & Johnson Services |
| Coty Inc. |
| Revlon Inc. |
| Others |
Value Chain & Pricing Dynamics
Urban mass-market retailers in California and New York concentrate purchase volume, forcing national brands into subscription-based recurring revenue models that trade upfront margin for lifetime value capture. This buyer archetype consolidation rewards scaled manufacturers with direct-to-consumer infrastructure while squeezing smaller formulators dependent on transactional wholesale pricing.
Pricing Analysis
Margin tightening in mass-market tiers reflects Proposition 65 compliance costs and dual-formulation inventory burdens. Three-tier pricing structure across premium salon-grade, standard retail, and economy private-label levels separates claim-substantiated scalp care from commodity surfactants. Cost-down pressure on aerosol styling accelerates because EPA VOC limits constrain propellant chemistry options. Salon-exclusive distribution shows least price sensitivity; supermarket impulse purchases show most.
Supply Chain Analysis
Single-source vulnerability sits with specialty silicone polymer suppliers concentrated in Germany and Japan for styling formulation inputs. Surfactant feedstocks draw from Gulf Coast petrochemical corridors and Midwest oleochemical processing. Tariff exposure on imported emollients creates working capital pressure for textured-hair oil segments. Distribution runs through regional contract manufacturers in Illinois and Florida serving direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MoCRA facility registration mandates have created a supply-constrained environment where compliant manufacturing capacity props pricing power for early-adopter scaled producers.
For Market Incumbents: Anchor professional salon exclusivity against mass-market erosion by deepening dermatology clinic partnerships for scalp-care claim substantiation. Add captive emulsion capacity in Texas to reduce reliance on Gulf Coast surfactant spot markets. Counter emerging clean-label challengers through accelerated sustainability certification investment that commands preferential retail placement. For New Entrants and Emerging Players: Enter via textured-hair oil segments where conventional emulsion technologies underpenetrate curl-pattern formulations. Target underdeveloped scalp-care applications in Texas and Florida where trichology-informed talent remains scarce among incumbent R&D teams. Pursue white-label contract manufacturing relationships with Midwest regional producers to bypass MoCRA compliance capital requirements. For Investors and Strategic Acquirers: The window for entry favors mid-sized specialists with established FDA quality systems and salon-exclusive distribution contracts. Long-term viability hinges on consolidation plays that aggregate compliant manufacturing capacity ahead of further state-level chemical restrictions. Watch California Office of Environmental Health Hazard Assessment precedent expansion as the inflection signal for national formulation standard elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Scalp Care Line Extension | Dermatology clinic partnerships substantiate trichology claims for premium positioning. |
| Direct-to-Consumer Platform Launch | Subscription replenishment converts transactional sales into recurring revenue streams. |
| MoCRA Compliance Infrastructure Investment | Early facility registration creates transparency advantages over smaller formulators. |
| Clean-Label Reformulation Program | Proposition 65 avoidance enables unified national product lines without warning labels. |
| Professional Salon Distribution Expansion | Service-anchored purchase occasions resist mass-market price commoditization. |
Study Parameters
Multi-period observation of salon-grade pricing trajectories and direct-to-consumer subscription growth anchored the trend analysis, supplemented by interviews with brand managers, category buyers at mass retailers, contract manufacturing plant managers, and regulatory affairs leads. Secondary validation drew from FDA MoCRA facility registration databases, EPA VOC compliance filings, California Proposition 65 warning notices, and Nielsen retail audit data. Bottom-up segmentation sizing triangulated against top-down market value estimates.
Input-output matrices modeled volume and value across product chemistry, end-user demographics, treatment purpose, and retail format dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with macroeconomic consumption indicators. Forecast inputs incorporated salon service frequency data and clean-label shelf-space expansion metrics from specialty retail channels.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated state-level chemical restriction adoption or silicone supply disruption scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Mexico Hair Care Market
Hair Care
North America Hair Care Market
Hair Care
Qatar Hair Care Market
Hair Care
Global Hair Color Market
Hair Care
Hair Extension Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
South Korea Hair Care Market
Hair Care
Russia Hair Care Market
Hair Care
France Haircare Market
Hair Care
Hair Bond Multiplier Market
Hair Care
Hair Dye Market
Hair Care
Hair Mask Market
Hair Care
Hair Texturizer Products Market
Hair Care
Hair Oil Market
Hair Care
Brazil Hair Care Market
Hair Care
United Arab Emirates Hair Care Market