
 Protein Shampoo Market | 2026-2036
Protein Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Shampoo Market Analysis
Multi-step treatment bundling is pivoting consumer purchasing behavior in the protein shampoo sector. Unilever leverages its mass-market distribution infrastructure to anchor bundled repair systems across supermarket and pharmacy channels. L'Oréal S.A. competes through professional-grade salon exclusives that sustain premium positioning. Procter & Gamble differentiates via dermatologist-validated formulations that occupy the clinical hair-care segment.
Protein shampoo denotes a surfactant-based cleansing formulation incorporating hydrolyzed keratin, wheat protein, or silk amino acids at concentrations typically ranging from 0.5% to 5% by weight, designed to deposit conditioning proteins onto damaged cuticle layers during the washing process. The product serves both cosmetic restoration of tensile strength and protective pre-treatment for chemically processed hair. Hydrating and strengthening variants lead volume shipments while smoothing formulations command the strongest margin pools in professional salon channels. Liquid form factors dominate mass retail throughput, though cream preparations are gaining traction in trichology and premium direct-to-consumer segments.
FDA cosmetic labeling requirements and EU REACH substance restrictions shape formulation chemistry and ingredient transparency obligations for manufacturers serving North American and European consumers. State-level Proposition 65 enforcement in California and emerging GB standards in China add compliance layers that influence raw material sourcing decisions. Stakeholders must monitor evolving biopolymer certification protocols and regional allergen disclosure mandates to protect market access and brand credibility.
Market Dynamics
Protein shampoo formulation chemistry is pivoting under tightening biopolymer certification protocols across multiple jurisdictions, forcing manufacturers to requalify raw material suppliers and revalidate label claims for hydrolyzed protein concentrations.
Growth Catalysts
- EU REACH substance restrictions:Ingredient disclosure mandates are accelerating transparency investments by formulators, creating competitive differentiation for early-compliant brands in professional salon channels.
- Chemically treated hair protocols:Trichology clinics in Germany and France are expanding protein shampoo prescriptions as pre-treatment standards for keratin and color services.
- Silk amino acid hydrolysis:Advances in enzymatic processing are lowering production costs for premium protein variants, widening addressable segments in direct-to-consumer markets.
Market Restraints
- Plant protein supply volatility:Wheat gluten and soy isolate prices fluctuate with agricultural yields in the Black Sea region, compressing margins on mass-market strengthening variants.
- California Proposition 65 enforcement:Trace contaminant litigation risk elevates compliance insurance costs for brands distributing in the United States.
- Quaternary ammonium substitution:Cationic surfactants in conventional conditioners partially replicate protein deposition effects at lower per-wash cost in price-sensitive segments.
Strategic Opportunities
- Trichology clinic channel expansion:Underpenetrated professional networks in Spain and Italy present white space for clinical-grade protein shampoo distribution.
- GB standards alignment in China:Harmonizing formulations to meet national cosmetic safety benchmarks opens access to cross-border e-commerce platforms serving Chinese consumers.
- Biopolymer certification tailwinds:USDA BioPreferred and EU Ecolabel recognition programs create premium positioning anchors for sustainably sourced protein variants.
Industry Challenges
- Analytical chemist talent scarcity:Validating protein molecular weight distributions for label compliance requires specialized chromatography expertise that outpaces current training pipeline output.
- Legacy ERP integration:Batch-level ingredient traceability systems for REACH documentation often conflict with established manufacturing execution platforms, delaying facility certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Shampoo Market |
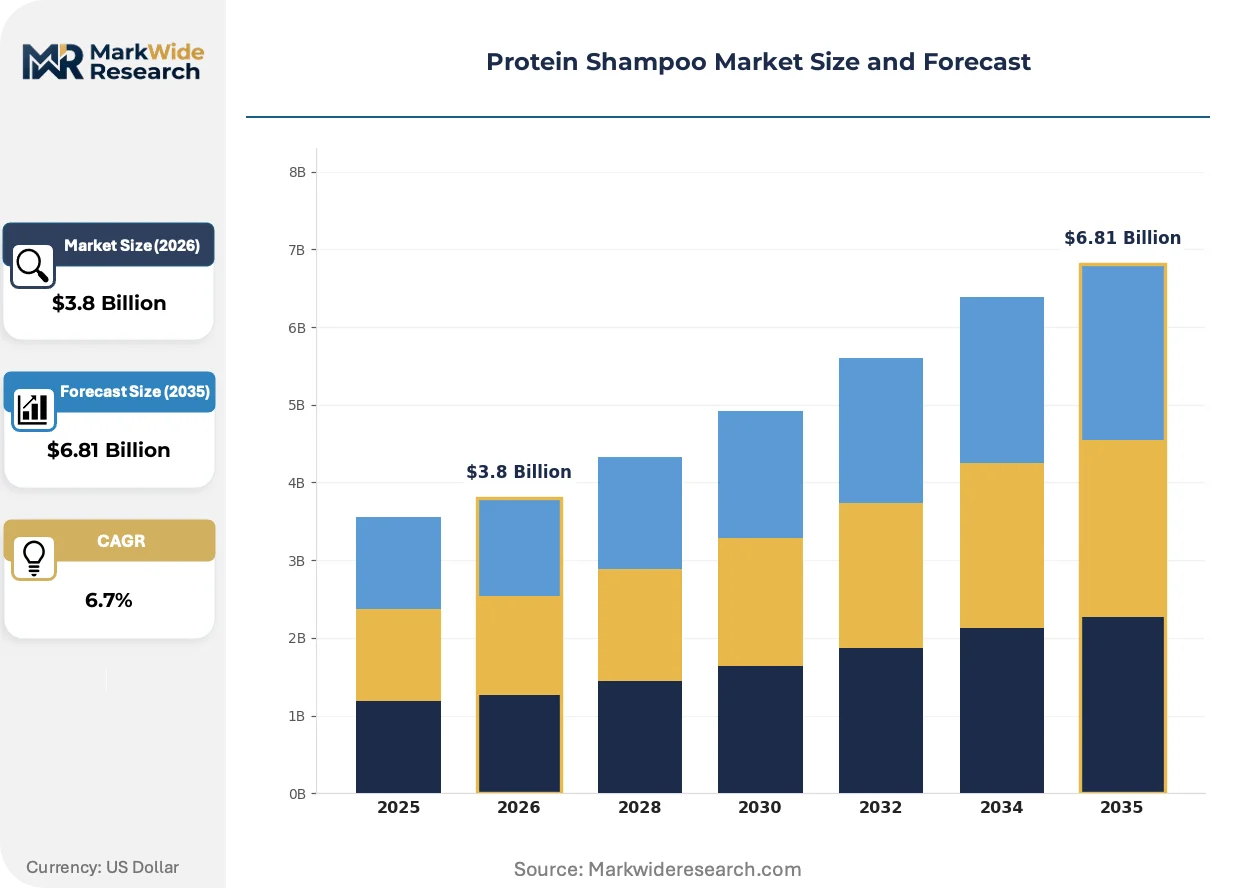
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating, Strengthening, Smoothing, Volume-Boosting Form: Liquid, Cream, Foam, Gel End User: Women, Men, Unisex, Children Distribution Channel: Supermarkets, Online Retailers, Salons, Pharmacies |
| Companies Covered | Shiseido Company, Henkel AG & Co KGaA, Unilever, Keratin Complex, Atlantic Coast, Procter & Gamble, Estée Lauder Companies Inc., Johnson & Johnson, L’Oréal S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Shampoo Market Emerging Trajectories
Biotechnology-enabled protein engineering is restructuring competitive advantage in hair care, displacing conventional hydrolysis methods with precision fermentation and recombinant expression systems that deliver consistent molecular weights.
Precision fermentation-derived keratin analogs are converging with traditional surfactant chemistry to create next-generation protein shampoos with tunable deposition profiles. Professional salon brands in Japan and South Korea are piloting these formulations for customized damage-repair protocols. The technology is converging with scalp microbiome research, enabling multifunctional products that address both structural hair damage and follicle health in single-application formats.
EU REACH Annex XIV authorization requirements for certain preservative compounds are forcing reformulation cycles across European supply chains. Manufacturers serving Germany and France must substitute legacy biocides with alternative preservation systems, extending product development timelines by 12-18 months. Professional-grade lines are absorbing these costs through premium positioning, while mass-market brands face margin compression or portfolio rationalization decisions.
Subscription-based replenishment models are displacing traditional retail replenishment cycles in North American and Western European protein shampoo markets. Direct-to-consumer brands leverage usage-data algorithms to predict reorder timing, capturing lifetime value from chemically treated hair consumers who require consistent protein deposition protocols. This behavioral shift concentrates most visibly in urban coastal markets where salon service frequency correlates with at-home maintenance product adherence.
Protein Shampoo Market Segmentation
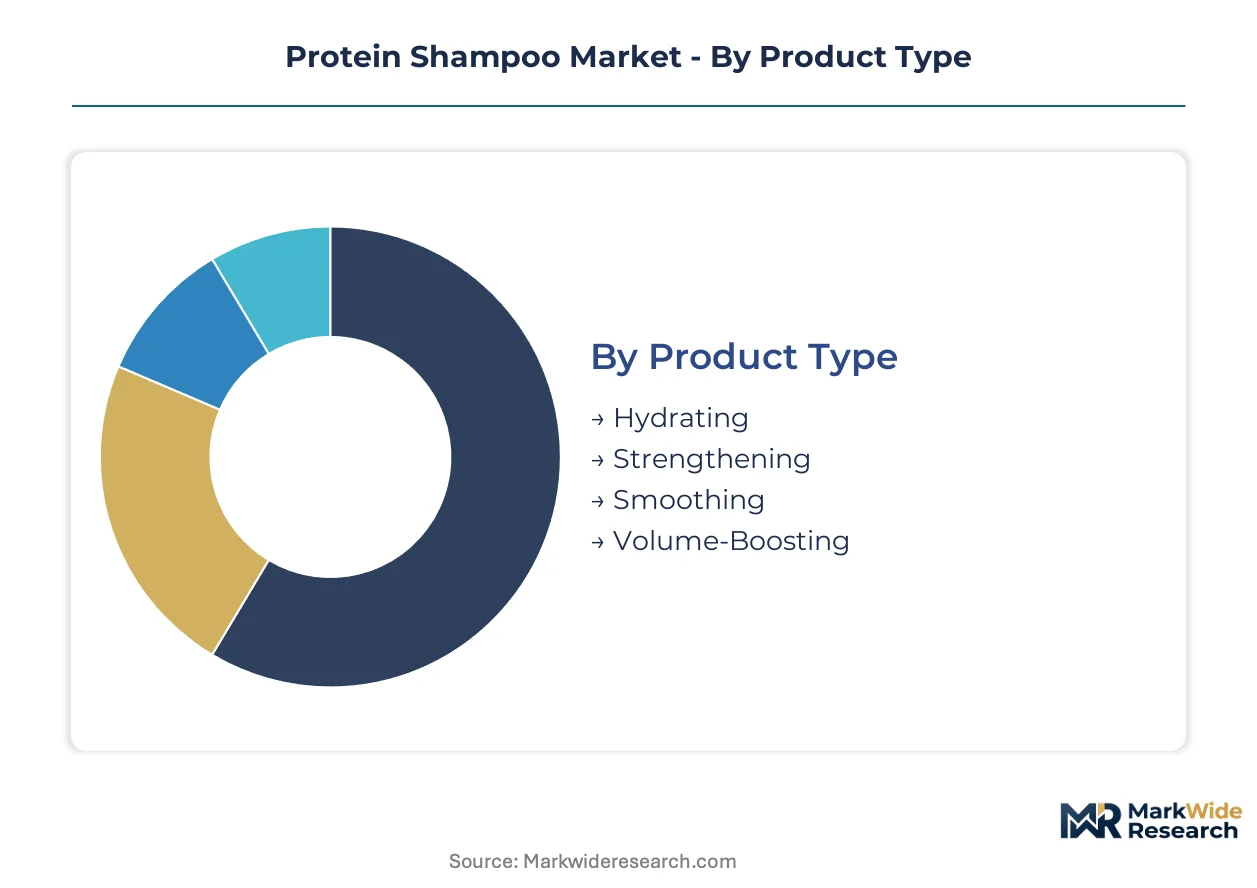
Protein shampoo purchasing decisions hinge on damage severity and treatment protocol adherence. Stylists in Frankfurt and Los Angeles prescribe specific variants based on chemical service history. Formulators must align viscosity, protein load, and preservative systems to each channel's compliance environment and usage context.
Product Type:
Buyers prioritize functional outcome over ingredient branding when selecting repair protocols.
- Hydrating:Glycerin-humectant bases combined with hydrolyzed silk proteins at 2-4% concentration restore moisture-depleted cuticles. Demand concentrates in California and Florida where sun exposure and hard water accelerate dryness. Salon professionals bundle these with deep-conditioning masks for color-treated clients.
- Strengthening:Hydrolyzed keratin and wheat protein formulations target tensile integrity recovery. Trichology clinics in Germany and France prescribe these as pre-treatment for chemical services. Supply volatility in Black Sea wheat gluten compresses margins on mass-market variants.
- Smoothing:Cationic polymer-protein complexes reduce frizz through cuticle sealing. Premium salon channels in Japan favor these for humidity-resistant finishes.
- Volume-Boosting:Lightweight hydrolyzed rice protein systems deposit without residue buildup. Direct-to-consumer brands in South Korea lead formulation innovation here.
Volume sits with Hydrating variants; growth tilts toward Strengthening as chemical service frequency rises.
Form:
Supply chain throughput and dispensing technology dictate manufacturing line allocation.
- Liquid:Standard surfactant-protein suspensions dominate supermarket and pharmacy distribution. Pump-dispense packaging lines in Ohio and Illinois run continuous batches for mass-market SKUs.
- Cream:Thickened emulsions with higher lipid content suit damaged hair protocols. Trichology clinics in Milan and Barcelona specify these for post-chemical recovery regimens.
- Foam:Aerosolized protein-surfactant systems enable even scalp distribution. Japanese salon brands pilot these for sensitive scalp applications.
- Gel:Carbomer-thickened clear bases appeal to male grooming segments. South Korean e-commerce platforms drive adoption here.
Liquid commands shelf space; cream gains share fastest in professional channels.
End User:
Gendered marketing spend correlates with service frequency and basket size.
- Women:Multi-step repair systems with conditioning masks and leave-in treatments. Salon channel concentration in Paris and New York supports premium pricing.
- Men:Simplified two-in-one formats with mint or wood fragrance profiles. Mass retail in Texas and Pennsylvania drives volume.
- Unisex:Neutral fragrance and minimalist packaging for shared household use. Online retailers in California and London prioritize these SKUs.
- Children:Tear-free surfactant bases with reduced protein loads for developing hair. Pediatric dermatologist recommendations in Massachusetts influence purchase decisions.
Women generate current revenue; unisex formats expand most quickly.
Distribution Channel:
Margin structure and compliance burden vary sharply by route-to-market.
- Supermarkets:High-velocity replenishment of standard 400ml family sizes. Walmart and Tesco procurement teams negotiate protein concentration specifications.
- Online Retailers:Subscription algorithms and review-driven discovery. Amazon and Sephora.com data shapes formulation feedback loops.
- Salons:Professional-exclusive SKUs with higher protein loads and stylist education requirements. L'Oréal and Kérastase field teams in Hamburg and Madrid control placement.
- Pharmacies:Dermatologist-endorsed variants with clinical packaging cues. CVS and Boots shelf sets emphasize sensitive scalp positioning.
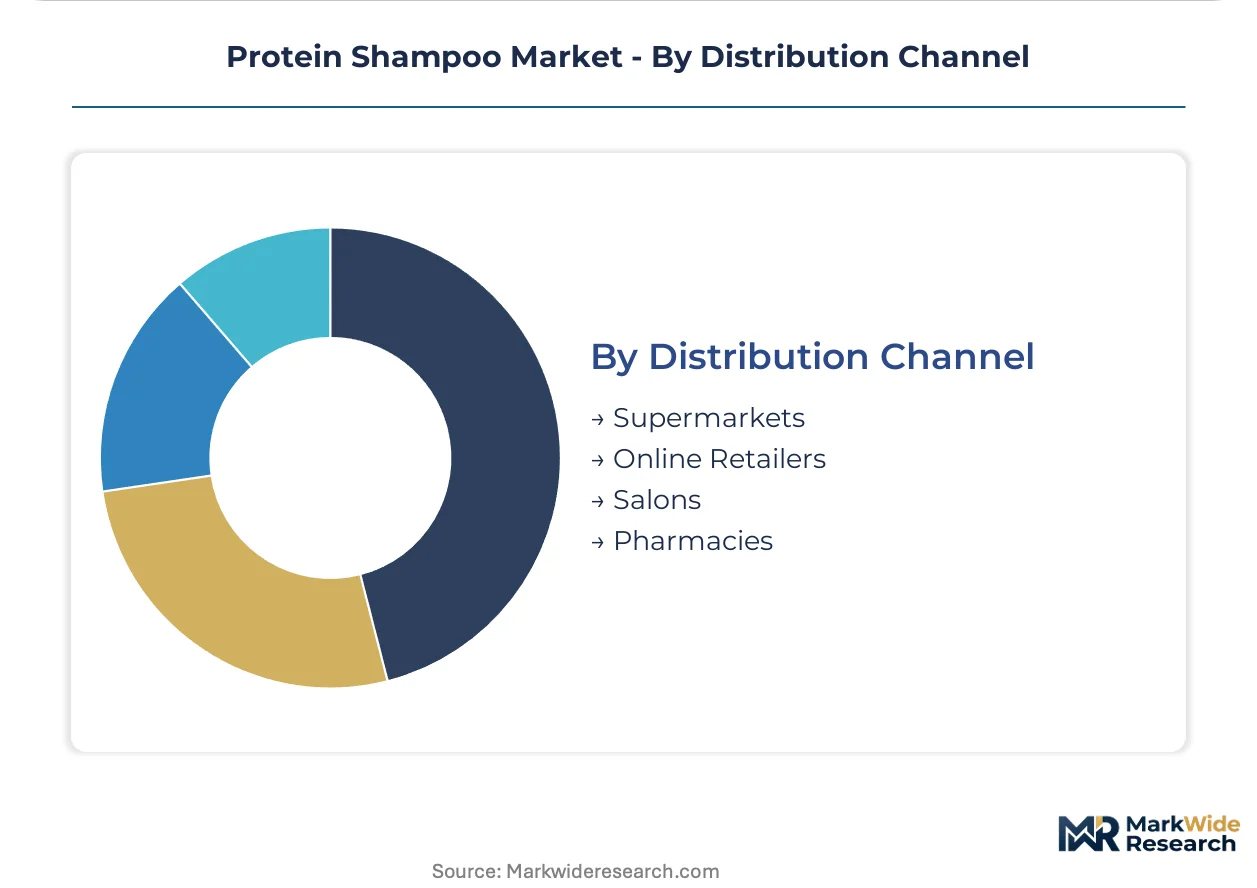
Salons capture value; online retail climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States while consumption tilts toward salon-dense urban corridors in France, Japan, and South Korea. Formulation chemistry expertise clusters near regulatory hubs that enforce REACH and FDA disclosure mandates.
United States
California and Florida drive hydrating variant demand through sun-exposed and hard-water-affected populations. FDA cosmetic labeling requirements and California Proposition 65 enforcement elevate compliance costs for brands distributing nationally. Trichology clinics in Los Angeles and New York prescribe protein shampoos as pre-treatment protocols for keratin services.
Germany
Frankfurt and Hamburg anchor professional salon channel expansion for clinical-grade strengthening formulations. EU REACH substance restrictions and Annex XIV authorization timelines force 12-18 month reformulation cycles. Trichology networks in Berlin and Munich integrate protein shampoos into standardized chemical service pre-treatment regimens.
France
Paris salon professionals bundle multi-step repair systems for color-treated clientele, sustaining premium pricing power. ANSM enforces ingredient disclosure standards that align with broader EU transparency mandates. L'Oréal field teams control placement across Île-de-France and Provence-Alpes-Côte d'Azur professional networks.
Japan
Tokyo and Osaka pilot precision fermentation-derived keratin analogs for customized damage-repair protocols. METI oversight of cosmetic safety benchmarks shapes formulation development timelines. Salon brands in Kanto prefecture lead adoption of foam-dispense protein systems for sensitive scalp applications.
South Korea
Seoul Capital Area direct-to-consumer brands drive volume-boosting rice protein innovation through e-commerce platforms. MFDS cosmetic safety regulations and GB standards alignment requirements influence export-oriented formulation decisions. Gwangju-Honam manufacturing clusters supply lightweight protein systems for male grooming gel segments.
Protein Shampoo Market Vendor Landscape
The competitive structure tilts toward multinational consumer goods conglomerates with professional salon exclusives. Mass-market distribution infrastructure anchors bundled repair systems across supermarket and pharmacy channels, while clinical validation and dermatologist endorsement occupy distinct positioning tiers. Three archetypes dominate: mass-market bundlers, professional-grade exclusivists, and dermatologist-validated clinical specialists. Capacity expansion and portfolio diversification represent the dominant competitive moves, with players extending protein shampoo lines into complementary treatment masks and leave-in conditioners.
Within the mass-market tier, Unilever and Procter & Gamble represent scale-driven distribution archetypes, leveraging supermarket and pharmacy infrastructure across North America and Western Europe. L'Oréal S.A. occupies the professional-grade exclusive position, anchoring salon channel presence through field-controlled placement in Hamburg, Madrid, and Paris. Among Japanese-headquartered specialists, Shiseido Company exemplifies biotechnology-enabled formulation innovation converging with scalp microbiome research.
| Leading Market Players |
|---|
| Shiseido Company |
| Henkel AG & Co KGaA |
| Unilever |
| Keratin Complex |
| Atlantic Coast |
| Procter & Gamble |
| Estée Lauder Companies Inc. |
| Johnson & Johnson |
| L'Oréal S.A. |
| Others |
Supply Flow & Price Mechanics
Backward integration into Black Sea wheat gluten and soy isolate sourcing anchors cost control for mass-market strengthening variants while professional-grade lines leverage captive silk amino acid hydrolysis facilities in Japan to sustain premium positioning. This integration choice separates brands absorbing agricultural commodity volatility from those commanding formulation exclusivity through controlled supply.
Pricing Analysis
Margin tightening in mass-market tiers reflects Black Sea agricultural yield volatility and California Proposition 65 compliance insurance burdens. Three-tier pricing structure across professional salon, pharmacy clinical, and supermarket economy levels stratifies by protein concentration and certification burden. Price differentiation rests on EU REACH compliance status and USDA BioPreferred recognition. Cost-down pressure accelerates on mass-market SKUs as cationic surfactant conditioners replicate protein effects at lower per-wash cost. Pharmacy and salon buyers show least price sensitivity; supermarket replenishment purchasers exhibit highest elasticity.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in protein shampoo given consumable nature, though reverse logistics for salon-exclusive packaging and pump-dispense systems concentrate in Ohio and Illinois remanufacturing hubs. Geographic supply concentration centers on Germany for REACH-compliant formulation chemistry, the United States for mass-market surfactant production, and Japan for precision fermentation-derived keratin analogs. Raw material dependencies draw from Black Sea wheat gluten, Brazilian soy isolate, and Chinese silk protein feedstocks. Single-source vulnerability in enzymatic hydrolysis equipment creates bottleneck risk. Distribution runs through professional salon field teams, Amazon subscription algorithms, and Walmart high-velocity replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH Annex XIV authorization timelines and biopolymer certification mandates are forcing portfolio rationalization that eliminates undercapitalized formulators lacking analytical chemistry expertise.
For Market Incumbents: Extend professional salon exclusives into trichology clinic networks in Spain and Italy before competitors establish clinical-grade positioning. Deepen backward integration into precision fermentation capacity in Japan and South Korea to lock recombinant keratin analog supply. Threat from biotechnology-enabled entrants with tunable deposition profiles demands preemptive capacity commitment. For New Entrants and Emerging Players: Capture direct-to-consumer subscription share in urban coastal markets through usage-data algorithms predicting reorder timing for chemically treated hair consumers. White space concentrates in volume-boosting rice protein systems for male grooming segments and pediatric dermatologist-endorsed tear-free variants. Go-to-market angle: partner with Seoul-based e-commerce platforms for cross-border distribution into China aligned with GB standards. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational consumer goods conglomerates seeking professional salon channel control and biotechnology formulation capabilities. Long-term viability favors targets with validated REACH documentation systems and established trichology clinic relationships. Signal to watch: FDA cosmetic labeling enforcement intensity and state-level Proposition 65 litigation volume as margin compression indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Formulation Partnership | Precision fermentation keratin analogs displace conventional hydrolysis in Japanese salon pilots. |
| Trichology Clinic Channel Expansion | Underpenetrated professional networks in Spain and Italy offer white-space distribution access. |
| EU REACH Compliance Investment | Annex XIV authorization timelines force 12-18 month reformulation cycles that eliminate weaker competitors. |
| Subscription Algorithm Development | Usage-data prediction models capture lifetime value from chemically treated hair maintenance protocols. |
| Biopolymer Certification Acquisition | USDA BioPreferred and EU Ecolabel recognition create premium positioning anchors for sustainable variants. |
Methodological Framework
Trade publications, customs records, and SEC 10-K filings formed the secondary backbone, cross-referenced with primary interviews involving formulation chemists, salon distribution managers, trichology clinic directors, and regulatory affairs specialists. Bottom-up and top-down triangulation validated protein concentration specifications and channel pricing structures across mass-market and professional tiers.
Bottom-up modeling anchored volume estimates in salon service frequency data and supermarket replenishment velocity, while top-down constraints drew from aggregate personal care expenditure patterns. Segmentation dimensions spanned product type, form factor, end-user gender, and distribution channel. CAGR derivation incorporated protein hydrolysis technology adoption curves and regulatory enforcement intensity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU REACH substance restriction expansion and precision fermentation cost reduction trajectories. Practitioners should monitor biopolymer certification protocol adoption and trichology clinic network expansion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
United States Hair Care Market
Hair Care
Hair Oil Market
Hair Care
Malaysia Shampoo Market
Hair Care
Hair Relaxer Market
Hair Care
Global Hair Color Market
Hair Care
Organic Hair Care Market
Hair Care
Chile Hair Care Market
Hair Care
Artificial Hair Integration Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Hair Edge Tamer Market
Hair Care
Argentina Hair Care Market
Hair Care
Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Australia Hair Care Market
Hair Care
Global Premium Hair Care Market
Hair Care
Israel Hair Care Market