
 Europe Hair Care Market | 2026-2036
Europe Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hair Care Market Foresight
Drugstore and pharmacy distribution networks across Western Europe is reconfiguring as retailers consolidate shelf space for science-backed brands. L'Oréal S.A. leverages its dermocosmetic heritage to anchor pharmacy placements in France and Germany. Henkel AG & Co., KGaA sustains manufacturing scale through its Schwarzkopf professional division, which dominates salon-exclusive distribution. Unilever PLC competes via mass-market density, controlling value-tier shelf positioning across Tesco, Carrefour, and DM networks.
Europe Hair Care encompasses formulations designed to cleanse, condition, treat, and style human hair, typically comprising surfactant bases, emollients, active botanicals, and functional polymers at pH ranges optimized for cuticle integrity and scalp compatibility. Shampoo and conditioner together occupy the volume core, though margin pools concentrate in scalp treatment and hair serum segments where clinical positioning commands price premiums. Hair mask and hair oil applications are expanding fastest among women aged 35-55 seeking damage recovery protocols tied to heat styling and color processing. Distribution through beauty salons and specialty stores captures the highest per-unit economics, while online retailers erode traditional channel boundaries through subscription models and AI-driven personalization.
REACH registration requirements and the EU Green Deal framework are eliminating certain silicones and microplastics, forcing reformulation investments that smaller brands struggle to fund. ECHA substance evaluations and France's ANSM cosmetic surveillance tighten claims substantiation, particularly for anti-hair-fall and growth-stimulation products. CSRD reporting obligations will soon require supply-chain transparency on palm oil derivatives and water stewardship. Stakeholders must monitor regulatory sequencing across EMA-aligned cosmetics frameworks and decide whether to consolidate formulation platforms or fragment portfolios by member-state compliance tier.
Market Dynamics
REACH chemical safety standards and the EU Green Deal are forcing wholesale reformulation of surfactant systems, with biodegradable alternatives displacing conventional silicones and microplastics across mass and prestige tiers simultaneously.
Growth Catalysts
- Professional salon retail expansion:German and French salon chains are building captive product portfolios, converting service appointments into recurring at-home regimen sales.
- Pharmacy-channel prestige migration:Heritage dermocosmetic positioning in French pharmacies sustains price premiums unavailable through conventional grocery retail.
- Biodegradable surfactant mandates:ECHA substance evaluations under REACH registration requirements accelerate adoption of plant-derived cleansing bases.
Market Restraints
- Palm oil derivative supply concentration:Southeast Asian oleochemical supply chains expose formulators to input cost volatility and CSRD-mandated transparency reporting burdens.
- Claims substantiation friction:France's ANSM cosmetic surveillance tightens evidentiary standards for anti-hair-fall and growth-stimulation positioning.
- Reformulation capex intensity:Smaller brands lack balance sheet capacity to fund parallel compliance-tier portfolios for differentiated member-state requirements.
Strategic Opportunities
- Scalp treatment clinical positioning:Underserved demand for dermatologist-validated solutions creates margin expansion space between pharmacy and salon channels.
- Subscription personalization models:AI-driven hair diagnostic tools enable direct-to-consumer capture of replenishment cycles previously owned by retailers.
- Water stewardship differentiation:EU Green Deal water-use benchmarks reward brands with closed-loop manufacturing and concentrated formulation architectures.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in natural polymer stabilization and preservative-free systems commands premium compensation.
- Multi-jurisdiction claims harmonization:Divergent national interpretations of EMA-aligned cosmetics frameworks fragment marketing asset deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hair Care Market |
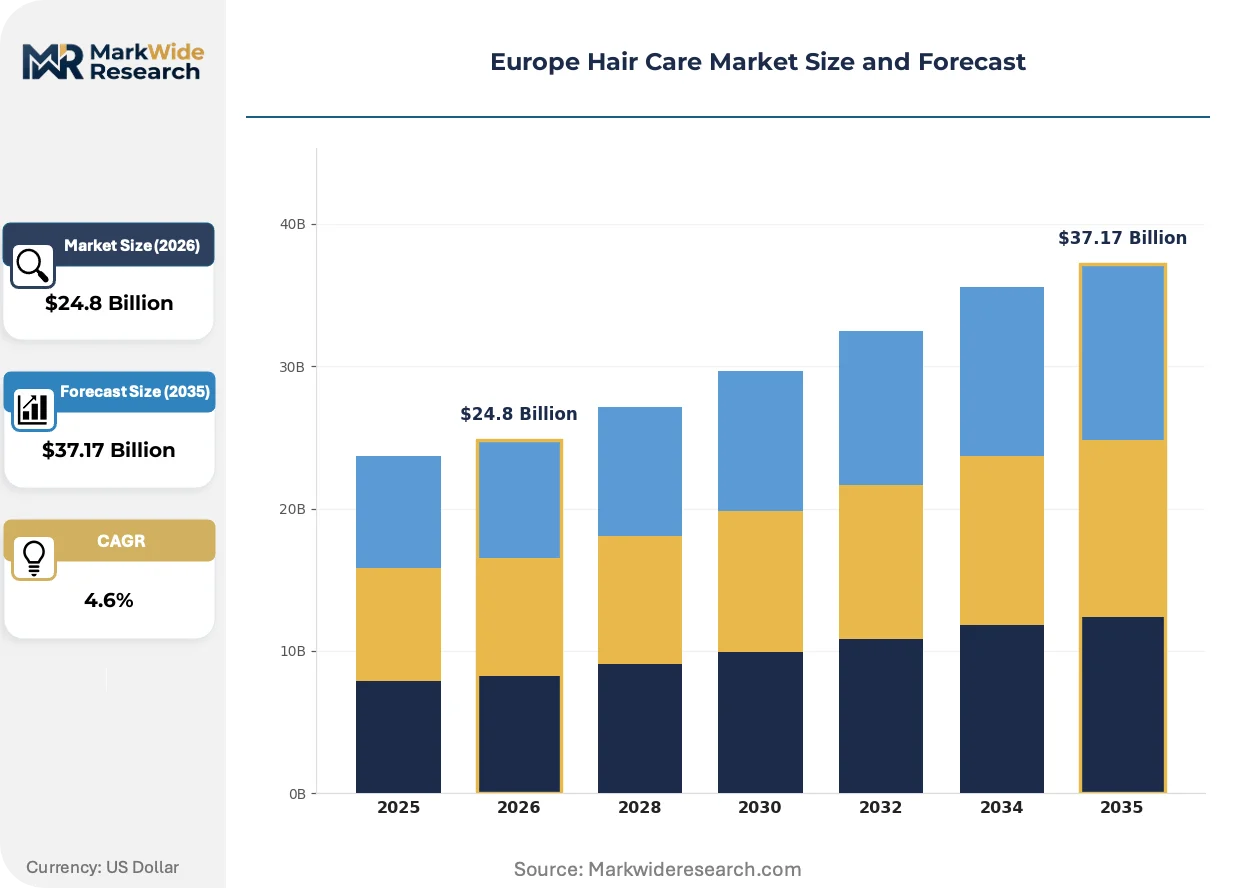
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Hair Serum, Hair Mask, Scalp Treatment Distribution Channel: Supermarkets, Beauty Salons, Online Retailers, Drugstores, Specialty Stores, Direct Selling End User: Men, Women, Children, Seniors Hair Concern: Hair Fall Control, Dandruff Management, Hair Repair, Color Protection, Moisturizing, Volume Enhancement |
| Companies Covered | Henkel AG & Co., KGaA, Unilever PLC, L'Oréal S.A., Procter & Gamble Company, Wella Company GmbH, Coty Inc., The Estée Lauder Companies Inc., Shiseido Company, Davines Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hair Care Market Shifts & Advancements
Formulation science is converging with digital diagnostics and circular material sourcing, compressing development cycles while elevating performance validation standards.
Biotechnology-derived active ingredients are hybridizing conventional botanical extracts with precision fermentation outputs. Prestige brands targeting women aged 35-55 are adopting these inputs fastest, integrating them into damage-recovery protocols for heat-styled and color-processed hair. This hybridizing of natural positioning with synthetic reproducibility is collapsing the traditional clean-versus-clinical positioning divide.
REACH registration requirements are eliminating cyclical silicones and microplastic-based conditioning agents from rinse-off formulations. The industrial consequence is accelerated R&D spending on polysaccharide and protein-derived film-forming alternatives. Salon-exclusive and pharmacy-channel products face the tightest compliance timelines, with German manufacturers leading reformulation investments.
Beauty advisors in physical retail are ceding replenishment ownership to algorithmic subscription platforms. Direct-to-consumer brands capture recurring revenue through AI-matched regimen sequencing, while traditional retailers respond with loyalty-program personalization. France and Germany show the steepest channel-shift velocity, where pharmacy and specialty-store density previously insulated incumbent distributors.
Europe Hair Care Market Segmentation
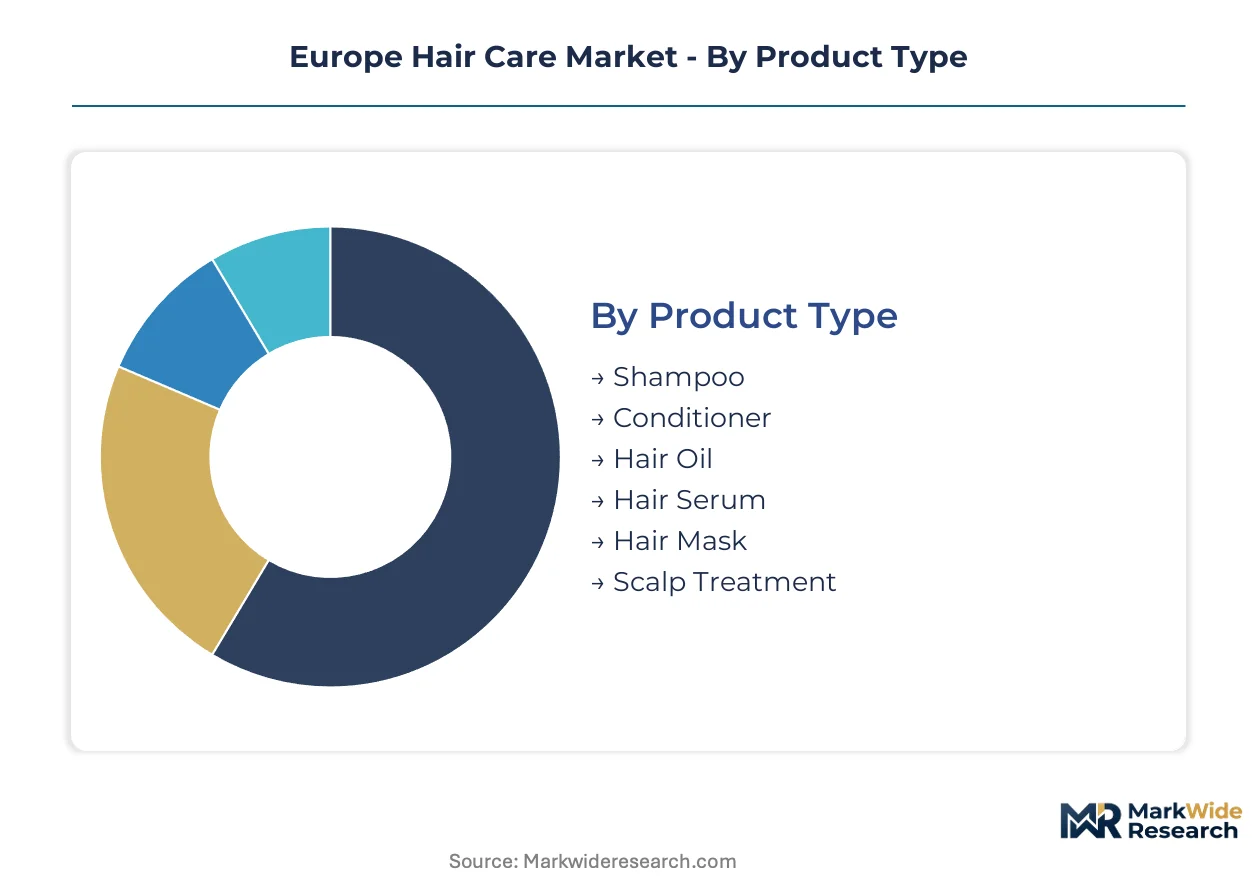
Segmentation in the Europe Hair Care Market reveals how formulation science, channel economics, and demographic targeting create distinct competitive arenas. Manufacturers must align R&D investment with the specific compliance and performance thresholds that govern each category.
Product Type:
Mature segments anchor volume while emerging formats capture margin expansion through clinical positioning and specialized protocols.
- Shampoo:Surfactant-based cleansing formulations dominate unit sales across mass and prestige tiers, with biodegradable base systems now mandated under REACH evaluations. German manufacturers lead reformulation investments to eliminate cyclical silicones.
- Conditioner:Cationic emulsion systems deliver cuticle sealing and detangling functionality; French pharmacy channels sustain premium pricing for heritage dermocosmetic positioning unavailable through grocery retail.
- Hair Oil:Silicone-free botanical blends target damage recovery protocols among heat-styling consumers.
- Hair Serum:Concentrated active delivery systems command the highest per-liter economics in salon-exclusive distribution.
- Hair Mask:Intensive treatment formats expand fastest among women aged 35-55 seeking color-processed hair rehabilitation.
- Scalp Treatment:Dermatologist-validated solutions occupy the underserved space between pharmacy clinical credibility and salon service authority.
Shampoo and conditioner together handle the majority of throughput; scalp treatment is expanding most quickly on share as clinical validation becomes a purchase prerequisite.
Distribution Channel:
Channel selection determines margin structure, with service-integrated and advice-dense formats outperforming transactional retail on per-unit economics.
- Supermarkets:High-velocity shelf space favors volume-tier formulations with mass-market price positioning; Carrefour and Tesco networks consolidate assortment toward science-backed heritage brands.
- Beauty Salons:Service-integrated retail captures recurring at-home regimen sales through captive product portfolios; German and French salon chains are expanding this model fastest.
- Online Retailers:Algorithmic subscription platforms erode traditional replenishment ownership through AI-matched regimen sequencing.
- Drugstores:DM and similar networks emphasize value-tier density with pharmacy-adjacent credibility.
- Specialty Stores:Curated assortment supports premium discovery and ingredient education.
- Direct Selling:Relationship-based distribution maintains foothold in Southern European markets with lower pharmacy-channel density.
Beauty salons and online retailers are climbing the fastest on revenue contribution; supermarkets retain the largest absolute volume base.
End User:
Demographic targeting shapes formulation architecture, with gender-specific and age-calibrated products commanding price premiums over universal formats.
- Women:Primary demand driver across all product categories, with concentrated investment in damage recovery and anti-aging scalp protocols.
- Men:Simplified regimen preference favors multifunctional formats; grooming subscription services target this segment with automated replenishment.
- Children:Gentle formulation requirements restrict active ingredient selection; tear-free surfactant systems dominate.
- Seniors:Emerging target for density-focused and gray-hair-specific positioning as population aging accelerates across France, Germany, and Italy.
Women account for the dominant share of expenditure; seniors represent the steepest expansion trajectory as age-specific claims gain regulatory clearance.
Hair Concern:
Concern-based positioning determines clinical substantiation requirements and permissible marketing claims under national surveillance frameworks.
- Hair Fall Control:France's ANSM imposes stringent evidentiary standards on growth-stimulation claims, fragmenting compliance-tier portfolios across member states.
- Dandruff Management:Antifungal active delivery requires pharmacy-channel placement in several European markets; OTC classification varies by jurisdiction.
- Hair Repair:Protein and ceramide-focused formulations target heat-styling and chemical-processing damage; biotechnology-derived actives are hybridizing conventional botanical extracts.
- Color Protection:UV filter and antioxidant systems extend dye longevity; salon-exclusive products lead on performance validation.
- Moisturizing:Hyaluronic acid and glycerin-based systems serve baseline conditioning needs across all price tiers.
- Volume Enhancement:Polymer-based film formers create temporary lift; natural alternatives displace conventional microplastic-containing technologies under EU Green Deal timelines.
Hair repair and color protection capture the highest margin pools; hair fall control is gaining share fastest as clinical positioning becomes a purchase differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
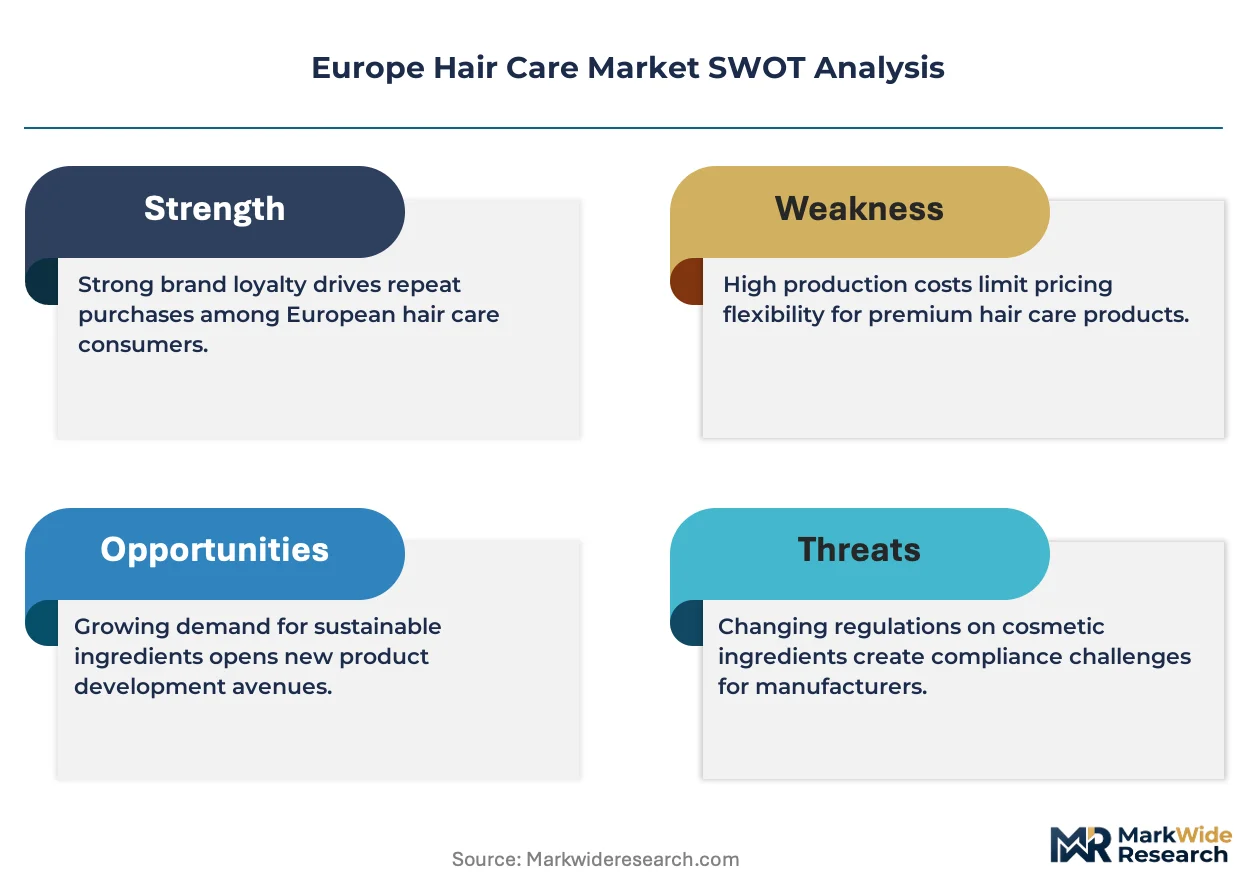
Pricing power in French pharmacies sustains 30-40% premiums over German mass-market equivalents, creating a two-tier revenue architecture across Western Europe. This asymmetry shapes capital allocation toward dermocosmetic positioning in Paris and Lyon corridors while German manufacturers optimize scale economics for export.
Germany
Professional salon chains in Munich and Hamburg are converting service appointments into captive at-home regimen sales. REACH registration requirements under ECHA jurisdiction are eliminating cyclical silicones from rinse-off formulations, forcing R&D spending on polysaccharide alternatives. North Rhine-Westphalia hosts the densest concentration of contract manufacturing facilities serving private-label supermarket brands.
France
Heritage dermocosmetic positioning in Parisian pharmacy networks sustains margin structures unavailable through grocery retail. ANSM cosmetic surveillance tightens evidentiary standards for anti-hair-fall claims, fragmenting compliance-tier portfolios. The Île-de-France corridor concentrates headquarters functions for prestige brands targeting export markets.
United Kingdom
Tesco and Boots networks are consolidating shelf space toward science-backed heritage brands with CSRD-aligned supply chain disclosures. The UK's departure from EU regulatory alignment creates parallel compliance obligations for brands serving both markets. Greater London retains the highest density of direct-to-consumer brand headquarters leveraging AI-driven personalization.
Italy
Specialty-store distribution in Milan and Rome supports premium discovery and ingredient education for color-protection protocols. Population aging across Lombardy and Veneto is accelerating demand for gray-hair-specific positioning. Italian contract manufacturers are investing in biotechnology-derived active fermentation capacity to serve French and German brand owners.
Spain
Direct-selling networks maintain foothold in Southern European markets with lower pharmacy-channel density, particularly in Andalusia and Valencia. Spanish consumers show elevated price sensitivity, favoring value-tier conditioning formats over premium treatment protocols. Barcelona hosts emerging formulation labs specializing in preservative-free systems for export to Northern European markets.
Europe Hair Care Market Competitive Landscape
Dermocosmetic heritage conglomerates and mass-market scale operators split the market between margin-intensive pharmacy channels and volume-driven retail networks. The competitive structure tilts toward consolidation at the top, with three to five holding companies controlling shelf placement across multiple price tiers. Strategic archetypes include science-backed prestige houses, manufacturing-scale consumer goods multinationals, and salon-exclusive professional specialists. Dominant competitive moves center on pharmacy-channel exclusivity agreements and reformulation investments to meet REACH biodegradability mandates.
Within the dermocosmetic heritage tier, L'Oréal S.A. and The Estée Lauder Companies Inc. occupy positions that exemplify pharmacy-channel prestige migration. Henkel AG & Co., KGaA represents the manufacturing-scale archetype through professional division structures. Unilever PLC anchors the mass-market density vector controlling value-tier positioning across consolidated retail networks. These three entities collectively illustrate how capital allocation diverges between clinical validation spending and shelf-space optimization.
| Leading Market Players |
|---|
| Henkel AG & Co., KGaA |
| Unilever PLC |
| L'Oréal S.A. |
| Procter & Gamble Company |
| Wella Company GmbH |
| Coty Inc. |
| The Estée Lauder Companies Inc. |
| Shiseido Company |
| Davines Group |
| Others |
Supply & Pricing Matrix
Palm oil derivative supply concentration in Southeast Asian oleochemical networks exposes European formulators to input cost volatility that simultaneously compresses mass-market margins and widens pharmacy-channel premium spreads. REACH-mandated reformulation investments and CSRD transparency reporting burdens force parallel supply chain restructuring across biodegradable surfactant sourcing and water stewardship certification tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order salon-exclusive protocols from standard supermarket shelf formats. Three-tier pricing structure across premium, standard, and economy levels anchors on pharmacy-channel heritage positioning, volume-scale mass retail, and private-label contract manufacturing respectively. Price differentiation hinges on clinical validation depth and dermocosmetic certification tier under ANSM surveillance frameworks. Cost compression in value-tier conditioning intensifies because DM and Carrefour networks consolidate assortment toward science-backed heritage brands with proven supply chain disclosures. Supermarket buyers exhibit highest price sensitivity; French pharmacy consumers demonstrate lowest elasticity due to dermatologist-validated trust transfer.
Supply Chain Analysis
Export-control regime angles under REACH registration requirements limit flows of cyclical silicones and microplastic-based conditioning agents into rinse-off formulations. Geographic supply concentration centers on Germany for professional salon manufacturing, France for dermocosmetic fermentation capacity, and Italy for biotechnology-derived active ingredient production. Raw material dependencies draw from Southeast Asian palm oil derivatives, Brazilian botanical extracts, and Chinese packaging substrates. Single-source vulnerability concentrates in oleochemical feedstocks subject to El Niño harvest disruptions. Distribution runs through pharmacy and salon channels for premium tiers, consolidated retail networks for volume, and algorithmic subscription platforms for direct-to-consumer capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic subscription platforms are reconstituting hair care as a platform-economy inflection, with AI-driven diagnostic interoperability between diagnostic hardware, regimen software, and replenishment logistics collapsing traditional channel boundaries.
For Market Incumbents: Insulate pharmacy-channel exclusivity agreements through accelerated dermatologist validation spending and captive salon portfolio expansion. Biodegradable surfactant R&D investment in North Rhine-Westphalia facilities defends against REACH compliance tier fragmentation. Backward integration into fermentation-derived active capacity secures supply continuity against Southeast Asian oleochemical volatility.
For New Entrants and Emerging Players: Pursue scalp treatment clinical positioning as the most penetrable white-space between pharmacy credibility and salon service authority. Target senior demographic segments across Lombardy and Veneto where gray-hair-specific claims gain regulatory clearance fastest. Deploy AI-matched subscription sequencing as primary go-to-market angle to bypass consolidated retail gatekeeping.
For Investors and Strategic Acquirers: The market sits at a reformulation capex intensity phase that favors manufacturing-scale operators with balance sheet capacity for parallel compliance-tier portfolios. Long-term viability across the projection horizon rests on water stewardship differentiation and closed-loop manufacturing certification. Acquisition target archetype: mid-cap biotechnology fermentation specialists serving French and German brand owners. Watch ECHA substance evaluation sequencing as inflection indicator for accelerated natural polymer stabilization adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Reformulation | REACH compliance eliminates cyclical silicones, forcing polysaccharide alternative R&D investment. |
| Pharmacy Channel Exclusivity Expansion | Heritage dermocosmetic positioning in French ANSM-regulated networks sustains 30-40% price premiums. |
| AI-Driven Subscription Personalization | Algorithmic regimen sequencing captures replenishment cycles previously owned by Tesco and Carrefour. |
| Water Stewardship Certification | EU Green Deal benchmarks reward closed-loop manufacturing and concentrated formulation architectures. |
| Scalp Treatment Clinical Validation | Dermatologist-validated solutions occupy underserved margin space between pharmacy and salon channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation chemists, pharmacy category buyers, salon chain procurement directors, and contract manufacturing facility managers. Secondary validation drew from ECHA substance evaluation databases, ANSM cosmetic surveillance filings, CSRD disclosure repositories, and Nielsen retail audit data across Carrefour, DM, and Boots networks. Bottom-up triangulation of unit economics by product format and channel combined with top-down reconciliation against national cosmetics trade flows anchored market sizing integrity.
Calibration approaches tested historical elasticity patterns against REACH regulatory sequencing and EU Green Deal implementation timelines across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end-user demographic, and hair concern-based positioning. CAGRs were derived from regression analysis of volume trajectories and price evolution by tier. Forecast inputs incorporated biotechnology-derived active ingredient adoption curves and pharmacy-channel shelf-space reconfiguration rates.
Sensitivities concentrate around ECHA evaluation acceleration, palm oil derivative supply disruptions, and ANSM claims substantiation tightening. Forecasts reflect assumptions on regulatory implementation pacing and consumer channel-shift velocity. Material shifts in REACH biodegradability deadlines or CSRD water-use benchmarking would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Latin America Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Australia Hair Removal Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
North America Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
Hair Care Appliances Market
Hair Care
Organic Hair Care Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Russia Hair Care Market
Hair Care
Mexico Hair Care Market
Hair Care
Qatar Hair Care Market
Hair Care
Rice Water Shampoo Market
Hair Care
Israel Hair Care Market