
 Australia Hair Removal Market | 2026-2036
Australia Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Hair Removal Market Intelligence
The Australia hair removal sector is recalibrating around a widening gap between clinical-grade laser systems and mass-market consumables. Alma Lasers leverages its medical-device heritage to anchor the premium clinic tier with multi-wavelength platforms. Caron Laboratories Pty Ltd sustains its position in waxing consumables through salon channel control and formulation specialization. Reckitt Benckiser Pty Ltd competes in retail with battery-operated devices that occupy pharmacy and supermarket aisles nationwide.
Australia hair removal encompasses the mechanical, thermal, chemical, and optical elimination of unwanted hair across consumer and professional settings, with clinical devices typically operating at wavelengths between 755 nm and 1064 nm to target melanin in follicular structures without damaging surrounding dermis. Laser Devices command the highest margin pools due to capital intensity and recurring maintenance revenue, while IPL systems penetrate the home-use segment through lower price points and reduced fluence settings. Dermatology Clinics represent the fastest-growing end-user channel as medical supervision becomes a preferred differentiator for permanent reduction procedures.
TGA registration requirements govern all therapeutic laser and IPL devices sold or operated in Australia, mandating clinical evidence standards that filter out lower-quality imports and elevate compliance costs for market entrants. The Australian Consumer Law complements this framework by imposing strict product safety and advertising standards on hair removal claims, particularly for at-home devices marketed with before-and-after imagery. Stakeholders must monitor evolving TGA reclassification proposals that could shift certain high-powered devices from cosmetic to medical regulatory pathways, fundamentally altering distribution requirements and operator qualifications.
Market Dynamics
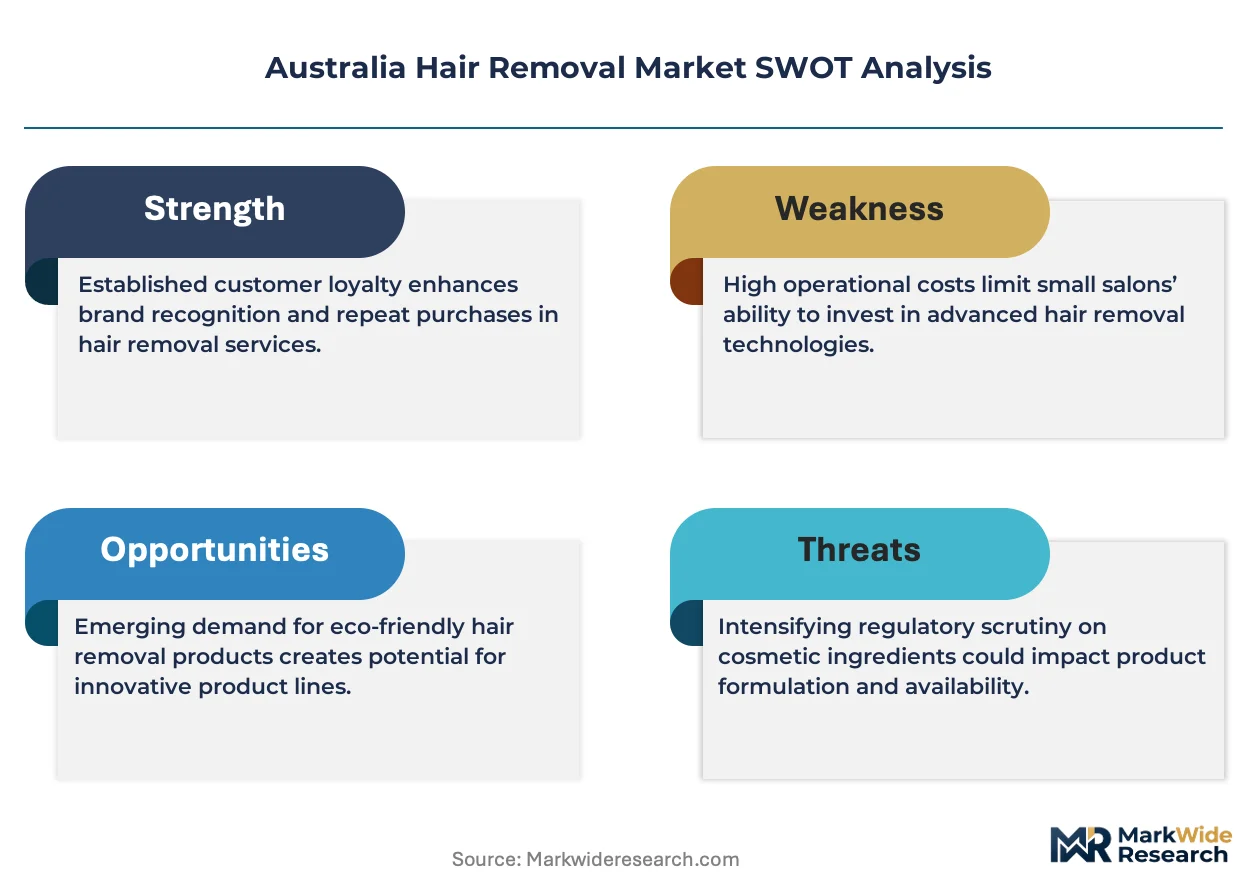
TGA reclassification proposals for high-powered laser devices are compressing the window between cosmetic and medical regulatory pathways, forcing clinic operators to recalibrate qualification requirements and capital deployment timelines ahead of formal rule changes.
Growth Catalysts
- Permanent reduction protocols:Australian dermatology clinics are expanding service menus beyond traditional aesthetics into medically supervised hair reduction, pulling demand from waxing salons toward clinical settings with higher compliance standards.
- TGA oversight intensification:Stricter clinical evidence requirements for laser and IPL device registration are filtering out low-quality imports and elevating average selling prices for compliant equipment.
- Metropolitan income concentration:Disposable income in Sydney and Melbourne exceeds national benchmarks, concentrating clinic density and device procurement in these two urban corridors.
Market Restraints
- Capital intensity for clinic operators:Multi-wavelength laser platforms require substantial upfront investment and recurring maintenance contracts, limiting independent clinic entry.
- IPL substitution pressure:Lower-priced home-use IPL devices with reduced fluence settings capture price-sensitive consumers seeking convenience over clinical efficacy.
- Compliance cost escalation:TGA registration mandates and Australian Consumer Law advertising standards impose documentation burdens that scale disproportionately for smaller device importers.
Strategic Opportunities
- Regional clinic penetration:Brisbane and Perth present underdeveloped demand relative to Sydney and Melbourne, with rising disposable income but lower clinic density per capita.
- Maintenance revenue streams:Laser device manufacturers can deepen recurring revenue through service contracts and consumable attachments as installed base expands.
- Channel hybridization:Salon-grade waxing specialists face margin pressure from clinical competitors, creating acquisition targets for dermatology chains seeking geographic footprint.
Industry Challenges
- Laser safety certification timelines:Clinic staff must complete TGA-recognized laser safety officer training, creating bottlenecks for rapid clinic scaling.
- Device integration complexity:New multi-wavelength platforms require retrofitting existing treatment rooms with enhanced cooling and electrical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Hair Removal Market |
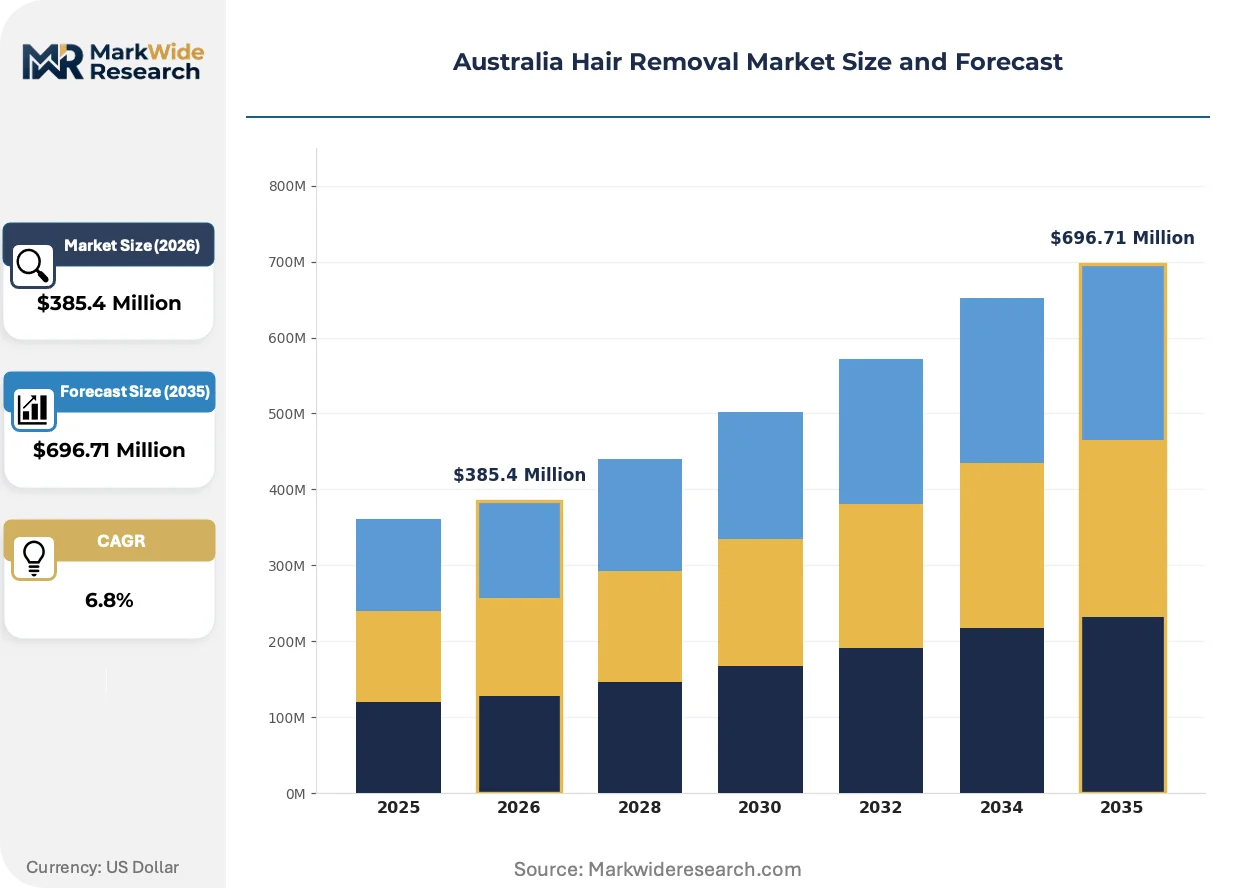
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Waxing Strips, Epilators, Creams End User: Households, Salons, Dermatology Clinics, Spas Application: Facial Hair Removal, Body Hair Removal, Sensitive Area Treatment, Professional Treatments Technology: IPL, Diode Laser, Electrolysis, Traditional Waxing |
| Companies Covered | Alma Lasers, Caron Laboratories Pty Ltd, Advanced Clinics Australia, Braun GmbH, Reckitt Benckiser Pty Ltd, Results Laser Clinics, Lumenis Be Ltd, Laser Clinics Australia, Silk Laser Clinics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Hair Removal Market Strategic Shifts & Innovations
Device manufacturers and clinic operators are navigating a bifurcation between clinical-grade capital equipment and accessible home-use alternatives, with regulatory pressure and consumer education shaping competitive positioning on both fronts.
Multi-wavelength laser platforms integrating 755 nm alexandrite, 808 nm diode, and 1064 nm Nd:YAG sources are electrifying treatment flexibility for diverse skin phototypes. Australian dermatology clinics with high Fitzpatrick scale patient diversity are adopting these systems to reduce device redundancy and maximize room utilization. The technology is compressing capital allocation decisions by substituting three single-wavelength machines with one configurable platform.
TGA consultation papers exploring reclassification of certain high-powered laser devices from cosmetic to medical pathways are forcing manufacturers to pre-position clinical evidence packages. Device sponsors must now submit prospective safety and efficacy data comparable to EU MDR Class IIa requirements, elevating barriers for new market entrants. Australian distributors with established regulatory affairs capabilities are consolidating relationships with overseas manufacturers lacking local compliance infrastructure.
Consumers are compressing their switching cycles between hair removal modalities, moving from waxing to IPL home devices to clinical laser treatments within shorter timeframes. This behavior fragments lifetime value across multiple channels and reduces brand loyalty for any single solution type. Sydney and Melbourne metropolitan clinics report higher consultation-to-treatment conversion rates when offering bundled multi-session packages with guaranteed outcomes.
Australia Hair Removal Market Segmentation
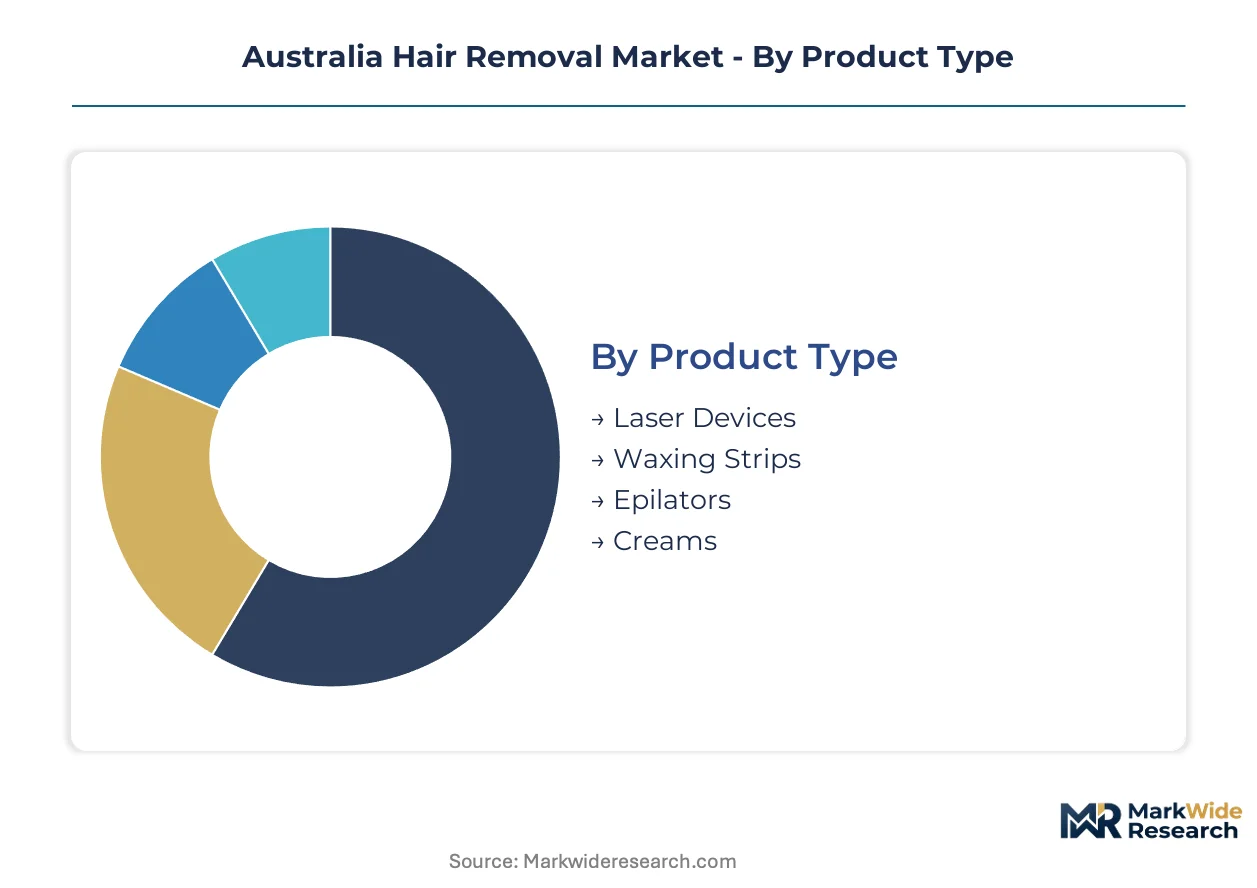
Hair removal purchasing patterns in Australia diverge sharply across clinical, professional, and consumer channels, with TGA compliance requirements and disposable income geography determining where each product type concentrates. Understanding these segment boundaries reveals why capital-intensive laser systems cluster in Sydney and Melbourne while consumables penetrate nationally through retail pharmacy networks.
Product Type:
Price sensitivity and purchase frequency separate buyers across this dimension, with capital equipment demanding multi-year amortization planning versus recurring consumable replenishment.
- Laser Devices:Multi-wavelength platforms operating between 755 nm and 1064 nm deliver permanent hair reduction through selective photothermolysis. Dermatology clinics in metropolitan Sydney and Melbourne dominate procurement, driven by TGA registration requirements that filter out lower-quality imports and elevate average selling prices for compliant equipment.
- Waxing Strips:Pre-coated fabric or polymer strips with rosin-based or sugar-derived adhesives enable rapid depilation without heating infrastructure. Salon chains across Brisbane and Perth sustain volume demand, though margin pressure from clinical competitors is forcing consolidation toward premium formulation differentiation.
- Epilators:Mechanical tweezer-array devices extract hair at the root through rotating or oscillating head mechanisms. Battery-operated variants occupy pharmacy and supermarket aisles nationwide, competing on convenience against both waxing and clinical alternatives.
- Creams:Thioglycolate or calcium hydroxide formulations chemically dissolve keratin structures above the skin surface. Price-sensitive households in regional Australia favor these for at-home facial and body applications where device investment is prohibitive.
Volume sits with waxing strips; growth tilts toward laser devices.
End User:
Regulatory burden and supervision requirements create distinct operational models across this category, from unregulated home use to TGA-registered clinical environments.
- Dermatology Clinics:Medically supervised facilities employing TGA-registered laser and IPL devices with laser safety officers on staff. These operators in Sydney and Melbourne are expanding service menus into permanent reduction protocols, pulling demand from traditional waxing salons.
- Salons:Non-medical establishments offering waxing, threading, and temporary hair removal services. Metropolitan concentration exceeds national averages, with independent operators facing acquisition pressure from dermatology chains seeking geographic footprint.
- Households:Individual consumers purchasing retail devices and consumables for autonomous use. Home-use IPL devices with reduced fluence settings capture this segment through lower price points and convenience positioning.
- Spas:Wellness-focused venues combining hair removal with broader aesthetic services. These operators typically avoid capital-intensive laser platforms, instead outsourcing permanent reduction referrals to affiliated dermatology clinics.
Revenue concentrates in dermatology clinics; household penetration expands most quickly.
Application:
Treatment area sensitivity and desired outcome duration shape modality selection, with permanent solutions commanding premium positioning for visible body zones.
- Body Hair Removal:Large-surface treatments including legs, arms, back, and chest where efficiency and speed drive equipment selection. Diode laser platforms at 808 nm dominate clinical protocols for these areas across Australian metropolitan corridors.
- Facial Hair Removal:Precision-demanding applications around brows, upper lip, and chin where skin sensitivity and hair density vary. Alexandrite lasers at 755 nm serve lighter skin phototypes in Sydney clinics with diverse patient populations.
- Sensitive Area Treatment:Bikini line and underarm applications requiring enhanced cooling and pain management. Nd:YAG wavelengths at 1064 nm penetrate deeper with reduced epidermal absorption, preferred for darker skin phototypes.
- Professional Treatments:Medically supervised protocols with guaranteed outcome commitments and multi-session bundling. Melbourne clinics report higher consultation-to-treatment conversion rates when offering these structured programs.
Procedure volume favors body hair removal; pricing power concentrates in professional treatments.
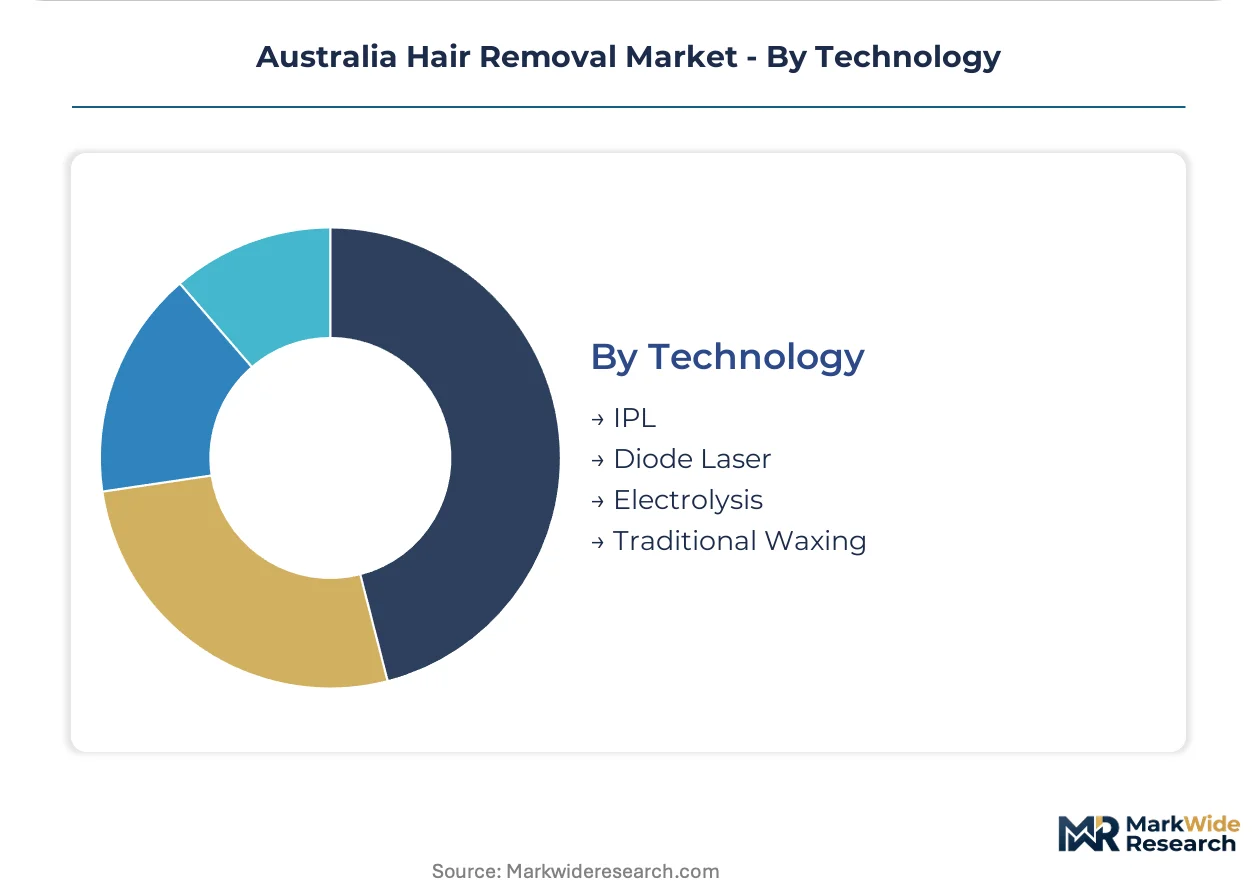
Technology:
Energy delivery mechanism and regulatory classification determine market access requirements and competitive moat durability for equipment manufacturers.
- Diode Laser:Semiconductor-generated coherent light at 808 nm optimized for melanin absorption in medium-dark skin phototypes. Alma Lasers and comparable manufacturers anchor premium clinic tier with these platforms in Australian metropolitan markets.
- IPL:Broadband incoherent light spanning 500-1200 nm with cut-off filters for skin-type adaptation. Home-use segment penetration is climbing the fastest due to lower price points and reduced fluence settings that avoid TGA medical device classification.
- Electrolysis:Galvanic or thermolysis current applied via fine probe to destroy individual follicles. Niche persistence for gray, white, or red hair lacking melanin targets for optical methods, concentrated in specialized Sydney clinics.
- Traditional Waxing:Mechanical extraction via heated resin or sugar paste application. Salon channel control sustains this method's volume position despite clinical competition, with formulation specialization driving margin recovery.
Installed base tilts toward traditional waxing; technology transition favors diode laser platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne dominate Australian hair removal demand, with clinic density and disposable income concentration exceeding national benchmarks by significant margins. Metropolitan corridors in these two cities account for the majority of laser device procurement and permanent reduction protocol adoption.
New South Wales
Sydney's eastern suburbs and North Shore host the densest cluster of dermatology clinics offering TGA-registered laser treatments. The state's therapeutic goods regulator enforces strict clinical evidence standards for device registration, filtering lower-quality imports from market entry. Parramatta and Liverpool emerging corridors show rising clinic penetration as operators seek rent arbitrage against premium CBD locations.
Victoria
Melbourne's inner-city and southeastern suburbs concentrate demand for multi-wavelength laser platforms serving diverse skin phototypes. Victorian health department oversight complements TGA requirements with additional laser safety officer certification mandates. Geelong and Ballarat present expansion targets for clinic chains seeking geographic diversification beyond the capital.
Queensland
Brisbane's clinic density per capita trails Sydney and Melbourne despite comparable disposable income growth. Queensland's workplace health and safety framework governs laser operator certification with requirements mirroring TGA-recognized training standards. Gold Coast tourism economy supports seasonal demand spikes for aesthetic services including hair removal protocols.
Western Australia
Perth's isolated market structure limits device supplier competition and elevates equipment procurement costs for independent operators. The state's consumer protection regulator enforces Australian Consumer Law advertising standards on hair removal outcome claims. Fremantle and Subiaco sub-regions show emerging clinic formation as metropolitan population concentrates.
Australia Hair Removal Market Key Industry Players
Premium-margin players sit above commodity-margin players across the technology-capability spectrum, with clinical-grade laser manufacturers commanding substantially higher returns than retail consumable suppliers. The market structure bifurcates between capital-intensive device sponsors and distribution-focused consumable marketers. Three archetypes dominate: medical-device heritage manufacturers, salon-channel consumable specialists, and retail-brand consumer electronics distributors. Competitive moves concentrate on clinic chain acquisition for geographic footprint expansion and maintenance contract deepening for recurring revenue capture.
Within the medical-device tier, Alma Lasers and Lumenis Be Ltd exemplify capital-equipment sponsors leveraging TGA registration requirements as competitive moats. Caron Laboratories Pty Ltd occupies a distinct position as a consumable-focused operator with salon-channel control. Reckitt Benckiser Pty Ltd anchors the retail-distribution vector with pharmacy and supermarket network penetration.
| Leading Market Players |
|---|
| Alma Lasers |
| Caron Laboratories Pty Ltd |
| Advanced Clinics Australia |
| Braun GmbH |
| Reckitt Benckiser Pty Ltd |
| Results Laser Clinics |
| Lumenis Be Ltd |
| Laser Clinics Australia |
| Silk Laser Clinics |
| Others |
Cost & Logistics Intelligence
Clinical-grade laser platform certification tiers bifurcate Australian hair removal markets into TGA-registered premium channels and unregulated commodity consumables, with this divergence compressing margins at the salon tier while elevating procurement costs for compliant device operators. Waxing consumables flow through pharmacy networks at standardized price points, whereas capital equipment sponsors anchor pricing to outcome guarantees and maintenance bundling.
Pricing Analysis
Outcome-based pricing anchors TGA-registered laser systems, with device sponsors bundling multi-session treatment guarantees and laser safety officer training into capital lease structures. Price differentiation separates premium multi-wavelength platforms with 755-1064 nm flexibility from single-wavelength diode systems and home-use IPL alternatives. Cost compression in salon-grade waxing consumables intensifies as clinical competitors capture permanent reduction demand. Households exhibit highest price sensitivity, gravitating toward battery-operated epilators and depilatory creams, while dermatology clinics prioritize throughput reliability over unit economics.
Supply Chain Analysis
Domestic-content thresholds under Australian Consumer Law reshape sourcing for consumable manufacturers, with local formulation and packaging operations preferred for salon-channel waxing strips. Laser device supply concentrates in Israel, Germany, and the United States, with Alma Lasers and Lumenis Be Ltd anchoring premium platform distribution. Optical components, cooling systems, and semiconductor laser diodes constitute critical input dependencies. Single-source vulnerability runs through specialized 808 nm diode foundries. Distribution runs through TGA-authorized medical device distributors with established regulatory affairs capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian hair removal markets present a consolidation play as TGA reclassification proposals and capital intensity pressures force independent salon operators toward acquisition or exit.
For Market Incumbents: To counter IPL substitution pressure from home-use devices, dermatology clinic chains should deepen maintenance revenue through service contract bundling and consumable attachment lock-in. Backward integration into laser safety officer training programs addresses certification bottlenecks while creating switching costs for competing clinic operators. For New Entrants and Emerging Players: Begin with regional clinic penetration in Brisbane and Perth, where disposable income growth outpaces clinic density formation. Target acquisition of distressed independent waxing salons facing margin compression from clinical competitors. A white-label IPL distribution partnership with pharmacy chains offers the most penetrable retail entry vector. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale dermatology clinic chains given TGA reclassification catalysts that will elevate compliance barriers and concentrate market share. Long-term viability favors operators with established laser safety infrastructure and multi-wavelength platform installed bases. Monitor TGA consultation paper finalization as the signal for accelerated consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Clinic Chain Acquisition | Geographic footprint expansion captures underpenetrated Brisbane and Perth metropolitan corridors. |
| Maintenance Contract Deepening | Recurring revenue capture from service agreements and consumable attachments stabilizes cash flows. |
| Laser Safety Officer Training Investment | In-house certification capacity removes scaling bottlenecks imposed by TGA-recognized external programs. |
| Multi-Wavelength Platform Adoption | 755-808-1064 nm flexibility reduces device redundancy while serving diverse Fitzpatrick scale populations. |
| Channel Hybridization | Salon-grade waxing specialists facing margin pressure become acquisition targets for dermatology chains. |
Research Approach
TGA registration databases, Australian Bureau of Statistics trade data, and SEC filings from listed device manufacturers formed the secondary backbone, supplemented by primary interviews with dermatology clinic operators, laser safety officers, and pharmacy category buyers. Bottom-up and top-down triangulation validated procurement volumes and pricing structures across Sydney, Melbourne, Brisbane, and Perth metropolitan markets.
Bottom-up modeling aggregated clinic-level device procurement, treatment session volumes, and consumable replenishment patterns across end-user segments. Segmentation dimensions included product type, technology platform, application area, and geographic corridor. CAGRs were derived from installed base expansion rates and per-clinic revenue intensity trends, with TGA regulatory timeline assumptions informing adoption curve phasing.
TGA reclassification delays, IPL device safety incidents triggering stricter oversight, and macroeconomic pressure on discretionary aesthetic spending are the dominant revision risks. Forecasts reflect assumptions regarding regulatory pathway stability and metropolitan income concentration persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Europe Hair Care Market
Hair Care
Hair Edge Tamer Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Hair and Scalp Care Market
Hair Care
Brazil Hair Care Market
Hair Care
Russia Hair Care Market
Hair Care
Argentina Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Global Hair Color Market
Hair Care
Italy Hair Care Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Protein Shampoo Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Latin America Hair Care Market