
 South Africa Cosmetics and Personal Care Products Market | 2026-2036
South Africa Cosmetics and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Cosmetics and Personal Care Products Market Analytics
Premium-grade formulation standards is rotating through the South African cosmetics sector as consumers prioritize dermatologically tested and ethically sourced products. L'Oreal SA leverages its advanced research capabilities to sustain innovation pipelines across skincare and fragrance lines. Adcock Ingram anchors its position through deep distribution networks spanning pharmacies and clinics nationwide. Unilever PLC competes aggressively via volume-driven personal care portfolios priced for mass-market penetration.
South Africa cosmetics and personal care products encompass topical formulations manufactured under Good Manufacturing Practice protocols, with stability testing typically conducted at degrees Celsius ranges simulating regional climate conditions. These products serve consumer hygiene, aesthetic enhancement, and skin health maintenance across diverse ethnic skin types and humidity exposures. Skincare commands the largest revenue pool due to elevated awareness of sun damage and hyperpigmentation concerns among the population. Haircare represents the fastest-expanding category as textured hair specialization drives product innovation and salon-service bundling. Fragrance maintains premium margin concentration through limited-edition releases and celebrity-endorsed positioning in Sandton and Umhlanga retail corridors.
South Africa's National Regulator for Compulsory Specifications mandates compliance with SANS standards for cosmetic safety, while the Department of Health enforces labeling transparency under the Foodstuffs, Cosmetics and Disinfectants Act. The Consumer Protection Act further shapes market access by requiring substantiated claims and prohibiting misleading ingredient disclosures. Stakeholders must monitor evolving amendments to compulsory specification timelines and align reformulation cycles with regulatory publication schedules.
Market Dynamics
Textured hair specialization and sun-damage awareness are restructuring competitive priorities across South Africa's cosmetics sector, forcing manufacturers to reformulate for diverse ethnic skin types and humidity exposures while navigating mandatory SANS compliance timelines.
Growth Catalysts
- SANS 1555 Cosmetic Safety Standards:Mandatory stability testing protocols under the National Regulator for Compulsory Specifications are elevating formulation quality thresholds and accelerating premium product development cycles.
- Johannesburg-Cape Town Urban Corridor:Dense retail networks and rising professional incomes in Gauteng and Western Cape provinces are concentrating demand for dermatologically tested skincare routines.
- Ethnic Skin Specialization:Hyperpigmentation and sun damage concerns among diverse population groups are driving innovation in SPF-integrated daily skincare formulations.
Market Restraints
- Petrochemical Input Volatility:Surfactant and silicone feedstock price instability compresses margin predictability for mass-market haircare and skincare manufacturers.
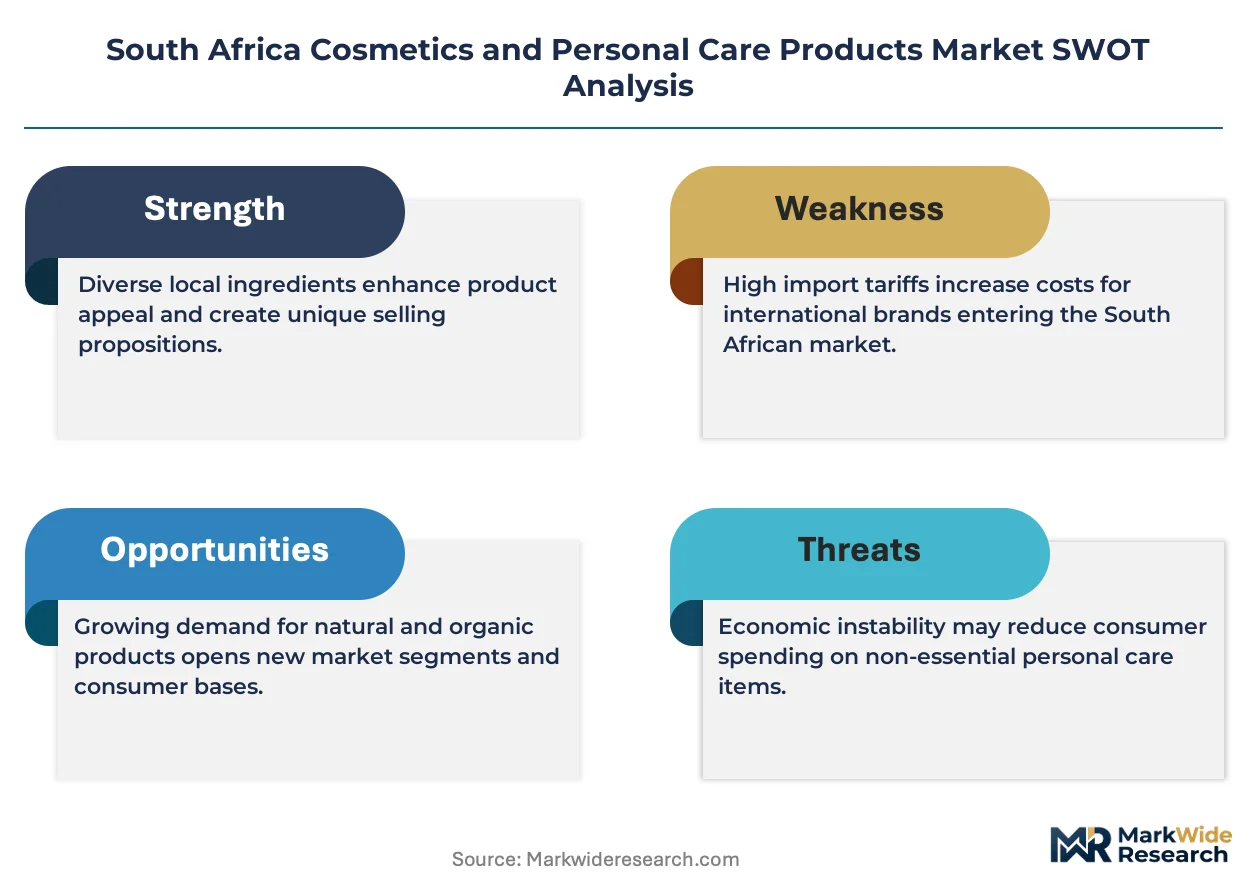
- Import Dependency Concentration:Active pharmaceutical ingredients and specialized emulsifiers flow predominantly through Durban port logistics, creating single-point vulnerability.
- Shelf-Life Technical Limitation:Climate simulation testing requirements struggle to replicate extreme humidity and temperature swings across Limpopo, KwaZulu-Natal, and Northern Cape storage conditions.
Strategic Opportunities
- Eastern Cape Underpenetration:Port Elizabeth and East London retail corridors remain underserved for premium salon-service bundled haircare relative to Gauteng density.
- Pharmacy-Channel Convergence:Clinic-adjacent cosmetic dispensing is merging dermatological consultation with product recommendation in Sandton and Umhlanga precincts.
- Consumer Protection Act Tailwind:Substantiated claims mandates are rewarding brands with clinical trial investments while penalizing misleading ingredient disclosures.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Cosmetic chemists with ethnic skin specialization remain concentrated in Johannesburg, constraining Cape Town and Durban R&D expansion.
- SANS Amendment Cycle Compression:Reformulation timelines must align with unpredictable compulsory specification publication schedules from the National Regulator.
- Legacy ERP Integration Friction:Batch traceability requirements for Good Manufacturing Practice compliance strain inventory systems at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Cosmetics and Personal Care Products Market |
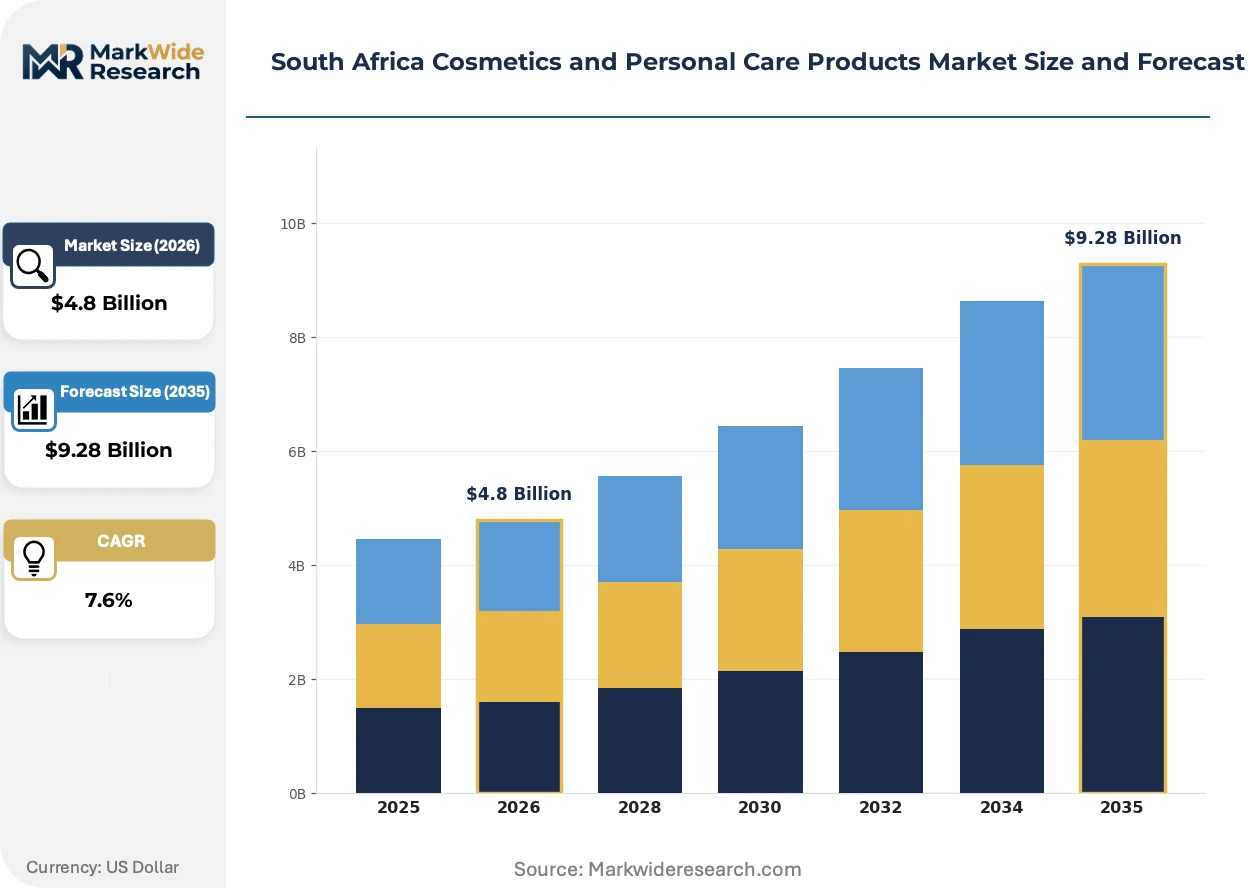
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance End User: Men, Women, Teens, Children Distribution Channel: Online, Supermarkets, Drugstores, Specialty Stores Packaging Type: Tubes, Glass Bottles, Jars, Sachets |
| Companies Covered | Beiersdorf AG, Procter & Gamble Company, L'Oreal SA, Adcock Ingram, Colgate-Palmolive Company, The Estée Lauder Companies Inc., Natura & Co, AVI Limited, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Cosmetics and Personal Care Products Market Evolving Landscape
Biotechnology-derived actives and algorithmic skin diagnostics are reconfiguring how South African consumers evaluate efficacy claims, while regulatory transparency mandates accelerate ingredient disclosure standards.
Biotechnology fermentation processes for ceramide and peptide production are supplanting petrochemical-derived emollients in premium skincare formulations. Young urban professionals in Sandton and Rosebank are adopting these biotech actives faster than mass-market segments. This ingredient shift is compressing price premiums for traditional luxury brands while enabling challenger labels to claim clinical equivalence.
The National Regulator for Compulsory Specifications is tightening SANS 1555 stability testing protocols for products claiming dermatological benefits. Manufacturers must now submit accelerated aging data specific to regional humidity and UV exposure profiles. Skincare lines with SPF claims face the steepest compliance burden, with several brands withdrawing marginal products rather than funding expanded testing.
Salon-service bundling is displacing standalone retail purchases for textured hair maintenance. Independent stylists in Soweto and Khayelitsha are integrating proprietary product lines into appointment workflows, capturing margin that previously flowed to mass retailers. This channel capture is most advanced in Gauteng province, where stylist training academies double as product distribution nodes.
South Africa Cosmetics and Personal Care Products Market Segmentation
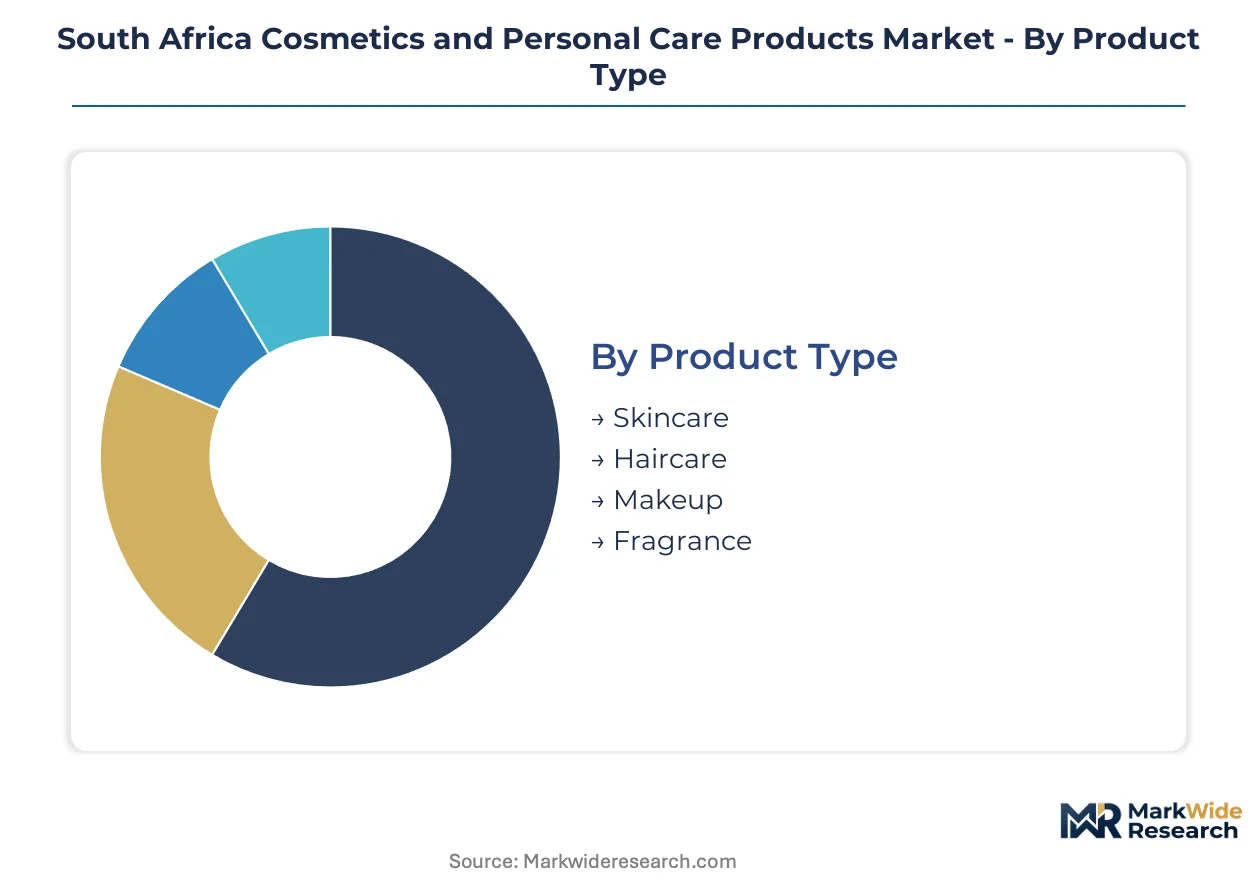
Channel fragmentation across South Africa's cosmetics sector demands granular segmentation to map how premium formulations reach distinct consumer clusters. Understanding product-distribution pairings reveals where margin capture concentrates versus where volume liquidation dominates.
Product Type:
Channel-mix patterns vary sharply across product categories, with skincare and fragrance commanding premium retail footprints while haircare penetrates through salon-service bundling and mass-market liquidators.
- Skincare:SPF-integrated daily formulations dominate revenue pools, driven by hyperpigmentation awareness among Gauteng and Western Cape urban professionals. Dermatologically tested lines concentrate in Sandton pharmacy-adjacent clinics and Rosebank specialty corridors.
- Haircare:Textured hair specialization is restructuring competitive priorities, with salon-service bundling in Soweto and Khayelitsha displacing standalone retail purchases. Independent stylists now capture margin previously flowing to mass retailers through proprietary product integration.
- Makeup:Color cosmetics flow predominantly through supermarket promotional cycles and online influencer-driven drops, with limited-edition releases concentrating in Umhlanga retail nodes.
- Fragrance:Premium margin concentration depends on celebrity-endorsed positioning and limited-edition releases in Sandton and Umhlanga corridors, with mass-market variants liquidating through drugstore chains.
Skincare dominates installed base. Haircare is where expansion concentrates.
End User:
Customer lifetime value calculations diverge across demographic tiers, with professional women in Johannesburg and Cape Town sustaining premium skincare repurchase rates while teen segments drive trial volume through digital-native channels.
- Women:Urban professionals aged 25-40 in Gauteng and Western Cape provinces anchor premium skincare and fragrance expenditure, with dermatological consultation driving clinic-adjacent product dispensing in Sandton precincts.
- Men:Grooming category expansion concentrates among young professionals in Johannesburg, with beard care and scalp health formulations penetrating through barbershop-service bundling in township retail nodes.
- Teens:Digital-native acquisition patterns dominate, with TikTok-driven trial cycling through sachet formats and online flash promotions before potential graduation to full-size premium lines.
- Children:Mild-formulation demand concentrates in middle-income Durban and Pretoria households, with hypoallergenic claims requiring SANS 1555 compliance documentation for pharmacy channel placement.
Women sustain revenue base. Men are gaining share fastest.
Distribution Channel:
Cost-to-serve economics separate premium margin capture from volume liquidation, with online and specialty stores extracting full price while supermarkets and drugstores trade margin for turnover velocity.
- Online:Direct-to-consumer platforms enable algorithmic skin diagnostics and subscription replenishment models, with young urban professionals in Johannesburg adopting biotech-actives faster than mass-market segments through this channel.
- Supermarkets:Volume-driven personal care portfolios price for mass-market penetration, with promotional cycling compressing margin predictability for manufacturers dependent on surfactant and silicone feedstocks.
- Drugstores:Clinic-adjacent cosmetic dispensing merges dermatological consultation with product recommendation, particularly in Sandton and Umhlanga precincts where pharmacy-channel convergence rewards clinical trial investments.
- Specialty Stores:Premium fragrance and skincare lines maintain margin through limited-edition releases and experiential retail formats in Sandton and Rosebank corridors.
Specialty stores anchor premium positioning. Online is climbing the fastest.
Packaging Type:
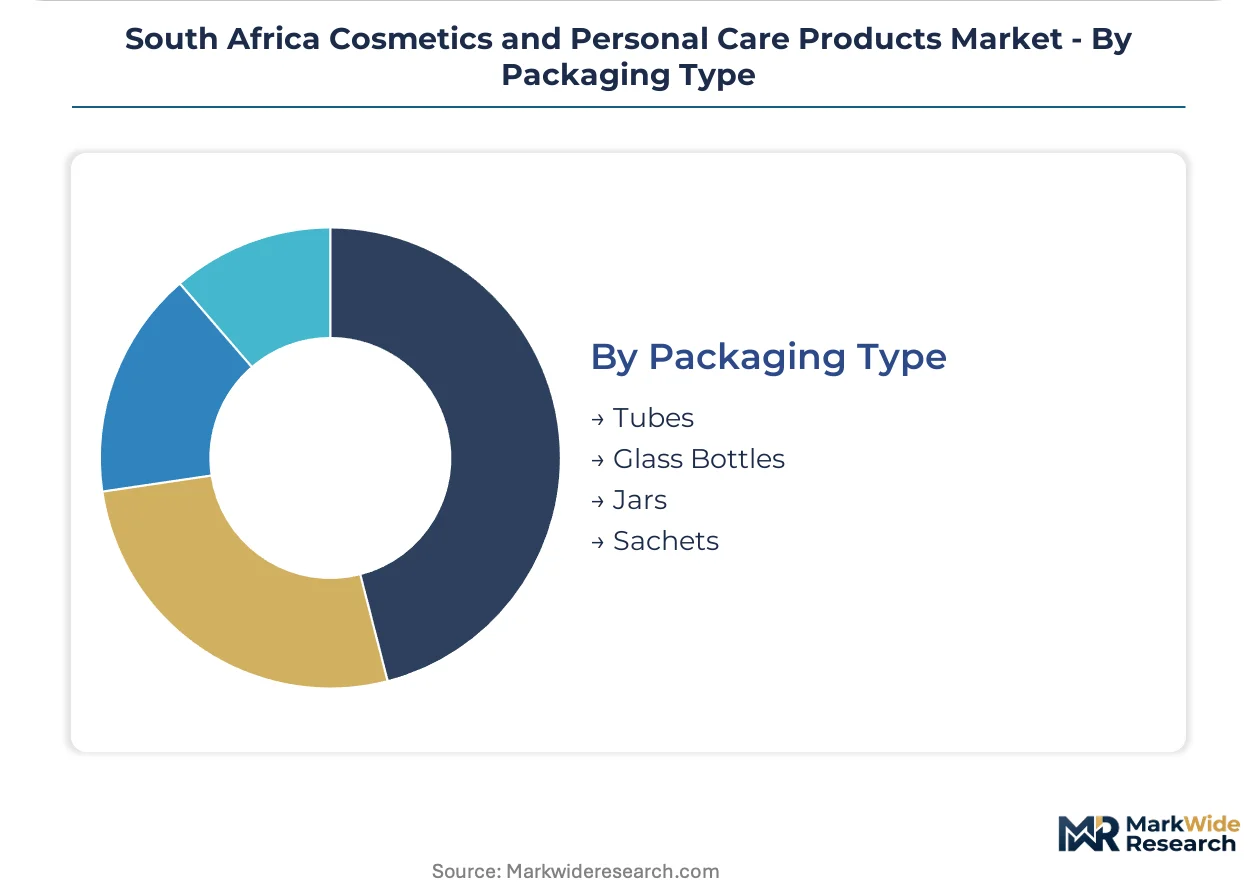
Supply concentration and climate resilience dictate format selection, with durability requirements under extreme humidity and temperature swings across Limpopo, KwaZulu-Natal, and Northern Cape storage conditions favoring specific material choices.
- Tubes:Flexible aluminum-plastic laminates dominate mass-market haircare and skincare, with Durban port logistics feeding active pharmaceutical ingredients and specialized emulsifiers into tube-forming facilities.
- Glass Bottles:Premium fragrance and serum formulations concentrate in Western Cape and Gauteng retail corridors, with weight and breakage risk limiting penetration beyond urban professional segments.
- Jars:Wide-mouth formats suit thick cream formulations targeting hyperpigmentation and sun damage concerns, with double-wall construction addressing stability testing requirements for regional climate simulation.
- Sachets:Single-use trial formats drive teen segment acquisition and township market penetration, with low unit economics enabling price accessibility despite compressed manufacturer margins.
Tubes dominate unit volume. Sachets are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for active pharmaceutical ingredients and specialized emulsifiers flows predominantly through Durban port logistics, creating concentrated supply vulnerability while Gauteng and Western Cape provinces absorb the majority of finished product distribution.
Gauteng Province
Dense retail networks in Johannesburg and Pretoria concentrate demand for dermatologically tested skincare routines among young urban professionals. The National Regulator for Compulsory Specifications enforces SANS 1555 cosmetic safety standards on all formulations entering pharmacy-adjacent clinics in Sandton precincts. Rosebank specialty corridors anchor premium fragrance and biotech-active skincare distribution.
Western Cape Province
Cape Town's professional demographic sustains elevated repurchase rates for SPF-integrated daily formulations addressing hyperpigmentation concerns. Provincial environmental health services align with national Foodstuffs, Cosmetics and Disinfectants Act enforcement for labeling transparency. Umhlanga retail nodes in the broader coastal corridor channel celebrity-endorsed fragrance positioning.
KwaZulu-Natal Province
Durban port logistics handle the bulk of surfactant and silicone feedstock imports for mass-market haircare manufacturers. Humidity and temperature storage challenges across the province strain stability testing protocols originally designed for temperate climates. Independent stylists in township retail nodes integrate proprietary textured hair product lines into appointment workflows.
Eastern Cape Province
Port Elizabeth and East London retail corridors remain underserved for premium salon-service bundled haircare relative to Gauteng density. Consumer Protection Act substantiated claims mandates apply uniformly, yet pharmacy-channel convergence lags the Sandton model. Local manufacturing presence is minimal, forcing reliance on interstate supply chains.
Limpopo and Northern Cape
Extreme climate conditions in these provinces expose shelf-life technical limitations in existing stability testing regimes. SANS amendment cycles from the National Regulator rarely account for storage temperature swings in remote distribution networks. Sparse retail infrastructure funnels demand toward supermarket promotional cycles rather than specialty store formats.
South Africa Cosmetics and Personal Care Products Market Competitive Landscape
Listed leaders compete with private specialists across formulation quality and channel access dimensions, producing a tiered structure where multinational scale confronts local distribution depth. Three to five global conglomerates anchor premium positioning through research capabilities, while mid-tier domestic players defend via pharmacy and clinic adjacency. Strategic archetypes separate biotech-active innovators, mass-market volume drivers, and salon-service bundlers. Competitive moves concentrate on portfolio diversification into ethnic skin specialization and geographic expansion into underpenetrated Eastern Cape corridors.
Within the multinational tier, L'Oreal SA and Unilever PLC exemplify divergent approaches to the South African market, with the former representing advanced research pipeline investment and the latter anchoring volume-driven personal care penetration. Adcock Ingram occupies a position bridging domestic distribution depth with clinic-adjacent cosmetic dispensing capabilities. These three entities collectively illustrate how competitive positioning splits between premium formulation credibility and mass-market accessibility.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Procter & Gamble Company |
| L'Oreal SA |
| Adcock Ingram |
| Colgate-Palmolive Company |
| The Estée Lauder Companies Inc. |
| Natura & Co |
| AVI Limited |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Durban port chemical handling facilities shapes both import cost structures and domestic price floors for surfactant-dependent formulations. Scale economies in bulk petrochemical processing concentrate pricing power among feedstock suppliers, forcing mid-tier manufacturers to absorb margin compression or cede volume share.
Pricing Analysis
Young urban professionals in Johannesburg and Cape Town anchor premium pricing for dermatologically tested skincare, with three-tier pricing structure across premium, standard, and economy levels stratifying by clinical validation depth and SPF integration. Price differentiation hinges on SANS 1555 certification status and biotech-active ingredient sourcing, with pharmacy-channel convergence in Sandton extracting maximum willingness-to-pay. Cost compression in mass-market haircare intensifies because petrochemical input volatility erodes manufacturer margins. Township retail nodes and teen digital-native segments exhibit highest price sensitivity, while clinic-adjacent dispensing commands lowest elasticity.
Supply Chain Analysis
China and India anchor active pharmaceutical ingredient and specialized emulsifier production feeding South African formulation facilities. Domestic manufacturing draws from imported ceramide precursors, peptide fermentation feedstocks, and silicone derivatives, with batch traceability requirements straining mid-tier ERP systems. Single-point vulnerability concentrates at Durban port logistics, where customs processing delays cascade through Gauteng distribution networks. Distribution runs through pharmacy-adjacent clinics for premium tiers, supermarket promotional cycles for mass-market liquidation, and independent stylist networks for textured hair bundling in township nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SANS 1555 compliance entrenchment creates defensive moats for established players, as reformulation timelines and testing investments erect switching costs that challenger brands struggle to replicate.
For Market Incumbents: Fortify clinic-adjacent dispensing relationships in Sandton and Umhlanga precincts through exclusive dermatological consultation partnerships. Deepen backward integration into biotech-active ingredient sourcing to insulate margin from petrochemical volatility, while accelerating Eastern Cape distribution buildout before competitor salon-service bundling captures Port Elizabeth and East London corridors. For New Entrants and Emerging Players: Differentiate on algorithmic skin diagnostics and subscription replenishment models targeting Rosebank and Sandton young professionals. White-space concentration in Eastern Cape pharmacy-channel convergence and Soweto stylist-academy distribution nodes offers lowest competitive density. Direct-to-consumer platforms with TikTok-native acquisition funnels provide the most penetrable go-to-market angle for teen segment trial conversion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotech-active innovators with clinical trial investments already amortized across SANS 1555 submission cycles. Long-term viability hinges on regulatory entrenchment depth rather than brand equity alone, with five-to-ten-year windows rewarding pharmacy-channel convergence capabilities. Watch for National Regulator amendment publications accelerating compulsory specification timelines as inflection signals for consolidation pressure on undercapitalized mid-tier formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Clinic-Adjacent Dispensing Expansion | Sandton and Umhlanga pharmacy convergence merges dermatological consultation with premium product recommendation workflows. |
| Biotech-Active Ingredient Backward Integration | In-house ceramide and peptide production insulates margin from petrochemical feedstock volatility compressing mass-market tiers. |
| Eastern Cape Distribution Buildout | Port Elizabeth and East London retail corridors remain underserved relative to Gauteng salon-service bundling density. |
| SANS 1555 Certification Investment | Accelerated stability testing protocols reward clinical trial investments while penalizing marginal product withdrawals. |
| Stylist-Academy Distribution Integration | Soweto and Khayelitsha training nodes capture margin previously flowing to mass retailers through proprietary textured hair lines. |
Research Methodology
Operator-level perspectives from cosmetic chemists, pharmacy procurement managers, salon distribution heads, and National Regulator compliance officers anchored the qualitative base. Primary interviews triangulated with secondary validation from SANS standard publications, Foodstuffs Act enforcement records, customs import data, and Nielsen retail audit coverage. Bottom-up volume modeling across product type, end user, distribution channel, and packaging format segments converged with top-down macroeconomic anchoring.
Sensitivity analysis framed volume and value outputs across the projection horizon, with segmentation dimensions spanning skincare SPF integration levels, haircare salon-service bundling intensity, pharmacy versus supermarket channel mix, and regional climate storage requirements. CAGRs derived from regression-based trend extrapolation moderated by regulatory amendment cycle uncertainty and petrochemical input volatility assumptions. Ethnic skin specialization R&D intensity and biotech-active adoption curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside SANS amendment timelines, Durban port throughput capacity, and regional humidity storage conditions would require recalibration. Forecasts reflect documented assumptions about compulsory specification enforcement consistency and clinic-channel convergence penetration ceilings. Recalibration cycles align with material shifts in National Regulator publication schedules and biotech-active ingredient cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Dye Market
Hair Care
Hair and Scalp Care Market
Hair Care
Malaysia Shampoo Market
Hair Care
North America Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
South Africa Hair Care Market
Hair Care
Chile Hair Care Market
Hair Care
Protein Shampoo Market
Hair Care
Hair Extension Market
Hair Care
Australia Hair Care Market
Hair Care
Qatar Hair Care Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Mexico Hair Care Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Hair Care Market