
 Global Skin Lightening Market | 2026-2036
Global Skin Lightening Market Size, Share, and Industry Trends Forecast 2026-2036
Global Skin Lightening Market Outlook
Plant-derived tyrosinase inhibitors is tilting formulation chemistry away from synthetic actives across the skin lightening industry. Beiersdorf AG leverages its dermatological heritage to anchor premium positioning in European pharmacy channels. L'Oréal S.A. sustains R&D intensity through dedicated pigment biology research centers in France and Brazil. Shiseido Co., Ltd. dominates East Asian markets with patented 4MSK technology and century-old brand equity in whitening aesthetics.
Skin lightening encompasses topical cosmetic and quasi-pharmaceutical products designed to reduce melanin synthesis through tyrosinase inhibition, antioxidant activity, or melanocyte downregulation, typically containing actives at concentrations between 0.5% and 4% depending on regulatory jurisdiction and intended use. These formulations serve consumer-driven aesthetic preferences and post-inflammatory hyperpigmentation management in clinical and retail settings. Hydroquinone-based prescription segments retain the highest margin pools despite regulatory contraction, while vitamin C serums capture the fastest volume growth in online retail channels. Creams maintain mature mass-market dominance through supermarket and drugstore distribution, whereas masks represent an emerging format concentrated in Asian beauty specialty stores.
The FDA maintains over-the-counter hydroquinone restrictions at 2% while requiring prescription oversight above that threshold, and EU REACH has banned hydroquinone in cosmetic formulations entirely, forcing multinational reformulation strategies. India's CDSCO and BIS frameworks govern cosmetic safety labeling but permit higher arbutin concentrations than Western equivalents, creating regulatory arbitrage for regional manufacturers. Stakeholders must monitor evolving national cosmetic ingredient lists and channel-specific compliance requirements to anticipate where formulation investment and geographic licensing priorities will shift next.
Market Dynamics
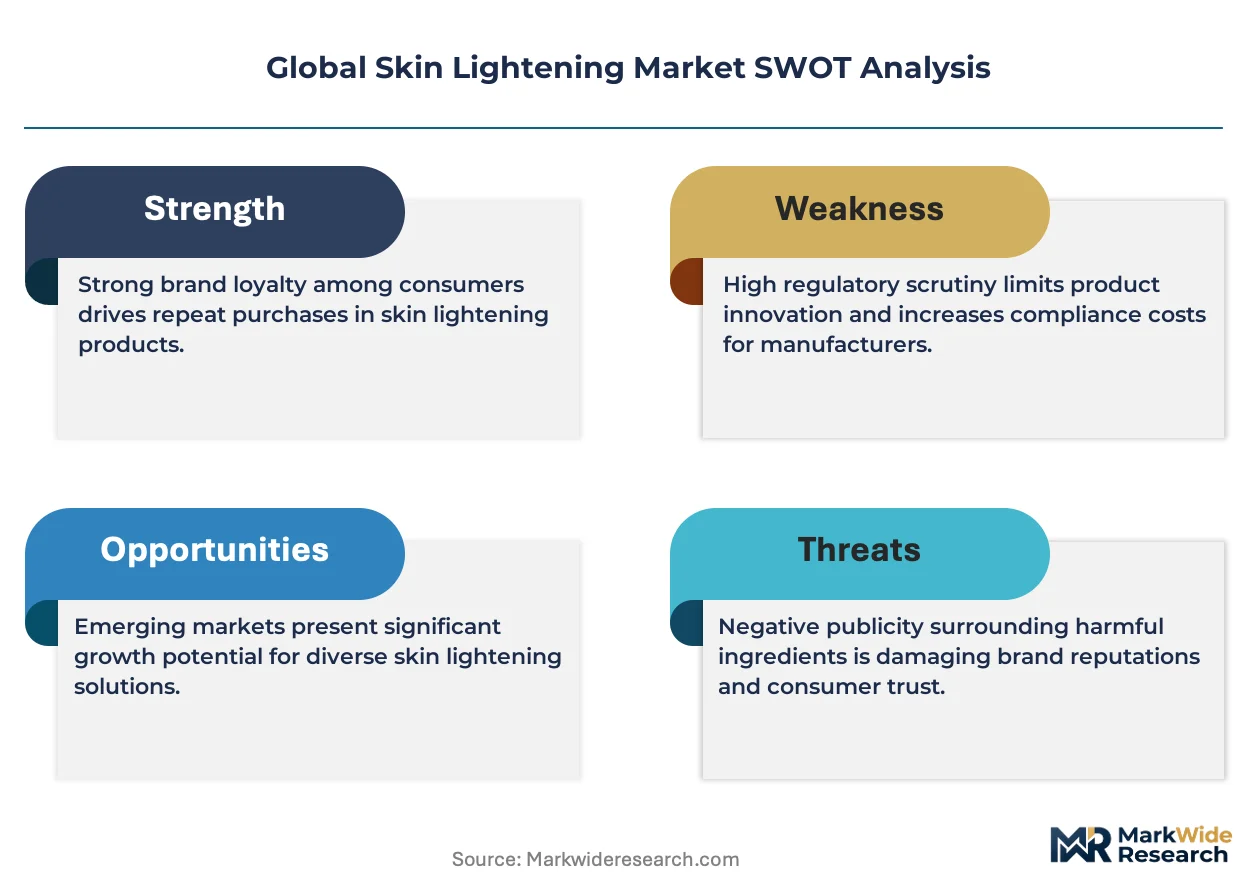
Regulatory fragmentation across the US, EU, and India is forcing simultaneous reformulation cycles as manufacturers navigate divergent hydroquinone thresholds while plant-derived tyrosinase inhibitors gain formulation share.
Growth Catalysts
- Professional channel expansion:Dermatology clinics and medical spas in Nigeria and Japan are driving clinically validated product adoption for post-inflammatory hyperpigmentation management.
- REACH-driven ingredient innovation:The EU's hydroquinone ban has accelerated R&D investment in kojic acid and arbutin derivatives as compliant alternatives.
- Patent-protected biotechnology:Shiseido's 4MSK compound and L'Oréal's pigment biology research are creating defensible premium positioning in East Asian pharmacy channels.
Market Restraints
- Raw material concentration:Kojic acid fermentation capacity concentrates in Chinese and Japanese biotech suppliers, creating geographic supply vulnerability.
- Regulatory compliance costs:Multinational manufacturers face parallel toxicology testing requirements under FDA, REACH, and CDSCO frameworks.
- Natural extract variability:Plant-derived tyrosinase inhibitors suffer from batch-to-batch potency inconsistency compared to synthetic hydroquinone standards.
Strategic Opportunities
- Underpenetrated African markets:Nigeria's informal retail sector and rising middle-class aesthetic expenditure create first-mover potential for compliant professional-grade formulations.
- Clean beauty certification:EWG Verified and COSMOS standards are opening premium shelf space in Sephora and Ulta Beauty for hydroquinone-free alternatives.
- Telemedicine integration:Remote dermatology consultations are enabling prescription-strength product distribution beyond traditional clinic footprints.
Industry Challenges
- Formulation scientist scarcity:The intersection of cosmetic chemistry and melanin biology requires specialized expertise that outpaces current academic pipeline output.
- Clinical trial timelines:FDA OTC monograph compliance and CDSCO safety documentation extend product launch cycles by 18-24 months.
- Counterfeit ingredient infiltration:Unregulated hydroquinone concentrations in gray-market imports undermine legitimate manufacturer safety investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Skin Lightening Market |
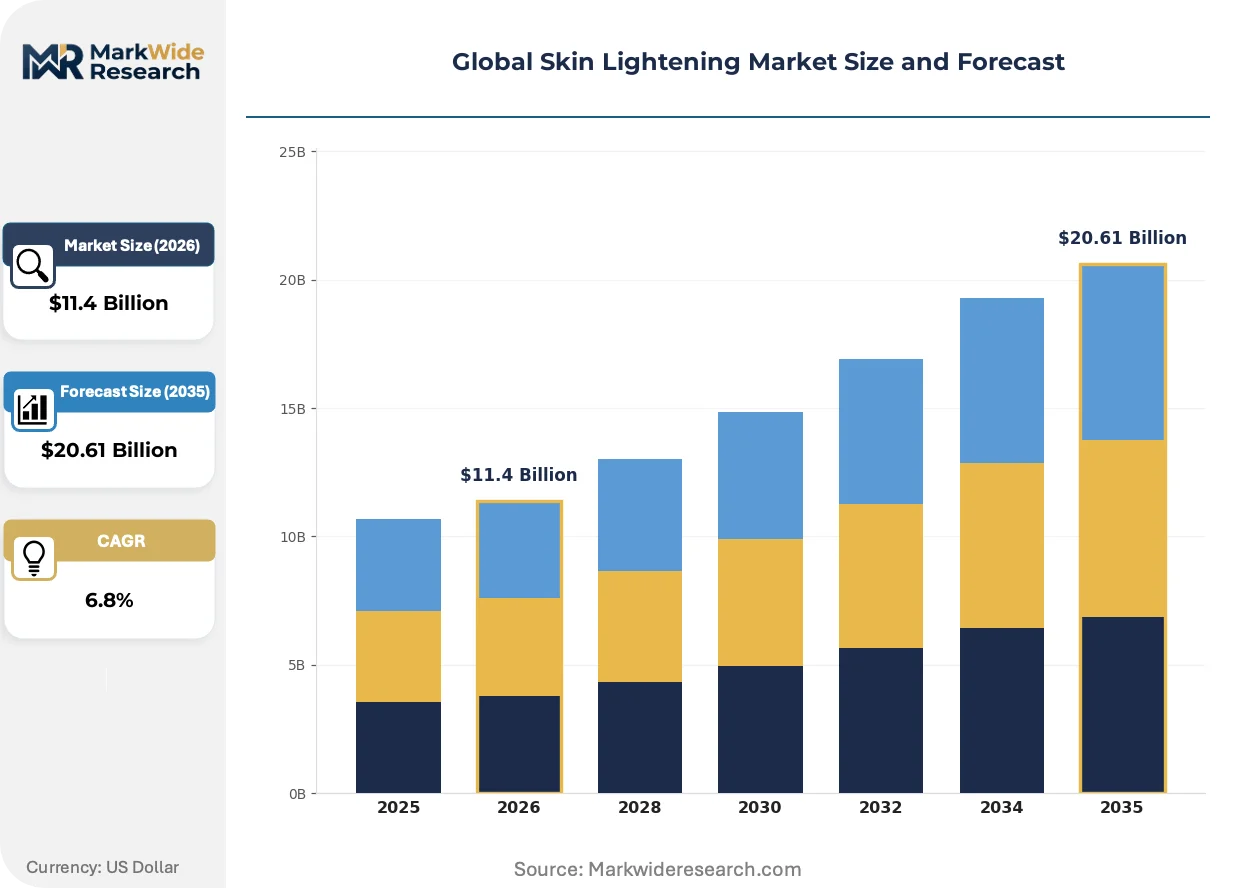
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Serums, Gels, Masks Active Ingredient: Hydroquinone, Kojic Acid, Vitamin C, Arbutin End User: Women, Men, Dermatologists, Salons Distribution Channel: Online Retail, Drugstores, Supermarkets, Beauty Stores |
| Companies Covered | Unilever PLC, Beiersdorf AG, L'Oréal S.A., Johnson & Johnson, Kao Corporation, Procter & Gamble, Shiseido Co., Ltd., Avon Products Inc., Estée Lauder Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Skin Lightening Market Strategic Shifts
Biotechnology-enabled ingredient discovery and channel digitization are compressing the traditional gap between cosmetic and pharmaceutical efficacy claims while regulatory divergence forces geographic customization.
Artificial intelligence is digitizing molecular screening for novel tyrosinase inhibitors, reducing lead compound identification from years to months. Beiersdorf and L'Oréal have deployed machine learning platforms to predict skin penetration and stability of plant-derived actives. This capability is digitizing competitive moats around formulation intellectual property and accelerating patent filing velocity.
EU REACH has banned hydroquinone in all cosmetic applications, forcing complete portfolio reformulation for brands serving European pharmacy and mass retail channels. Manufacturers are redirecting R&D budgets toward arbutin, vitamin C derivatives, and fermented kojic acid to maintain efficacy positioning. The professional dermatology segment is absorbing the highest compliance costs as prescription-grade hydroquinone requires renewed clinical documentation.
Subscription-based replenishment models are displacing traditional retail replenishment cycles in North American and European direct-to-consumer channels. Brands like The Ordinary and Paula's Choice have unbundled professional guidance from product purchase through AI skin assessment tools. This shift concentrates customer lifetime value data with first-party platforms while reducing dependence on Sephora and Ulta Beauty for repeat purchase capture.
Global Skin Lightening Market Segmentation
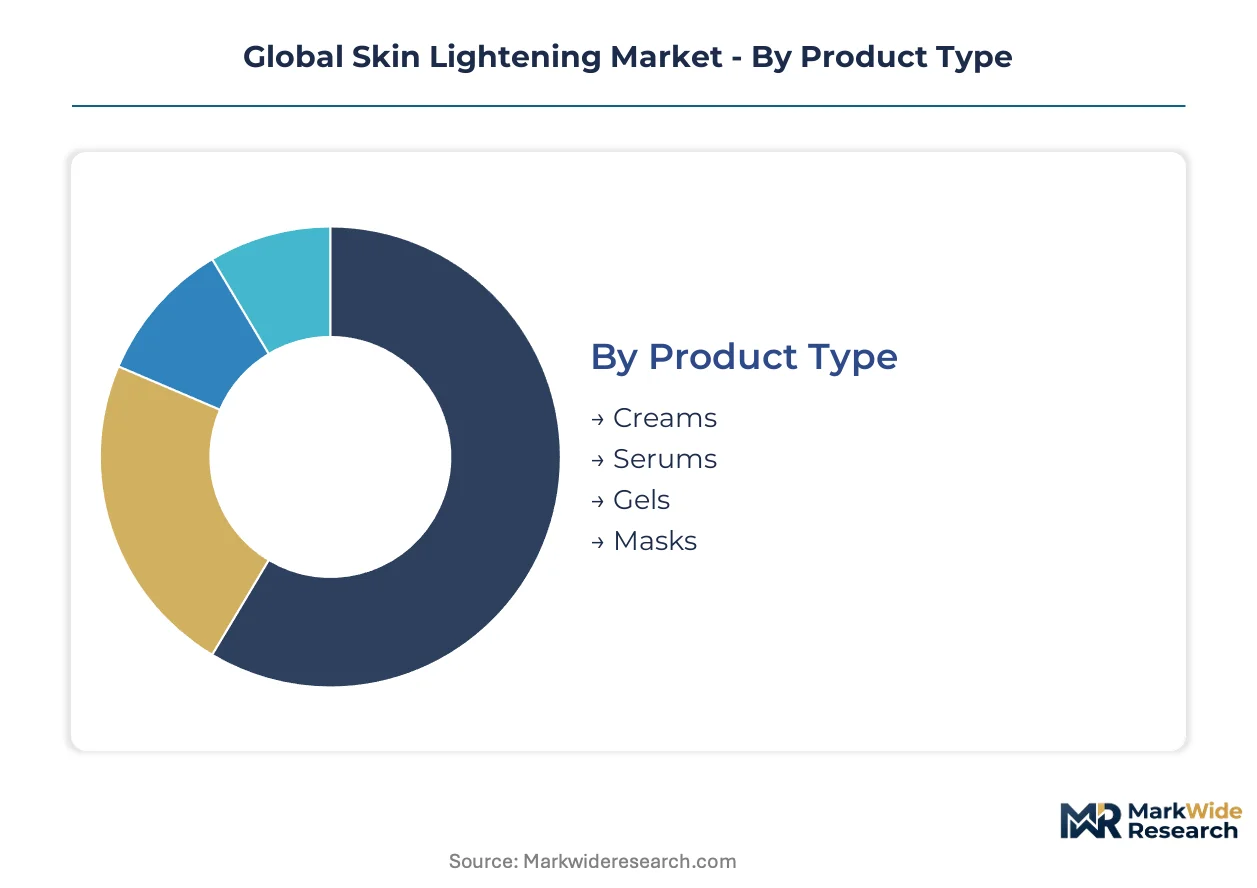
Skin lightening formulations fragment across four critical dimensions that determine regulatory compliance, margin structure, and channel access. Product type and active ingredient choices dictate formulation investment and geographic licensing priorities. End user targeting and distribution channel selection shape pricing architecture and clinical validation requirements.
Product Type:
Texture and delivery mechanism determine absorption kinetics, consumer application behavior, and shelf positioning across pharmacy and prestige retail channels.
- Creams:Oil-in-water emulsions with occlusive bases deliver sustained active release for daily maintenance regimens. Mass-market dominance in Indian and Nigerian supermarket channels reflects consumer familiarity and lower per-unit price points.
- Serums:Water-based concentrates with smaller molecular weight actives penetrate stratum corneum more efficiently. Accelerating volume in Japanese pharmacy and North American online retail channels is climbing the fastest as consumers prioritize visible efficacy timelines over cost.
- Gels:Hydro-alcoholic matrices suit oily skin types and tropical climates. Demand concentrates in Southeast Asian markets where humidity tolerance drives formulation preference.
- Masks:Occlusive sheet and rinse-off formats enable intensive weekly treatment protocols. Asian beauty specialty stores in Tokyo and Seoul represent the primary volume channel for this emerging format.
Established volume favors creams; emerging adoption favors masks.
Active Ingredient:
Regulatory jurisdiction and clinical claim ambition determine which tyrosinase inhibitors manufacturers deploy across regional portfolios.
- Hydroquinone:Synthetic phenol compound at 2-4% concentrations delivers potent melanogenesis inhibition through tyrosinase inactivation. Prescription oversight requirements under FDA and complete EU REACH prohibition restrict this segment to US dermatology clinics and select Latin American markets.
- Kojic Acid:Fermented rice-derived chelating agent interrupts melanin production by binding copper at the tyrosinase active site. Japanese biotech fermentation capacity and Brazilian consumer preference for natural actives are expanding most quickly for this compliant alternative.
- Vitamin C:Ascorbic acid and stable derivatives provide antioxidant-mediated melanin reduction with collagen co-benefits. L'Oréal's pigment biology research centers and direct-to-consumer subscription models are accelerating adoption.
- Arbutin:Hydroquinone glycoside from bearberry extract offers gradual depigmentation with reduced irritation potential. India's CDSCO permits higher concentrations than Western equivalents, creating regulatory arbitrage for regional manufacturers.
Clinical efficacy concentration favors hydroquinone; clean beauty certification favors arbutin.
End User:
Consumer self-treatment and professional administration segments demand divergent safety documentation and packaging formats.
- Women:Primary household purchasers driving mass-market volume through drugstore and supermarket replenishment cycles. Cultural complexion preferences in Nigeria and Japan sustain per-capita consumption leadership.
- Men:Emerging segment concentrated in East Asian markets where male grooming category expansion includes tone-evening formulations. Shiseido's 4MSK technology licensing targets this demographic through dedicated product lines.
- Dermatologists:Prescription-grade hydroquinone and combination therapy protocols require clinical trial documentation and medical representative detailing. US clinic channel retains highest margin pools despite regulatory contraction.
- Salons:Professional treatment settings in Lagos and Mumbai deploy higher-strength peels and maintenance protocols. Post-inflammatory hyperpigmentation management for acne-prone skin drives service attachment rates.
Volume concentration favors women; professional validation favors dermatologists.
Distribution Channel:
Channel selection determines customer data ownership, margin retention, and regulatory compliance burden for ingredient disclosure.
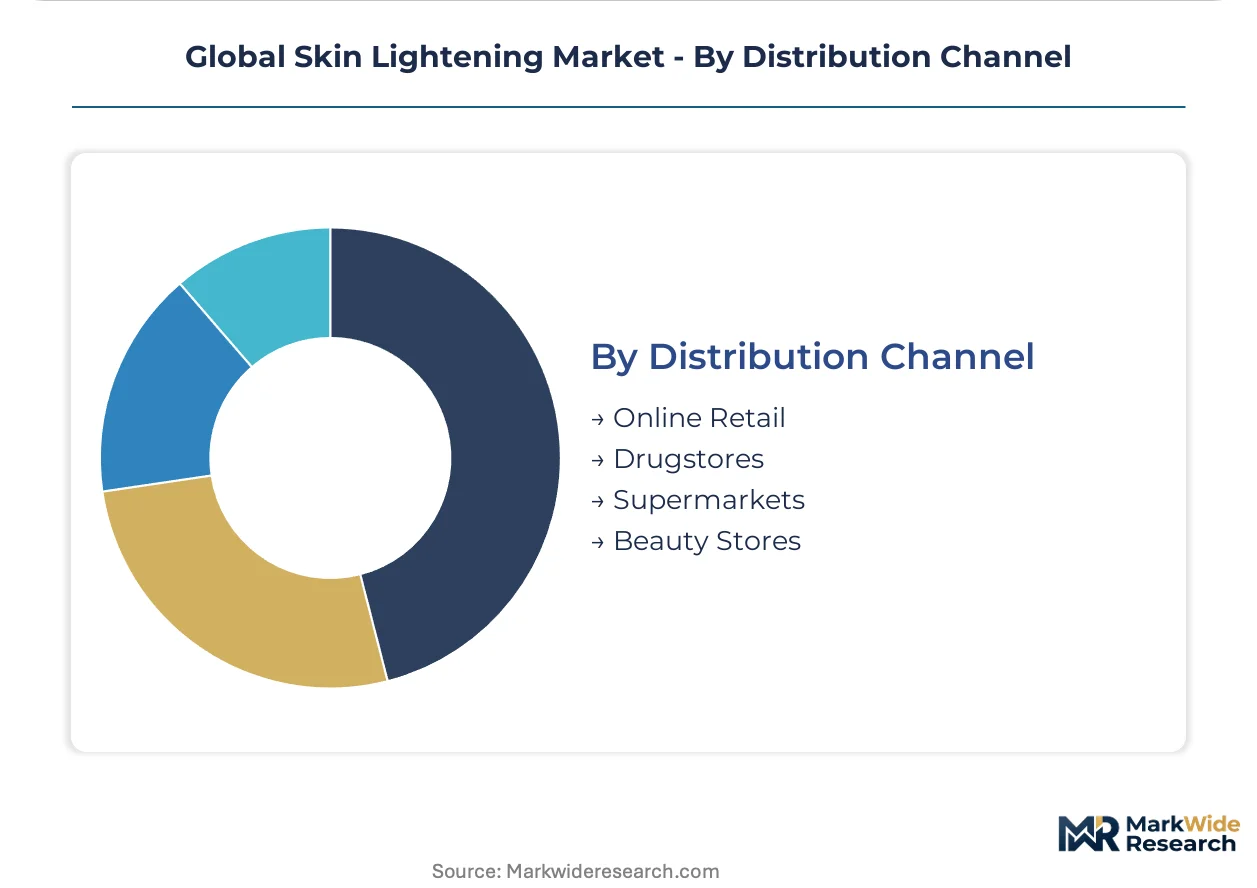
- Online Retail:Direct-to-consumer platforms enable AI skin assessment tools and subscription replenishment models. The Ordinary and Paula's Choice concentrate customer lifetime value data through first-party platforms.
- Drugstores:Pharmacy-affiliated retail in Germany and France requires EU REACH compliance documentation and trained beauty advisor presence. Beiersdorf leverages dermatological heritage for premium positioning.
- Supermarkets:Mass-market cream distribution in Indian urban centers and Nigerian informal retail sectors prioritizes price accessibility and local language labeling.
- Beauty Stores:Sephora and Ulta Beauty in North America allocate premium shelf space to EWG Verified and COSMOS-certified hydroquinone alternatives.
Margin retention favors online retail; physical trial access favors beauty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-inflammatory hyperpigmentation management and cultural complexion preferences concentrate buyer archetypes in India, Nigeria, and Japan, where per-capita consumption sustains distinct regulatory and channel ecosystems.
India
Urban middle-class aesthetic expenditure and bridal skincare rituals drive mass-market cream demand through supermarket and pharmacy channels. CDSCO permits higher arbutin concentrations than Western equivalents, creating regulatory arbitrage for domestic manufacturers. Mumbai and Delhi-NCR host formulation R&D clusters serving both local brands and multinational licensees.
Nigeria
Informal retail sector penetration and professional salon channel expansion sustain volume leadership across West Africa. NAFDAC enforces cosmetic safety labeling while permitting hydroquinone alternatives in quasi-pharmaceutical categories. Lagos anchors distribution networks extending into Ghana and Côte d'Ivoire through cross-border trader networks.
Japan
Century-old whitening aesthetics and male grooming category expansion concentrate premium serum and mask adoption. PMDA oversight governs quasi-drug classifications for 4MSK and other patented actives. Tokyo-Osaka pharmacy corridors represent the highest-value channel for biotechnology-enabled formulations.
United States
Telemedicine-integrated dermatology and subscription direct-to-consumer models reshape prescription-grade hydroquinone distribution. FDA maintains 2% over-the-counter thresholds while requiring clinical documentation above that concentration. Greater Boston and San Francisco Bay Area host AI-enabled skin assessment platform developers.
Germany
EU REACH hydroquinone prohibition and pharmacy channel premium positioning drive reformulation toward COSMOS-certified alternatives. ECHA compliance documentation requirements extend product launch timelines for multinational portfolios. Bavaria and North Rhine-Westphalia concentrate dermatological research institutes and contract manufacturing capacity.
Global Skin Lightening Market Competitive Environment
Channel-controlling players compete with product-specialist players across pharmacy, supermarket, and direct-to-consumer vectors. The market exhibits tiered consolidation with multinational consumer goods conglomerates anchoring mass-market volume while biotechnology-focused specialists capture premium positioning. Three archetypes dominate: dermatology-heritage pharmacy brands, fermentation-technology specialists, and AI-enabled direct-to-consumer platforms. Competitive moves concentrate on geographic licensing partnerships and clean beauty certification acquisition.
Within the dermatology-heritage tier, Beiersdorf AG and L'Oréal S.A. occupy positions anchored by pigment biology research infrastructure and European pharmacy channel relationships. Shiseido Co., Ltd. exemplifies the biotechnology-specialist archetype through patented active compound development. These three entities represent distinct competitive vectors—formulation science, channel control, and regional brand equity—rather than direct substitution.
| Leading Market Players |
|---|
| Unilever PLC |
| Beiersdorf AG |
| L'Oréal S.A. |
| Johnson & Johnson |
| Kao Corporation |
| Procter & Gamble |
| Shiseido Co., Ltd. |
| Avon Products Inc. |
| Estée Lauder Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Osaka-Kobe fermentation clusters anchor global kojic acid supply, concentrating tyrosinase inhibitor production capacity in Japanese biotech facilities that translate raw material scarcity into premium pricing power for compliant alternatives. This geographic concentration forces multinational formulators into long-term offtake commitments or backward integration investments to secure stable input costs.
Pricing Analysis
Cost-plus contracts with Japanese fermentation suppliers index kojic acid pricing to rice substrate costs and bioreactor capacity utilization, creating predictable but elevated input baselines for hydroquinone-free formulations. Price differentiation separates COSMOS-certified professional serums from mass-market arbutin creams through clinical validation documentation and pharmacy channel positioning. Pricing pressure stems from REACH compliance costs and parallel toxicology testing under FDA and CDSCO frameworks. Mass-market supermarket buyers in Nigeria and India exhibit highest price sensitivity, while Japanese pharmacy consumers demonstrate lowest elasticity for patented 4MSK formulations.
Supply Chain Analysis
Export-control scrutiny over biotechnology fermentation equipment limits capacity expansion outside established Japanese and Chinese supply zones, constraining geographic diversification for plant-derived tyrosinase inhibitors. Raw material dependencies center on rice substrate for kojic acid fermentation, bearberry extract for arbutin concentration, and L-ascorbic acid precursor chemicals. Single-source vulnerability concentrates in Osaka-area fermentation facilities serving Shiseido and L'Oréal pigment biology operations. Distribution runs through pharmacy-affiliated wholesale networks in Germany and France, direct-to-consumer subscription platforms in North America, and informal trader channels extending from Lagos across West Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, REACH, and CDSCO frameworks fragments competitive space, creating niche opportunities for region-specific formulation specialists as multinational incumbents struggle with simultaneous reformulation cycles.
For Market Incumbents: Harden supply security through captive fermentation capacity in Japan or strategic offtake agreements with Osaka-Kobe biotech clusters. Invest in CDSCO-compliant documentation for Indian market retention as domestic manufacturers exploit arbutin concentration arbitrage. Defensive patent filings around AI-enabled skin penetration prediction will protect premium positioning against direct-to-consumer platform erosion. For New Entrants and Emerging Players: Nigeria's informal retail sector and professional salon channel expansion offer first-mover terrain for compliant hydroquinone alternatives with NAFDAC safety labeling. Target Lagos-based distribution networks extending into Ghana and Côte d'Ivoire through cross-border trader relationships. Go-to-market execution should prioritize telemedicine-integrated dermatology partnerships enabling prescription-strength product distribution beyond traditional clinic footprints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology specialists with patented tyrosinase inhibitors over commodity formulation houses. Long-term viability rests on defensible active compound IP and geographic licensing revenue streams rather than brand equity alone. Monitor FDA OTC monograph revision timelines for hydroquinone thresholds as inflection indicator for prescription-grade margin pool contraction or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive kojic acid production insulates Japanese manufacturers from Chinese substrate volatility and export licensing delays. |
| CDSCO Compliance Documentation Investment | Accelerated safety filing enables market retention as India's BIS frameworks tighten cosmetic ingredient disclosure requirements. |
| AI-Enabled Skin Assessment Platform Launch | First-party data concentration reduces Sephora and Ulta Beauty dependence for repeat purchase capture in North America. |
| COSMOS Certification Acquisition | EWG Verified status unlocks premium shelf positioning in European pharmacy channels where REACH prohibits hydroquinone entirely. |
| Telemedicine Dermatology Partnership | Remote consultation integration extends prescription-grade hydroquinone distribution beyond traditional US clinic footprints. |
Study Parameters
Initial hypotheses were tested against primary input from formulation R&D directors, regulatory affairs leads at multinational cosmetics firms, pharmacy channel buyers, and dermatology clinic procurement managers and refined through secondary validation against FDA OTC monograph filings, ECHA REACH substance evaluations, CDSCO cosmetic safety notifications, and Japanese PMDA quasi-drug registration databases. Bottom-up volume modeling from ingredient consumption data and top-down value triangulation from channel margin structures were cross-checked for consistency.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product texture, active ingredient regulatory status, end-user administration setting, and distribution channel data ownership structure. CAGRs were derived from trend extrapolation of professional channel adoption rates and clean beauty certification penetration. Forecast inputs incorporated AI-enabled skin assessment platform deployment velocity and telemedicine-integrated dermatology expansion patterns.
Practitioners should monitor FDA hydroquinone monograph revision proceedings, ECHA substance restriction proposals, and NAFDAC enforcement intensity for early signals of regulatory-driven demand shifts. Forecasts reflect assumptions about sustained cultural complexion preferences in India, Nigeria, and Japan and stable fermentation capacity utilization in Osaka-Kobe clusters. Material shifts in REACH scope expansion to additional tyrosinase inhibitors or breakthrough synthetic alternatives with superior stability profiles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Herbal Mascara Market