
 Cosmetic Chemicals Market | 2026-2036
Cosmetic Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Chemicals Market Intelligence
Prestige skincare is shifting toward clinical-grade active ingredients, pulling cosmetic chemical demand toward higher-specification emollients and preservatives. BASF SE leverages its integrated specialty chemicals platform to supply multi-functional actives for anti-aging formulations. Croda International Plc sustains leadership in naturally derived lipids through sustained biotechnology R&D investment. Evonik Industries anchors its position with high-purity surfactants engineered for sensitive-skin applications.
Cosmetic chemicals comprise functional and active ingredients—surfactants, emollients, preservatives, thickeners, and sensory modifiers—formulated at precise concentrations to deliver stability, efficacy, and skin compatibility in finished personal care products. Manufacturing relies on esterification, ethoxylation, and fermentation-derived pathways to achieve specified purity grades and dermatological safety profiles. Emollients command durable margin pools as brands prioritize skin-barrier repair claims, while surfactants face formulation pressure from sulfate-free and mild-cleansing trends. Preservatives attract reformulation investment as clean-label preferences challenge traditional paraben and formaldehyde-releaser systems.
REACH registration requirements and the EU Green Deal framework restrict petrochemical-derived inputs and mandate biodegradability testing for rinse-off products. FDA cosmetic safety substantiation rules and MoCRA modernization in the United States impose new adverse-event reporting and good manufacturing practice obligations on ingredient suppliers. China's NMPA and GB standards enforce safety assessment protocols for imported cosmetic raw materials. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation costs and supply chain qualification timelines.
Market Dynamics
Clean-label mandates and REACH-driven ingredient substitution are compressing formulation timelines for cosmetic chemical suppliers. Brands now demand pre-validated, multi-functional actives that satisfy both EU biodegradability protocols and Chinese safety dossier requirements.
Growth Catalysts
- Biotechnology-derived emollients:Fermentation-based lipid production delivers consistent carbon-chain profiles that petroleum esters cannot match. Korean and Chinese skincare brands are scaling procurement of these materials for barrier-repair claims.
- EU Green Deal compliance deadlines:The 2030 biodegradability mandate for rinse-off products forces reformulation cycles. Suppliers with pre-certified ingredient portfolios capture qualification advantages.
- India:Domestic contract manufacturers are building specialty chemical capabilities to serve emerging direct-to-consumer beauty brands. Local production reduces import dependency on Chinese surfactant intermediates.
Market Restraints
- Palm oil and coconut oil price volatility:Natural emollient feedstocks face agricultural supply shocks. Formulators cannot hedge long-term pricing for bio-based surfactants.
- Chinese intermediate concentration:Ethoxylation capacity clusters in Jiangsu and Zhejiang provinces. Geopolitical friction or environmental enforcement disruptions propagate through global supply chains.
- Preservative efficacy gaps:Clean-label alternatives to parabens and formaldehyde-releasers often fail broad-spectrum testing. Reformulation costs multiply when shelf-stability claims are compromised.
Strategic Opportunities
- Brazil:ANVISA's streamlined cosmetic ingredient notification pathway reduces registration timelines. Suppliers can establish South American formulation hubs ahead of domestic brand premiumization.
- Microbiome-targeted actives:Prebiotic and postbiotic ingredients for scalp and skin health applications command formulation premiums. Biotechnology platforms enable patent-protected positioning.
- Saudi Arabia:SFDA's harmonization with Gulf Cooperation Council standards creates a 35-million-consumer addressable market. Local manufacturing incentives under Vision 2030 reduce import duty exposure.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with dual expertise in dermatological safety and sustainable process design command premium compensation. Recruitment pipelines lag demand.
- Cross-jurisdictional dossier management:REACH registrations, FDA MoCRA substantiation files, and NMPA safety assessments require parallel documentation. Compliance teams face capacity constraints.
- Legacy preservative system obsolescence:Brands with entrenched paraben-based formulations face consumer rejection before technical alternatives achieve equivalent performance validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Chemicals Market |
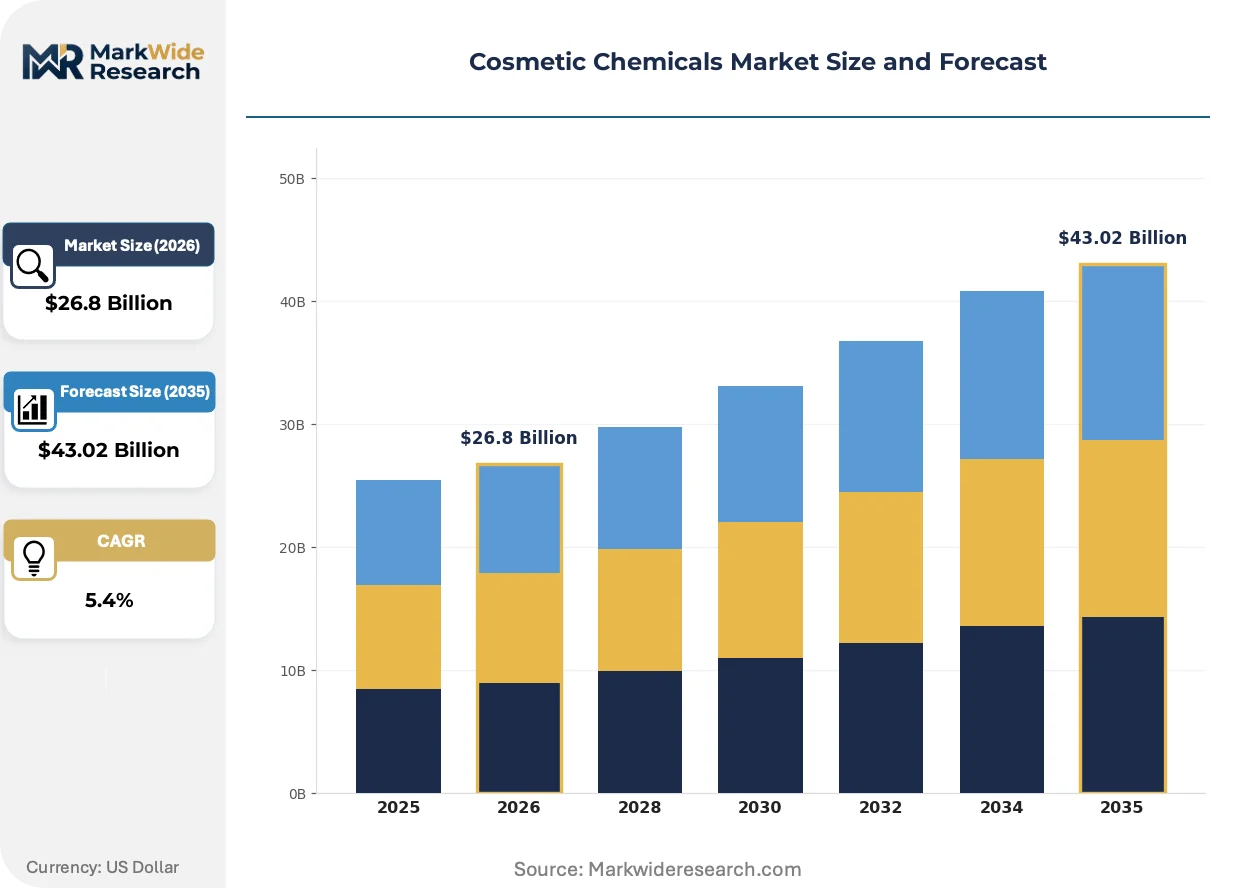
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emollients, Surfactants, Preservatives, Thickeners Application: Skincare, Haircare, Makeup, Fragrance Form: Liquid, Cream, Gel, Powder End User: Manufacturers, Retailers, Distributors, Salon Owners |
| Companies Covered | Croda International Plc, Evonik Industries, Ashland Global Holdings Inc, Givaudan SA, Solvay S.A, BASF SE, Dow Inc, Symrise AG, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Chemicals Market Strategic Shifts & Innovations
Biotechnology platforms and regulatory disclosure requirements are redrawing competitive boundaries. Suppliers now compete on pre-certification depth and carbon-footprint transparency rather than commodity scale alone.
Enzymatic esterification is absorbing capital allocation from traditional acid-catalyzed processes. Specialty chemical producers deploy lipase biocatalysts to achieve milder reaction conditions and higher stereoselectivity for sensitive-skin emollients. European and North American formulators prioritize these inputs for atopic dermatitis-positioned products. The technology is absorbing market share from petrochemical routes by enabling carbon-14 dating verification for natural-origin claims.
REACH Annex XVII restrictions on microplastics in rinse-off cosmetics entered full enforcement. The prohibition covers synthetic polymer-based exfoliants and film-forming agents. Formulators substitute with cellulose, silica, or biodegradable polymer alternatives. Color cosmetics and sun care segments face the steepest reformulation costs due to texture and sensory requirements.
Ingredient traceability requirements now penetrate procurement contracts. Beauty brands mandate blockchain-verified supply chain documentation from palm oil derivatives to fermentation feedstocks. Tier-1 suppliers in Germany and France invest in mass-balance certification infrastructure. This behavioral shift compresses qualification timelines for uncertified competitors.
Cosmetic Chemicals Market Segmentation
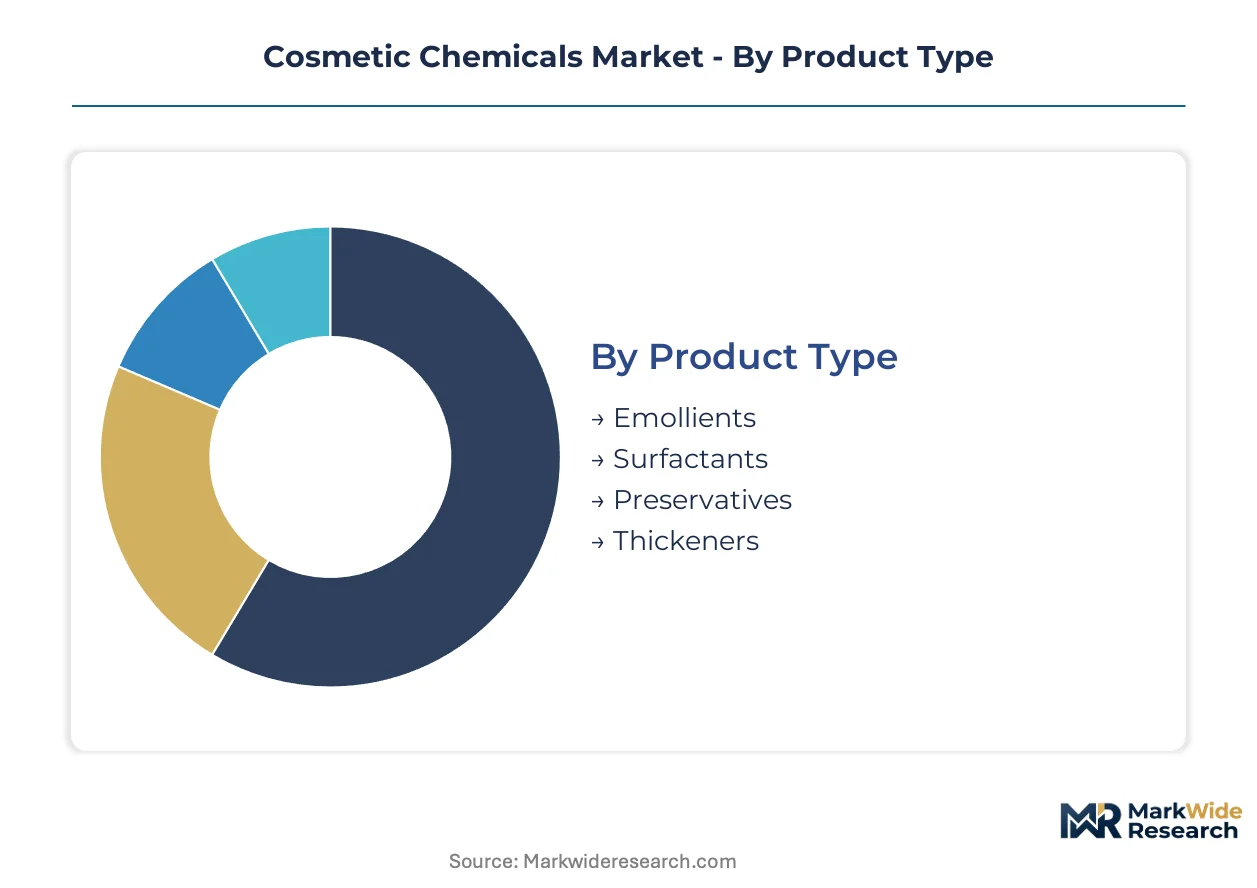
Cosmetic chemical procurement diverges sharply across product categories and end-use applications. Formulators select ingredient specifications based on performance claims, regulatory jurisdiction, and manufacturing process compatibility.
Product Type:
Specification hierarchies separate commodity surfactants from high-purity actives engineered for sensitive-skin positioning.
- Emollients:Lipid-based occlusive and humectant compounds restore skin-barrier function in therapeutic and prestige skincare. Korean brands scale fermentation-derived squalane procurement for atopic dermatitis claims; REACH biodegradability mandates favor bio-based esters over petroleum-derived alternatives.
- Surfactants:Surface-active agents reduce interfacial tension for cleansing and emulsification functions. Sulfate-free anionic and amphoteric variants capture formulation share in China and India as mild-cleansing positioning spreads; ethoxylation capacity concentration in Jiangsu province creates supply vulnerability.
- Preservatives:Antimicrobial systems prevent microbial contamination in water-based formulations.
- Thickeners:Rheology modifiers control viscosity and sensory properties in creams and lotions.
Emollients lead on scale; surfactants lead on momentum.
Application:
End-use segments impose distinct purity, stability, and sensory requirements on chemical suppliers.
- Skincare:Moisturizers, serums, and treatment products demand clinical-grade actives with validated dermatological safety profiles. Chinese domestic brands drive premiumization of niacinamide and peptide formulations; NMPA safety dossier requirements extend supplier qualification timelines.
- Haircare:Shampoos, conditioners, and styling products prioritize mild surfactant systems and conditioning quaternaries. Indian contract manufacturers expand local amodimethicone production to serve direct-to-consumer brand growth; sulfate-free mandates reshape anionic surfactant procurement.
- Makeup:Color cosmetics require film-forming agents, pigments, and texture modifiers with photostability and wear-resistance properties.
- Fragrance:Perfumes and scented products utilize fixatives, solubilizers, and encapsulation technologies for controlled release.
Skincare commands the largest volume commitment; haircare demonstrates the steepest expansion trajectory.
Form:
Physical state determines manufacturing equipment, packaging compatibility, and preservative system selection.
- Liquid:Pump-dispensed serums, toners, and essences require water-soluble actives and clear-formulation stability. Airless packaging adoption in China and Germany reduces oxidation-sensitive ingredient degradation; cold-process manufacturing cuts energy costs for emulsion systems.
- Cream:Oil-in-water and water-in-oil emulsions deliver occlusive and hydrating benefits for mature and dry skin segments. O/W systems dominate mass-market facial moisturizers; W/O architectures capture sun care and night repair premium positioning.
- Gel:Hydrogel and organogel structures provide lightweight texture and rapid absorption for oily and combination skin.
- Powder:Dry formulations enable preservative-free claims and extended shelf stability in mineral makeup and dry shampoo.
Cream formulations anchor current production scale; gel structures gain share fastest among millennial and Gen Z demographics.
End User:
Procurement authority and technical capability vary across the value chain, reshaping supplier engagement models.
- Manufacturers:Contract and owned-brand producers specify ingredient grades and conduct stability testing. Brazilian ANVISA notification pathways accelerate new ingredient adoption for multinational production hubs; EU-based manufacturers demand REACH-compliant pre-certification packages.
- Retailers:Private-label beauty brands and pharmacy chains negotiate direct chemical sourcing for exclusive formulations. Clean-label mandates from Sephora and Ulta Beauty propagate upstream to surfactant and preservative suppliers; blockchain traceability requirements penetrate tier-2 contracts.
- Distributors:Regional chemical traders manage inventory and logistics for small-batch formulators.
- Salon Owners:Professional hair and skin treatment providers purchase back-bar quantities for in-service applications.
Manufacturers dominate volume procurement; retailers reshape specification standards fastest through clean-beauty mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor global surfactant intermediate production, concentrating ethoxylation capacity that feeds formulation networks across personal care supply chains. This Chinese cluster shapes raw material availability for brands operating under REACH biodegradability deadlines and NMPA safety dossier requirements.
China
Domestic skincare brands scale premium niacinamide and peptide procurement for anti-aging lines. NMPA enforces safety assessment protocols for imported cosmetic raw materials, extending supplier qualification timelines. Specialty ingredient capacity expands in Jiangsu province as local producers capture share from multinational chemical suppliers.
Germany
Contract manufacturers demand REACH-compliant pre-certification packages for emollients and preservatives. ECHA administers Annex XVII microplastic restrictions and biodegradability mandates under EU Green Deal frameworks. BASF SE anchors integrated specialty chemicals production in Ludwigshafen for multi-functional actives.
United States
Clean-label mandates from Sephora and Ulta Beauty propagate upstream to surfactant suppliers. FDA MoCRA modernization imposes adverse-event reporting and good manufacturing practice obligations on ingredient suppliers. New Jersey and Texas host formulation hubs serving direct-to-consumer beauty brands.
Brazil
Domestic contract manufacturers build specialty chemical capabilities for emerging direct-to-consumer beauty brands. ANVISA streamlined cosmetic ingredient notification pathways reduce registration timelines for multinational suppliers. São Paulo anchors South American formulation hubs ahead of domestic brand premiumization.
India
Direct-to-consumer haircare brands drive sulfate-free surfactant procurement from local amodimethicone producers. BIS standards and DGFT import regulations shape feedstock availability for bio-based emollients. Gujarat and Maharashtra contract manufacturers reduce dependency on Chinese surfactant intermediates.
Cosmetic Chemicals Market Key Industry Players
Capacity expansion dominates the current landscape as suppliers position pre-certified ingredient portfolios ahead of EU biodegradability deadlines. The vendor base stratifies across integrated multinational chemical platforms, biotechnology-focused lipid specialists, and regional formulation service providers. Three archetypes define competitive positioning: REACH-registered specialty chemical suppliers with mass-balance certification infrastructure, fermentation-derived emollient specialists leveraging carbon-14 verification, and contract manufacturing organizations with integrated regulatory dossier capabilities. Geographic expansion into Brazil and Saudi Arabia and strategic partnerships for microbiome-targeted actives represent the dominant competitive moves.
Within the integrated multinational tier, BASF SE and Croda International Plc exemplify divergent strategic anchors. BASF represents the vertically integrated petrochemical-to-specialty platform capable of supplying multi-functional actives at scale across anti-aging and sensitive-skin segments. Croda occupies a position exemplifying biotechnology-forward lipid production, with fermentation-derived squalane and naturally derived emollients serving Korean and Chinese barrier-repair formulation trends. Evonik Industries sits within the high-purity surfactant specialist archetype, engineered for mild-cleansing and sulfate-free applications where dermatological safety validation commands formulation premiums.
| Leading Market Players |
|---|
| Croda International Plc |
| Evonik Industries |
| Ashland Global Holdings Inc |
| Givaudan SA |
| Solvay S.A |
| BASF SE |
| Dow Inc |
| Symrise AG |
| Clariant |
| Others |
Cost & Logistics Intelligence
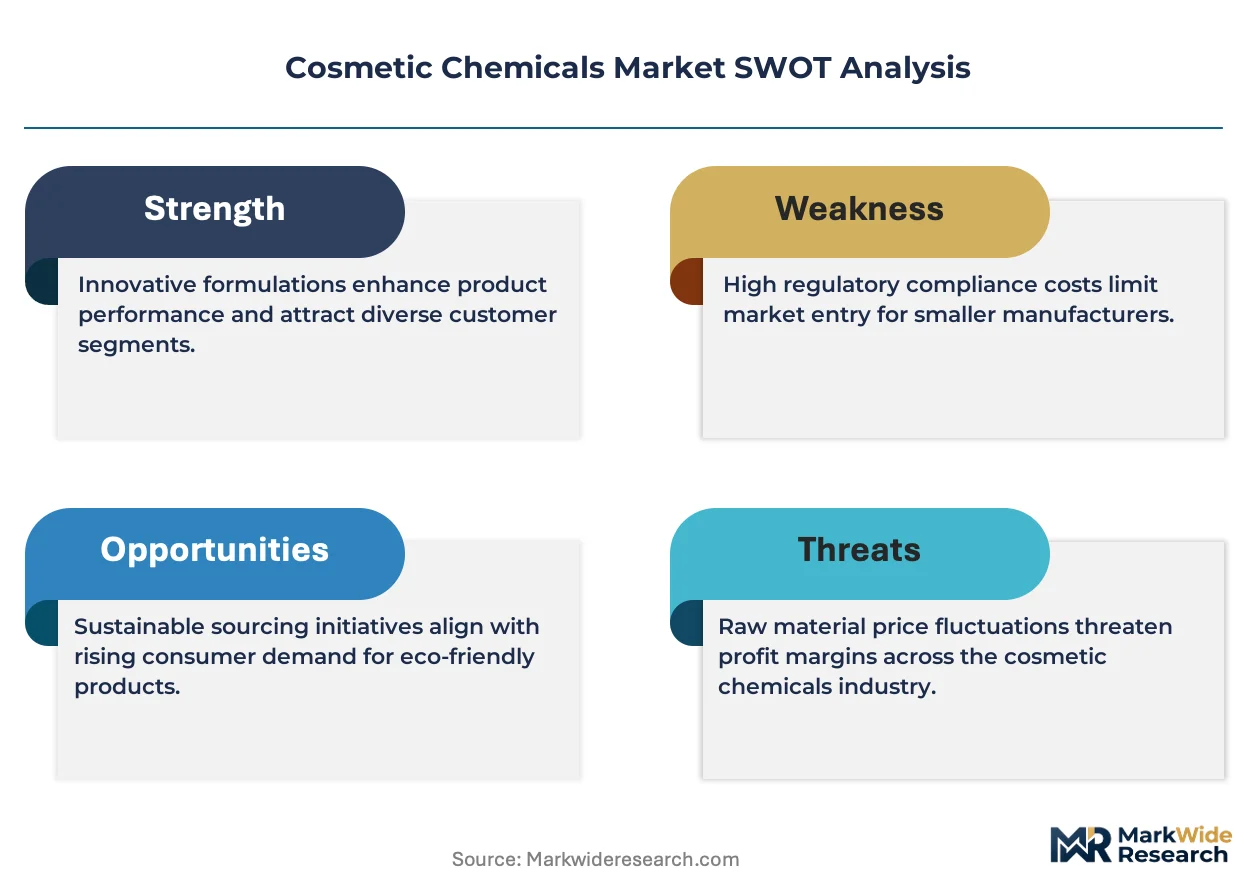
REACH certification tiers bifurcate cosmetic chemical procurement into pre-validated premium grades and commodity alternatives, with this divergence manifesting in both margin structures and supplier qualification timelines across European and Asian manufacturing networks.
Pricing Analysis
Input-cost pass-through from palm oil and coconut oil feedstocks intensifies margin compression for natural emollient suppliers, while fermentation-derived squalane commands sustained premiums through carbon-14 verification. Three-tier pricing structure across REACH-certified premium, mass-market standard, and unverified economy grades reflects certification investment recovery. Pricing pressure stems from Chinese domestic producers expanding specialty surfactant capacity. Contract manufacturers exhibit highest price sensitivity; prestige skincare brands demonstrate lowest.
Supply Chain Analysis
Ethoxylation capacity rests on Jiangsu and Zhejiang province clusters in China, with secondary concentration in German Ludwigshafen and Texas Gulf Coast chemical corridors. Key inputs include fatty alcohols, ethylene oxide, and fermentation feedstocks. Single-source vulnerability propagates from Jiangsu environmental enforcement actions. Distribution runs through regional chemical distributors serving contract manufacturers and direct brand procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate where EU biodegradability mandates inflate compliance costs against Chinese domestic production incentives, creating divergent landed cost structures for identical ingredient specifications.
For Market Incumbents: Extend REACH-registered product portfolios into microbiome-targeted actives before biotechnology specialists capture formulation premiums. BASF SE and Croda International Plc demonstrate defensive positioning through backward integration into fermentation feedstocks. Capacity addition in São Paulo and Riyadh reduces tariff exposure from Chinese intermediate concentration.
For New Entrants and Emerging Players: Launch via direct-to-consumer brand partnerships targeting sulfate-free surfactant white space in Indian haircare and Brazilian professional salon channels. ANVISA's streamlined notification pathway offers the most penetrable regulatory entry point. Position around blockchain-verified supply chain documentation as a service layer to tier-2 formulators.
For Investors and Strategic Acquirers: Consolidation pressure builds where cross-jurisdictional dossier management costs exceed standalone compliance team capacity for mid-cap specialty chemical producers. Long-term viability favors fermentation-derived lipid platforms with patent-protected carbon-chain profiles. Watch NMPA safety assessment timeline extensions as inflection indicator for Chinese import substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Croda International Plc secures squalane supply consistency against agricultural price volatility. |
| REACH Pre-Certification Portfolio Expansion | Evonik Industries captures qualification advantages ahead of EU Green Deal deadlines. |
| Brazilian Formulation Hub Establishment | Multinational suppliers leverage ANVISA pathways ahead of domestic brand premiumization. |
| Microbiome-Targeted Active Development | Biotechnology platforms enable patent-protected positioning in scalp and skin health. |
| Blockchain Traceability Infrastructure Investment | German and French tier-1 suppliers compress competitor qualification timelines. |
Research Approach
Direct dialogue with cosmetic chemists, procurement leads at contract manufacturers, regulatory affairs directors, and specialty chemical distribution channel partners grounded qualitative insights. Secondary validation drew from ECHA REACH registration databases, NMPA safety assessment filings, customs trade data for surfactant intermediates, and SEC 10-K disclosures from listed chemical suppliers. Bottom-up ingredient demand modeling and top-down personal care market sizing enabled triangulation across estimation approaches.
Segment-level outputs across emollient grade tiers, end-use applications spanning skincare through haircare, and regional production hub configurations structured the analytical framework throughout the projection horizon. CAGRs derived from regression analysis against historical procurement volumes and forward-looking brand formulation pipeline disclosures. Industry-specific inputs included ethoxylation capacity utilization rates and REACH registration completion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Jiangsu environmental enforcement intensification or NMPA safety dossier requirement expansion. Projections reflect assumptions around EU biodegradability mandate adherence and Chinese domestic specialty chemical capacity scaling. A small set of named triggers—palm oil supply shocks, REACH Annex XVII microplastic restriction enforcement, and SFDA-GCC harmonization acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Arbutin for Cosmetics Market