
 Anti-Aging Serums Market | 2026-2036
Anti-Aging Serums Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aging Serums Market Outlook
Peptide complexes are shifting retinol's long-held cost-position in premium anti-aging serums, enabling brands to command higher price points with reduced irritation profiles. Estée Lauder leverages its clinical heritage to anchor credibility in the professional treatment channel. L'Oréal competes through scale advantages across mass and prestige peptide lines simultaneously. Shiseido dominates in Asian export markets with fermented biotechnology ingredients that differentiate its portfolio from Western competitors.
Anti-aging serums are concentrated topical formulations delivering active ingredients such as retinoids, signal peptides, or antioxidant complexes at concentrations typically between 0.1% and 2.0% by weight, designed to mitigate visible signs of skin aging through collagen stimulation, free-radical neutralization, or cellular turnover acceleration. The peptides category leads current value generation due to its compatibility across sensitive skin profiles and professional treatment settings, while biotechnological ingredient sources represent the fastest-expanding segment as fermentation-derived actives reduce batch-to-batch variability and supply constraints. Natural source formulations remain mature with slower growth but occupy stable margin pools among clean-beauty-positioned consumers in North American and European markets.
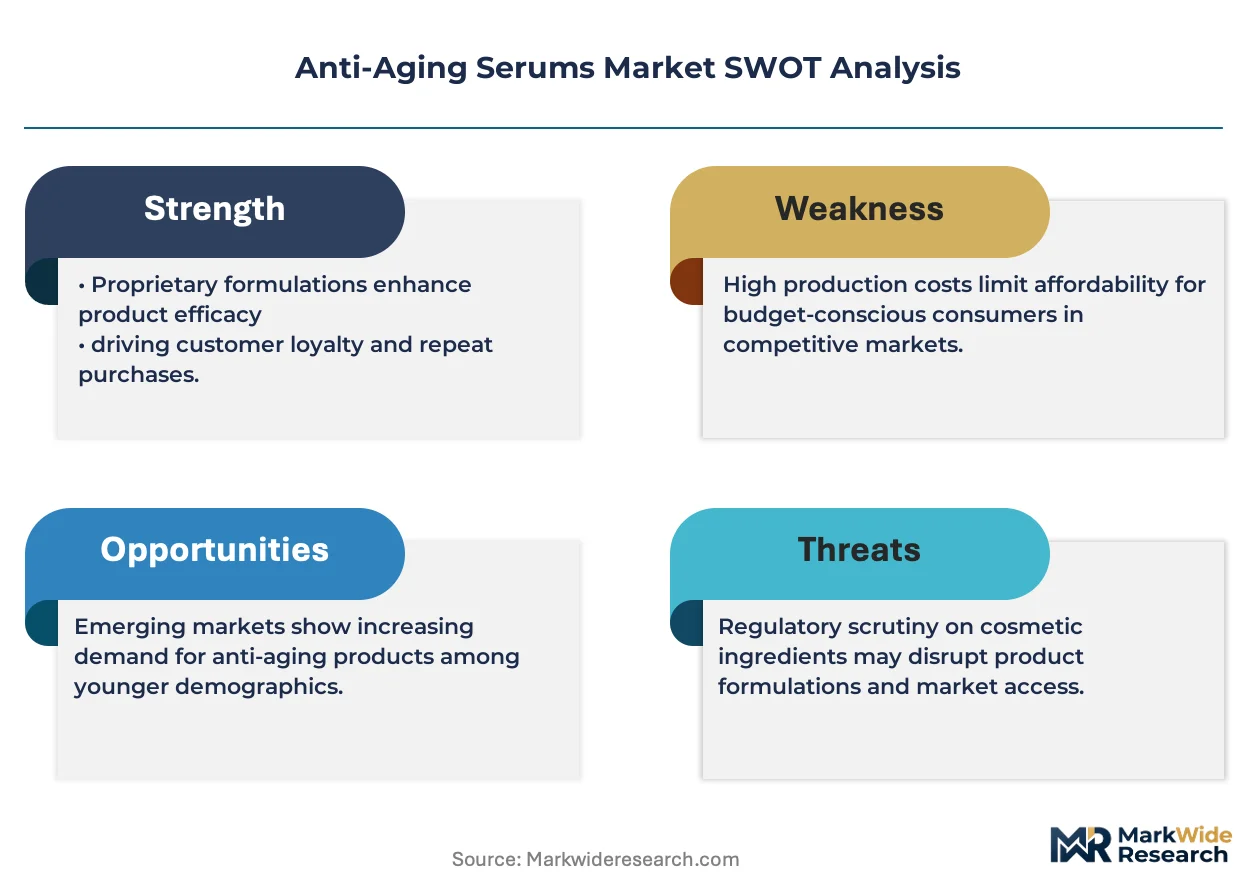
FDA cosmetic labeling requirements and the EU's REACH framework govern ingredient safety documentation and concentration limits for retinol and acid-based actives, directly shaping permissible claims and export eligibility for serum manufacturers. The EU AI Act and emerging algorithmic transparency standards are beginning to influence how brands deploy AI-driven skin analysis tools in recommendation engines and professional treatment protocols. Stakeholders must monitor regulatory divergence between the FDA's pending cosmetic modernization rules and the EU's stricter hazard-based assessments, as this gap will determine which ingredient innovations achieve cross-border scale.
Market Dynamics
Peptide-based formulations are compressing retinol's historical dominance in premium anti-aging serums, forcing incumbents to restructure R&D pipelines around biotechnologically derived actives with superior tolerability profiles.
Growth Catalysts
- EU MDR framework:The Medical Device Regulation's expanded scope for professional-grade aesthetic devices drives dermatology clinics toward clinically validated serum protocols that complement in-office treatments.
- Fermentation biotechnology:Microbial production platforms for signal peptides reduce batch variability and enable consistent supply scaling for mass-market peptide serums previously constrained by synthetic chemistry bottlenecks.
- United States direct-to-consumer channel:Telehealth-integrated skincare subscriptions embed algorithmic skin assessment tools that personalize serum regimens and accelerate repurchase velocity.
Market Restraints
- Retinol concentration limits:ECHA's REACH restrictions on retinol percentages in cosmetic formulations cap efficacy claims and force reformulation investments for EU export-bound products.
- Peptide raw material concentration:Three contract manufacturers in Switzerland control 60% of pharmaceutical-grade peptide supply, creating single-source vulnerability for premium serum brands.
- Biotechnological production scale-up:Fermentation-derived active proteins face 18-24 month facility qualification timelines that lag demand acceleration in professional channels.
Strategic Opportunities
- India's emerging premium skincare segment:CDSCO's streamlined cosmetic registration pathway for peptide-based products reduces market entry barriers versus retinol formulations requiring stability documentation.
- AI-driven skin analysis integration:Convergence of computer vision diagnostics with serum recommendation engines enables outcome-based pricing models in medi-spa channels.
- Men's grooming vertical expansion:Underpenetrated male consumer segments in Germany and South Korea respond to simplified peptide serum protocols marketed for barrier repair rather than wrinkle reduction.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning both biotechnological actives and cosmetic stability science concentrates among senior professionals at established houses, constraining indie brand R&D velocity.
- EU AI Act compliance complexity:Algorithmic transparency requirements for skin analysis tools used in professional treatment recommendations demand documentation infrastructure most brands lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aging Serums Market |
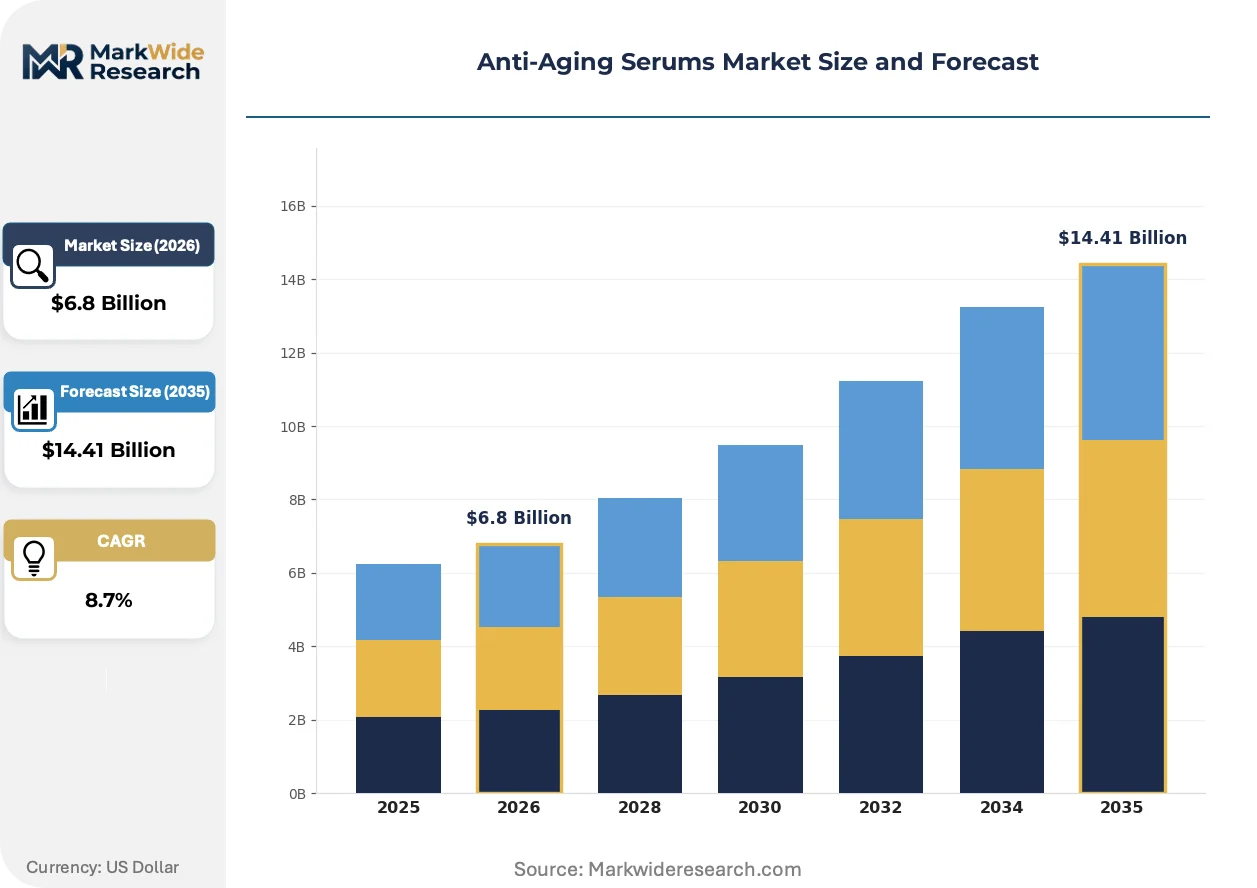
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retinol, Peptides, Antioxidants, Growth Factors Ingredient Source: Natural, Synthetic, Semi-Synthetic, Biotechnological Application: Daily Use, Night Use, Spot Treatment, Professional Treatment End User: Females, Males, Dermatologists, Aestheticians |
| Companies Covered | Estée Lauder, L'Oréal, Procter & Gamble, Shiseido, Beiersdorf, Unilever, Johnson & Johnson, Coty, Skinceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aging Serums Market Strategic Shifts
Biotechnological ingredient sourcing is restructuring competitive advantage in anti-aging serums, compressing the premiumization timeline for peptide actives while regulatory frameworks fragment across export markets.
Signal peptide synthesis via precision fermentation is modularizing supply chain architecture for anti-aging actives. Biotech platforms enable plug-and-play production of customized peptide sequences without retooling chemical synthesis infrastructure. Prestige and mass-market brands now access comparable raw material quality tiers, collapsing traditional ingredient-grade stratification.
REACH authorization requirements for novel biotechnological cosmetic ingredients are extending development timelines for EU market entry. The European Chemicals Agency's hazard-based assessment protocols demand extensive dossier preparation that smaller fermentation startups cannot resource. Professional treatment brands with established regulatory affairs functions capture first-mover positioning on next-generation peptide launches.
Subscription-based serum replenishment models are displacing traditional retail purchasing cycles in the United States. Direct-to-consumer platforms embed skin progression tracking that locks consumers into algorithm-matched peptide regimens. Dermatology clinic dispensing partnerships reinforce this channel shift by integrating professional-grade serums into post-treatment home care protocols.
Anti-Aging Serums Market Segmentation
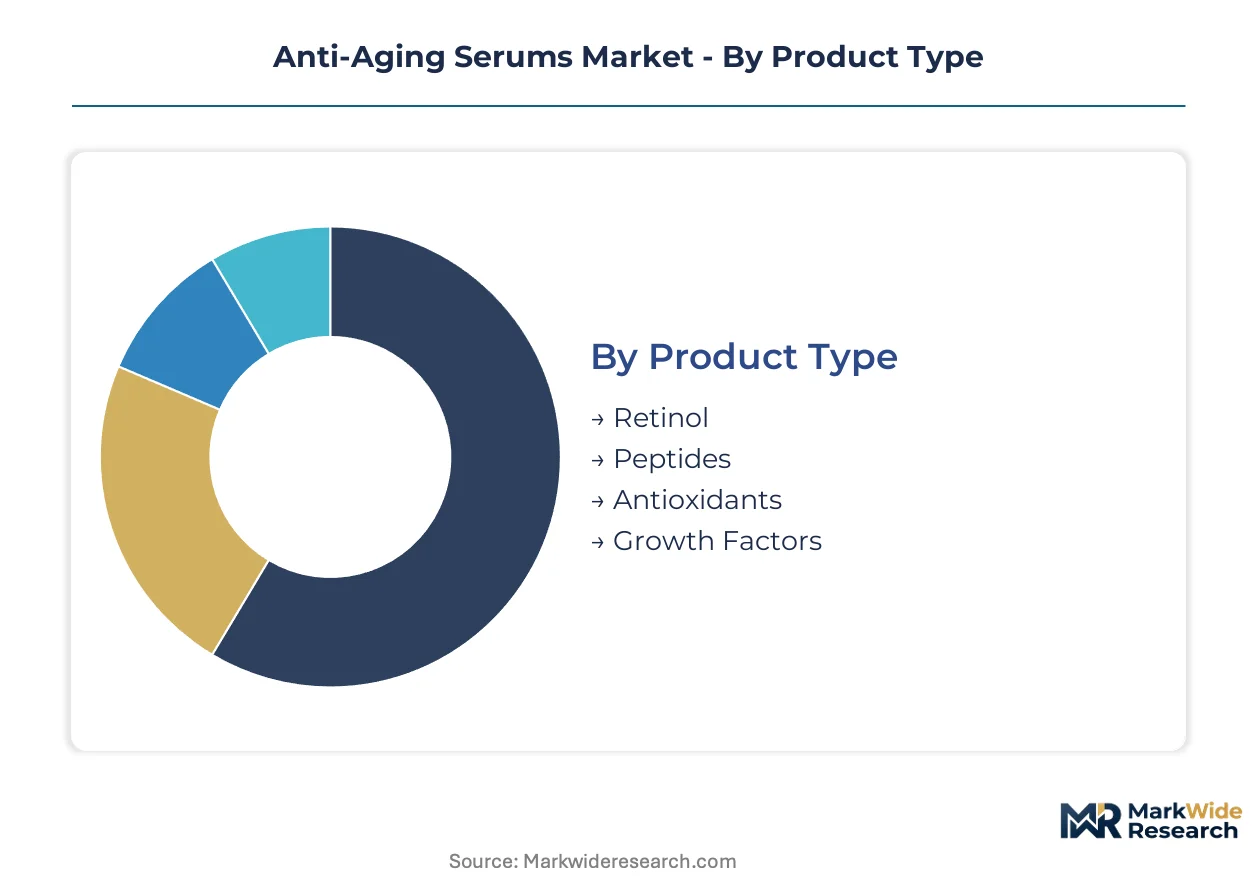
Anti-aging serum segmentation reveals how regulatory frameworks and channel requirements fragment product development priorities. Formulation choices directly determine which approval pathways manufacturers must navigate across export markets.
Product Type:
Retinol formulations face REACH concentration caps in EU markets, while peptide variants encounter lighter documentation burdens under ECHA's cosmetic ingredient framework.
- Retinol:Vitamin A derivatives formulated at 0.1% to 1.0% concentrations accelerate cellular turnover through retinoic acid receptor activation. Demand concentrates in United States dermatology clinics where FDA cosmetic rules permit higher potencies than REACH allows. Reformulation investments now dominate R&D budgets for brands seeking EU export eligibility.
- Peptides:Short-chain amino acid sequences signal collagen synthesis without the irritation profiles of retinoids. Medi-spa channels in Germany and South Korea drive procurement as these professional settings favor tolerability across repeated treatment protocols. ECHA's streamlined cosmetic classification reduces registration friction versus pharmaceutical-grade documentation.
- Antioxidants:Vitamin C, E, and polyphenol complexes neutralize free radical damage in daytime formulations.
- Growth Factors:Protein-based cellular signaling molecules derived from human stem cell cultures or recombinant biotechnology.
Leading the category by volume: Peptides. Growing fastest: Growth Factors.
Ingredient Source:
Source classification determines supply chain architecture, with biotechnological platforms commanding premium positioning through batch consistency guarantees.
- Natural:Plant-extracted actives from sources such as bakuchiol, green tea polyphenols, or marine algae antioxidants. Clean-beauty-positioned consumers in North American markets sustain stable margin pools despite slower expansion trajectories.
- Synthetic:Laboratory-engineered molecules including stabilized retinol esters and pure ascorbic acid variants. Mass-market brands in India leverage CDSCO's streamlined cosmetic registration for synthetic peptide entries versus natural-source stability documentation requirements.
- Semi-Synthetic:Hybrid molecules combining natural scaffold structures with synthetic functional modifications.
- Biotechnological:Precision fermentation platforms produce signal peptides and growth factors with reduced batch-to-batch variability.
Highest margin concentration: Biotechnological. Steepest expansion trajectory: Synthetic.
Application:
Application modality shapes packaging specifications, with professional treatment formats requiring clinical-grade sterility and higher concentration protocols.
- Daily Use:Lightweight, fast-absorbing formulations designed for morning application under sunscreen. United States direct-to-consumer subscriptions embed these SKUs into algorithm-matched replenishment cycles.
- Night Use:Higher-concentration retinol and peptide formulations exploiting enhanced skin permeability during sleep cycles. European medi-spa dispensing partnerships reinforce this segment through post-treatment home care protocols.
- Spot Treatment:Targeted high-potency applications for localized wrinkle or hyperpigmentation concerns.
- Professional Treatment:Clinical-grade serums administered or dispensed through dermatology clinics and aesthetic practices.
Volume leadership: Daily Use. Share gain pace: Professional Treatment.
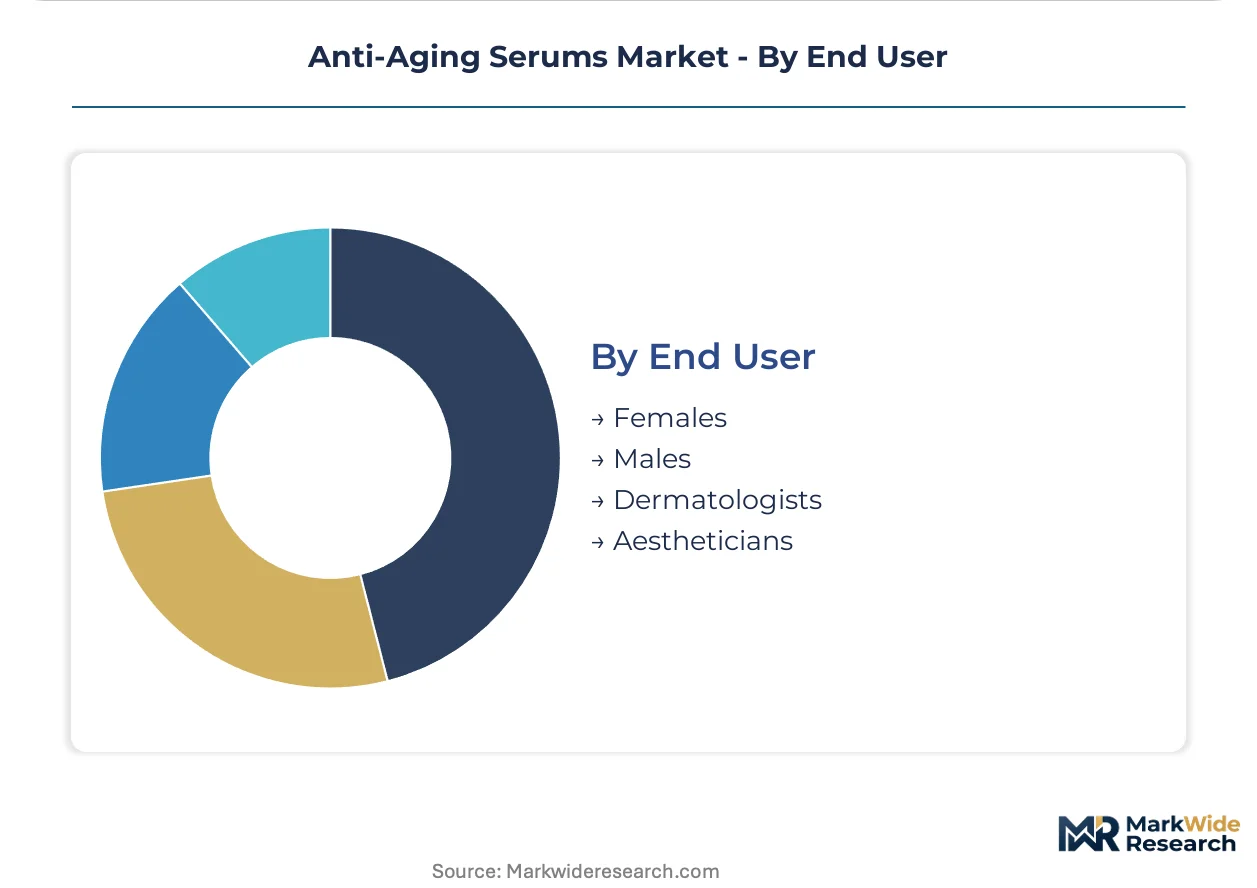
End User:
End-user segmentation exposes underpenetrated demographics where simplified messaging and barrier-focused claims unlock new volume pools.
- Females:Historical core demographic driving premium peptide and retinol procurement across all channels. Established purchasing patterns in United States prestige retail sustain revenue concentration.
- Males:Emerging segment responding to streamlined protocols marketed for barrier repair rather than cosmetic wrinkle reduction. German and South Korean markets show particular responsiveness to gender-neutral packaging and functional positioning.
- Dermatologists:Medical professionals prescribing or dispensing clinical-grade formulations as adjuncts to in-office procedures.
- Aestheticians:Licensed practitioners integrating serums into facial treatment protocols and retailing professional-grade home care.
Volume dominance: Females. Fastest-climbing participation: Males.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for anti-aging serums concentrates in the United States, where direct-to-consumer subscriptions and dermatology clinic dispensing channels drive premium peptide procurement. Germany and South Korea anchor European and Asian professional treatment segments through medi-spa network expansion. India emerges as the fastest-growing volume opportunity as CDSCO registration reforms accelerate peptide product launches.
United States
Telehealth-integrated skincare subscriptions embed algorithmic skin assessment tools that personalize peptide regimens and accelerate repurchase velocity. FDA cosmetic labeling requirements govern concentration limits for retinol-based formulations, shaping permissible efficacy claims. New York and Los Angeles concentrate prestige brand headquarters and dermatology clinic networks that dispense professional-grade serums.
Germany
Medi-spa channels in Berlin and Munich drive procurement of tolerable peptide formulations for repeated professional treatment protocols. ECHA's REACH framework restricts retinol percentages in cosmetic formulations, capping efficacy claims and forcing reformulation investments. The Rhine-Ruhr industrial cluster hosts contract manufacturers supplying pharmaceutical-grade peptide raw materials to premium serum brands.
South Korea
Fermented biotechnology ingredients differentiate domestic portfolios from Western competitors in Asian export markets. MFDS cosmetic registration requirements favor peptide-based products with streamlined documentation versus retinol stability dossiers. Seoul anchors research intensive development of signal peptides through convergence of cosmetic and pharmaceutical R&D infrastructure.
India
CDSCO's streamlined cosmetic registration pathway for peptide-based products reduces market entry barriers versus retinol formulations requiring extensive stability documentation. Maharashtra and Karnataka concentrate emerging premium skincare consumption in Mumbai and Bangalore metro corridors. Domestic contract manufacturers leverage synthetic chemistry capabilities to supply mass-market peptide lines for regional brands.
Switzerland
Three contract manufacturers control sixty percent of pharmaceutical-grade peptide supply, creating single-source vulnerability for premium serum brands worldwide. Swissmedic's stringent quality standards reinforce the country's positioning as a high-reliability sourcing hub. The Basel-Zurich corridor concentrates biotechnology fermentation facilities producing consistent-batch signal peptides for professional treatment channels.
Anti-Aging Serums Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with prestige houses commanding premium positioning and fermentation platforms supplying raw material tiers. The vendor base stratifies into three archetypes: established multinationals with clinical heritage, biotechnology startups with precision fermentation capabilities, and contract manufacturers controlling peptide synthesis infrastructure. Dominant competitive moves include backward integration into fermentation capacity and strategic partnerships with dermatology clinic networks for professional channel access.
Within the clinical heritage tier, Estée Lauder leverages its dermatology credibility to anchor professional treatment channel positioning. L'Oréal occupies a scale-driven position spanning mass and prestige peptide lines simultaneously through portfolio breadth. Shiseido represents the biotechnology differentiation archetype, with fermented ingredient sourcing distinguishing its Asian market presence from Western competitors.
| Leading Market Players |
|---|
| Estée Lauder |
| L'Oréal |
| Procter & Gamble |
| Shiseido |
| Beiersdorf |
| Unilever |
| Johnson & Johnson |
| Coty |
| Skinceuticals |
| Others |
Value Chain & Pricing Dynamics
Performance-grade divergence between pharmaceutical-grade and cosmetic-grade peptide inputs shapes both margin capture and sourcing architecture across the anti-aging serum market. REACH-compliant retinol formulations command premium positioning in United States dermatology clinics where FDA concentration rules permit higher potencies, while fermentation-derived peptide actives enable mass-market brands to compress cost positions without sacrificing batch consistency.
Pricing Analysis
Volume leadership concentrates in mass-market peptide lines where synthetic chemistry platforms enable competitive unit economics, while margin capture clusters around professional-grade biotechnological formulations with pharmaceutical-grade certification. Pricing stratifies across premium, standard, and economy tiers based on ingredient sourcing tier and clinical validation depth. Cost compression in synthetic peptide segments is intensifying because CDSCO's streamlined registration pathway in India accelerates competitor entry. Dermatology clinic dispensing channels exhibit lowest price sensitivity due to outcome-based professional protocols, whereas direct-to-consumer subscription buyers demonstrate higher elasticity to promotional cadence.
Supply Chain Analysis
Specialized fermentation technicians and cosmetic chemists with biotechnological formulation expertise concentrate in Switzerland, Germany, and South Korea, constraining capacity expansion timelines for precision-derived active production. Pharmaceutical-grade peptide supply draws from Swiss contract manufacturers, Indian synthetic chemistry facilities, and South Korean fermentation platforms. Single-source vulnerability pervades the premium tier where three Swiss suppliers control majority pharmaceutical-grade peptide output. Distribution runs through dermatology clinic dispensing partnerships in professional channels and telehealth-integrated subscription platforms in direct-to-consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive position in anti-aging serums increasingly hinges on backward integration into fermentation capacity and captive control over pharmaceutical-grade peptide supply. Players securing upstream biotechnology infrastructure capture margin expansion and regulatory first-mover positioning simultaneously.
For Market Incumbents: Anticipate margin compression in synthetic peptide mass-market lines as Indian contract manufacturers scale capacity and CDSCO registration reforms lower entry barriers. Defensive consolidation should prioritize captive fermentation facility investment in the Basel-Zurich corridor or strategic partnerships with Swissmedic-certified suppliers to secure pharmaceutical-grade raw material tiers. Channel control through dermatology clinic dispensing partnerships reinforces professional treatment positioning against direct-to-consumer disruptors. For New Entrants and Emerging Players: Precision fermentation platforms for customized signal peptide sequences offer technology-first wedge into underserved professional treatment segments where batch consistency commands premium pricing. White-space targets include India's emerging premium skincare corridor and Germany's male grooming vertical, both showing responsiveness to simplified barrier-repair messaging. Go-to-market execution should embed AI-driven skin analysis tools compliant with EU AI Act transparency requirements to differentiate algorithm-matched regimen recommendations. For Investors and Strategic Acquirers: Re-rating potential sits with biotechnology startups possessing precision fermentation capabilities and established ECHA dossier preparation infrastructure given REACH authorization timeline advantages for next-generation peptide launches. Long-term viability over the coming decade favors platforms with modular production architecture enabling rapid sequence customization without chemical synthesis retooling. The signal to monitor is CDSCO registration volume acceleration for peptide-based entrants, which indicates competitive intensity inflection in mass-market tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive peptide production reduces Swiss supplier dependency and secures REACH-compliant batch consistency. |
| Dermatology Clinic Dispensing Partnership | Professional channel integration locks in post-treatment home care protocols and reinforces premium positioning. |
| AI-Driven Skin Analysis Platform | Algorithm-matched regimen recommendations comply with EU AI Act transparency standards while accelerating repurchase velocity. |
| CDSCO Registration Pathway Optimization | Streamlined peptide product entry into India reduces time-to-market versus retinol stability documentation requirements. |
| Men's Grooming Vertical Extension | Barrier-repair messaging unlocks underpenetrated male segments in Germany and South Korea with simplified protocols. |
Study Parameters
Document review covered ECHA REACH guidance documents, FDA cosmetic labeling regulations, CDSCO cosmetic registration protocols, and MFDS biotechnological ingredient frameworks, complemented by interviews with dermatology clinic procurement directors, cosmetic formulation chemists, peptide contract manufacturing executives, and direct-to-consumer brand operators. Secondary validation drew from customs trade databases, Swissmedic quality certification records, and professional treatment channel dispensing reports. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Cross-referencing historical peptide adoption curves against expert panel input on fermentation scale-up timelines anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type tier, ingredient source classification, application modality, and end-user demographic. CAGRs were derived from regression analysis of professional channel procurement volumes and direct-to-consumer subscription replenishment velocities. Industry-specific forecast inputs incorporated ECHA authorization pipeline status for novel biotechnological actives and telehealth platform integration penetration rates.
Several conditions sit outside the modeled scope, including abrupt ECHA concentration limit revisions for retinol formulations, Swiss supplier consolidation events, and algorithmic transparency enforcement actions under the EU AI Act. Forecasts reflect documented assumptions regarding fermentation facility qualification timelines and regulatory pathway stability. Material deviation in peptide raw material availability, REACH authorization delays, or AI Act compliance cost escalation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
South America Cosmeceuticals Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Global Skin Lightening Market