
 Lip Powder Market | 2026-2036
Lip Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Powder Market Analysis
REACH compliance is recalibrating the cost-of-entry calculus for new lip powder entrants in Europe, forcing reformulation investments that favor established laboratories. L'Oréal leverages its in-house toxicology infrastructure to navigate substance restriction updates ahead of smaller competitors. Estée Lauder Companies anchors its premium positioning through captive R&D centers that validate safety dossiers for mineral-based lines. Shiseido Company differentiates via Japan's stringent cosmetic standards, converting regulatory rigor into export credibility across Asian markets.
Lip powder comprises micro-fine pigment particles bound with silica, mica, or talc carriers, engineered for dry application that delivers matte-to-satin finishes with extended wear resistance; the format serves consumers seeking transfer-proof color without liquid or wax-based heaviness. The matte category dominates volume due to its alignment with professional make-up workflows demanding longevity under studio lighting. Vegan formulation is expanding fastest as clean beauty certifications from PETA and Leaping Bunny reshape retailer procurement criteria. Specialty stores capture the highest margin pools by curating prestige brands with demonstrable ingredient provenance and personalized shade-matching services.
The FDA governs color additive safety through 21 CFR 73 and 74 listings, while the EU's REACH framework and MDR-adjacent cosmetic vigilance requirements impose parallel compliance burdens on multinational suppliers. China's NMPA and GB standards for imported cosmetics add a third regulatory layer, particularly for brands sourcing mica or titanium dioxide from cross-border supply chains. Stakeholders must monitor pending PFAS restrictions in both European and North American jurisdictions, as these synthetic compounds appear in some long-wear binding systems and threaten reformulation timelines.
Market Dynamics
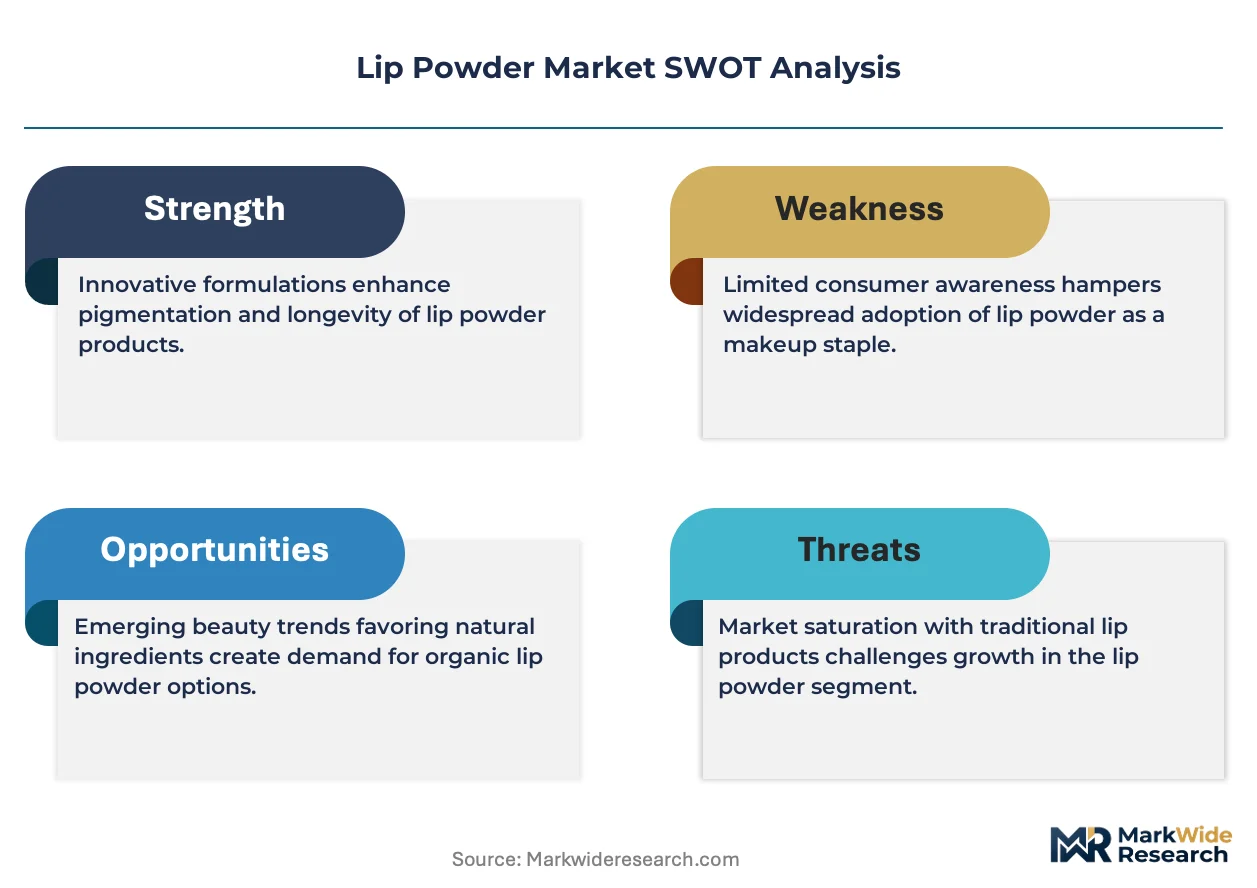
REACH substance restriction updates are forcing simultaneous reformulation across European lip powder portfolios, compressing development timelines and elevating toxicology infrastructure from cost center to competitive barrier.
Growth Catalysts
- Clean beauty certification proliferation:PETA and Leaping Bunny standards are reshaping retailer procurement criteria, channeling formulation investment toward vegan mineral bases.
- Professional makeup artist adoption:Studio workflows under high-intensity lighting demand transfer-proof, long-wear formats that dry application delivers without wax-based heaviness.
- Specialty retail channel expansion:Curated prestige positioning with personalized shade-matching services captures margin pools unavailable through mass-market distribution.
Market Restraints
- Mica supply concentration:Cross-border sourcing from limited geographic clusters exposes brands to ethical sourcing verification costs and supply disruption risk.
- PFAS regulatory overhang:Pending restrictions in European and North American jurisdictions threaten reformulation timelines for long-wear binding systems.
- Input cost volatility:Silica and titanium dioxide price fluctuations compress margin stability for mineral-based format producers.
Strategic Opportunities
- Japan's stringent cosmetic standards:Regulatory rigor converts into export credibility across Asian markets for brands validating safety dossiers to PMDA levels.
- Digital-first distribution models:Direct-to-consumer channels with virtual try-on technology bypass traditional retail gatekeepers and capture first-party shade preference data.
- Biodegradable carrier innovation:Convergence of micro-fine pigment engineering with plant-derived silica alternatives opens premium positioning against conventional talc and mica.
Industry Challenges
- Toxicology dossier compilation:REACH-compliant safety documentation demands specialized regulatory affairs talent scarce among mid-scale laboratories.
- Multi-jurisdiction compliance synchronization:Parallel FDA 21 CFR, EU REACH, and China NMPA filing timelines strain product launch coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Powder Market |
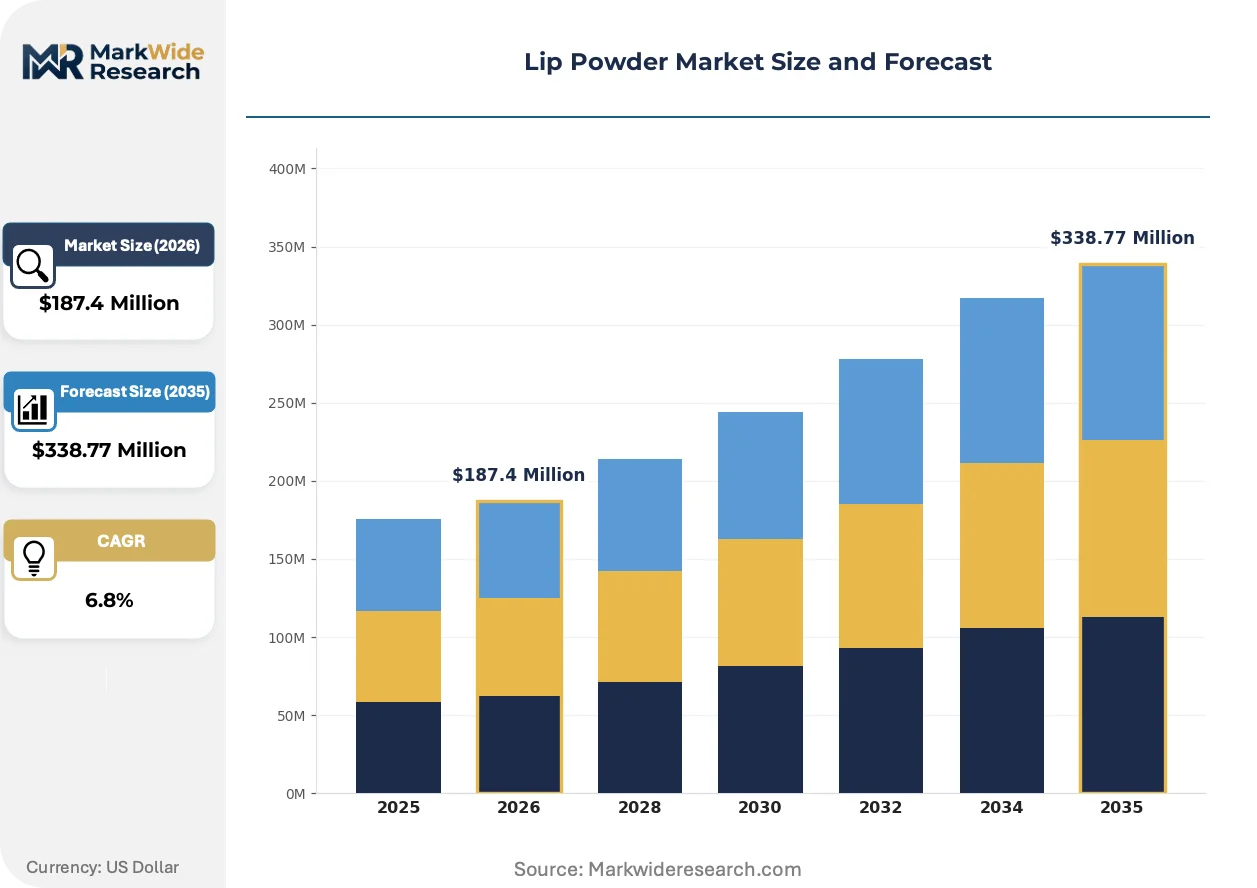
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matte, Shimmer, Satin, Glitter Application: Everyday Use, Professional Make-up, Special Occasions, Casual Outings Distribution Channel: Online Retail, Department Stores, Specialty Stores, Drugstores Formulation: Mineral-based, Vegan, Organic, Conventional |
| Companies Covered | L'Oréal, Estée Lauder Companies, Shiseido Company, Revlon, LVMH, Coty, Huda Beauty, Procter & Gamble, BY TERRY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Powder Market Emerging Trajectories
Formulation chemistry and distribution architecture are undergoing simultaneous recalibration as regulatory pressure intersects with shifting purchase behavior in color cosmetics.
Silica-microsphere encapsulation technology is consolidating matte-finish formulation standards by enabling controlled pigment release without wax binders. Professional makeup artists in Los Angeles and London studios are adopting these systems at accelerating rates for high-definition camera work. The technology is consolidating supplier tiers as only laboratories with particle engineering capabilities meet performance benchmarks.
REACH Annex XVII substance restriction expansions are recalibrating European formulation pipelines toward restricted substance lists with accelerated compliance deadlines. Industrial consequence includes mandatory toxicology infrastructure investment that favors established players with captive R&D centers. Mineral-based lines targeting Germany and France face compressed reformulation timelines as ECHA updates propagate through supply contracts.
Specialty store buyers are prioritizing demonstrable ingredient provenance over traditional brand heritage in assortment decisions. Curated retail channels in New York, Paris, and Milan are displacing conventional department store counters with personalized consultation models. This pattern is most visible in United States coastal markets where clean beauty certification drives shelf placement authority.
Lip Powder Market Segmentation
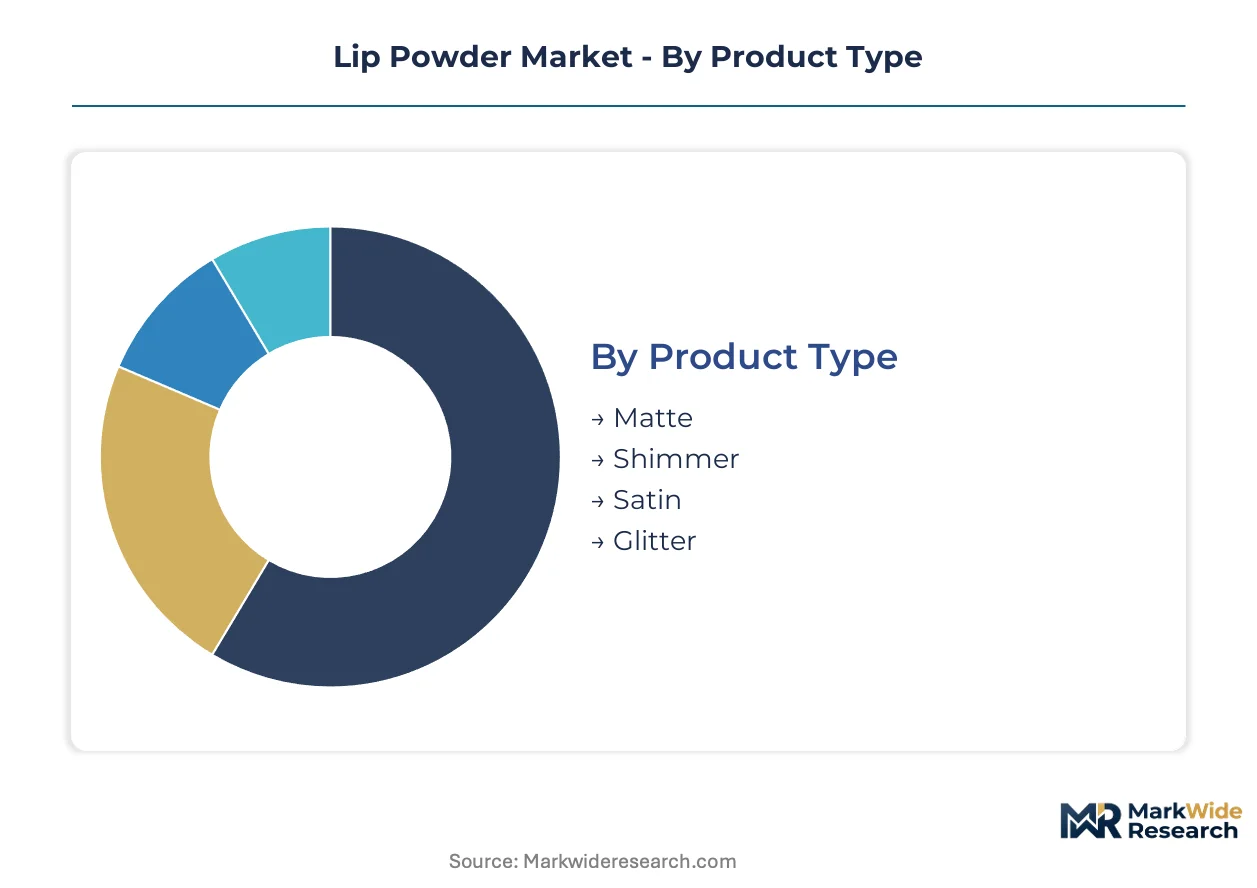
Segmentation in lip powder markets reveals how formulation chemistry, distribution architecture, and end-use context create distinct margin pools. Upgrade cycles vary dramatically across professional versus everyday applications, with mineral-based formats commanding premium positioning through certification-driven procurement.
Product Type:
Replacement cycles accelerate where professional workflows demand studio-grade performance under high-intensity lighting.
- Matte:Silica-microsphere encapsulation enables controlled pigment release without wax binders, delivering transfer-proof finishes that withstand extended wear under camera lighting. Los Angeles and London studio professionals are consolidating procurement around these systems for high-definition production work. Volume placements concentrate in Matte; the faster expansion belongs to Shimmer.
- Shimmer:Mica-based light-reflective particles create dimensional finishes through engineered particle size distribution, with demand clustering in evening and editorial contexts where luminosity outweighs longevity requirements. Specialty retailers in Paris and Milan curate these formats for personalized consultation models.
- Satin:Balanced pigment-to-binder ratios yield semi-matte finishes with subtle light diffusion, serving consumers seeking professional aesthetics without full studio-grade investment.
- Glitter:Larger particle suspensions in mineral carriers target festival and entertainment segments with bold visual impact prioritized over everyday wearability.
Professional procurement gravitates toward Matte for reliability; consumer experimentation drives Shimmer adoption fastest.
Application:
Cost tier differentiation separates premium positioning from mass-market accessibility across usage contexts.
- Everyday Use:Consumers prioritize convenience and comfort for daily wear, favoring satin and matte formats with simplified application routines. United States coastal markets show concentration here as clean beauty certification influences routine purchasing decisions.
- Professional Make-up:Studio workflows demand batch consistency and extended wear validation, with makeup artists specifying mineral-based matte systems for bridal, editorial, and film production. REACH-compliant safety dossiers have become non-negotiable entry requirements for European professional kit suppliers.
- Special Occasions:Event-driven purchasing elevates shimmer and glitter formats where photographic performance and novelty outweigh per-use cost considerations.
- Casual Outings:Lightweight satin formulations serve intermittent use patterns with lower commitment thresholds and accessible price positioning.
Professional application commands highest per-unit margins; everyday use generates largest absolute volume.
Distribution Channel:
Customer type determines channel preference, with curation-seeking buyers diverging from convenience-oriented purchasers.
- Specialty Stores:Curated prestige positioning with personalized shade-matching services captures margin pools unavailable through mass-market distribution. New York and Paris flagships emphasize demonstrable ingredient provenance over traditional brand heritage in assortment decisions.
- Online Retail:Direct-to-consumer channels with virtual try-on technology bypass traditional retail gatekeepers and capture first-party shade preference data. Digital-first models are expanding fastest as algorithmic personalization reduces return rates.
- Department Stores:Conventional counter models face displacement as specialty formats capture curation-oriented consumers seeking consultation depth.
- Drugstores:Mass-market accessibility serves price-sensitive segments with conventional formulations and limited shade range efficiency.
Specialty stores anchor premium volume; online retail climbs the fastest as virtual try-on technology matures.
Formulation:
Supply concentration in mineral sourcing creates tiered entry barriers based on certification infrastructure investment.
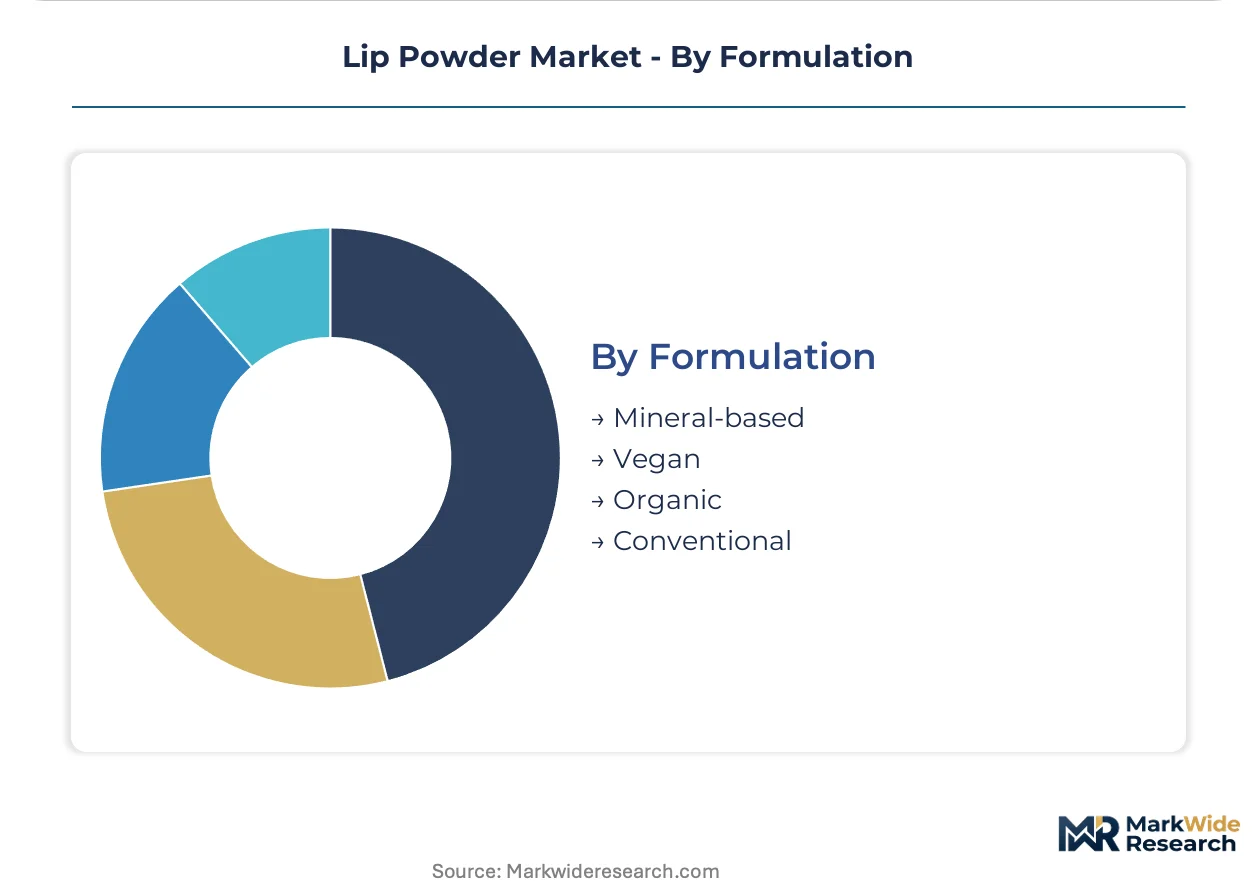
- Mineral-based:Micro-fine pigment particles bound with silica, mica, or talc carriers engineered for dry application deliver matte-to-satin finishes with extended wear resistance. Professional makeup artists across Germany and France are expanding procurement as REACH compliance validates safety dossiers.
- Vegan:Absence of animal-derived binders and colorants aligns with PETA and Leaping Bunny certification requirements reshaping retailer procurement criteria. This segment is expanding most quickly as clean beauty certifications displace conventional positioning.
- Organic:Plant-derived carrier systems and naturally sourced pigments target consumers prioritizing agricultural provenance alongside cosmetic performance.
- Conventional:Synthetic binder systems and petroleum-derived carriers maintain cost efficiency for mass-market price positioning despite regulatory headwinds.
Mineral-based formulations dominate professional procurement; vegan certification drives fastest consumer segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Parc d'Activités de la Plaine Saint-Denis hosts concentrated formulation R&D, drawing clean beauty investment through tax-advantaged zones. Specialty retail flagships in Paris and Lyon anchor European premium positioning.
United States
Clean beauty certification from PETA and Leaping Bunny drives procurement criteria shifts among specialty retailers. FDA 21 CFR 73 and 74 listings govern color additive safety dossiers. Los Angeles studio professionals specify mineral-based matte systems for high-definition production workflows.
Germany
REACH Annex XVII substance restriction updates compress reformulation timelines for mineral-based portfolios. ECHA compliance documentation demands specialized toxicology infrastructure. Berlin and Hamburg laboratories validate safety dossiers ahead of competitor filings.
France
Specialty store buyers in Paris and Lyon prioritize demonstrable ingredient provenance over brand heritage. ANSM cosmetic vigilance requirements parallel EU REACH frameworks. Île-de-France formulation clusters convert regulatory rigor into export credibility.
Japan
PMDA stringent cosmetic standards enable export positioning across Asian markets. METI industrial policy supports mineral-based innovation through targeted R&D subsidies. Osaka and Tokyo R&D centers anchor captive toxicology infrastructure.
United Kingdom
Professional makeup artist adoption accelerates in London editorial and bridal segments. UK REACH alignment with EU substance restrictions maintains parallel compliance burdens. Manchester and Birmingham distribution hubs serve specialty retail channels.
Lip Powder Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning bands. The structure concentrates around three strategic archetypes: multinational beauty conglomerates with captive R&D infrastructure, mid-scale specialty houses emphasizing clean beauty certification, and digital-native direct-to-consumer brands. Competitive moves center on M&A for toxicology capabilities and strategic partnerships for mica supply security.
Within the multinational conglomerate tier, L'Oréal and Estée Lauder Companies exemplify archetypes distinguished by in-house regulatory affairs scale. Shiseido Company occupies a position converting Japan's PMDA standards into Asian market export credibility. Among specialty-focused entities, Huda Beauty and BY TERRY represent positioning built on influencer-driven distribution and curated retail channel depth respectively.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder Companies |
| Shiseido Company |
| Revlon |
| LVMH |
| Coty |
| Huda Beauty |
| Procter & Gamble |
| BY TERRY |
| Others |
Supply Flow & Price Mechanics
Professional makeup artist procurement in Los Angeles and London studios concentrates demand for REACH-validated mineral-based systems, anchoring a contract-based pricing model where long-term offtake agreements secure batch consistency premium. This buyer archetype's specification power elevates toxicology documentation from compliance cost to price justification lever.
Pricing Analysis
Short lead-time premiums dominate specialty retail channels, where curated Paris and Milan flagships command markups for immediate shade-matching availability against standard delivery timelines. Three-tier pricing structure across prestige, professional-grade, and mass-market levels separates certification depth from formulation complexity. Cost compression in mineral-based tiers is intensifying because REACH Annex XVII updates force simultaneous reformulation investments. Mass-market drugstore segments exhibit highest price sensitivity; professional kit suppliers show least.
Supply Chain Analysis
Regional distribution centers in Hamburg, Lyon, and Osaka anchor hub-and-spoke patterns serving specialty retail and direct-to-consumer channels. Mica sourcing concentrates in India, Madagascar, and Brazil; silica processing centers on Germany, China, and the United States. Raw material dependencies include titanium dioxide, engineered microspheres, and plant-derived carrier alternatives. Single-source vulnerability in ethical mica verification threatens continuity. Distribution runs through captive laboratory networks and third-party logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty retail shelf space constraints prop pricing power for REACH-compliant portfolios, as finite formulation laboratory capacity bottlenecks new entrant supply. This supply-constrained structure favors incumbents with validated toxicology infrastructure.
For Market Incumbents: Hedge against PFAS regulatory overhang by accelerating biodegradable carrier R&D in captive Osaka and Berlin centers. Secure multi-year mica supply agreements with verified ethical sourcing chains before ECHA restriction timelines compress. Channel control through exclusive specialty retail partnerships limits emerging clean beauty brand shelf access. For New Entrants and Emerging Players: Digital-native direct-to-consumer channels offer lowest barrier entry, bypassing gatekeeper concentration in Paris and New York specialty retail. Target vegan certification white-space in United States coastal markets where PETA and Leaping Bunny procurement criteria reshape assortment decisions. Virtual try-on technology deployment captures first-party shade preference data for algorithmic personalization. For Investors and Strategic Acquirers: The window for entry favors mid-scale laboratories with captive REACH toxicology dossier capabilities. Long-term viability rests on regulatory affairs talent scarcity creating acquisition premiums for compliant infrastructure. Watch ECHA substance restriction update velocity as inflection indicator for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Toxicology Infrastructure Investment | Captive laboratory validation in Berlin and Hamburg accelerates European market entry ahead of competitors. |
| Ethical Mica Supply Agreement | Verified sourcing chains from Madagascar and India reduce disruption risk under EU conflict mineral scrutiny. |
| Biodegradable Carrier R&D Program | Plant-derived silica alternatives open premium positioning against conventional talc-dependent formulations. |
| Direct-to-Consumer Channel Launch | Virtual try-on technology bypasses specialty retail gatekeepers in Paris and New York. |
| Clean Beauty Certification Repositioning | PETA and Leaping Bunny validation drives procurement criteria shifts among United States specialty retailers. |
Methodological Framework
Independent corroboration across formulation laboratory executives, specialty retail category buyers, professional makeup artists, and regulatory affairs consultants underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through ECHA substance restriction databases, FDA 21 CFR color additive listings, and customs trade records for mica and titanium dioxide flows. Bottom-up volume triangulation against top-down value estimates anchored market sizing.
Comparable-period anchoring tied projection trajectories to historical mineral-based format adoption curves and clean beauty certification proliferation rates. The analytical framework segmented by product finish type, application context, distribution channel, and formulation chemistry across the modeling period. CAGR derivation incorporated professional procurement intensity indices and specialty retail expansion velocity. Forecast inputs included REACH compliance cost curves and virtual try-on technology penetration assumptions.
Caveats apply where PFAS restriction implementation timelines or mica supply disruption events could materially shift the outlook. Forecasts reflect documented assumptions around regulatory enforcement consistency and clean beauty certification retailer adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Anti-Acne Serum Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market