
 Asia Pacific Cosmetic Preservatives Market | 2026-2036
Asia Pacific Cosmetic Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cosmetic Preservatives Market Analysis
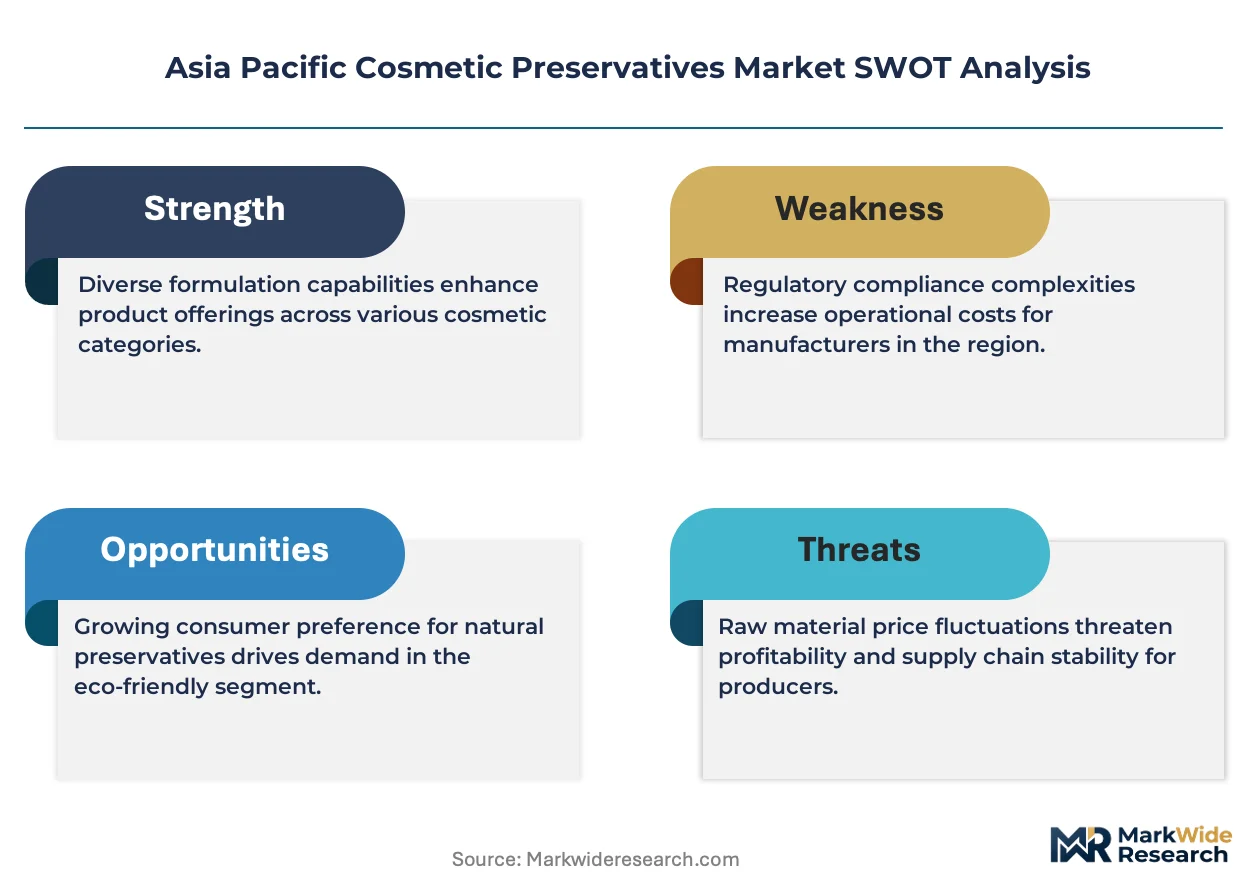
ISO 16128 natural and organic cosmetics certification is reorganizing supplier eligibility across the Asia Pacific, forcing reformulation investments from preservative makers. Evonik Industries AG leverages its amino acid-derived biotech portfolio to anchor clean-label supply relationships with Korean and Japanese formulators. Symrise AG sustains regional competitiveness through specialized botanical preservation actives that navigate ASEAN harmonized cosmetic directive variations. BASF SE dominates synthetic organic acid production at scale, operating integrated fermentation complexes that control cost positions against smaller regional challengers.
Cosmetic preservatives comprise biocidal and biostatic compounds—typically phenoxyethanol, paraben esters, or organic acids at concentrations between 0.1% and 1.0%—engineered to inhibit microbial proliferation in water-based personal care matrices. Their primary commercial function extends product shelf stability while meeting dermatological safety thresholds for repeated skin contact. Phenoxyethanol and organic acids capture expanding share as paraben alternatives, with phenoxyethanol benefiting from broad-spectrum efficacy against Gram-negative bacteria and organic acids gaining traction in low-pH gel formulations where traditional donors degrade. Skincare applications command the deepest preservative specification requirements due to facial product sensitivity standards and extended wear times that elevate microbial risk profiles.
China's NMPA cosmetic registration rules, Japan's MHLW quasi-drug preservatives positive list, and ASEAN's cosmetic directive harmonization framework collectively restrict which actives gain market access across the region. These regulatory architectures shape R&D allocation, with compliance costs disproportionately burdening mid-tier suppliers lacking dedicated regulatory affairs teams in Shanghai or Tokyo. Stakeholders must monitor divergence between China's forthcoming cosmetic supervision regulations and Japan's existing standards, as misalignment would fragment formulation strategies and duplicate toxicological testing expenditures.
Market Dynamics
Clean-label procurement mandates from K-beauty conglomerates are cascading backward through Asia Pacific supply chains, forcing preservative suppliers to abandon paraben-dependent portfolios and absorb ISO 16128 certification costs.
Growth Catalysts
- Japan's MHLW quasi-drug positive list:This framework creates predictable regulatory pathways for novel preservation actives, reducing toxicological testing duplication for compliant suppliers.
- Biotechnology-derived amino acid platforms:Fermentation-based production of phenoxyethanol alternatives achieves cost parity with petrochemical routes while satisfying clean-label specifications.
- Southeast Asia skincare manufacturing clusters:Indonesia and Vietnam contract manufacturers are expanding water-based formulation capacity, driving preservative consumption intensity per unit output.
Market Restraints
- Feedstock volatility in organic acid precursors:Citric acid and sorbic acid raw material costs fluctuate with Brazilian sugarcane harvest cycles and Chinese citrate fermentation capacity.
- Regulatory fragmentation between NMPA and MHLW:Divergent cosmetic safety dossier requirements force dual registration expenditures for suppliers serving both China and Japan.
- Natural preservative efficacy gaps:Botanical extracts struggle to match phenoxyethanol's Gram-negative bactericidal performance in neutral pH emulsions.
Strategic Opportunities
- Vietnam's emerging domestic brand ecosystem:Local skincare labels lack captive R&D facilities, creating white-space demand for turnkey preservation system suppliers.
- ASEAN cosmetic directive harmonization:Streamlined ingredient approvals across member states reduce regulatory friction for multi-market formulations.
- Biotech-dermatology convergence:Preservative suppliers partnering with microbiome research platforms can develop skin-flora-compatible preservation systems.
Industry Challenges
- ISO 16128 certification backlog:Third-party auditors face capacity constraints, delaying supplier eligibility for clean-label procurement pools.
- Legacy paraben decontamination:Manufacturing facilities must validate equipment cleaning protocols to prevent cross-contamination in paraben-free production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cosmetic Preservatives Market |
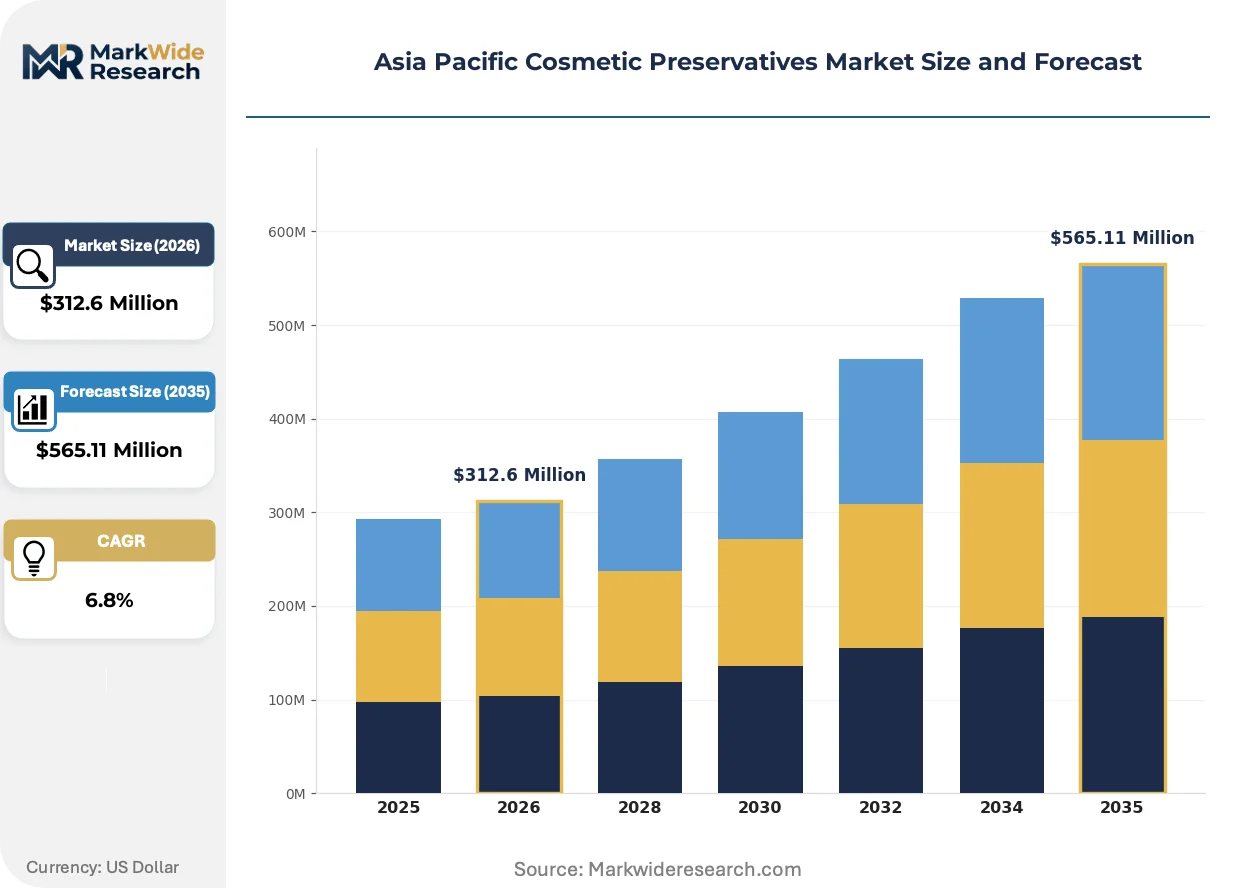
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabens, Formaldehyde Donors, Organic Acids, Phenoxyethanol Application: Skincare, Haircare, Makeup, Fragrances Formulation Type: Emulsions, Gels, Powders, Sprays End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | Evonik Industries AG, Symrise AG, Ashland Inc, Akema S.R.L., Celanese Corp, BASF SE, Lanxess AG, The Dow Chemical Company, Clariant AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cosmetic Preservatives Market Emerging Trajectories
Biotechnology platforms and regulatory harmonization efforts are compressing traditional synthetic preservative dominance while elevating fermentation-derived alternatives to commercial viability.
Enzymatic preservation systems harnessing glucose oxidase and lactoperoxidase are decomposing the technical barrier between natural-origin claims and broad-spectrum antimicrobial efficacy. Korean formulators at Amorepacific and LG Household & Health Care have accelerated adoption timelines from pilot to scale within eighteen-month cycles. This enzymatic shift is decomposing incumbent suppliers' reliance on phenoxyethanol as the default paraben alternative.
China's NMPA cosmetic supervision regulations are tightening safety dossier requirements for preservative concentrations above 0.5% in leave-on facial products. The industrial consequence is a surge in low-dose preservation system R&D combining organic acids with chelating agents. Domestic Chinese brands targeting Tmall flagship stores are most affected, redirecting formulation budgets toward compliance consulting.
Direct-to-consumer K-beauty brands now specify raw material provenance down to fermentation facility location, compressing traditional distributor layers. This disintermediation favors preservative suppliers with transparent supply chain documentation and captive biotech production. The behavior is most visible in South Korea's Olive Young retail ecosystem, where ingredient-conscious consumers drive brand reformulation cycles.
Asia Pacific Cosmetic Preservatives Market Segmentation
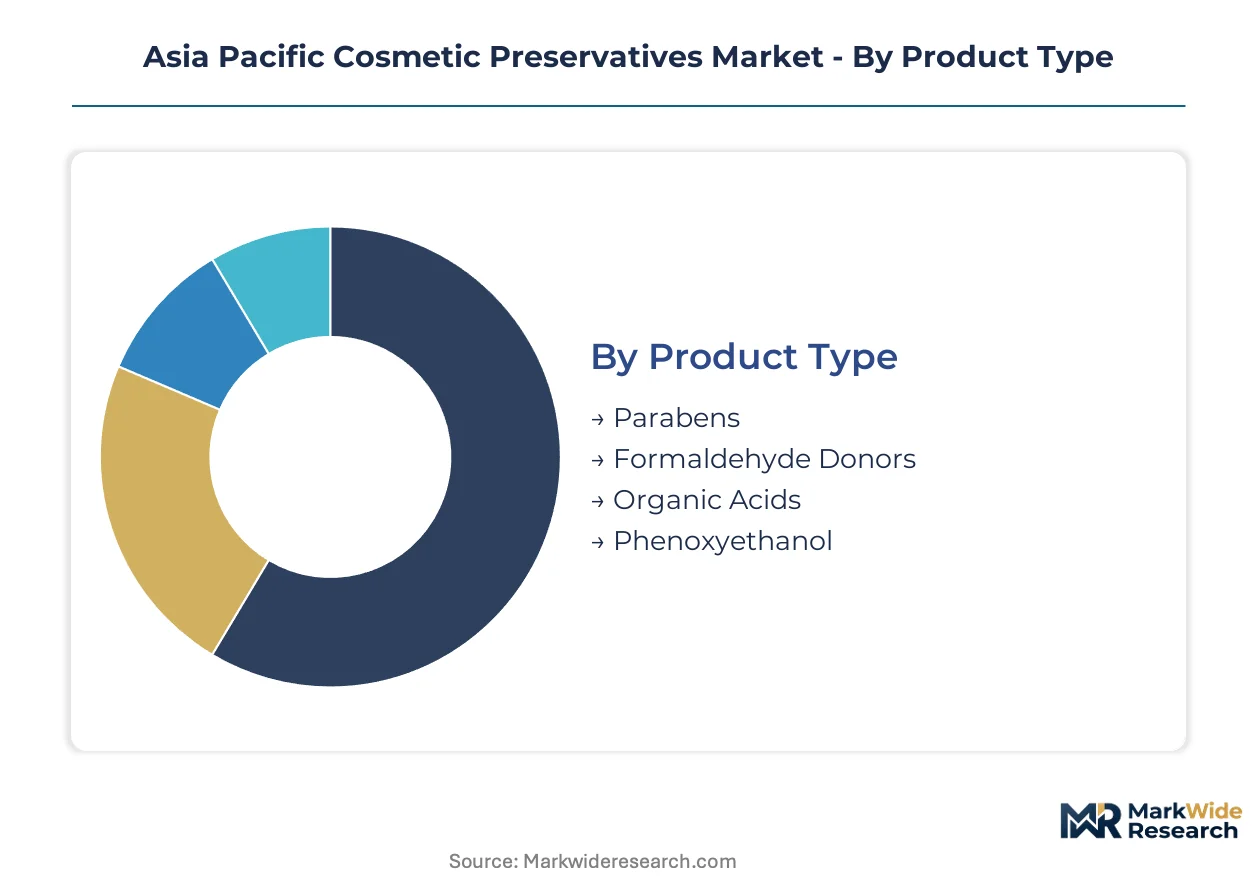
Preservative selection in Asia Pacific cosmetic manufacturing follows formulation chemistry, regulatory acceptance, and clean-label positioning rather than commodity logic. Segment boundaries shift as K-beauty procurement mandates cascade backward through supply chains, forcing suppliers to rebalance portfolios across incompatible technical specifications.
Product Type:
Paraben alternatives face the most intense substitution pressure as ISO 16128 certification and brand clean-label mandates systematically disqualify legacy chemistries from premium procurement pools.
- Phenoxyethanol:A glycol ether with broad-spectrum efficacy against Gram-negative bacteria at 0.5-1.0% concentrations. South Korean formulators at Amorepacific and LG Household & Health Care specify phenoxyethanol as the default paraben replacement in water-based serums, though Japan's MHLW maintains concentration caps in leave-on facial products.
- Organic Acids:Sorbic acid, benzoic acid, and their salts function optimally in low-pH gel matrices where dissociation states enhance antimicrobial activity. Chinese domestic brands targeting Tmall flagship stores absorb reformulation costs to meet NMPA safety dossier requirements for organic acid complexes above 0.5% threshold.
- Parabens:Methyl-, ethyl-, and propylparaben esters retain cost advantages in mass-market haircare and body wash segments across Southeast Asian contract manufacturing clusters.
- Formaldehyde Donors:DMDM hydantoin and diazolidinyl urea release formaldehyde slowly; Vietnam and Indonesia manufacturers specify these for rinse-off applications where regulatory scrutiny remains less intensive.
Phenoxyethanol anchors the volume base while organic acids gain share at the steepest rate.
Application:
Water content and wear duration determine preservation intensity, with facial products commanding the strictest microbiological safety margins.
- Skincare:Moisturizers, essences, and ampoules with 60-80% water content require multi-modal preservation systems combining phenoxyethanol with chelating agents. China's NMPA registration rules impose additional toxicological testing burdens on leave-on facial preservatives above 0.5% concentration.
- Haircare:Shampoos and conditioners tolerate higher pH ranges where organic acid efficacy degrades, favoring phenoxyethanol and formaldehyde donor combinations. Indonesian and Vietnamese contract manufacturers expand water-based formulation capacity for export to Korean brand owners.
- Makeup:Anhydrous and powder formulations reduce microbial risk, permitting lower preservative loads or antioxidant-only protection in lipsticks and pressed powders.
- Fragrances:High alcohol content provides intrinsic preservation, limiting biocidal additive requirements to trace levels in eau de parfum and cologne matrices.
Skincare commands the deepest specification requirements while haircare delivers the highest absolute tonnage demand.
Formulation Type:
Physical state dictates preservative solubility, release kinetics, and compatibility with emulsifier systems.
- Emulsions:Oil-in-water creams and lotions require partition-coefficient optimization to concentrate actives in the aqueous phase where microbial proliferation occurs.
- Gels:Carbomer-thickened matrices at pH 5.0-6.0 favor organic acid preservation with enhanced undissociated acid penetration through microbial cell membranes.
- Powders:Talc and starch-based color cosmetics rely on low water activity and packaging barriers rather than chemical preservation.
- Sprays:Aerosol and pump-dispensed formats introduce propellant and valve compatibility constraints that exclude certain organic acid salts.
Emulsions absorb the largest preservative volumes while gel formulations expand most quickly on clean-label positioning.
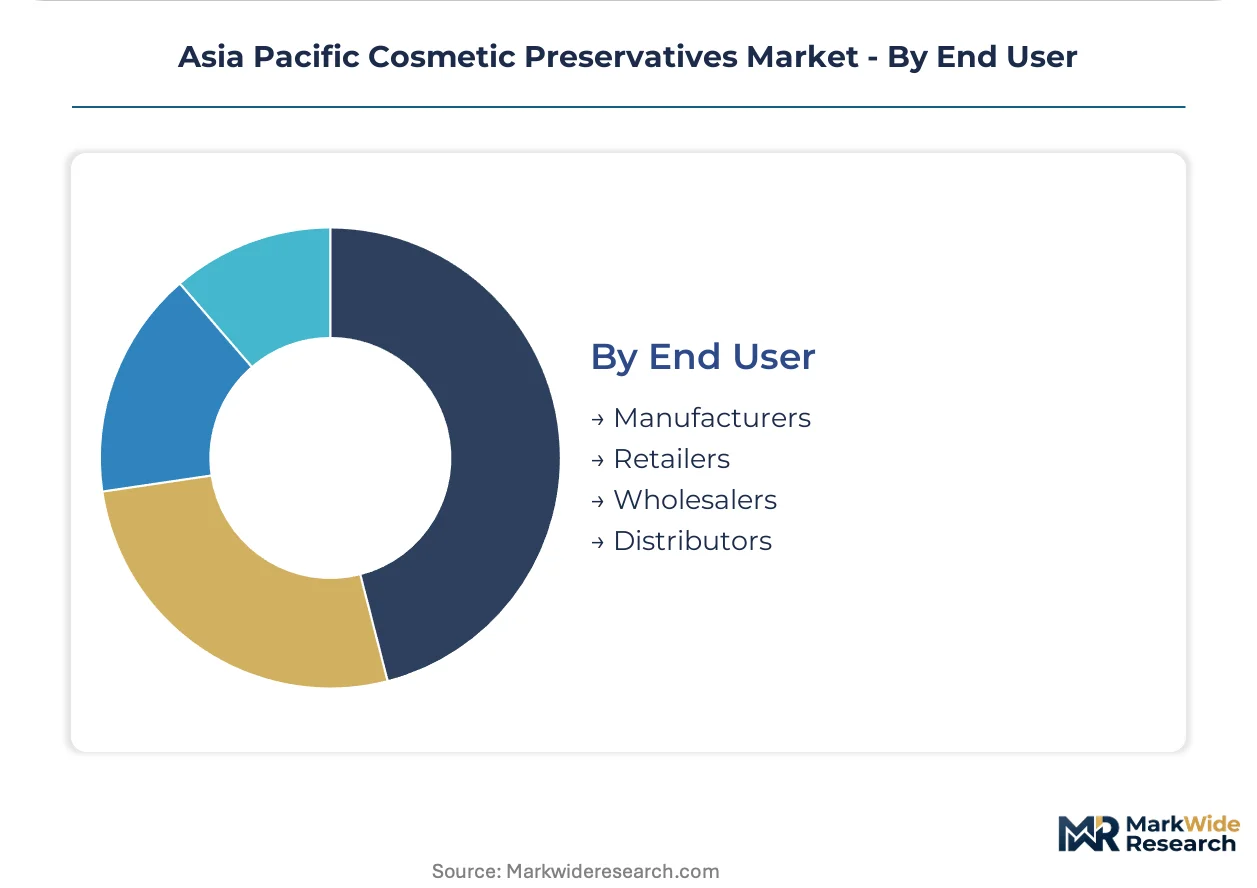
End User:
Supply chain position determines technical service intensity and regulatory documentation requirements.
- Manufacturers:Korean and Japanese formulators demand full supply chain documentation down to fermentation facility location, compressing distributor margins.
- Retailers:Olive Young and similar K-beauty retail ecosystems transmit consumer ingredient consciousness directly to brand reformulation cycles.
- Wholesalers:ASEAN regional traders navigate harmonized cosmetic directive variations across member state import requirements.
- Distributors:Domestic Chinese intermediaries face NMPA cosmetic supervision regulation compliance costs that favor consolidation toward larger regulatory affairs capabilities.
Manufacturers anchor procurement volume while retailer direct specifications gain influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA cosmetic supervision regulations and Japan's MHLW quasi-drug positive list are reorganizing formulation standards across the region. South Korea's K-beauty procurement mandates cascade backward through ASEAN supply chains. Vietnam and Indonesia contract manufacturers absorb compliance costs to maintain export eligibility.
China
Domestic skincare brands targeting Tmall flagship stores absorb reformulation costs to meet NMPA safety dossier requirements for preservatives above 0.5% concentration. The country's GB standards for cosmetic safety tighten toxicological testing burdens on leave-on facial products. Yangtze River Delta formulators redirect R&D budgets toward compliance consulting and low-dose preservation system development.
Japan
MHLW's quasi-drug preservatives positive list creates predictable regulatory pathways for novel preservation actives, reducing testing duplication for compliant suppliers. METI oversees harmonization efforts with ASEAN cosmetic directives. Kanto region formulators leverage this regulatory clarity to accelerate adoption of enzymatic preservation systems from pilot to commercial scale.
South Korea
Amorepacific and LG Household & Health Care specify raw material provenance down to fermentation facility location, compressing traditional distributor layers. MFDS maintains alignment with international cosmetic safety standards. Seoul Capital Area biotech suppliers capture clean-label procurement mandates through transparent supply chain documentation and captive fermentation production.
Vietnam
Local skincare labels lack captive R&D facilities, creating white-space demand for turnkey preservation system suppliers. The country's national cosmetic regulator navigates ASEAN harmonized directive variations. Ho Chi Minh City contract manufacturers expand water-based formulation capacity for Korean brand owners, driving phenoxyethanol and organic acid consumption intensity.
Indonesia
Haircare and body wash contract manufacturers specify formaldehyde donors for rinse-off applications where regulatory scrutiny remains less intensive. The national pharmaceutical and cosmetic regulator implements ASEAN cosmetic directive provisions. Java-based manufacturing clusters absorb feedstock volatility in citric acid precursors while expanding export-oriented water-based formulation capacity.
Asia Pacific Cosmetic Preservatives Market Vendor Landscape
Listed leaders compete with private specialists across fermentation scale and regulatory documentation capabilities. The supplier base organizes into three tiers: multinational chemical conglomerates with integrated biotech platforms, mid-cap specialists in botanical preservation actives, and regional distributors navigating NMPA-MHLW compliance fragmentation. Consolidation pressures concentrate among mid-tier suppliers lacking dedicated regulatory affairs teams in Shanghai or Tokyo. Dominant competitive moves include backward integration into amino acid fermentation capacity and strategic partnerships with microbiome research platforms.
Within the multinational tier, Evonik Industries AG anchors clean-label supply relationships through its amino acid-derived biotech portfolio. BASF SE occupies a position at the scale-driven end, leveraging integrated fermentation complexes to control cost positions against smaller regional challengers. Symrise AG exemplifies the botanical specialization archetype, sustaining regional competitiveness through preservation actives that navigate ASEAN directive variations. These three entities represent distinct strategic postures: biotech platform depth, manufacturing scale dominance, and regulatory agility through natural-origin positioning.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Symrise AG |
| Ashland Inc |
| Akema S.R.L. |
| Celanese Corp |
| BASF SE |
| Lanxess AG |
| The Dow Chemical Company |
| Clariant AG |
| Others |
Supply Flow & Price Mechanics
Fermentation capacity utilization at Yangtze River Delta and Kanto region biotech complexes anchors cost positions for amino acid-derived preservatives, compressing margin structures for smaller regional suppliers lacking captive production. This scale concentration enables integrated manufacturers to absorb ISO 16128 certification costs while maintaining price floors that exclude commodity traders from premium procurement pools serving Korean and Japanese formulators.
Pricing Analysis
Certification level creates the primary spread, with ISO 16128-compliant biotech-derived actives commanding substantial premiums over conventional synthetic alternatives. Three-tier pricing structure separates fermentation-origin premium grades from standard petrochemical phenoxyethanol and economy formaldehyde donors. Pricing pressure stems from K-beauty clean-label mandates cascading backward through supply chains, forcing mid-tier suppliers to absorb reformulation costs. Mass-market haircare manufacturers in Indonesia and Vietnam exhibit highest price sensitivity, while Seoul Capital Area skincare formulators prioritize supply chain transparency over unit cost.
Supply Chain Analysis
Inventory lead times for citric acid and sorbic acid precursors fluctuate with Brazilian sugarcane harvest cycles, compressing working capital efficiency for organic acid specialists. Manufacturing concentration centers on China, South Korea, and Japan, with Yangtze River Delta fermentation complexes supplying amino acid platforms and Kanto region facilities producing enzymatic preservation systems. Raw material dependencies include Brazilian sugarcane-derived citric acid, Chinese corn-based fermentation feedstocks, and Korean biotech-engineered enzyme cultures. Single-source vulnerability in citric acid precursors elevates supply risk during South American climate disruptions. Distribution runs through direct manufacturer-to-formulator relationships in premium tiers, with ASEAN regional traders handling economy-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific cosmetic preservatives sit within early-cycle expansion as biotechnology-derived alternatives achieve cost parity with petrochemical routes, accelerating clean-label adoption timelines from pilot to commercial scale.
For Market Incumbents: Secure captive fermentation capacity in Yangtze River Delta or Kanto region clusters to defend margin positions against feedstock volatility. Prioritize ISO 16128 certification investment to maintain eligibility for Amorepacific and LG Household & Health Care procurement pools, as clean-label mandates systematically disqualify uncertified suppliers from premium formulation contracts. For New Entrants and Emerging Players: Lead with turnkey preservation system offerings targeting Vietnam's domestic skincare brands, which lack captive R&D facilities and absorb technical service bundled with raw material supply. Penetrate white-space demand in Ho Chi Minh City contract manufacturing clusters through enzymatic preservation platforms that navigate ASEAN directive harmonization gaps. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biotech-platform suppliers with long-term supply agreements to Korean conglomerates, as clean-label mandates create sticky procurement relationships. Acquisition targets should demonstrate regulatory affairs capabilities in Shanghai or Tokyo alongside captive fermentation assets. The signal to watch is NMPA-MHLW regulatory alignment progress, as convergence would eliminate dual registration cost burdens and revalue compliant supplier portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Fermentation | Captive production at Yangtze River Delta complexes controls cost positions against Brazilian citric acid volatility. |
| ISO 16128 Certification Acceleration | Third-party auditor capacity constraints create first-mover advantage in clean-label procurement pools. |
| Microbiome Research Partnership | Collaboration with dermatology platforms develops skin-flora-compatible preservation systems for premium skincare. |
| Turnkey Technical Service Expansion | Vietnam domestic brands absorb bundled formulation consulting alongside raw material supply. |
| ASEAN Regulatory Harmonization Positioning | Streamlined ingredient approvals reduce compliance friction for multi-market formulation strategies. |
Methodological Framework
Desk research of NMPA cosmetic registration filings, ASEAN harmonized directive provisions, and Korean MFDS safety standards preceded structured interviews with biotech R&D directors, regulatory affairs leads at preservative suppliers, procurement managers at Korean skincare conglomerates, and contract manufacturing executives in Vietnam and Indonesia. Secondary validation drew from customs trade data, SEC 10-K disclosures of listed chemical conglomerates, and fermentation capacity reports from Yangtze River Delta industrial databases. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and country dimensions.
Variance decomposition across the projection horizon isolates drivers by segmentation dimension: product type shifts between phenoxyethanol, organic acids, and enzymatic alternatives; application intensity variations across skincare, haircare, and makeup matrices; and regulatory cluster differences between NMPA, MHLW, and ASEAN directive frameworks. CAGRs were derived from elasticity-adjusted demand modeling incorporating K-beauty procurement mandate propagation rates and biotechnology cost-parity achievement timelines. Industry-specific inputs included fermentation capacity utilization rates and ISO 16128 certification pipeline backlogs.
The analysis sits within stated boundaries; outcomes outside sustained clean-label procurement mandate intensity or regulatory harmonization progress would require recalibration. Forecasts reflect assumptions regarding biotechnology scale-up economics and NMPA cosmetic supervision regulation implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Minoxidil Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market