
 Guanabana Market | 2026-2036
Guanabana Market Size, Share, and Industry Trends Forecast 2026-2036
Guanabana Market Analysis
Fragmentation among specialty beverage startups is repositioning procurement patterns across the guanabana value chain. Goya Foods, Inc. leverages its established Caribbean and Latin American sourcing networks to secure consistent tropical fruit supply. Fructo AG anchors European distribution through its deep cold-chain infrastructure for frozen fruit products. Jumex Group differentiates via integrated juice processing capabilities spanning Mexico into US Hispanic retail channels.
Guanabana (Annona muricata) is a tropical evergreen fruit weighing 2.7–6.8 kg with white fibrous pulp containing 81% moisture, 17% carbohydrates, and notable acetogenin compounds. The fruit undergoes flash-freezing at minus 18 degrees Celsius or spray-drying into powder to preserve bioactive properties for industrial formulation. Powder applications in dietary supplements command premium positioning due to concentrated acetogenin content and extended shelf stability. Fresh fruit sales through supermarkets retain volume leadership yet face perishability constraints that frozen fruit formats circumvent for food manufacturers. Juice segments compete in beverage applications where clean-label positioning and tropical flavor profiles drive reformulation cycles.
The FDA governs guanabana juice and supplement labeling under Food Safety Modernization Act traceability rules, while EFSA evaluates novel food petitions for acetogenin-enriched extracts seeking European market entry. Mexico's COFEPRIS and Brazil's ANVISA enforce pesticide residue limits on imported tropical fruit pulp that directly shape supplier qualification criteria for North and South American buyers. Stakeholders must monitor evolving novel food approvals and cold-chain infrastructure investments as determinants of which processing formats capture disproportionate value expansion.
Market Dynamics
Flash-freezing at minus 18 degrees Celsius and spray-drying technologies are compressing perishability windows and opening industrial formulation channels for guanabana processors across tropical supply zones.
Growth Catalysts
- Functional beverage formulation:Beverage manufacturers in Mexico and Colombia are scaling frozen pulp procurement for clean-label tropical drink lines targeting health-conscious consumers.
- EFSA novel food pathways:The EU's Novel Food Regulation is creating structured entry mechanisms for acetogenin-enriched extracts seeking European commerce authorization.
- Southeast Asian processing concentration:Vietnam and Thailand are expanding tropical fruit ingredient export infrastructure, capturing economies of scale in pulp processing and cold-chain logistics.
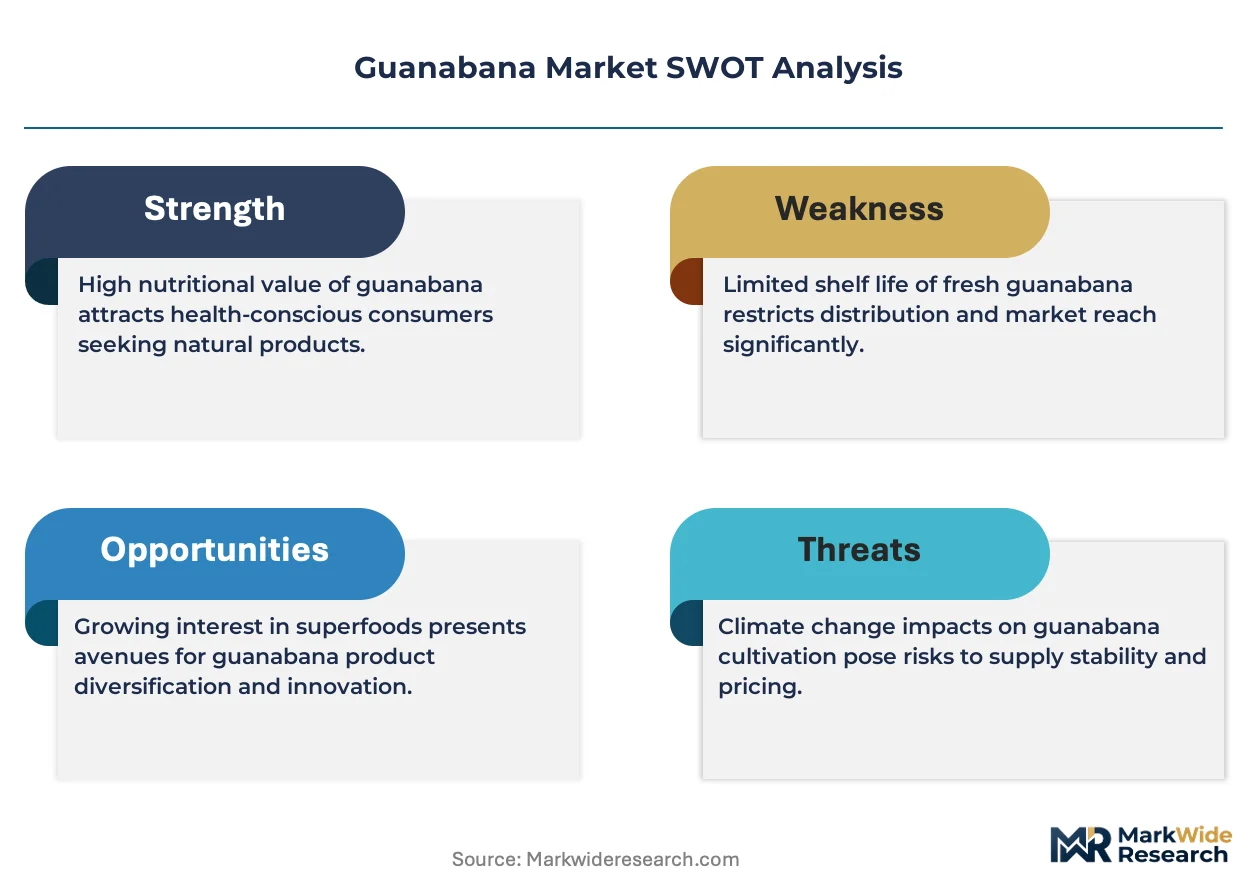
Market Restraints
- Input cost volatility:Fresh guanabana perishability creates price instability for processors dependent on just-in-time harvest procurement from fragmented smallholder networks.
- Regulatory friction:Mexico's COFEPRIS and Brazil's ANVISA enforce divergent pesticide residue limits on imported pulp, complicating cross-border supplier qualification for North and South American buyers.
- Substitution pressure:Moringa and acerola powders compete for shelf space in functional beverage and supplement applications with comparable tropical positioning and longer-established supply chains.
Strategic Opportunities
- Dietary supplement white space:Acetogenin-concentrated powders command premium positioning in North American nutraceutical channels where bioactive standardization remains underdeveloped.
- EU regulatory tailwind:Successful EFSA novel food petitions for acetogenin extracts would unlock formulated ingredient sales into European food and supplement manufacturers.
- Direct-to-manufacturer channels:Frozen pulp suppliers are bypassing traditional import distributors to contract directly with beverage co-packers, capturing margin compression from disintermediation.
Industry Challenges
- Cold-chain capex intensity:Minus 18 degrees Celsius flash-freezing infrastructure requires substantial capital deployment that constrains processor expansion in origin markets.
- Acetogenin standardization gaps:Absence of unified ISO or pharmacopeial methods for acetogenin quantification complicates batch consistency for supplement-grade powder production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guanabana Market |
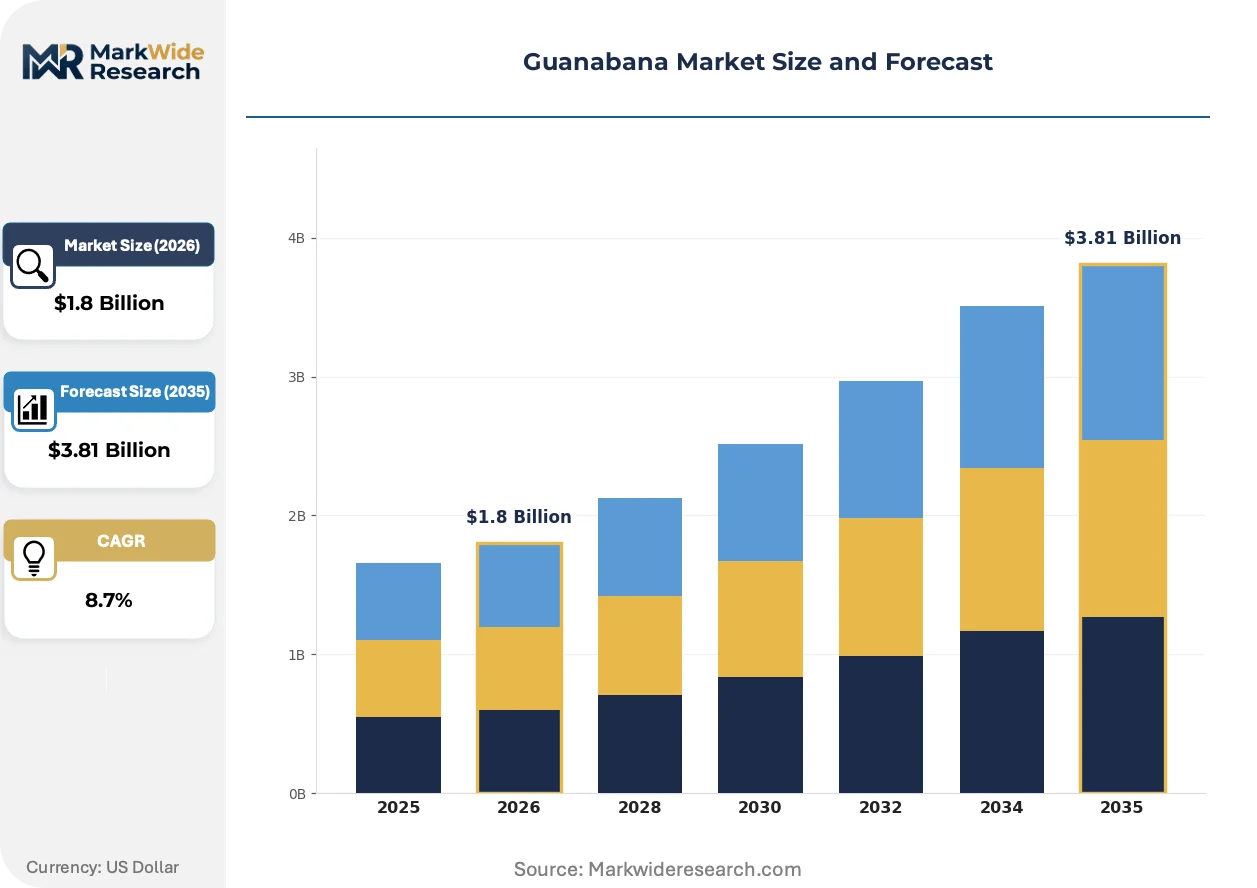
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fruit, Frozen Fruit, Juice, Powder End User: Retail Consumers, Food Manufacturers, Beverage Companies, Health Stores Distribution Channel: Online Retail, Supermarkets, Farmers' Markets, Wholesalers Application: Food Products, Dietary Supplements, Cosmetics, Beverages |
| Companies Covered | Now Health Group Inc., Fructo AG, Goya Foods, Inc., Amelia Organic Products, Amanaci Rohstoffe UG & Co.KG, Jumex Group, Austrofood Cia Ltda., Guanabana de Canarias, Sunshine Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guanabana Market Emerging Trajectories
Spray-drying and advanced cryogenic preservation are displacing traditional sun-drying methods, while regulatory science around bioactive compounds is reshaping how processors validate health-positioned ingredients for cross-border trade.
Low-temperature spray-drying technology preserves heat-sensitive acetogenin compounds in powder formats for supplement and functional food applications. Dietary supplement manufacturers in North America are adopting these inputs at accelerating rates for capsule and tablet formulations. This preservation capability is expanding into beverage premix channels where water-dispersible tropical fruit powders replace liquid concentrates in clean-label formulations.
The EU's Novel Food Regulation is tightening safety documentation requirements for acetogenin-enriched extracts entering European food and supplement markets. EFSA evaluations now demand comprehensive toxicological dossiers that extend approval timelines and elevate R&D spending for petitioning firms. Powder and extract categories face the steepest compliance burden, prompting some suppliers to prioritize conventional frozen pulp sales into established food applications while awaiting novel food determinations.
Beverage co-packers are consolidating procurement relationships directly with Vietnamese and Thai frozen pulp processors, compressing traditional importer margins. This channel disintermediation is most visible in North American Hispanic retail and foodservice segments where volume buyers seek supply security and price transparency. Direct contracting is displacing spot-market purchasing for frozen guanabana pulp as formulation consistency becomes a competitive differentiator in functional drink launches.
Guanabana Market Segmentation
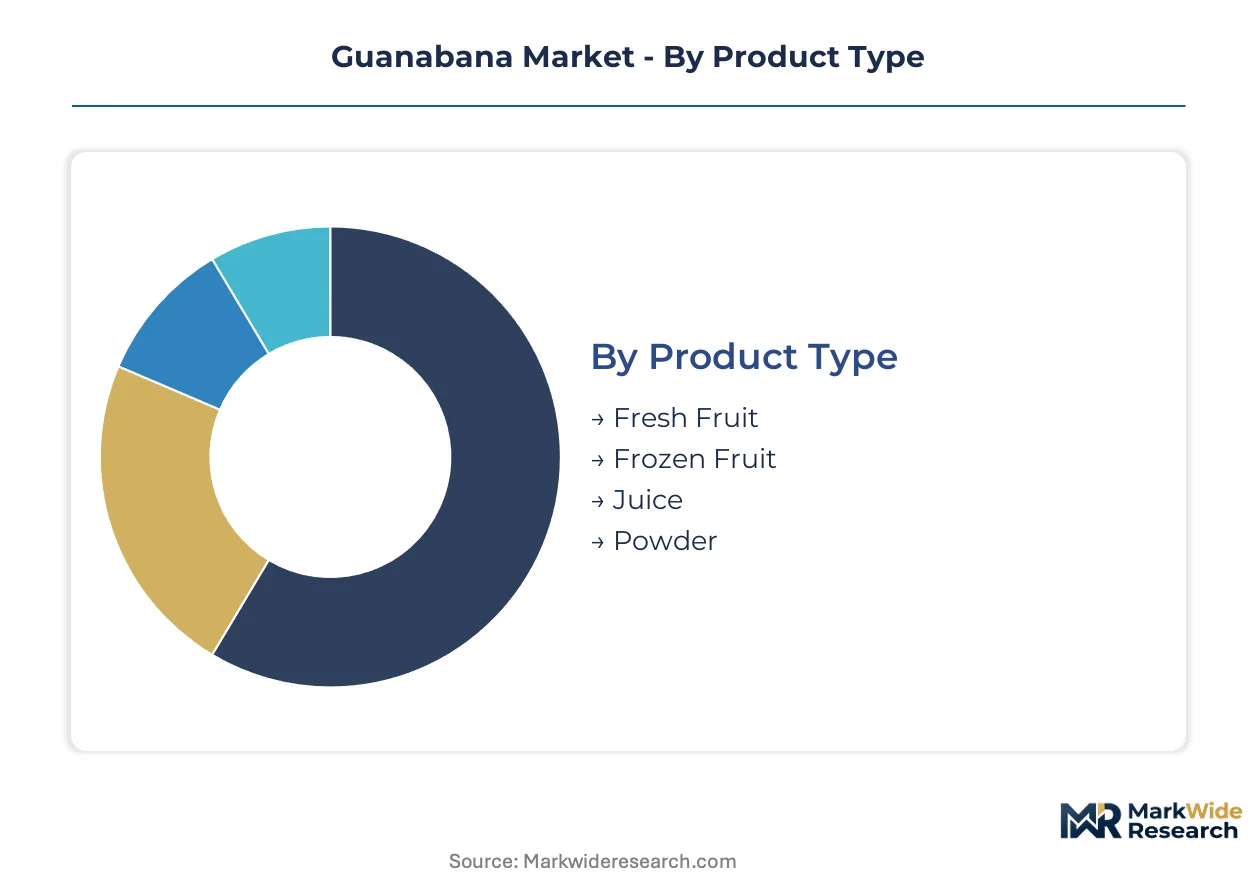
Guanabana's perishability and bioactive compound sensitivity create sharp performance divides across processing formats. Format selection determines shelf stability, acetogenin retention, and addressable customer base for suppliers navigating tropical supply chains.
Product Type:
Flash-freezing and spray-drying technologies are displacing traditional fresh distribution as processors seek to compress spoilage windows and access industrial buyers.
- Frozen Fruit:Flash-frozen pulp at minus 18 degrees Celsius preserves acetogenin integrity for 18-24 months. Beverage co-packers in Mexico and Colombia are consolidating procurement directly with Vietnamese and Thai processors to secure formulation consistency for functional drink lines.
- Powder:Low-temperature spray-drying concentrates bioactive compounds into water-dispersible formats. Dietary supplement manufacturers in North America adopt these inputs for capsule and tablet formulations where standardization commands premium positioning.
- Fresh Fruit:Supermarket retail retains volume leadership despite 5-7 day shelf life constraints that limit geographic reach to regional tropical markets.
- Juice:Single-strength and concentrate formats compete in clean-label beverage reformulations where tropical flavor profiles drive Hispanic retail channel placement.
Frozen fruit sits at the top of the volume ranking, with powder climbing the fastest as nutraceutical applications expand.
End User:
Customer sophistication around acetogenin content and cold-chain reliability stratifies procurement requirements across the value chain.
- Beverage Companies:Scale frozen pulp procurement for clean-label tropical drink launches targeting health-conscious demographics. These buyers prioritize batch consistency and direct processor relationships over spot-market flexibility.
- Food Manufacturers:Integrate frozen pulp into ice creams, yogurts, and bakery fillings where tropical positioning supports premium tier placement.
- Health Stores:Stock powder and supplement formats emphasizing acetogenin concentration and organic certification for wellness-focused consumers.
- Retail Consumers:Purchase fresh fruit and juice through supermarkets and farmers' markets with limited price elasticity for imported tropical products.
Beverage companies anchor procurement volume, while health stores are gaining share fastest as supplement applications proliferate.
Distribution Channel:
Channel selection determines margin capture and customer access for processors competing across fragmented tropical fruit supply networks.
- Wholesalers:Traditional importers face margin compression as direct-to-manufacturer contracting expands. Established cold-chain infrastructure remains essential for frozen pulp distribution into food manufacturing.
- Online Retail:Powder and supplement formats leverage e-commerce for direct consumer access, bypassing retail slotting fees and geographic constraints.
- Supermarkets:Fresh fruit and juice placement depends on regional tropical proximity and perishability management capabilities.
- Farmers' Markets:Local-origin fresh sales concentrate in Caribbean and Latin American production zones with minimal processing overhead.
Wholesalers retain the largest throughput position, with online retail expanding most quickly as supplement formats scale.
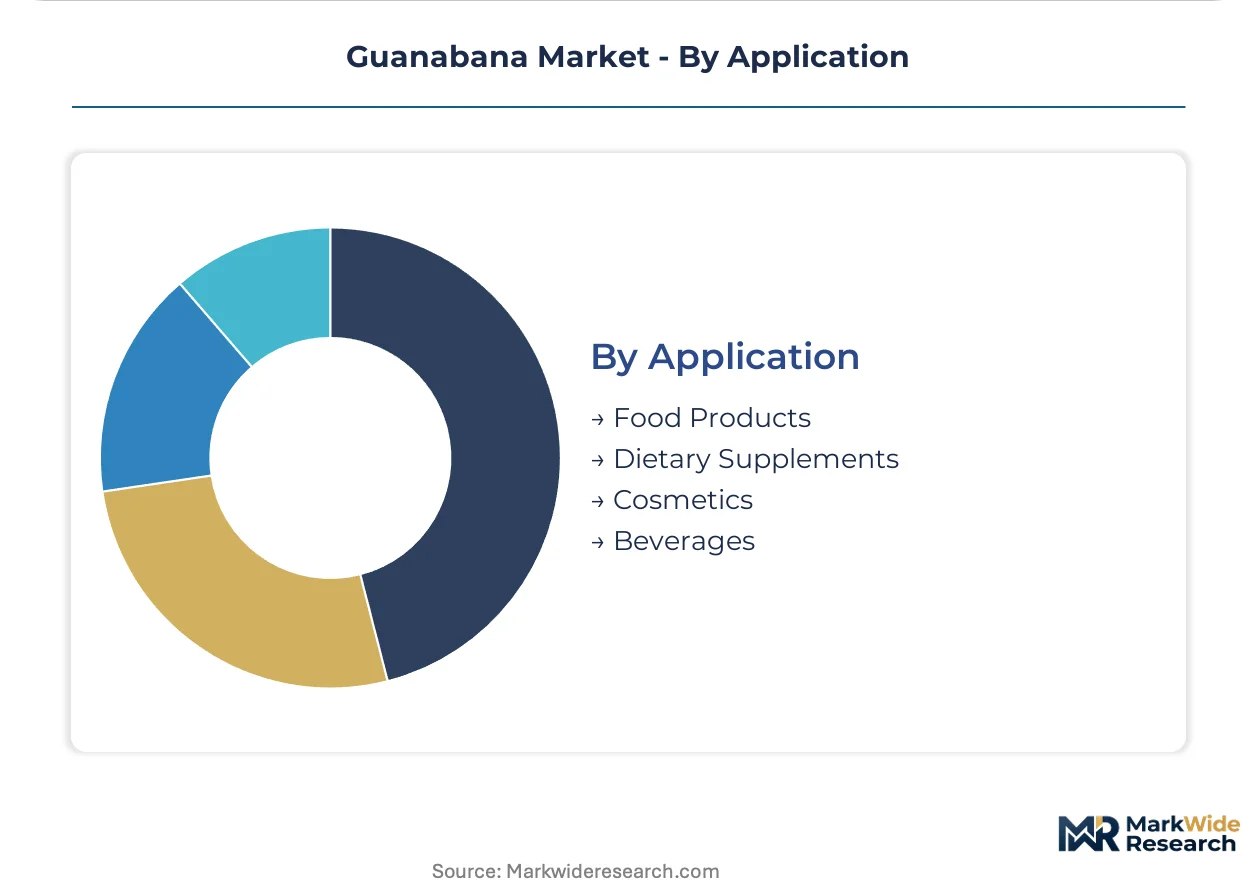
Application:
End-use formulation requirements dictate processing technology investment and regulatory compliance burden for suppliers.
- Dietary Supplements:Acetogenin-concentrated powders face EFSA novel food evaluation requirements for European market entry. North American nutraceutical channels adopt these inputs with less regulatory friction but demand batch standardization.
- Beverages:Functional drink lines in Mexico and Colombia drive frozen pulp procurement at scale. Clean-label positioning and tropical flavor differentiation support reformulation cycles away from artificial alternatives.
- Food Products:Frozen pulp integrates into ice creams, sorbets, and bakery applications where texture and flavor consistency matter more than bioactive marketing.
- Cosmetics:Extract applications in skincare remain nascent with limited commercial scale compared to ingestible categories.
Beverages dominate current volume, with dietary supplements tracking the steepest expansion trajectory as bioactive standardization improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's beverage co-packers scale frozen pulp procurement faster than Colombian processors, while Vietnamese cold-chain infrastructure outpaces Thai export capacity for tropical fruit ingredients.
Mexico
Beverage manufacturers in Jalisco and Nuevo León consolidate direct procurement contracts with Vietnamese frozen pulp processors for clean-label functional drink lines. COFEPRIS enforces pesticide residue limits on imported tropical fruit pulp that reshape supplier qualification criteria for North American buyers. Mexico City Metro anchors distribution networks spanning Hispanic retail channels across the southwestern United States.
Colombia
Functional beverage startups in Bogotá and Medellín drive frozen guanabana pulp demand for reformulated tropical drink portfolios targeting health-conscious demographics. The national agricultural regulator enforces phytosanitary certification requirements on imported fruit ingredients that filter processor eligibility. Caribbean coastal processing zones concentrate flash-freezing operations serving Andean urban markets.
Vietnam
Mekong Delta fruit processors expand minus 18 degrees Celsius cold-chain infrastructure to capture frozen pulp export contracts from North American beverage co-packers. The Ministry of Agriculture and Rural Development implements tropical fruit export quality standards that elevate batch consistency requirements. Ho Chi Minh City logistics hubs coordinate direct-to-manufacturer shipping lanes bypassing traditional importer networks.
Thailand
Eastern Seaboard processing clusters scale spray-drying capacity for acetogenin-concentrated powders targeting North American nutraceutical channels. The national food and drug administration evaluates novel food safety dossiers for bioactive extract exports seeking regulatory pre-clearance. Bangkok-based ingredient traders coordinate Southeast Asian supply aggregation for consolidated export shipments.
United States
Dietary supplement manufacturers in California and Florida adopt low-temperature spray-dried guanabana powders for capsule formulations where acetogenin standardization commands premium positioning. FDA traceability rules under the Food Safety Modernization Act govern juice and supplement labeling requirements for tropical fruit-derived ingredients. Miami cold-chain distribution centers handle frozen pulp transshipments from Latin American and Southeast Asian origin markets.
Guanabana Market Vendor Landscape
Latin American producers anchor one tier; European specialists hold distribution infrastructure advantages for frozen fruit formats. The market structure stratifies across integrated juice processors, tropical fruit sourcing networks, and regional cold-chain distributors. Three archetypes dominate: Caribbean-origin suppliers with established smallholder networks, Southeast Asian processors with scaled flash-freezing capacity, and European distributors with deep frozen logistics expertise. Capacity expansion and direct-to-manufacturer contracting represent the primary competitive vectors reshaping procurement relationships.
Within the integrated processing tier, Goya Foods, Inc. and Jumex Group exemplify Latin American-origin players with beverage manufacturing footprints spanning origin markets into US Hispanic retail channels. Fructo AG occupies a position representing European distribution specialists with established cold-chain infrastructure for frozen tropical fruit products. These three companies illustrate how geographic origin and downstream integration depth stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Now Health Group Inc. |
| Fructo AG |
| Goya Foods, Inc. |
| Amelia Organic Products |
| Amanaci Rohstoffe UG & Co.KG |
| Jumex Group |
| Austrofood Cia Ltda. |
| Guanabana de Canarias |
| Sunshine Naturals |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EFSA novel food petitioners and conventional frozen pulp suppliers manifests in pricing power asymmetries and supply chain specialization. Premium acetogenin-concentrated powders command formulation premiums while commodity frozen fruit competes on logistics efficiency and harvest timing.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for frozen guanabana pulp as Mekong Delta processors scale minus 18 degrees Celsius infrastructure. Contract-based long-term offtake dominates procurement between beverage co-packers and Southeast Asian suppliers, with price differentiation driven by acetogenin batch consistency and organic certification tier. Cost compression in conventional frozen pulp is intensifying because direct-to-manufacturer contracting displaces traditional importer margins. Smallholder-dependent fresh fruit channels exhibit highest price sensitivity, while North American nutraceutical buyers show least elasticity for standardized powder inputs.
Supply Chain Analysis
Refrigerated container freight costs from Ho Chi Minh City and Bangkok to Miami and Los Angeles anchor total landed cost structures for North American buyers. Supply concentrates in Vietnam, Thailand, and Mexico, with raw material dependencies on smallholder guanabana harvests, acetogenin assay reagents, and food-grade packaging materials. Single-source vulnerability persists where beverage co-packers lock exclusive processor contracts without qualified secondary suppliers. Distribution runs through direct manufacturer contracting that bypasses traditional import distributors, compressing channel margins while securing batch consistency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory milestones, with successful EFSA novel food petitions for acetogenin extracts serving as the primary demand catalyst unlocking European formulation channels.
For Market Incumbents: Deepen backward integration into Mekong Delta flash-freezing operations to secure supply continuity against COFEPRIS and ANVISA pesticide residue enforcement. Anchor defensive positioning through captive cold-chain infrastructure investments in Vietnam and Thailand, while accelerating ISO method development for acetogenin quantification to outpace standardization gaps threatening batch consistency premiums.
For New Entrants and Emerging Players: Capture dietary supplement white space in North American nutraceutical channels where bioactive standardization remains underdeveloped and incumbent powder suppliers face EFSA approval delays. Target direct-to-manufacturer frozen pulp contracting with Mexican beverage co-packers in Jalisco and Nuevo León, leveraging price transparency and supply security as entry wedges against established importer relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where cold-chain capex intensity and regulatory compliance burdens fragment processor viability, favoring scaled Southeast Asian operators with EFSA petition capabilities. Acquisition targets include Vietnamese flash-freezing specialists with direct North American beverage contracts and Thai spray-drying facilities serving nutraceutical channels. Watch EFSA novel food determination timelines as inflection indicators for powder category premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Petition Filing | Unlocks European acetogenin extract commerce for petitioning firms ahead of competitors. |
| Direct-to-Manufacturer Contracting | Disintermediates traditional importers, capturing margin compression for Vietnamese processors. |
| Acetogenin Standardization Investment | Establishes batch consistency credentials for North American nutraceutical premium positioning. |
| Cold-Chain Infrastructure Expansion | Secures 18-24 month shelf stability guarantees for beverage co-packer procurement commitments. |
| Organic Certification Acquisition | Meets COFEPRIS and ANVISA residue limits while commanding price premiums in health stores. |
Methodological Framework
Multiple input streams — primary interviews with frozen pulp processors, beverage formulation executives, and dietary supplement procurement leads; secondary validation through FDA FSMA traceability filings, EFSA novel food petition databases, and Vietnamese Ministry of Agriculture export quality standards — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned Southeast Asian cold-chain operators, Mexican beverage co-packers, and North American nutraceutical manufacturers to capture procurement pattern shifts and regulatory compliance burdens.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct analytical frameworks across product type, end user, distribution channel, and application dimensions. CAGRs were derived through segment-level growth rate reconciliation with macro drivers including EFSA approval timelines, COFEPRIS enforcement intensity, and Southeast Asian cold-chain capex cycles. Forecast inputs incorporated acetogenin standardization progress and direct contracting adoption rates as industry-specific variables.
EFSA novel food determination delays, COFEPRIS pesticide residue enforcement shifts, and Southeast Asian cold-chain infrastructure investment shortfalls are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight these assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Fresh Strawberry Market