
 Citrus Pulp Market | 2026-2036
Citrus Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Pulp Market Analysis
EU REACH compliance for feed-grade byproducts is redrawing competitive access across the citrus pulp value chain. Louis Dreyfus Company leverages its Brazilian crush infrastructure to dominate South American supply. Citrosuco anchors global availability through its integrated orange processing footprint. Cargill Incorporated competes on dairy nutrition formulation expertise, extending its reach into customized citrus pulp blends.
Citrus pulp comprises the dried residue of citrus fruits after juice extraction, typically containing 6-10% crude protein and 12-15% crude fiber on a dry matter basis, serving primarily as an energy-dense feed ingredient for ruminant livestock. Animal feed applications sustain the largest revenue pool given dairy herd expansion, while nutraceutical extraction from citrus bioflavonoids occupies the fastest-growing margin tier. Citrus peel processing for pectin recovery leads value-added product lines, and citrus powder formats are gaining traction in precision-blended premix channels.
The EU Green Deal and REACH frameworks govern residue classification and circular economy compliance for European processors, while the FDA and USDA set mycotoxin limits and labeling standards for U.S. feed ingredient imports. Brazil's ANVISA and Ministry of Agriculture regulate domestic citrus byproduct safety for both export and internal dairy sector supply. Stakeholders must monitor how evolving carbon accounting rules for agricultural byproducts reshape procurement premiums and border certification requirements.
Market Dynamics
Dairy nutrition science is redefining citrus pulp procurement as Brazilian processors integrate real-time fiber analytics into contract pricing, shifting value capture from commodity tonnage to metabolizable energy guarantees.
Growth Catalysts
- EU Green Deal residue mandates:Circular economy compliance requirements are forcing citrus processors to monetize former waste streams, creating certified feedstock supply for compound feed manufacturers.
- Brazilian dairy herd expansion:São Paulo state's industrial citrus belt is scaling dried citrus pellet output to match ruminant feed demand from expanding confinement operations.
- Pectin recovery technology:Advanced peel processing systems are extracting higher-value hydrocolloids while leaving optimized fiber residues for animal nutrition applications.
Market Restraints
- Input cost volatility:Fresh fruit procurement contracts expose processors to weather-driven orange supply shocks that compress drying operation margins.
- REACH registration burdens:ECHA compliance costs for feed-grade byproduct classification create entry barriers for smaller Mediterranean citrus processors.
- Soy hull substitution:Oilseed processing residues compete directly on rumen-degradable protein metrics in price-sensitive dairy ration formulations.
Strategic Opportunities
- Indian dairy cooperatives:Gujarat and Maharashtra milk unions represent underpenetrated demand for imported citrus fiber as indigenous orange processing remains minimal.
- Precision fermentation feed:Convergence of citrus bioflavonoid extraction with microbial protein synthesis opens novel ingredient co-product architectures.
- EU carbon farming incentives:CAP eco-scheme payments for agricultural residue valorization are redirecting processor investment toward anaerobic digestion-integrated facilities.
Industry Challenges
- Mycotoxin certification timelines:FDA and USDA testing protocols for aflatoxin and ochratoxin create 14-21 day border delays that disrupt just-in-time dairy feed supply chains.
- Legacy drying asset retrofit:Conventional rotary kiln installations require substantial capital redeployment to meet evolving moisture specification tolerances for pelleted export grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Pulp Market |
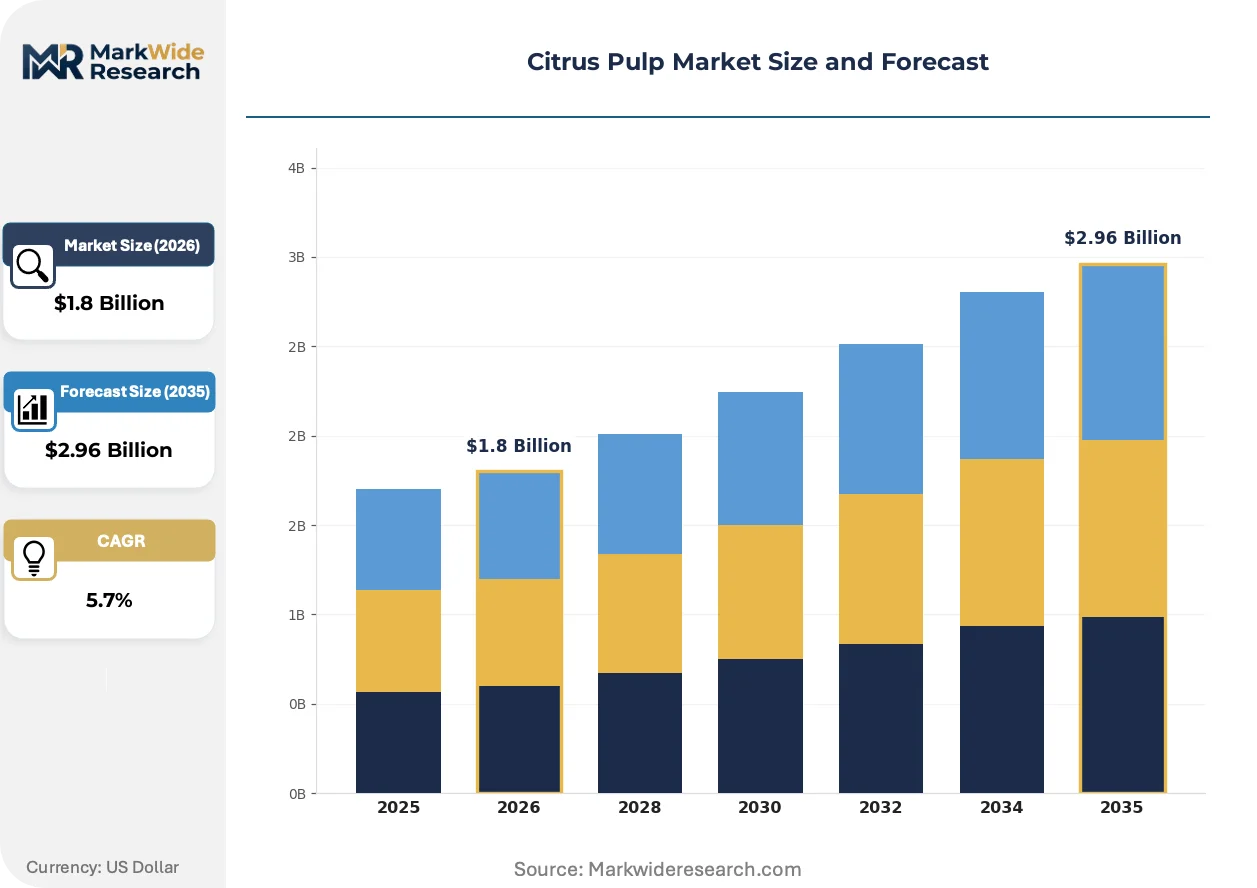
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Peel, Citrus Meal, Citrus Powder, Citrus Juice Application: Animal Feed, Food Ingredient, Nutraceutical, Biogas Production Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors End User: Dairy Farms, Poultry Farms, Food Processing, Beverage Industry |
| Companies Covered | Louis Dreyfus Company, Citrosuco, Cargill Incorporated, Archer Daniels Midland Company, Cefetra Group, Furst-McNess Company, LaBudde Group Inc., SAF Feed & Food, Sucocitrico Cutrale Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Pulp Market Emerging Trajectories
Near-infrared spectroscopy is penetrating citrus pulp quality assurance, enabling real-time metabolizable energy verification that is compressing traditional laboratory assay cycles and rewiring procurement contract structures.
Sensor-based sorting systems deploying hyperspectral imaging are displacing manual peel grading at Brazilian processing facilities. Large dairy cooperatives in Minas Gerais state are adopting these systems for inbound load verification. The technology is displacing subjective visual inspection protocols that previously dominated spot-market transactions.
EU CSRD sustainability reporting mandates now require Scope 3 agricultural residue traceability from citrus processors selling into European compound feed channels. This is forcing documentation system upgrades across Brazilian and Florida supply bases. Mid-sized processors lacking ERP integration face exclusion from premium-tier procurement pools.
Direct contracting between citrus processors and dairy nutritionists is bypassing traditional feed distributor intermediaries in North American markets. Large herd operations in California's Central Valley now source specified fiber fractions through bilateral agreements. This channel compression is most visible in herds exceeding five thousand head where formulation precision justifies dedicated supply relationships.
Citrus Pulp Market Segmentation
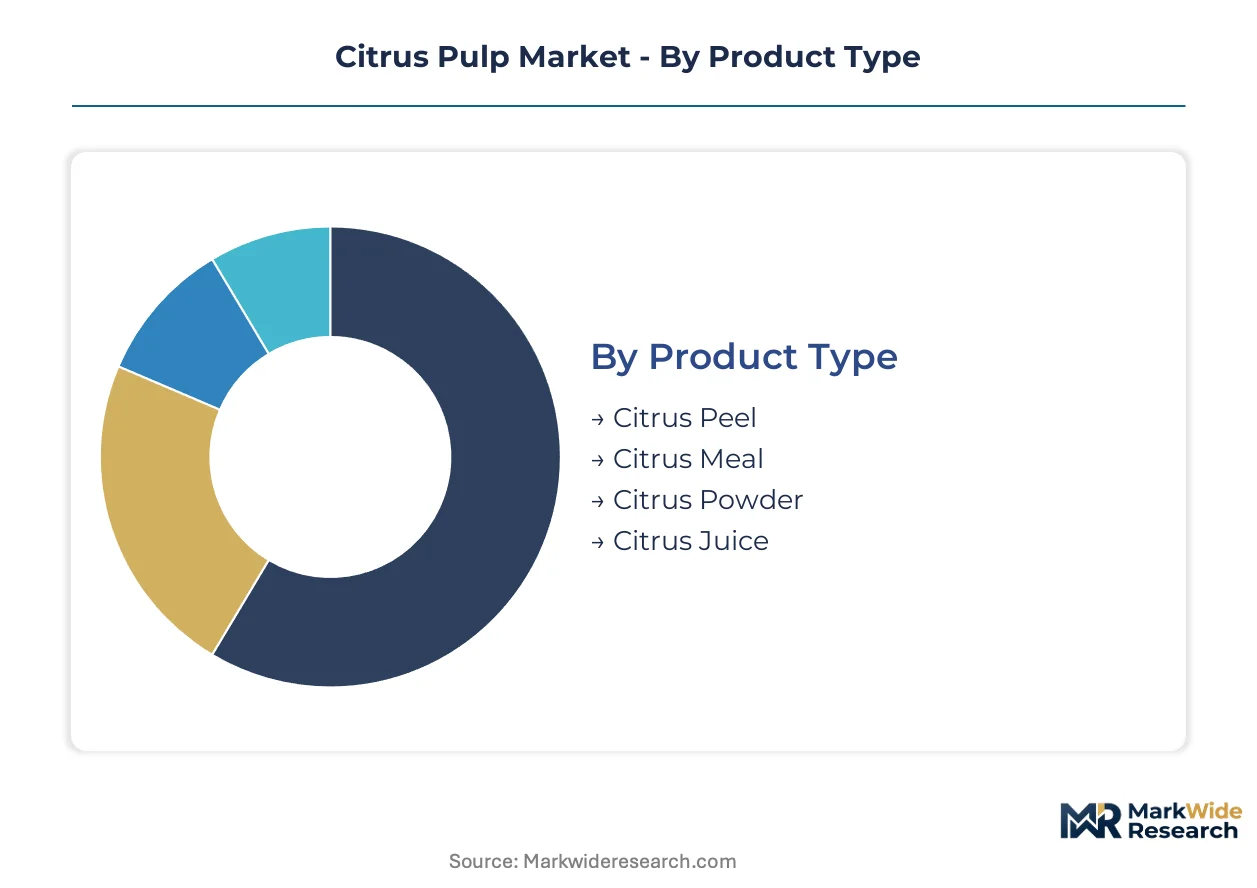
Citrus pulp procurement decisions pivot on fiber composition, moisture specification, and metabolizable energy guarantees. Dairy nutritionists prioritize segments delivering consistent rumen-degradable carbohydrate profiles, while nutraceutical extractors target bioflavonoid-rich peel fractions.
Product Type:
Soy hull and beet pulp substitution pressures vary sharply across citrus pulp formats, with dried pellet grades facing the most intense price competition from oilseed residues.
- Citrus Peel:Comprises the flavedo and albedo layers remaining after juice extraction, typically dried to 10-12% moisture for pelleted feed applications. São Paulo state's industrial citrus belt concentrates peel processing capacity to supply expanding dairy confinement operations in Minas Gerais with standardized fiber fractions.
- Citrus Meal:Finely ground residue containing 6-10% crude protein on a dry matter basis, serving as an energy-dense base ingredient in compound feed formulations. Brazilian processors are integrating real-time fiber analytics into meal contracts, shifting value capture from tonnage to metabolizable energy guarantees.
- Citrus Powder:Precision-milled format gaining traction in premix channels where uniform particle size enables automated blending. Food processing applications in precision nutrition bars drive quality premiums for specified mesh grades.
- Citrus Juice:Secondary extraction streams from pulp wash operations, concentrated for beverage industry acidulation or fermented for biogas feedstock. Supply fluctuates with primary juice commodity pricing cycles.
Citrus peel retains volume leadership; citrus powder holds the steepest expansion curve.
Application:
Margin architecture diverges sharply between commodity feed tonnage and value-added extraction tiers, with nutraceutical applications commanding pricing multiples despite smaller absolute volumes.
- Animal Feed:Dominant revenue pool sustaining ruminant nutrition programs across Brazilian and North American dairy sectors. São Paulo processors scale dried pellet output to match confinement operation demand, with fiber analytics now embedded in procurement contracts.
- Nutraceutical:Bioflavonoid extraction from citrus peel occupies the fastest-climbing margin tier, with hesperidin and naringin isolates targeting functional food and dietary supplement channels. EU REACH compliance requirements for feed-grade byproduct classification create entry barriers that concentrate higher-value extraction among integrated processors.
- Food Ingredient:Pectin recovery from peel streams supplies hydrocolloid demand in confectionery and dairy applications, leaving optimized fiber residues for animal nutrition.
- Biogas Production:Anaerobic digestion of wet pulp fractions generates renewable energy credits under EU carbon farming incentives, redirecting processor investment toward integrated facilities.
Animal feed commands absolute tonnage; nutraceutical extraction delivers the highest margin expansion.
Distribution Channel:
Channel compression is accelerating as large herd operations bypass intermediaries, while mid-scale buyers remain dependent on distributor networks for technical support and credit terms.
- Direct Sales:Bilateral contracting between citrus processors and dairy nutritionists now dominates North American markets for herds exceeding five thousand head, where formulation precision justifies dedicated supply relationships.
- Distributors:Traditional feed distributor networks retain relevance for mid-scale operations requiring technical support, credit terms, and blended ration services. Margin compression from channel bypassing is forcing distributors toward value-added formulation consulting.
- Wholesalers:Bulk aggregation of standardized pellet grades for regional compound feed manufacturers lacking direct processor relationships.
- Online Retail:Emerging channel for specialty citrus powder formats targeting small-scale nutraceutical blenders and artisan food processors, though feed-grade volumes remain negligible.
Direct sales channels are capturing share fastest from large operations; distributors defend position through technical service bundling.
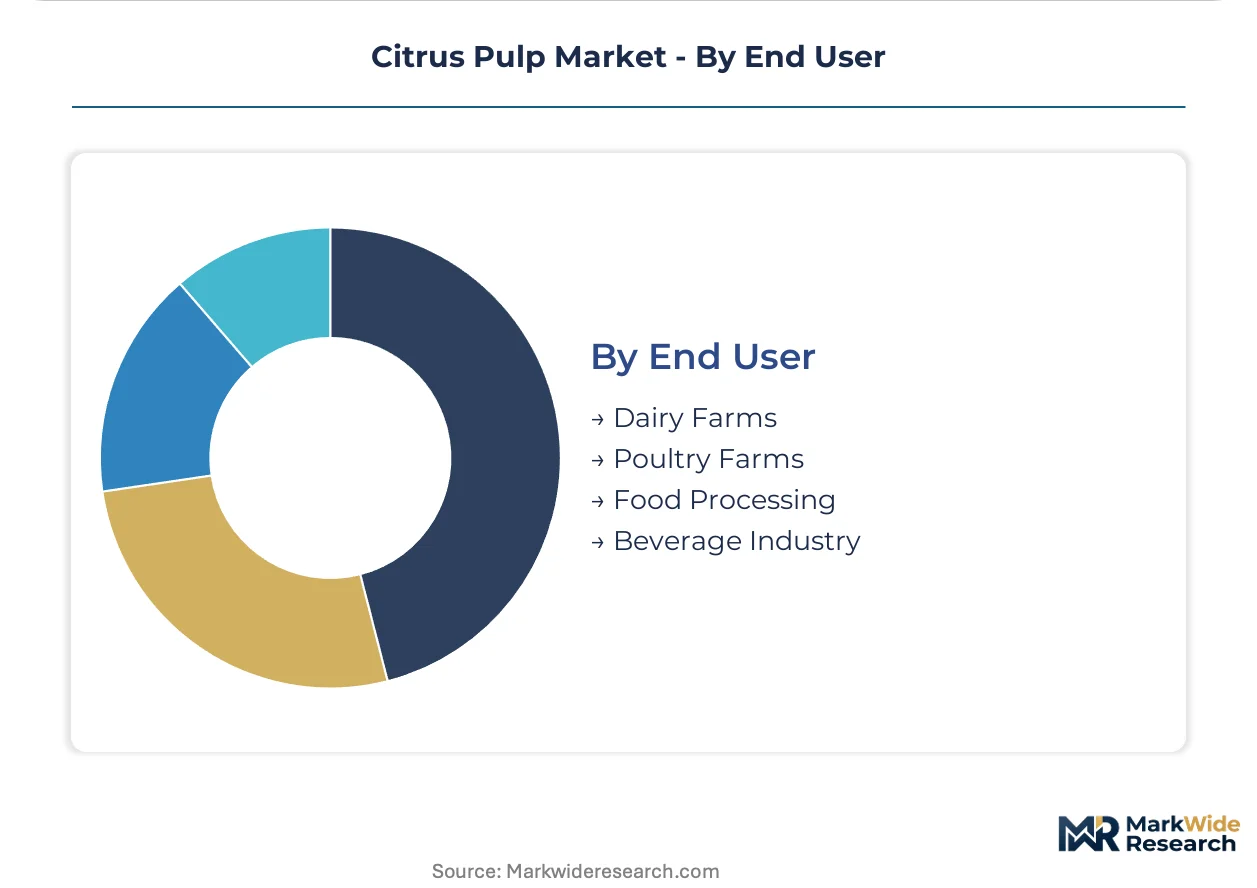
End User:
End-use concentration in dairy nutrition creates procurement leverage for large cooperatives, while poultry and beverage segments offer diversification against milk price volatility.
- Dairy Farms:Primary demand anchor, with Brazilian confinement operations driving pellet specification standardization. California's Central Valley herds now source specified fiber fractions through bilateral processor agreements.
- Food Processing:Pectin and fiber ingredient demand from confectionery, dairy, and bakery applications, with EU CSRD sustainability reporting mandates forcing Scope 3 agricultural residue traceability documentation.
- Poultry Farms:Secondary ruminant feed market facing substitution pressure from soybean meal and synthetic amino acid formulations.
- Beverage Industry:Acidulant and clouding agent applications for citrus juice fractions, competing with synthetic citric acid on cost but preferred for clean-label positioning.
Dairy farms dominate procurement volume; food processing applications are climbing fastest on clean-label ingredient demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminal underwrites Brazil's dominance in citrus pulp export logistics, handling pelletized feed ingredient volumes that supply dairy operations across three continents.
Brazil
São Paulo state's industrial citrus belt scales dried pellet output to match ruminant feed demand from expanding Minas Gerais confinement operations. ANVISA and the Ministry of Agriculture regulate domestic byproduct safety for both export certification and internal dairy sector supply. Citrosuco and Sucocitrico Cutrale anchor processing capacity in the Limeira-Araraquara corridor, integrating peel drying with juice extraction economics.
United States
California's Central Valley herds exceeding five thousand head now source specified fiber fractions through bilateral processor agreements, bypassing traditional distributor channels. FDA and USDA mycotoxin testing protocols for aflatoxin and ochratoxin create 14-21 day border delays that disrupt just-in-time supply chains. Florida's Indian River citrus district maintains wet pulp processing for regional biogas feedstock under state renewable energy incentives.
Netherlands
Rotterdam's bulk handling terminals serve as the EU's primary entry point for South American citrus pulp, with compound feed manufacturers in the Randstad region driving standardized pellet specification adoption. ECHA REACH registration requirements for feed-grade byproduct classification create entry barriers that concentrate import access among established traders. Cefetra Group leverages its Rotterdam storage infrastructure to arbitrage Atlantic supply flows.
India
Gujarat and Maharashtra dairy cooperatives represent underpenetrated demand for imported citrus fiber as indigenous orange processing remains minimal across the Nashik-Nagpur belt. FSSAI feed ingredient safety standards and DGFT import licensing govern inbound shipments, with BIS quality benchmarks emerging for premix channel adoption. Mid-scale operations in Anand and Kolhapur districts trial citrus meal inclusion in buffalo ration formulations.
Germany
Lower Saxony's dairy cooperatives drive metabolizable energy contracting innovation, embedding real-time fiber analytics into procurement agreements with Brazilian suppliers. EU CSRD sustainability reporting mandates require Scope 3 agricultural residue traceability, forcing documentation system upgrades across supply bases. The Port of Hamburg's bulk liquid terminals handle pectin concentrate imports for Baden-Württemberg hydrocolloid processors, leaving optimized fiber residues for animal nutrition channels.
Citrus Pulp Market Vendor Landscape
Listed leaders compete with private specialists across residue valorization capabilities, with publicly traded agribusiness conglomerates facing family-owned citrus processors in contract pricing for dairy nutrition programs. Market structure tilts toward consolidation at the origination tier, where integrated juice processors capture drying economics, while distribution fragments across regional feed compounders and nutrition consultants. Three archetypes dominate: integrated citrus processors with captive peel supply, diversified agribusiness traders with multi-origin sourcing networks, and specialized dairy nutrition formulators with formulation expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, as processors retrofit legacy drying assets and nutritionists forge direct contracting relationships with large herd operations.
Within the integrated processor tier, Citrosuco and Sucocitrico Cutrale exemplify Brazilian-origin private specialists that anchor South American supply availability through captive orange processing infrastructure. Louis Dreyfus Company occupies a position among diversified trading conglomerates, leveraging multi-commodity logistics networks to arbitrage citrus pulp across Atlantic and Pacific basin demand centers. Cargill Incorporated represents the nutrition formulation archetype, extending reach into customized citrus pulp blends through dairy sector technical service relationships.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| Citrosuco |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Cefetra Group |
| Furst-McNess Company |
| LaBudde Group Inc. |
| SAF Feed & Food |
| Sucocitrico Cutrale Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term metabolizable energy contracts lock in both supply access and price visibility for Brazilian citrus pulp processors serving EU dairy compounders, embedding fiber analytics guarantees that insulate buyers from spot-market volatility while securing drying capacity utilization for sellers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies citrus pulp procurement based on certification grade and volume scale. Premium tiers command REACH-registered, mycotoxin-certified pellet grades for EU compound feed manufacturers, while economy tiers serve price-sensitive Brazilian domestic dairies with basic dried peel fractions. Cost compression in standard-tier contracts is intensifying because soy hull substitution pressures rumen-degradable protein metrics. Small-scale Gujarat cooperatives exhibit highest price sensitivity, whereas German Lower Saxony dairy unions prioritize metabolizable energy consistency over per-ton savings.
Supply Chain Analysis
Santos container terminal chokepoint underwrites Brazil's export dominance, with pelletized volumes feeding Rotterdam bulk terminals for EU distribution and California Central Valley direct contracts. Supply concentrates in São Paulo state's Limeira-Araraquara corridor and Florida's Indian River district, drawing from fresh orange procurement, natural gas for rotary kiln drying, and pectin extraction co-product streams. Single-source vulnerability runs through ANVISA-certified Brazilian processors serving EU REACH compliance channels. Distribution runs through bilateral processor-nutritionist agreements for large herds and regional feed compounder networks for mid-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where EU REACH registration costs and mycotoxin certification timelines create structural barriers that protect incumbent integrated processors from commodity trader arbitrage.
For Market Incumbents: Shield margin capture by retrofitting legacy drying assets to meet EU CSRD Scope 3 traceability mandates before mid-sized competitors face exclusion from premium procurement pools. Deepen backward integration into captive orange processing infrastructure to offset fresh fruit procurement volatility. Prioritize real-time fiber analytics R&D partnerships with German dairy cooperatives to lock in metabolizable energy contracting innovation ahead of trader competition. For New Entrants and Emerging Players: ANVISA-ECHA dual certification fast-tracks unlock EU market access for Brazilian specialists with drying capacity in Minas Gerais proximity to dairy demand. Target India's Gujarat and Maharashtra milk unions with citrus meal trials in buffalo ration formulations, exploiting indigenous processing gaps across the Nashik-Nagpur belt. Lead with precision fermentation feed co-product architectures that converge bioflavonoid extraction with microbial protein synthesis. For Investors and Strategic Acquirers: Capital is best deployed toward integrated citrus processors with captive peel supply and existing REACH registrations, given the decade-long viability window for residue valorization under EU circular economy mandates. Monitor ECHA feed-grade byproduct classification enforcement as the inflection signal for consolidation acceleration among Mediterranean processors facing compliance cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | São Paulo processors scale pellet output to match Minas Gerais confinement operation demand growth. |
| Backward Integration | Citrosuco and Cutrale anchor supply through captive orange crushing infrastructure in the Limeira-Araraquara corridor. |
| Green Manufacturing Transition | EU carbon farming incentives redirect investment toward anaerobic digestion-integrated facilities for biogas credit generation. |
| Long-term Supply Agreement | California Central Valley herds exceeding five thousand head bypass distributors through bilateral fiber fraction contracts. |
| Joint Venture | Near-infrared spectroscopy partnerships with German cooperatives compress laboratory assay cycles and rewire procurement structures. |
Methodological Framework
A spread of perspectives from citrus processing plant managers, dairy nutrition formulation leads, EU compound feed procurement officers, and Brazilian Ministry of Agriculture regulators converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation from ANVISA safety filings, ECHA REACH registration databases, EU CSRD sustainability disclosures, and Brazilian customs trade records anchored supply-side characterization. Bottom-up capacity modeling and top-down demand triangulation from dairy herd expansion data cross-checked volume estimates.
Segmentation dimensions modeled include product format tier, application margin architecture, distribution channel structure, and end-user procurement scale across the projection horizon. CAGRs were derived from trend extrapolation of metabolizable energy contract adoption and pectin recovery technology diffusion, calibrated against historical orange processing residue yields and dairy ration formulation shifts. Forecast inputs incorporated EU Green Deal residue mandate enforcement timelines and Brazilian confinement operation growth trajectories.
Underlying assumptions cover sustained EU REACH compliance cost structures and Brazilian fresh fruit supply stability, with deviation risk concentrated in weather-driven orange crop shocks and FDA mycotoxin testing protocol delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market