
 Cloud Field Service Management (FSM) Market | 2026-2036
Cloud Field Service Management (FSM) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Field Service Management (FSM) Market Outlook
Modular platform bundling is decoupling core scheduling from advanced analytics, letting buyers assemble solutions from multiple vendors rather than accepting monolithic suites. Salesforce, Inc. leverages its CRM-native architecture to anchor customer engagement workflows inside field operations. Microsoft Corporation sustains hybrid-cloud traction by extending Azure infrastructure into edge devices used by technicians. ServiceNow competes on IT-service alignment, positioning its FSM modules for enterprises that already run digital workflows on its platform.
Cloud Field Service Management comprises software delivered over internet-hosted infrastructure that coordinates mobile workforces through real-time scheduling, asset tracking, and customer communication protocols, typically integrating GPS telemetry and API-based enterprise resource connections. Its primary commercial purpose is to minimize technician idle time and first-visit failure rates while capturing service revenue through automated billing triggers. Public cloud deployments lead in new bookings because they eliminate capital expenditure for mid-sized service organizations, though hybrid cloud configurations capture the strongest margin pools where manufacturers require air-gapped asset data alongside remote accessibility. Artificial Intelligence segments within scheduling and dispatching are expanding fastest as predictive arrival-time algorithms reduce penalty costs from missed service-level agreements.
FCC guidelines on wireless spectrum allocation shape how IoT-enabled field devices transmit telemetry in the United States, while GDPR and the EU AI Act impose consent and explainability requirements on automated workforce allocation across European deployments. OSHA inspection protocols for lone-worker safety are pushing utilities toward real-time location tracking as a compliance layer within dispatch software. Buyers must weigh whether single-vendor consolidation or best-of-breed assembly delivers superior total cost of ownership as platform boundaries continue to fragment.
Market Dynamics
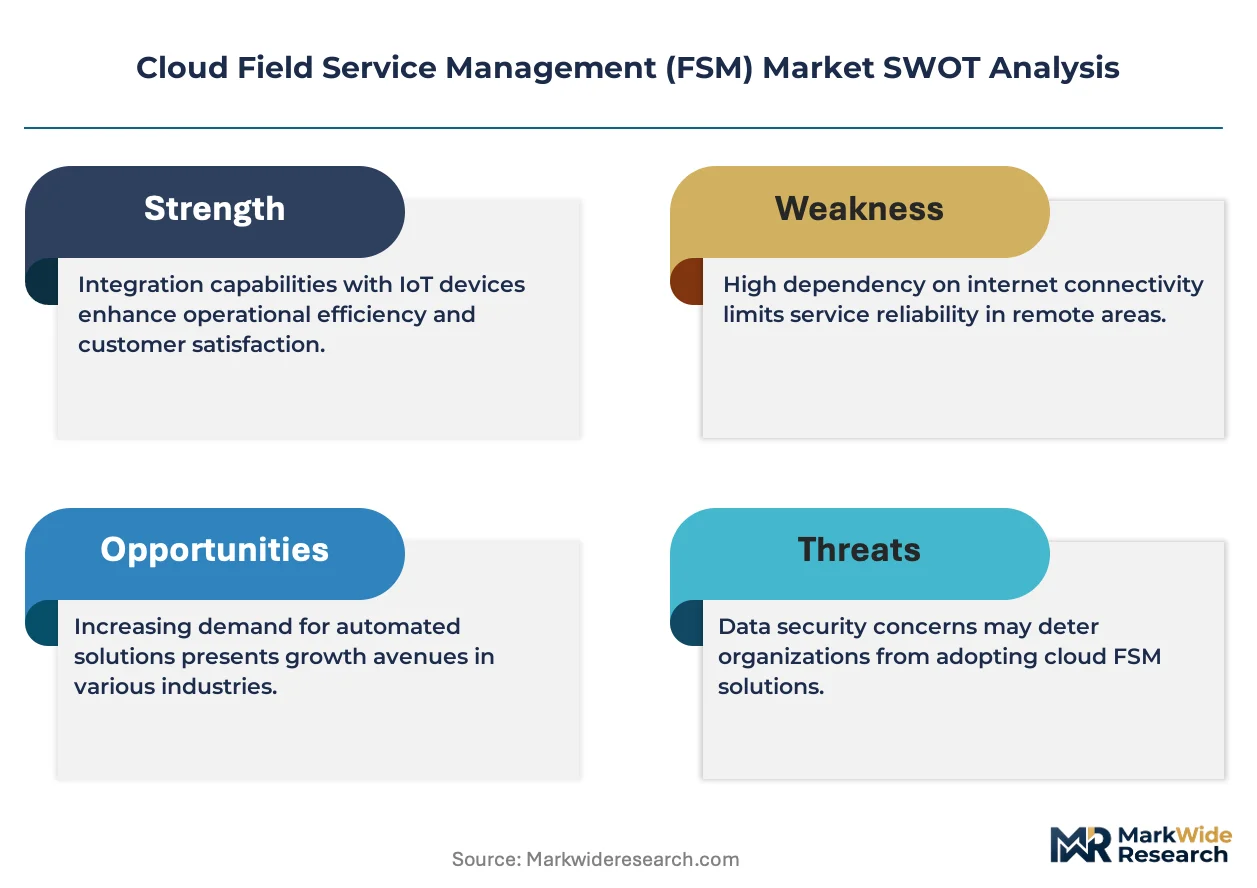
Modular platform architecture is fragmenting vendor lock-in across cloud FSM deployments, forcing incumbents to expose APIs and interoperability layers that erode suite-based pricing power.
Growth Catalysts
- EU AI Act compliance mandates:European utilities must deploy explainable workforce allocation algorithms, accelerating replacement of opaque legacy dispatch systems with auditable cloud platforms.
- Industrial OEM consolidation in Germany:Manufacturers are bundling field service modules into enterprise ERP contracts, creating anchor demand for integrated scheduling and asset management suites.
- Predictive arrival-time algorithms:Machine learning models that forecast technician ETAs are compressing penalty costs from missed service-level agreements, pulling mid-sized service organizations off on-premise infrastructure.
Market Restraints
- GDPR data residency requirements:Cross-border workforce telemetry storage faces consent and localization friction, raising compliance overhead for multi-national deployments.
- Air-gapped asset data requirements:Manufacturers in defense and critical infrastructure sectors demand hybrid configurations that isolate sensitive equipment records, limiting pure public cloud adoption.
- Legacy system integration complexity:Decades-old ERP and CMMS installations in established service organizations require costly middleware development, slowing migration timelines.
Strategic Opportunities
- Underpenetrated mid-sized HVAC and facilities management:Service organizations with 50-500 technicians lack capital for on-premise infrastructure, creating pull for subscription-based dispatch platforms.
- OSHA lone-worker safety mandates:Real-time location tracking is becoming a compliance layer within dispatch software, opening attach revenue for GPS telemetry modules.
- Edge-to-cloud convergence:Technicians' mobile devices are becoming local compute nodes that cache work orders and sync asynchronously, reducing dependency on continuous connectivity.
Industry Challenges
- API interoperability standards:Fragmented data exchange protocols between scheduling, CRM, and asset management systems force buyers into expensive custom integration projects.
- Field technician digital literacy gaps:Aging workforces resist mobile-first workflows, requiring change management investment that delays platform ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Field Service Management (FSM) Market |
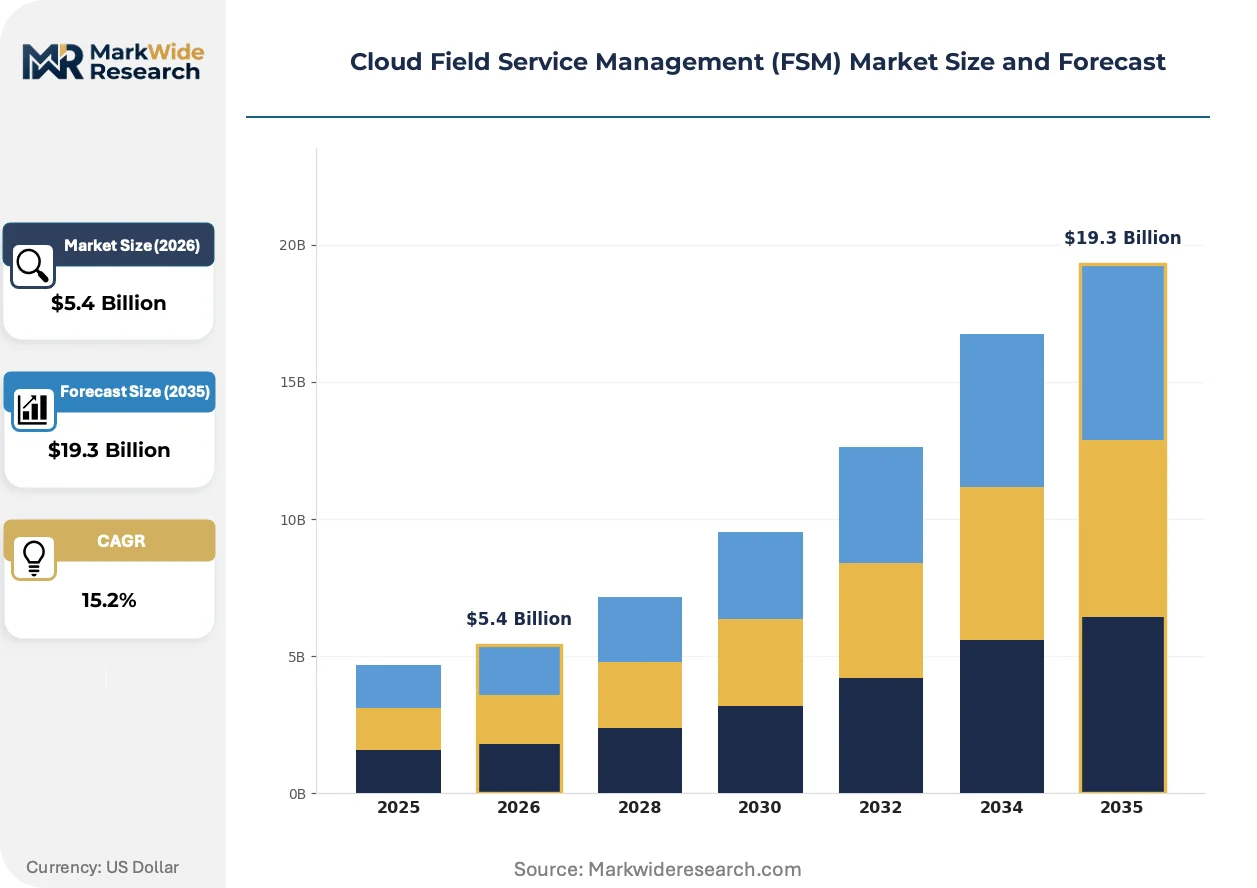
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $19.3 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Scheduling, Dispatching, Workforce Management, Customer Engagement End User: Telecommunications, Utilities, Manufacturing, Construction Technology: Mobile Applications, Internet of Things, Artificial Intelligence, Analytics |
| Companies Covered | Oracle Corporation, Salesforce, Inc., Microsoft Corporation, IFS AB, SAP SE, ServiceMax, Inc., ServiceNow, IBM Corporation, Infor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Field Service Management (FSM) Market Strategic Shifts
Artificial intelligence is compressing the latency between service event detection and technician dispatch, while regulatory pressure on algorithmic transparency is reshaping vendor development priorities.
Generative AI copilots embedded in technician mobile applications are automating work order summarization, parts recommendation, and customer communication drafting. Utilities with distributed generation assets are deploying these tools fastest, cutting average case resolution time without expanding headcount. The technology is automating knowledge transfer from retiring specialists to field crews, reducing dependency on tribal expertise.
The EU AI Act's risk classification framework is forcing European deployments to maintain human-in-the-loop overrides for automated dispatch decisions. Vendors must now document training data provenance and model drift monitoring, adding compliance engineering overhead. German industrial OEMs are demanding these audit trails as contractual prerequisites, extending the requirement to global rollout specifications.
Outcome-based service contracts are displacing time-and-materials billing in commercial HVAC and medical equipment maintenance. Buyers now pay for uptime guarantees rather than technician hours, shifting vendor incentives toward predictive intervention and remote resolution. This compression is most visible in the United States, where IRA energy efficiency rebates reward service providers that minimize truck rolls through remote diagnostics.
Cloud Field Service Management (FSM) Market Segmentation
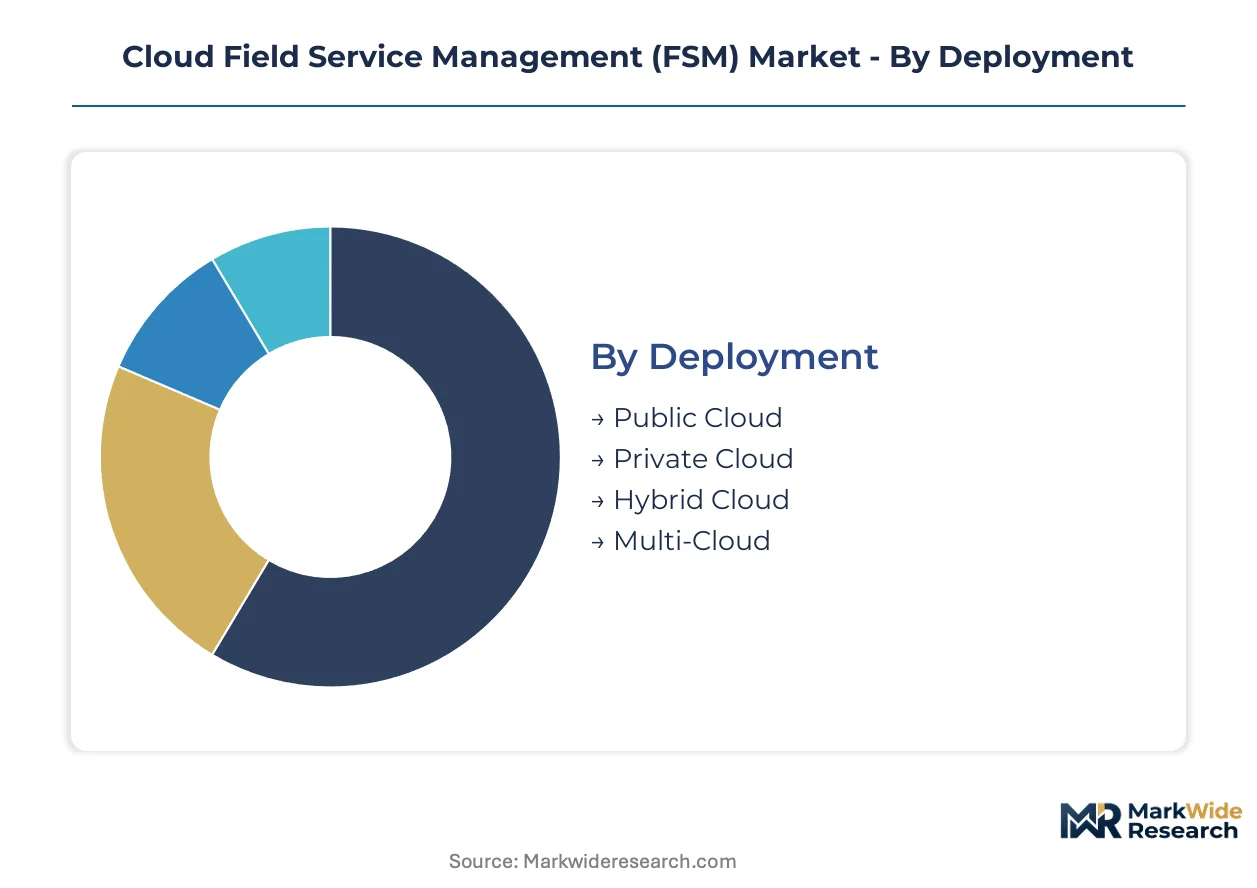
Cloud FSM purchasing decisions fragment across deployment architecture, functional modules, industry verticals, and enabling technologies. Buyers prioritize segments that compress technician idle time while satisfying compliance mandates for data residency and algorithmic transparency.
Deployment:
Replacement cycles for on-premise workforce management systems are accelerating as subscription economics displace capital-intensive infrastructure commitments.
- Public Cloud:Internet-hosted infrastructure eliminates server procurement and maintenance overhead for mid-sized service organizations. German industrial OEMs are consolidating vendor relationships around public cloud suites that bundle scheduling with ERP modules.
- Hybrid Cloud:Configurations isolate sensitive asset data in private infrastructure while exposing customer-facing workflows to public accessibility. Manufacturers in defense and critical infrastructure sectors mandate this architecture for air-gapped equipment records.
- Private Cloud:Dedicated single-tenant environments serve utilities with strict GDPR data residency requirements.
- Multi-Cloud:Distributing workloads across hyperscaler platforms reduces dependency on single-vendor outages.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest.
Service Type:
Functional specialization within FSM platforms reflects divergent margin profiles across automation layers.
- Scheduling:Real-time capacity optimization algorithms minimize penalty costs from missed service-level agreements. Predictive arrival-time models are pulling mid-sized HVAC contractors off legacy on-premise systems.
- Dispatching:Automated technician assignment based on proximity, skill certification, and parts availability compresses response windows. EU AI Act compliance mandates are forcing European utilities toward explainable dispatch logic.
- Workforce Management:Time-tracking, certification monitoring, and labor law compliance modules anchor back-office integration.
- Customer Engagement:Automated appointment notifications and real-time technician tracking portals reduce no-show rates.
Scheduling commands the largest revenue share, with Dispatching gaining share fastest as compliance complexity rises.
End User:
Industry-specific regulatory exposure shapes platform feature requirements and procurement timelines.
- Utilities:Distributed generation asset maintenance drives demand for IoT-enabled telemetry and predictive intervention workflows. OSHA lone-worker safety mandates are embedding real-time location tracking as a compliance layer.
- Telecommunications:FCC wireless spectrum allocation shapes how field devices transmit service-event data, favoring edge-to-cloud architectures with asynchronous sync capabilities.
- Manufacturing:Outcome-based service contracts displace time-and-materials billing, shifting vendor incentives toward uptime guarantees.
- Construction:Project-based workforce mobilization requires flexible subscription scaling rather than perpetual licensing.
Utilities lead absolute spending, with Telecommunications expanding most quickly as 5G infrastructure deployment accelerates.
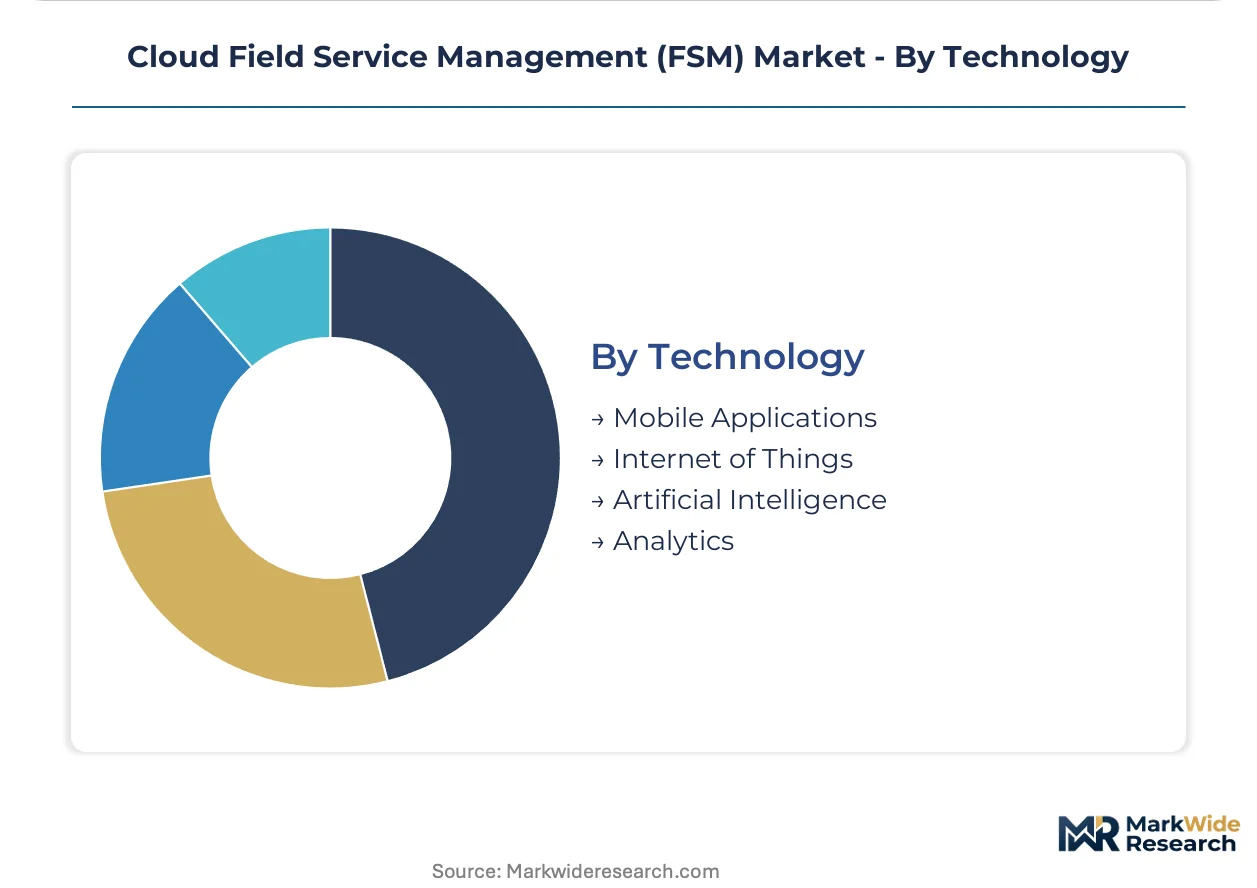
Technology:
Technology layers within FSM platforms are decoupling, enabling buyers to assemble solutions from specialized vendors.
- Artificial Intelligence:Machine learning models for predictive maintenance and workforce optimization are expanding fastest as explainability requirements reshape vendor development priorities. The EU AI Act's risk classification framework mandates human-in-the-loop overrides for automated decisions.
- Internet of Things:Sensor telemetry from field assets enables condition-based service triggers that reduce truck rolls. IRA energy efficiency rebates in the United States reward remote diagnostic capabilities.
- Mobile Applications:Technician-facing interfaces cache work orders locally and sync asynchronously, reducing dependency on continuous connectivity in remote service territories.
- Analytics:Performance dashboards and SLA compliance reporting satisfy procurement governance requirements.
Mobile Applications anchor installed base volume, with Artificial Intelligence showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud FSM platforms originated in Silicon Valley's enterprise software ecosystem during the mid-2000s, then migrated to European industrial centers as GDPR and sector-specific regulations reshaped deployment requirements. Geographic demand patterns now track regulatory intensity and industrial asset density rather than pure technology adoption curves.
United States
Utilities and telecommunications providers drive FSM platform procurement as grid modernization and 5G infrastructure deployment accelerate. OSHA lone-worker safety mandates embed real-time location tracking as a compliance layer within dispatch software. The Dallas-Fort Worth metroplex anchors utility sector adoption, where distributed generation asset maintenance demands predictive intervention workflows.
Germany
Industrial OEMs consolidate vendor relationships around integrated service suites that bundle scheduling with ERP modules. The EU AI Act's risk classification framework mandates human-in-the-loop overrides for automated dispatch decisions, forcing platform upgrades. Bavaria's manufacturing corridor leads deployment density, with Munich-based industrial groups demanding audit trails for algorithmic workforce allocation.
United Kingdom
Facilities management contractors migrate from on-premise workforce systems to subscription-based dispatch platforms as operational property portfolios expand. GDPR data residency requirements favor domestic cloud infrastructure providers over continental alternatives. London's commercial real estate cluster drives premium-tier adoption, where outcome-based service contracts displace time-and-materials billing.
Japan
Telecommunications infrastructure maintenance demands edge-to-cloud architectures with asynchronous sync capabilities for remote terrain coverage. METI industrial digitization incentives accelerate replacement of legacy dispatch systems. The Kanto region's dense manufacturing base concentrates deployment, with Tokyo-based service organizations prioritizing mobile-first technician workflows.
India
Mid-sized HVAC and facilities management organizations with 50-500 technicians pull toward subscription-based dispatch platforms as capital constraints limit on-premise infrastructure investment. The PLI scheme for electronics manufacturing creates downstream service demand. Bengaluru's technology services corridor anchors adoption, where IT-enabled service companies pilot AI-assisted workforce optimization.
Cloud Field Service Management (FSM) Market Competitive Environment
The competitive structure tilts toward platform-native incumbents with adjacent enterprise software ecosystems. Consolidation pressure intensifies as modular architecture fragments vendor lock-in, forcing suite providers to expose APIs that erode pricing power. Three archetypes dominate: CRM-native platforms anchoring customer engagement workflows, infrastructure providers extending cloud services into edge devices, and IT-service alignment specialists positioning modules for existing digital workflow customers. Dominant competitive moves include strategic partnerships with industrial OEMs and geographic expansion through localized compliance engineering.
Within the enterprise software tier, Salesforce, Inc. and Microsoft Corporation exemplify platform-native positioning, while ServiceNow occupies a specialist niche for IT-service alignment. These three anchors represent divergent architectural bets on how field service workflows integrate with broader enterprise systems. Salesforce leverages CRM-native infrastructure to embed customer engagement protocols directly into technician dispatch. Microsoft sustains hybrid-cloud traction by extending Azure infrastructure into mobile edge devices. ServiceNow competes on workflow continuity, targeting enterprises that already run digital operations on its platform.
| Leading Market Players |
|---|
| Oracle Corporation |
| Salesforce, Inc. |
| Microsoft Corporation |
| IFS AB |
| SAP SE |
| ServiceMax, Inc. |
| ServiceNow |
| IBM Corporation |
| Infor, Inc. |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration into hyperscaler cloud infrastructure anchors both supply positioning and pricing power for Cloud FSM vendors, as platform-native providers leverage captive compute and storage assets to compress delivery costs while sustaining subscription premiums. German industrial OEMs and US utilities consolidate procurement around these integrated suites, forcing modular competitors to absorb margin erosion from middleware development.
Pricing Analysis
Subscription-based SaaS tiers with per-technician seat licensing dominate Cloud FSM commercial structures, separating enterprise-grade predictive analytics modules from basic scheduling functionality. Price differentiation rests on GDPR compliance certification tier and API integration depth, with EU AI Act audit-ready platforms commanding premiums. Cost compression in mid-market segments is intensifying because Salesforce and Microsoft bundle FSM modules into existing enterprise contracts, eroding standalone vendor pricing power. Small HVAC contractors with 50-200 technicians exhibit highest price sensitivity, while defense-sector manufacturers with air-gapped requirements show lowest elasticity due to compliance-driven procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries producing edge-device chipsets for technician mobile hardware, while cloud infrastructure concentrates among US hyperscalers operating European data centers for GDPR residency compliance. Raw material dependencies span lithium-ion battery cells for field device power management, rare earth elements for GPS telemetry components, and specialized memory modules for local work-order caching. Supply chain risk centers on tariff exposure for Chinese-manufactured IoT sensors embedded in asset monitoring endpoints. Distribution runs through direct enterprise sales teams for large utilities and telecommunications providers, with channel partners serving mid-sized facilities management contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud FSM margins expand through predictive algorithm premiums that displace penalty costs from missed service-level agreements, compressing total cost of ownership for buyers while lifting vendor revenue per seat.
For Market Incumbents: Extend API interoperability layers to neutralize modular platform threats from best-of-breed assemblers, while deepening vertical integration into edge-device firmware to lock in technician workflow data. Salesforce's CRM-native anchoring and Microsoft's Azure edge extension demonstrate how platform gravity defends pricing power against point-solution erosion. For New Entrants and Emerging Players: The premium-to-economy pricing gap in explainable AI dispatch modules for EU AI Act compliance opens white-space entry for audit-trail-native platforms targeting Bavarian industrial OEMs. Mid-sized HVAC contractors in India and the southern United States represent the most penetrable segment, with subscription scalability and mobile-first technician interfaces as the critical go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional facilities management software specialists because fragmented buyer procurement across 50-500 technician organizations prevents national-scale organic growth. Long-term viability hinges on AI-enabled workforce optimization capabilities that survive platform consolidation. Watch OSHA lone-worker safety mandate enforcement timelines as the inflection signal for GPS telemetry module attach-rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Exposes scheduling modules to third-party analytics vendors, eroding suite-based lock-in for German OEMs. |
| Edge-to-Cloud Infrastructure Investment | Caches work orders on technician devices for FCC-regulated telecommunications coverage in remote terrain. |
| EU AI Act Compliance Engineering | Documents algorithmic provenance for Munich-based manufacturers demanding human-in-the-loop audit trails. |
| Outcome-Based Service Contract Enablement | Shifts billing from technician hours to uptime guarantees for IRA-rewarded HVAC efficiency providers. |
| Mid-Market Subscription Scaling | Captures 50-500 technician organizations in India's PLI-driven electronics manufacturing service corridors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with field service operations directors, IT procurement officers at utilities, platform integration specialists, and aftermarket service heads at industrial OEMs with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory submission databases. Bottom-up technician deployment estimates and top-down enterprise software spending patterns were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic through recent replacement-cycle acceleration established baseline adoption curves across the projection horizon. The analytical framework modeled deployment architecture, functional module penetration, end-user vertical regulatory exposure, and AI-enabled feature adoption as core segmentation dimensions. CAGRs were derived from technician headcount expansion rates, cloud migration timelines for legacy on-premise systems, and compliance-driven upgrade cycles tied to GDPR and EU AI Act enforcement phases.
Caveats apply where OSHA enforcement intensity, FCC spectrum reallocation, or EU AI Act interpretive guidance could materially shift the outlook for workforce telemetry and automated dispatch adoption. Forecasts reflect assumptions about mid-sized service organization capital constraints and hyperscaler bundling strategies that may revise with macroeconomic credit conditions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
E-Ink E-Reader Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Digital Pen Market
Digital Solutions
Consent Management Market