
 Legal Transcription Market | 2026-2036
Legal Transcription Market Size, Share, and Industry Trends Forecast 2026-2036
Legal Transcription Market Outlook
AAERT certification is rotating as the primary credential gate for legal transcription providers entering court reporting and deposition workflows. Rev leverages a distributed freelancer network to sustain rapid turnaround for law firms nationwide. LexTranscribe specializes in certified court transcription, dominating state-level judicial procurement channels.
Legal transcription converts audio and video legal proceedings into formatted text documents with verbatim accuracy standards typically requiring 98 percent precision or higher for admissible court records. Its primary purpose is creating searchable, timestamped documentation for litigation support, appellate review, and compliance archiving. Outsourced transcription services occupy the largest revenue pool among service type segments, while speech recognition technology leads growth as firms integrate automated first-pass drafting with human quality assurance. Real-time transcription is accelerating fastest in courtroom and deposition settings where immediate record availability shapes procedural efficiency.
Court administrators in the United States must align transcription workflows with HIPAA privacy safeguards for medical-legal cases and state bar ethics rules governing confidentiality. The Federal Rules of Civil Procedure discovery standards shape document production timelines that directly dictate transcription volume and urgency. Stakeholders should monitor how state judicial budgets and AI accuracy benchmarks reshape procurement criteria between certified human transcribers and hybrid automation models.
Market Dynamics
AI-powered speech recognition is compressing turnaround times for legal transcription while court systems modernize record-keeping standards, creating tension between certified human transcribers and hybrid automation models in procurement decisions.
Growth Catalysts
- Federal Rules of Civil Procedure discovery standards:Document production timelines in US litigation directly dictate transcription volume and urgency for law firms managing regulatory discovery requirements.
- Real-time transcription technology:Courtroom and deposition settings now demand immediate record availability, reshaping procedural efficiency expectations among judicial administrators.
- Medical-legal case expansion:HIPAA privacy safeguards for health-related litigation create specialized transcription demand requiring certified handling protocols.
Market Restraints
- AAERT certification scarcity:The credential gate for court reporting and deposition workflows limits qualified provider pool expansion and extends onboarding timelines.
- Speech recognition accuracy ceilings:Automated first-pass drafting still requires human quality assurance to meet 98 percent verbatim precision standards for admissible court records.
- State judicial budget volatility:Procurement channel concentration in government-funded court systems creates demand unpredictability for transcription service providers.
Strategic Opportunities
- Appellate review automation:Timestamped documentation tools for litigation support enable searchable archive products beyond basic transcription delivery.
- Compliance archiving convergence:Integration of legal transcription with enterprise governance platforms creates bundled service offerings for corporate legal departments.
- State-level judicial procurement channel consolidation:Dominant positioning in certified court transcription opens multi-year service contracts as court systems centralize vendor relationships.
Industry Challenges
- Freelancer network quality assurance:Distributed transcription labor pools complicate consistency enforcement for verbatim accuracy standards across dispersed workflows.
- Legacy court recording system integration:Modern transcription platforms face technical friction when interfacing with aging analog infrastructure still deployed in municipal court facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal Transcription Market |
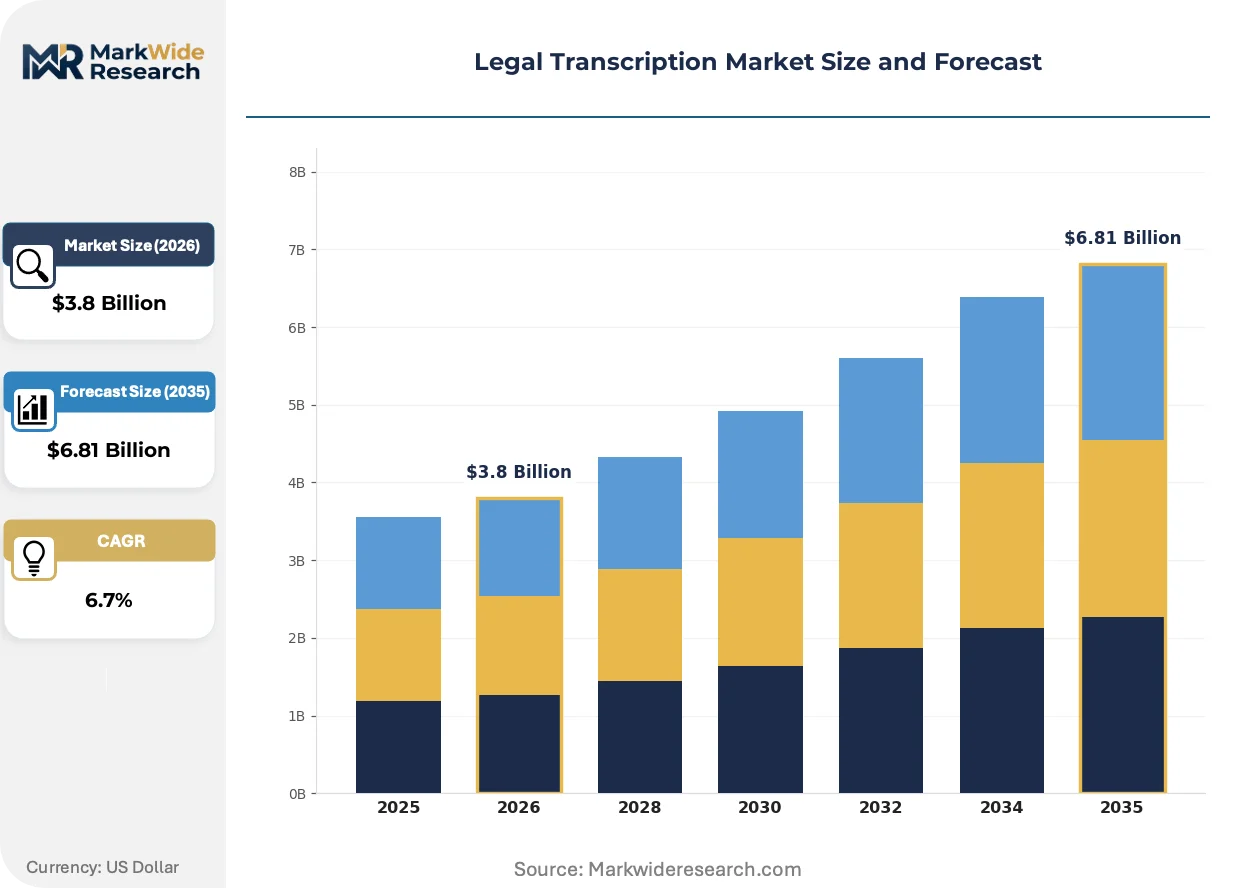
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Real-time Transcription, Outsourced Transcription, Digital Recording, Manual Transcription Client Type: Law Firms, Corporations, Courts, Independent Practitioners Format: Verbatim, Edited, Summarized, Hybrid Technology: Speech Recognition, Dictation Software, Cloud Storage, Audio Playback |
| Companies Covered | Rev, Sonix, LexTranscribe, GoTranscript, Ditto Transcripts, SpeakWrite, Flatworld Solutions, TranscribeMe, Servixer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal Transcription Market Strategic Shifts
Speech recognition technology is actively reshaping competitive positioning between pure human transcription and hybrid automation models, while regulatory discovery requirements and procurement centralization create simultaneous pressure for speed and certification integrity.
Automated speech-to-text engines with legal vocabulary training are supplanting manual first-pass drafting in high-volume deposition workflows. Mid-sized litigation support firms now deploy these tools for initial transcript generation before human editors apply verbatim accuracy standards. The structural consequence is compression of per-page production costs and reallocation of skilled transcribers toward quality assurance rather than raw transcription.
HIPAA privacy safeguards and state bar ethics rules governing confidentiality are tightening data handling requirements for medical-legal transcription providers. Court administrators must now demonstrate encrypted workflow architectures and access logging to qualify for sensitive case assignments. US-based litigation support firms are responding by segregating infrastructure for health-related matters and pursuing specialized compliance certifications beyond baseline AAERT credentials.
Law firm procurement departments are consolidating vendor relationships around transcription providers offering both rapid turnaround and certified court admissibility. Boutique litigation practices previously managing multiple regional vendors now favor national platforms with distributed freelancer networks and standardized quality protocols. This concentration is most visible in metropolitan legal markets where discovery volume and regulatory deadline pressure coexist.
Legal Transcription Market Segmentation
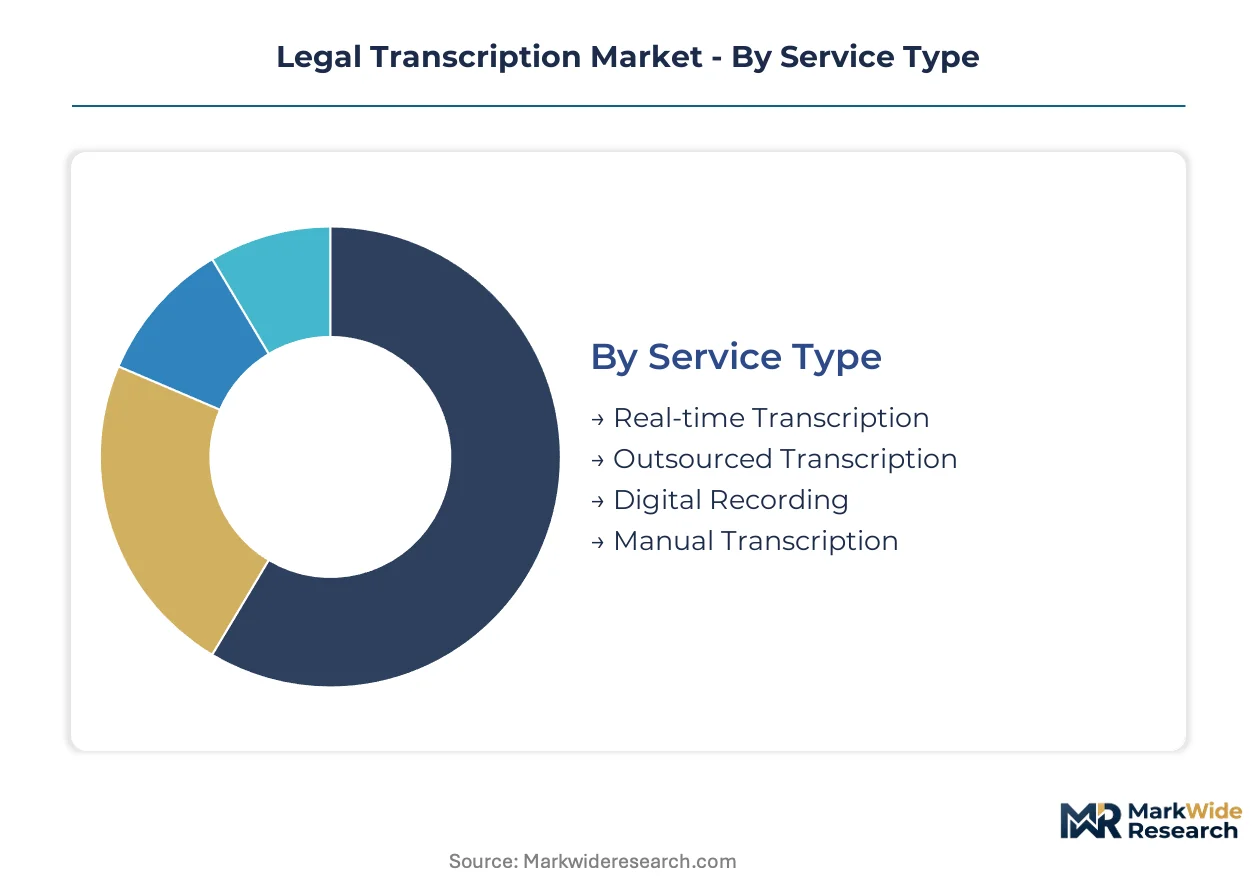
Legal transcription procurement splits sharply between certified court-admissible workflows and high-volume commercial litigation support. Segment boundaries determine pricing tiers, compliance obligations, and technology deployment strategies across the value chain.
Service Type:
Domestic court systems anchor demand for certified transcription, while export-led growth concentrates in litigation support services for multinational law firms.
- Outsourced Transcription:Third-party providers manage high-volume deposition and discovery documentation under contractual SLA frameworks. Law firms in the United States drive procurement concentration, with HIPAA-compliant handling requirements for medical-legal cases tightening vendor qualification standards.
- Real-time Transcription:Courtroom stenography and live deposition feeds deliver instantaneous text streams through CAT software integration. State judicial administrators in California, Texas, and New York represent the primary deployment geography, where procedural rules mandate immediate record availability for appellate preservation.
- Digital Recording:Audio-capture infrastructure for subsequent transcription processing, deployed predominantly in municipal court facilities upgrading from analog systems.
- Manual Transcription:Human-only drafting without automation assistance, retained for accent-heavy or poor-quality source audio where speech recognition fails.
Outsourced transcription commands the established base. The steepest expansion runs through real-time transcription.
Client Type:
Cost tier stratification separates enterprise legal departments with bundled procurement budgets from individual practitioners purchasing per-page.
- Law Firms:AmLaw 200 firms and regional litigation practices generate sustained volume through discovery-heavy practice areas. Federal Rules of Civil Procedure deadlines compress turnaround requirements, with e-discovery vendors increasingly embedding transcription into broader document production workflows.
- Courts:State and federal court administrators procure certified transcription for official records, appellate transcripts, and public access compliance. Budget volatility in California, Florida, and Illinois judicial systems creates demand unpredictability for contracted providers.
- Corporations:In-house legal departments and compliance functions purchase transcription for internal investigations, regulatory examinations, and employment litigation.
- Independent Practitioners:Solo attorneys and small partnerships buy ad-hoc transcription for discrete matters without volume commitments.
Law firms command the established base. The steepest expansion runs through corporate legal departments.
Format:
Application context determines format selection, with admissibility requirements forcing verbatim precision while internal review permits summarization.
- Verbatim:Word-for-word transcription including false starts, filler words, and non-verbal markers. Court reporters in deposition and trial settings must achieve 98 percent accuracy under AAERT certification standards for admissible records.
- Edited:Cleaned transcription removing stutters and repetitions while preserving substantive content. Corporate legal departments favor this format for witness preparation and internal strategy review.
- Summarized:Condensed narrative capturing key testimony points without full dialogue reconstruction. Regulatory investigations and due diligence processes deploy this format to accelerate document triage.
- Hybrid:Automated first-pass drafting with human editorial refinement, gaining adoption in high-volume discovery contexts where cost compression outweighs precision requirements.
Verbatim format commands the established base. The steepest expansion runs through hybrid processing.
Technology:
Supply concentration among speech recognition vendors is reshaping competitive dynamics between pure human transcription and augmented automation models.
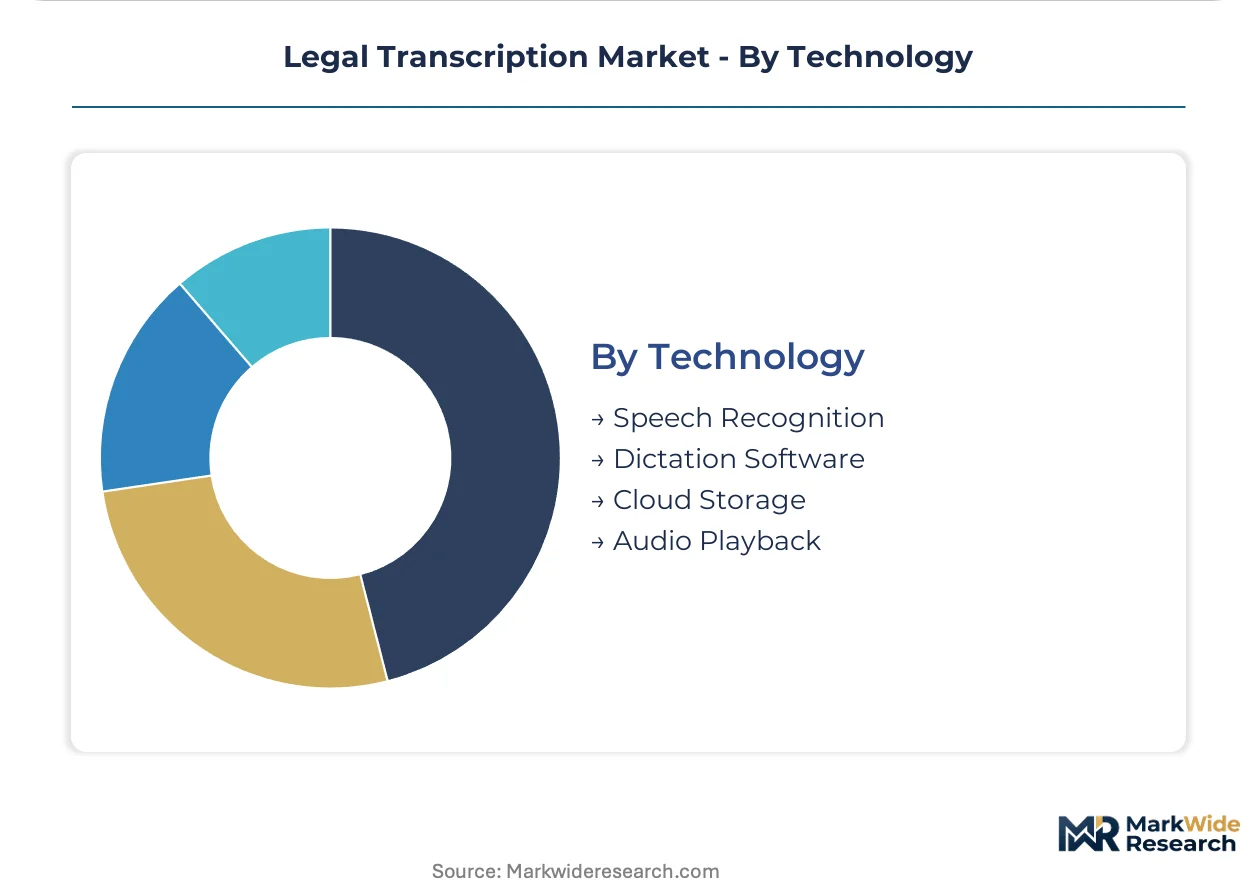
- Speech Recognition:AI-powered engines trained on legal vocabulary and speaker identification, deployed for initial transcript generation before human quality assurance. Mid-sized litigation support firms integrate these tools to compress per-page production costs.
- Cloud Storage:Encrypted workflow architectures with access logging and geographic data residency controls, mandatory for HIPAA-compliant medical-legal transcription.
- Dictation Software:Attorney-captured audio for subsequent transcription processing, retained in corporate legal departments and solo practice settings.
- Audio Playback:Variable-speed review tools with timestamp synchronization, supporting human transcribers in accuracy verification workflows.
Speech recognition commands the established base. The steepest expansion runs through cloud storage infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Law firms and court systems in the United States drive the majority of procurement volume, with litigation discovery requirements and judicial modernization programs sustaining demand concentration. Secondary markets in Canada, the United Kingdom, Australia, and India exhibit growth through outsourced litigation support services and domestic court digitization initiatives.
United States
Federal Rules of Civil Procedure discovery standards and HIPAA privacy safeguards for medical-legal cases sustain transcription demand from AmLaw 200 firms and state court administrators. The Department of Justice and state bar associations enforce confidentiality protocols that shape vendor qualification criteria. California, Texas, and New York represent the primary deployment geography, where real-time transcription mandates in appellate preservation accelerate technology procurement.
Canada
Provincial court digitization programs and bilingual legal proceedings in Quebec generate specialized transcription requirements for certified providers. Health Canada privacy regulations govern medical-legal documentation handling, while the Department of Justice Canada oversees federal court standards. Toronto and Vancouver anchor commercial litigation support demand, with Ottawa-based government legal services sustaining public sector procurement.
United Kingdom
Civil Procedure Rules discovery timelines and GDPR data handling requirements create compliance-layered transcription demand from London-based magic circle firms and regional chambers. The Ministry of Justice oversees court reporting standards, while the Information Commissioner's Office enforces cross-border data transfer restrictions. The City of London and Manchester legal districts concentrate outsourced transcription procurement for international arbitration and commercial litigation.
Australia
Federal Court of Australia digitization mandates and state-level uniform evidence law reforms drive transcription modernization across judicial systems. The Therapeutic Goods Administration and state health privacy regulations govern medical-legal documentation workflows. Sydney and Melbourne anchor corporate litigation support demand, with Brisbane and Perth expanding procurement through resource sector regulatory investigations.
India
Legal process outsourcing from US and UK law firms sustains transcription service demand through Bangalore, Hyderabad, and Delhi-NCR delivery centers. The Bar Council of India and Information Technology Act data protection provisions shape vendor operating requirements. Mumbai's commercial litigation practices and Chennai's court reporting services represent domestic demand pockets amid export-led growth concentration.
Legal Transcription Market Competitive Environment
Player mix skews toward distributed freelancer networks and certified court specialists competing against hybrid automation platforms. The vendor base separates into three functional tiers: rapid-turnaround generalists, certified judicial specialists, and technology-augmented scale operators. Consolidation pressure concentrates among mid-sized litigation support firms pursuing geographic coverage, while strategic partnerships between speech recognition vendors and quality assurance providers reshape service delivery architectures.
Within the certified specialist tier, LexTranscribe occupies a position exemplifying state-level judicial procurement dominance. Rev and TranscribeMe represent the distributed network archetype, anchoring rapid-turnaround capacity for law firms nationwide. Sonix exemplifies technology-augmented positioning, sitting within the automation-first segment where legal vocabulary training and speaker identification tools compress production timelines.
| Leading Market Players |
|---|
| Rev |
| Sonix |
| LexTranscribe |
| GoTranscript |
| Ditto Transcripts |
| SpeakWrite |
| Flatworld Solutions |
| TranscribeMe |
| Servixer |
| Others |
Value Chain & Pricing Dynamics
Twenty-four to seventy-two hour turnaround windows for certified court transcripts concentrate pricing power among AAERT-credentialed providers with established judicial procurement relationships, while distributed freelancer networks compete on cost for high-volume deposition workflows. This lead-time stratification feeds directly into supply chain configuration, where quality-assurance labor pools and speech recognition infrastructure investments determine competitive positioning across service tiers.
Pricing Analysis
Cost-plus contracts with Consumer Price Index escalation clauses dominate state judicial procurement for certified transcription, while per-page transactional pricing prevails in commercial litigation support. Price differentiation hinges on AAERT certification grade and volume scale, with boutique providers commanding premiums for rush turnaround. Cost compression in hybrid automation tiers is intensifying as speech recognition tools displace manual first-pass drafting. Corporate legal departments exhibit highest price sensitivity, whereas court administrators prioritize certification integrity over per-unit cost.
Supply Chain Analysis
The United States anchors certified court transcription capacity, while India and the Philippines concentrate export-oriented litigation support labor pools. Cloud infrastructure and encrypted workflow architectures constitute critical input dependencies alongside AAERT-credentialed transcribers. Single-source vulnerability in speech recognition engine providers creates concentration risk for hybrid automation operators. Distribution runs through direct judicial procurement channels and law firm vendor consolidation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The legal transcription market exhibits cyclical recovery characteristics as litigation volume rebounds from pandemic-era court backlogs and federal discovery deadlines compress procurement timelines. State judicial modernization budgets and AI accuracy benchmarks constitute the primary cyclical drivers reshaping demand patterns.
For Market Incumbents: Consolidate market position by acquiring AAERT-credentialed regional specialists to deepen certification coverage and secure multi-year judicial contracts. Invest in backward integration into proprietary speech recognition training datasets to differentiate hybrid automation offerings against generic API-dependent competitors. This counters margin pressure from pure-play technology entrants.
For New Entrants and Emerging Players: Anchor in corporate legal departments with compliance archiving convergence products, the most penetrable segment amid bundled service procurement trends. Target mid-sized litigation support firms lacking HIPAA-compliant infrastructure for medical-legal transcription. Pursue channel partnerships with e-discovery vendors to embed transcription into broader document production workflows.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because judicial procurement centralization and certification scarcity favor scaled operators with diversified geographic coverage. Acquisition targets should demonstrate dominant positioning in state-level court channels or proprietary legal vocabulary speech recognition assets. Monitor state judicial budget appropriations as the signal to watch for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| AAERT Certification Expansion | Deepens judicial procurement eligibility and commands premium pricing in court-admissible workflows. |
| Speech Recognition Platform Development | Reduces per-page production costs and reallocates skilled labor toward quality assurance functions. |
| HIPAA-Compliant Infrastructure Investment | Opens medical-legal case assignments and satisfies health privacy regulations for sensitive litigation. |
| State Judicial Procurement Consolidation | Secures multi-year service contracts as court systems centralize vendor relationships and technical standards. |
| Real-Time Transcription Technology Deployment | Addresses appellate preservation mandates in California, Texas, and New York courtroom settings. |
Study Parameters
Operator-level perspectives from court administrators, litigation support firm executives, AAERT-certified transcribers, and law firm procurement officers anchored the qualitative base for this analysis. Secondary validation drew from Federal Rules of Civil Procedure amendments, state judicial budget appropriations, HIPAA enforcement guidance, and speech recognition accuracy benchmarking studies. Bottom-up transcription volume modeling triangulated against top-down legal services expenditure data to establish market sizing.
Sensitivity analysis across certification penetration rates, AI adoption curves, and judicial budget scenarios shaped the analytical framework. Segmentation dimensions included service type, client category, format precision requirements, and technology deployment model. CAGRs derived from historical transcription volume growth correlated with litigation filing trends and court modernization program schedules. Forecast inputs incorporated speech recognition accuracy improvement trajectories and state procurement centralization timelines.
Decision-makers should treat outputs as directional under assumptions of sustained federal discovery standards and gradual AI accuracy convergence; material deviation in judicial technology adoption or regulatory privacy enforcement would warrant model refresh. Specific risk factors include state budget austerity programs and breakthrough speech recognition performance that displaces human quality assurance requirements. Recalibration cycles align with material shifts in court system modernization appropriations and AI benchmarking milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Transport Management System Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Platform Architecture Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Infrastructure As Code (Iac) Market
Digital Solutions
Global E-Passport and E-Visa Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market