
 Bike Fenders Market | 2026-2036
Bike Fenders Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Fenders Market Analytics
REACH compliance is rebalancing the cost-of-entry calculus for European manufacturers by restricting certain plasticizers and surface treatments in bicycle accessory production. SKS leverages its Rhineland-Palatinate manufacturing base to sustain integrated aluminum forming capabilities. Mucky Nutz competes through specialized polymer compounds designed for extreme mountain-bike conditions. Zefal anchors its position via century-old French tooling expertise and direct OEM relationships with major bicycle assemblers.
Bike fenders are protective shields mounted above bicycle wheels, typically manufactured from polypropylene blends, aluminum extrusions, or carbon fiber prepregs, with widths ranging from 35mm to 75mm to match tire profiles and block water, debris, and road spray from reaching the rider or drivetrain. Their primary purpose spans rider comfort, component longevity, and safety compliance in fleet and commercial cycling operations. The material dimension shows aluminum and carbon fiber capturing premium margin pools in performance cycling, while plastic compounds dominate volume in commuter and entry-level segments. Full coverage and clip-on types lead the type dimension, with integrated installation systems gaining share as bicycle OEMs design fender mounts into frame architectures from initial concept stages.
The European Chemicals Agency enforces REACH substance restrictions that directly affect polymer sourcing decisions for fender manufacturers serving EU markets. The US Consumer Product Safety Commission maintains bicycle equipment safety standards that influence fender attachment integrity requirements for products entering American distribution channels. Japan's Ministry of Economy, Trade and Industry promotes JIS-standardized bicycle component interoperability that shapes export-ready product development cycles. Stakeholders must monitor evolving extended-producer-responsibility frameworks that will increasingly mandate recyclability disclosures and end-of-life collection infrastructure for bicycle accessories.
Market Dynamics
The EU Green Deal's circular-economy mandates are forcing material redesign cycles across bicycle accessory supply chains, with ECHA REACH restrictions on plasticizers and surface treatments compressing formulation timelines for polymer-based fenders.
Growth Catalysts
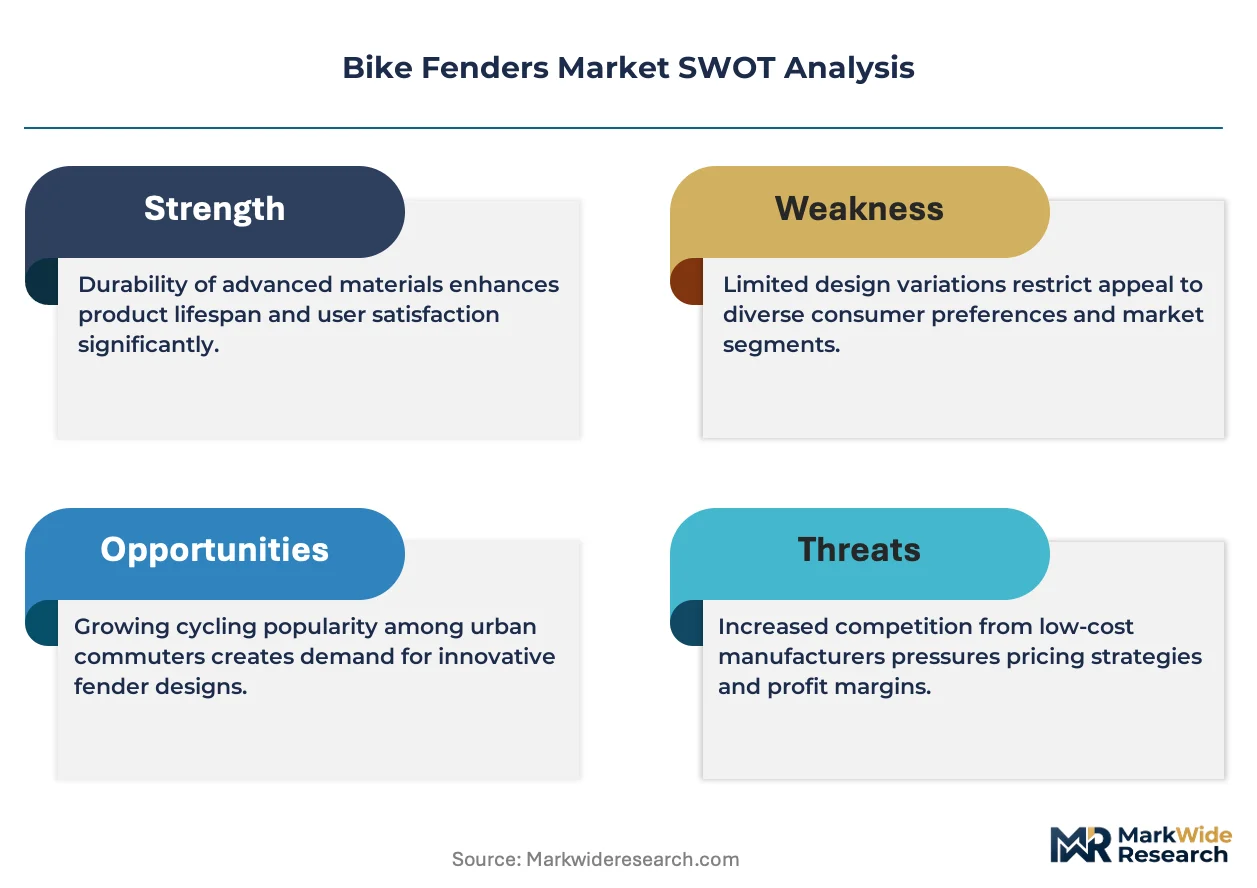
- Protected bike lane procurement:European municipalities are expanding urban commuting fleets with dedicated infrastructure, creating fleet-scale demand for durable fender systems.
- REACH substance restrictions:ECHA enforcement is accelerating R&D investment in compliant polymer compounds and aluminum forming techniques among incumbent manufacturers.
- Integrated frame architectures:Bicycle OEMs are embedding fender mounts into initial design stages, reducing aftermarket friction and locking in supplier relationships.
Market Restraints
- Aluminum price volatility:Premium segment margins face pressure from London Metal Exchange aluminum fluctuation and energy-intensive extrusion costs.
- Polymer feedstock concentration:Polypropylene blend sourcing clusters in German and Benelux petrochemical corridors create geographic supply risk.
- Carbon fiber prepreg substitution ceiling:High material and layup labor costs limit carbon fiber fender penetration to ultra-premium racing segments.
Strategic Opportunities
- Extended producer responsibility frameworks:EU-mandated recyclability disclosures and end-of-life collection infrastructure create first-mover advantage for circular-design specialists.
- E-bike fleet standardization:Commercial cycling operators in Germany and the Netherlands are specifying unified fender widths and attachment systems across mixed fleets.
- 3D-printed polymer tooling:Converging additive manufacturing with recycled ocean plastics enables low-volume customization for boutique frame builders.
Industry Challenges
- Multi-material bonding expertise:Hybrid aluminum-polymer fender assemblies require specialized adhesive chemistries and thermal expansion management that strain existing production engineering teams.
- REACH pre-registration timelines:ECHA substance notification windows compress product development cycles, forcing parallel regulatory and commercial track management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Fenders Market |
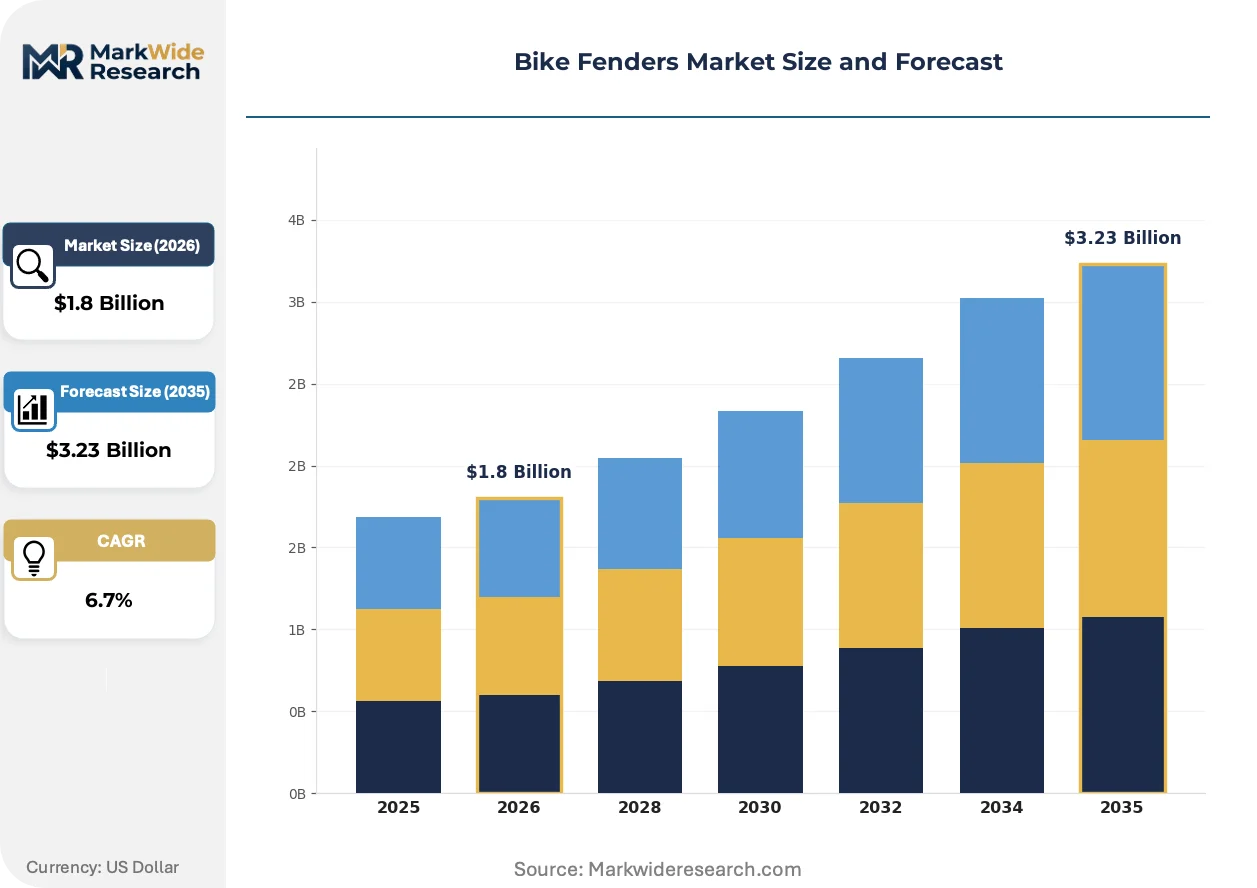
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Full Coverage, Clip-On, Lightweight, Mudguard Material: Plastic, Aluminum, Steel, Carbon Fiber Application: Road Bikes, Mountain Bikes, Commuting, Touring Installation: Permanent, Removable, Adjustable, Integrated |
| Companies Covered | SKS, Mucky Nutz, Portland Design Works, Blackburn, Topeak, All Mountain Style, Zefal, Planet Bikes, Velochampion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Fenders Market Evolving Landscape
Material science advances and regulatory compliance automation are compressing product development timelines while fragmenting competitive positioning between integrated OEM suppliers and specialized aftermarket brands.
Modular quick-release attachment systems are integrating magnetic and cam-lock mechanisms to enable tool-free wheel clearance adjustments. Urban commuters and commercial fleet operators in Copenhagen and Amsterdam are adopting these systems fastest. This technology is integrating formerly separate fender and rack product categories into unified cargo-commuter accessory platforms.
REACH SVHC candidate list expansion is forcing reformulation of UV-stabilized polypropylene blends used in commuter fender production. Compounders serving the bicycle accessory sector are accelerating bio-based plasticizer substitution programs. German and French manufacturers face the steepest compliance cost curves given their integrated European supply base exposure.
Fleet procurement managers are consolidating vendor relationships through multi-year framework agreements covering fenders, racks, and lighting systems. Bicycle leasing operators in Germany are displacing spot-market purchasing with lifecycle cost contracting. This concentration is most visible in municipal bike-share tenders across Rhineland-Palatinate and Baden-Württemberg.
Bike Fenders Market Segmentation
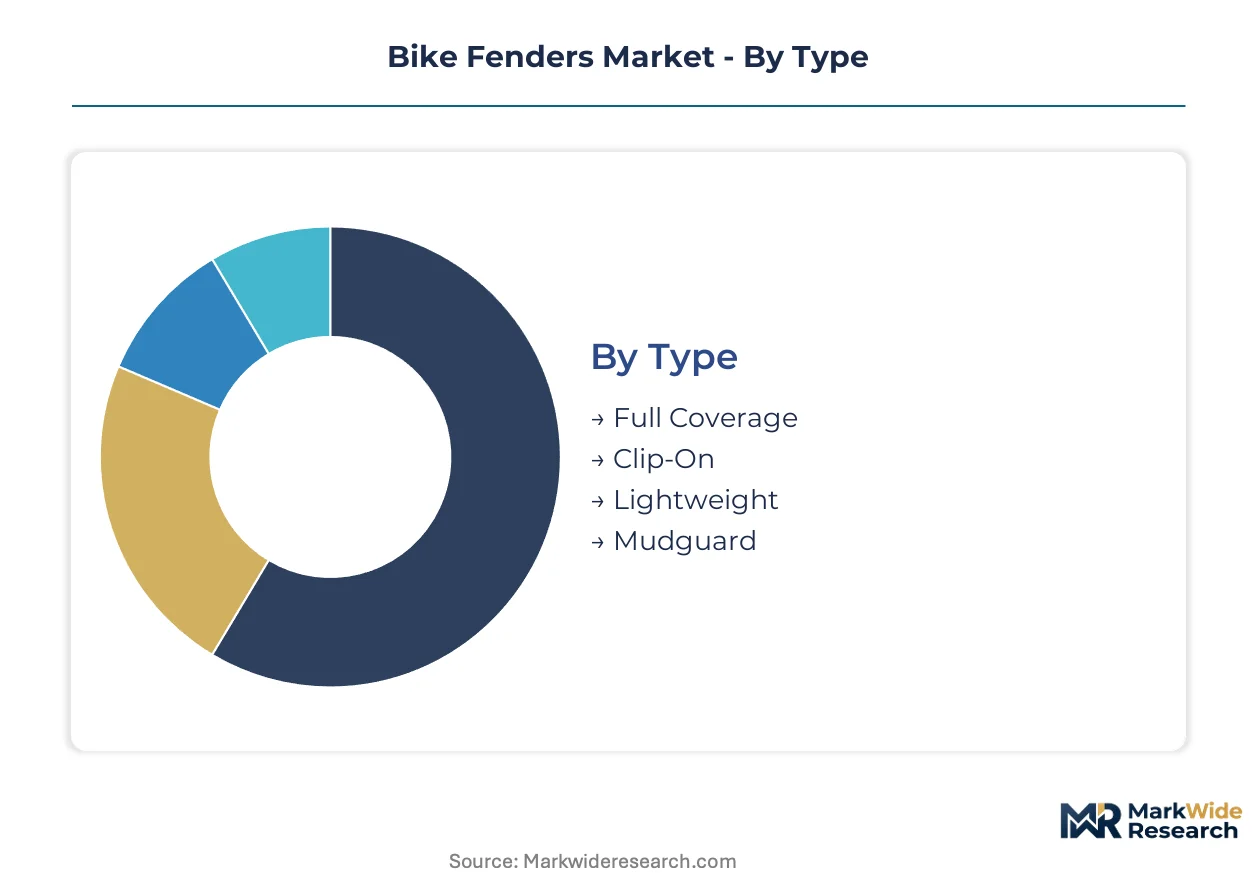
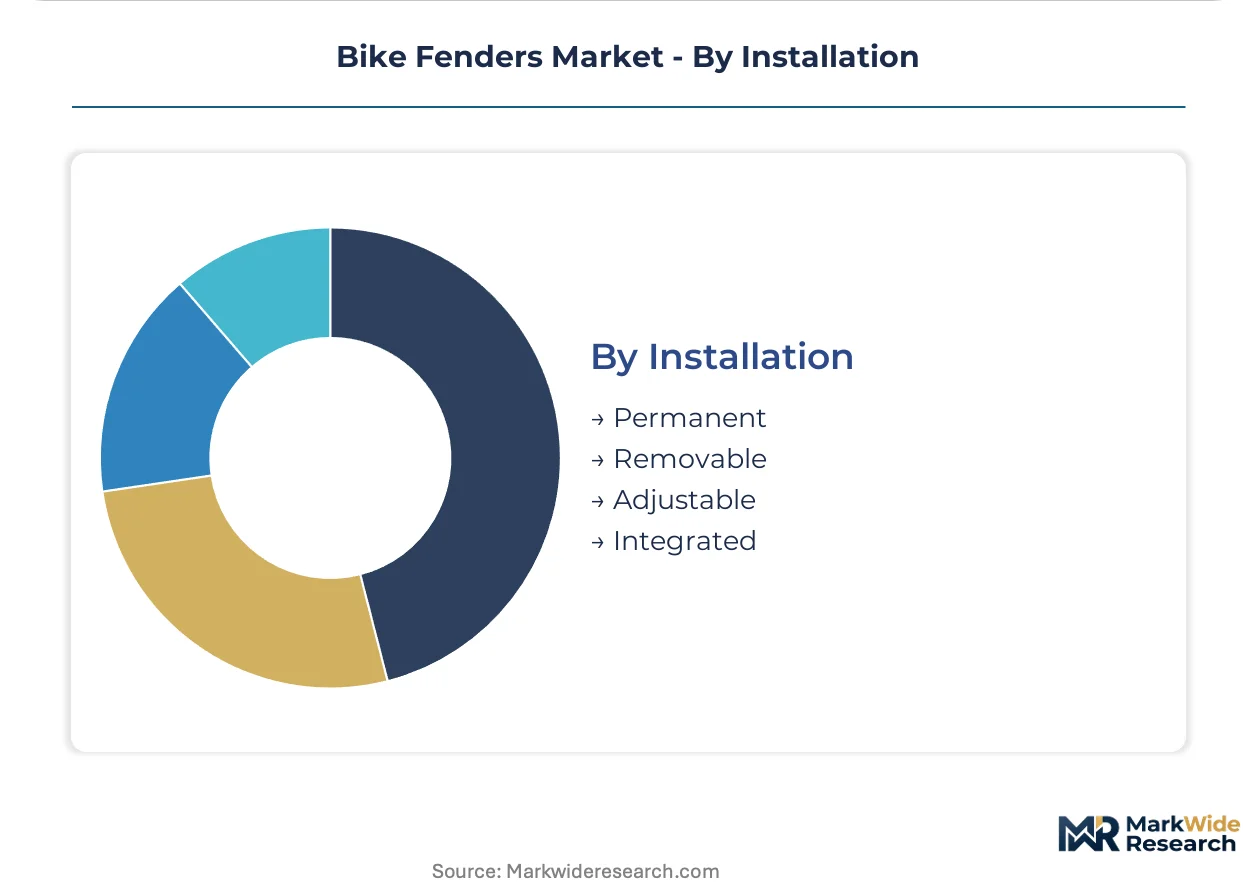
Bike fender segmentation reflects divergent performance requirements across cycling disciplines and mounting constraints imposed by frame architectures. Material and installation type choices cascade into supply chain configurations that favor either mass-volume polymer molding or precision metal forming capabilities.
Type:
Volume production concentrates in commuter-oriented designs, while premium positioning attaches to specialized mountain and racing configurations.
- Full Coverage:Wrap-around shields extending from fork crown to chainstay bridge, manufactured in polypropylene blends or aluminum extrusions. Copenhagen and Amsterdam municipal fleets specify these for year-round rider protection in wet climates. REACH-compliant polymer sourcing from Rhineland-Palatinate compounders anchors European supply.
- Clip-On:Detachable brackets enabling rapid wheel clearance without tools. Demand clusters with urban commuters and bike-share operators in Dutch and German cities seeking theft-deterrent quick-release functionality. SKS and Zefal dominate OEM specification for these systems.
- Lightweight:Minimal-coverage designs in carbon fiber prepregs or thin-gauge aluminum for racing weight constraints.
- Mudguard:Partial-coverage rear shields for mountain bike rear triangle protection against trail debris.
Mature deployment sits with Full Coverage in Northern European fleet procurement. Newer deployment is concentrated in Clip-On systems for mixed-use private bicycles.
Material:
Cost tier stratification separates commodity thermoplastics from performance metals and composites, with regulatory compliance costs widening the gap.
- Plastic:Polypropylene and ABS blends dominate unit economics through injection molding at scale. ECHA REACH restrictions on phthalate plasticizers and UV stabilizers are forcing reformulation cycles among German and Benelux compounders serving the sector.
- Aluminum:Extruded and roll-formed alloys capture premium commuter and touring segments. London Metal Exchange price volatility and energy-intensive extrusion costs pressure margin structures at SKS's Rhineland-Palatinate facilities.
- Steel:Chromoly and stainless variants persist in utility and cargo bike applications requiring impact resistance.
- Carbon Fiber:Prepreg layup construction limited to ultra-premium racing segments where gram-level weight reduction commands price premiums.
Plastic formulations retain volume leadership across entry and mid-tier positioning. Aluminum is gaining share fastest in fleet-specified durability requirements.
Application:
End-use concentration tracks infrastructure development patterns and weather exposure severity across cycling cultures.
- Road Bikes:Narrow-profile fenders in lightweight aluminum or carbon matching tire widths. German and French racing component assemblers specify minimal-coverage designs for criterium and sportive use.
- Mountain Bikes:Impact-resistant polymer compounds formulated for extreme trail conditions. Mucky Nutz specializes in flexible polymer formulations that deform without cracking on rock strikes.
- Commuting:Full-coverage systems with integrated lighting mounts and rack compatibility. Municipal procurement across Baden-Württemberg and Rhineland-Palatinate standardizes these for fleet uniformity.
- Touring:Heavy-duty aluminum or steel construction with multiple attachment points for loaded bicycle stability.
Commuting applications anchor current procurement volume. Mountain bike configurations are expanding most quickly through trail network investments in German and Austrian alpine regions.
Installation:
Mounting architecture evolution is fragmenting supplier relationships between frame-integrated OEM supply and aftermarket retrofit specialists.
- Permanent:Bolt-on brackets requiring frame drilling, dominant in traditional touring and utility bicycle construction.
- Removable:Strap and clamp systems for frames lacking dedicated mounting points. Aftermarket demand concentrates in retrofit markets for older bicycle stock.
- Adjustable:Sliding bracket mechanisms accommodating tire width changes. German leasing operators specify these for mixed-fleet flexibility across seasonal tire swaps.
- Integrated:Frame manufacturers embedding fender mounts into initial design stages. Canyon and Rose Bikes specify these architectures, locking in supplier relationships at concept phase.
Permanent installation retains installed base dominance. Integrated mounting is climbing the fastest as OEMs design accessory compatibility from concept stage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized manufacturing zones in Germany's Rhineland-Palatinate and France's Auvergne-Rhône-Alpes regions concentrate precision aluminum forming capabilities for premium fender production. These clusters leverage proximity to European bicycle OEM headquarters and ECHA REACH compliance infrastructure.
Germany
Municipal fleet procurement across Baden-Württemberg and Rhineland-Palatinate drives standardized full-coverage fender demand for year-round commuter operations. The EU Green Deal's circular-economy mandates tighten material specifications through ECHA substance restrictions. SKS anchors integrated manufacturing in Rhineland-Palatinate, sustaining aluminum extrusion and polymer compounding under one roof.
France
Zefal's century-old tooling expertise in the Auvergne-Rhône-Alpes region supplies OEM relationships with major bicycle assemblers. REACH SVHC candidate list expansions force reformulation of UV-stabilized polypropylene blends among domestic compounders. The cluster specializes in clip-on quick-release systems for urban commuter markets in Paris and Lyon metropolitan areas.
Netherlands
Amsterdam and Copenhagen municipal bike-share operators specify unified fender widths across mixed commercial fleets. National cycling infrastructure investments accelerate protected bike lane procurement with dedicated fender durability requirements. Rotterdam's port logistics hub facilitates polymer feedstock import from German and Benelux petrochemical corridors.
United Kingdom
Mountain bike trail network investments in Scottish Highlands and Lake District regions expand demand for impact-resistant polymer formulations. The country's national environmental regulator enforces extended-producer-responsibility frameworks affecting end-of-life collection infrastructure. Mucky Nutz exemplifies specialized compound design for extreme conditions through UK-based R&D operations.
United States
Portland and Seattle metropolitan cycling cultures sustain aftermarket demand for premium clip-on and full-coverage systems. The Consumer Product Safety Commission maintains bicycle equipment safety standards influencing fender attachment integrity requirements for domestic distribution. Pacific Northwest frame builders drive low-volume customization demand through boutique manufacturing relationships.
Bike Fenders Market Competitive Landscape
German producers anchor the integrated OEM supply tier; French and UK specialists hold positions in compound innovation and extreme-condition applications. The market structure fragments between mass-volume polymer molders serving commuter segments and precision metal formers capturing premium durability requirements. Three archetypes dominate: century-old European tooling houses with direct OEM relationships, specialized polymer compounders for mountain bike applications, and scale-driven Asian manufacturers supplying entry-level markets. Competitive moves concentrate on strategic partnerships with frame manufacturers for integrated mounting architectures and geographic expansion into e-bike fleet procurement channels.
Within the established European tooling tier, SKS and Zefal represent integrated manufacturing archetypes with co-located aluminum forming and polymer operations. Mucky Nutz occupies a specialist position exemplifying compound-driven differentiation for extreme trail conditions. These three anchors demonstrate how geographic clustering around regulatory compliance infrastructure and OEM proximity shapes sustainable competitive positioning. Each represents a distinct capability vector: Rhineland-Palatinate integrated production, Auvergne-Rhône-Alpes century-old tooling relationships, and UK-based polymer science specialization.
| Leading Market Players |
|---|
| SKS |
| Mucky Nutz |
| Portland Design Works |
| Blackburn |
| Topeak |
| All Mountain Style |
| Zefal |
| Planet Bikes |
| Velochampion |
| Others |
Value Network & Pricing Analysis
Municipal fleet procurement across German states anchors contract-based pricing structures, with multi-year framework agreements displacing spot-market purchasing and compressing margin variability for volume suppliers. This buyer concentration forces pricing discipline through lifecycle cost contracting rather than per-unit negotiation.
Pricing Analysis
Short lead-time premiums apply to integrated frame-mount systems demanded by Canyon and Rose Bikes for concept-stage specification, while spot inventory discounts emerge for standard clip-on brackets in aftermarket channels. Three-tier pricing structure across premium aluminum, standard polymer, and economy recycled compounds separates tiers by REACH compliance certification and durability testing. Pricing pressure stems from London Metal Exchange aluminum volatility and energy-intensive extrusion costs pressuring SKS's Rhineland-Palatinate operations. Municipal fleet managers exhibit highest price sensitivity through competitive tender processes, while boutique frame builders accept premium positioning for customization flexibility.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp facilitate hub-and-spoke patterns for polymer feedstock movement from German and Benelux petrochemical corridors. Manufacturing concentrates in Germany, France, and the Netherlands, with Rhineland-Palatinate and Auvergne-Rhône-Alpes anchoring precision aluminum forming. Raw material dependencies rest on polypropylene blends, aluminum extrusion billets, and carbon fiber prepregs. Single-source vulnerability concentrates in specialized REACH-compliant compounders serving bicycle accessory sectors. Distribution runs through OEM direct supply for integrated mounting systems and aftermarket distributors for retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bike fenders market sits in a materials-transition phase, with integrated polymer-aluminum hybrid architectures displacing single-material legacy designs across premium commuter segments.
For Market Incumbents: Cement supplier relationships with frame manufacturers at concept stage through co-development of integrated mounting architectures, locking out aftermarket competitors. Expand in-house polymer compounding capabilities in Rhineland-Palatinate to capture REACH compliance premiums and reduce feedstock cost exposure. Carbon fiber substitution in ultra-premium racing segments threatens aluminum durability positioning; defend through hybrid material patents and thermal expansion management expertise. For New Entrants and Emerging Players: EU Green Deal circular-economy mandates in Germany and France open a window for recycled ocean plastic compounders to capture municipal fleet procurement seeking sustainability credentials. Target 3D-printed polymer tooling for boutique frame builders in Portland and Seattle metropolitan areas, where low-volume customization commands price premiums. Pursue direct relationships with e-bike leasing operators standardizing mixed-fleet fender specifications across seasonal tire swaps. For Investors and Strategic Acquirers: The window for entry favors specialized compounders with REACH-compliant formulation libraries and direct OEM relationships. Long-term viability hinges on regulatory compliance infrastructure proximity and integrated manufacturing scale. Watch ECHA SVHC candidate list expansion velocity as inflection indicator for reformulation cost curves and competitive consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Frame-Mount Co-Development | Locks in supplier relationships at Canyon and Rose Bikes concept stages. |
| REACH-Compliant Polymer Compounding | Captures premium positioning as ECHA restrictions tighten formulation requirements. |
| Recycled Ocean Plastic Sourcing | Aligns with EU Green Deal circular-economy mandates for municipal fleet procurement. |
| 3D-Printed Tooling Investment | Enables low-volume customization for Pacific Northwest boutique frame builders. |
| E-Bike Fleet Standardization Partnerships | Consolidates vendor relationships with German and Dutch leasing operators. |
Research Methodology
Multi-period observation of municipal procurement patterns, REACH compliance cost trajectories, and integrated frame architecture adoption anchored the trend analysis, supplemented by interviews with bicycle OEM procurement directors, polymer compounder technical leads, fleet procurement managers, and aftermarket distribution channel heads. Secondary validation drew from ECHA substance restriction databases, EU Green Deal implementation directives, London Metal Exchange aluminum pricing records, and bicycle industry association production statistics. Bottom-up segment sizing triangulated against top-down market value estimates derived from manufacturer revenue disclosures.
Segment-weighting approaches distributed value and volume across material type, installation architecture, and end-use application dimensions throughout the forecast period. CAGRs emerged from regression analysis against infrastructure investment cycles, regulatory implementation timelines, and technology substitution elasticities. Model inputs incorporated protected bike lane procurement forecasts, e-bike fleet penetration assumptions, and polymer feedstock price correlation factors.
The model assumes a particular technology adoption path; alternative pathways for carbon fiber prepreg substitution or bio-based polymer breakthroughs would alter the outlook for aluminum and conventional plastic demand trajectories. Forecasts reflect documented assumptions regarding REACH implementation velocity and municipal infrastructure spending continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bicycle Saddles Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market