
 Gloss Meters Market | 2026-2036
Gloss Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Gloss Meters Market Foresight
The gap between handheld field units and laboratory-grade tabletop systems is rebalancing as manufacturers recalibrate price-to-performance ratios across tiers. BYK Gardner leverages its coating industry heritage to dominate European reference standards. Elcometer anchors its position through deep channel control in protective coatings inspection. Konica Minolta competes by extending optical sensing expertise from colorimetry into gloss measurement workflows.
A gloss meter quantifies specular reflection at defined geometries, typically 20°, 60°, and 85° incidence angles, to characterize surface finish in manufacturing quality control. Digital technology variants now embed onboard data logging and Bluetooth connectivity, displacing analog readouts in plant-floor environments. Handheld gloss meters lead volume shipments due to portability demands from automotive OEMs and on-site coating contractors, while benchtop systems capture margin pools in research institutions requiring traceable calibration chains. Spectrophotometric technology represents the fastest-growing segment as multi-parameter instruments consolidate color, gloss, and haze measurement into single platforms.
ISO 2813 and ASTM D523 govern measurement geometry and reporting formats, compelling manufacturers to certify interoperability across national metrology frameworks. The U.S. FDA and EPA indirectly shape demand through surface finish requirements in medical device packaging and corrosion-resistant industrial coatings. Stakeholders must monitor how emerging battery enclosure standards and EV body panel specifications redefine gloss tolerance bands before committing to next-generation platform development.
Market Dynamics
The convergence of ISO 2813 and ASTM D523 measurement protocols with automotive OEM surface quality mandates is compressing tolerance bands and forcing instrument upgrades across coating supply chains.
Growth Catalysts
- Automotive OEM Surface Verification Mandates:EV manufacturers in Germany, Japan, and the United States now require 20°/60°/85° multi-angle gloss documentation for body panels and battery enclosures, pulling demand for certified handheld units.
- REACH and RoHS Compliance Deadlines:European coating formulators face tightened hazardous substance reporting, necessitating traceable surface finish data for regulatory dossiers and supplier audits.
- Spectrophotometric Platform Convergence:Colorimetry-gloss-haze integration into single instruments is collapsing capital expenditure thresholds for mid-tier manufacturers who previously maintained separate devices.
Market Restraints
- Optical Component Supply Concentration:German and Japanese precision lens manufacturers control critical interferometer-grade optics, creating single-source vulnerability for mid-range instrument makers.
- Metrology Calibration Backlog:National metrology institutes in the United States, Germany, and Japan face 12-18 month queues for ISO 17025 traceable certification, delaying new product launches.
- Smartphone-Based Visual Assessment Substitution:Low-stakes coating contractors in emerging markets increasingly rely on camera apps and cloud comparison tools for informal quality checks, bypassing instrument purchase.
Strategic Opportunities
- Indian Protective Coatings Infrastructure Buildout:BIS certification requirements for industrial coatings and PLI scheme incentives for domestic manufacturing are creating instrument demand clusters around Mumbai and Chennai.
- Cloud-Connected Fleet Management:Gloss meter-as-a-service models with subscription calibration and blockchain-anchored audit trails are penetrating automotive tier-one supplier networks.
- EU Battery Passport Regulations:Surface finish documentation for EV battery enclosures will become mandatory under emerging CSRD-linked supply chain disclosure rules, opening new compliance-driven procurement.
Industry Challenges
- Interoperability Fragmentation Across Metrology Stacks:Proprietary data formats from legacy tabletop systems block seamless integration with modern LIMS and MES platforms, forcing expensive middleware development.
- Field Technician Certification Bottlenecks:ASTM D523 proficiency testing and ISO 2813 operator certification programs lack capacity in Eastern European and Southeast Asian manufacturing hubs, slowing deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gloss Meters Market |
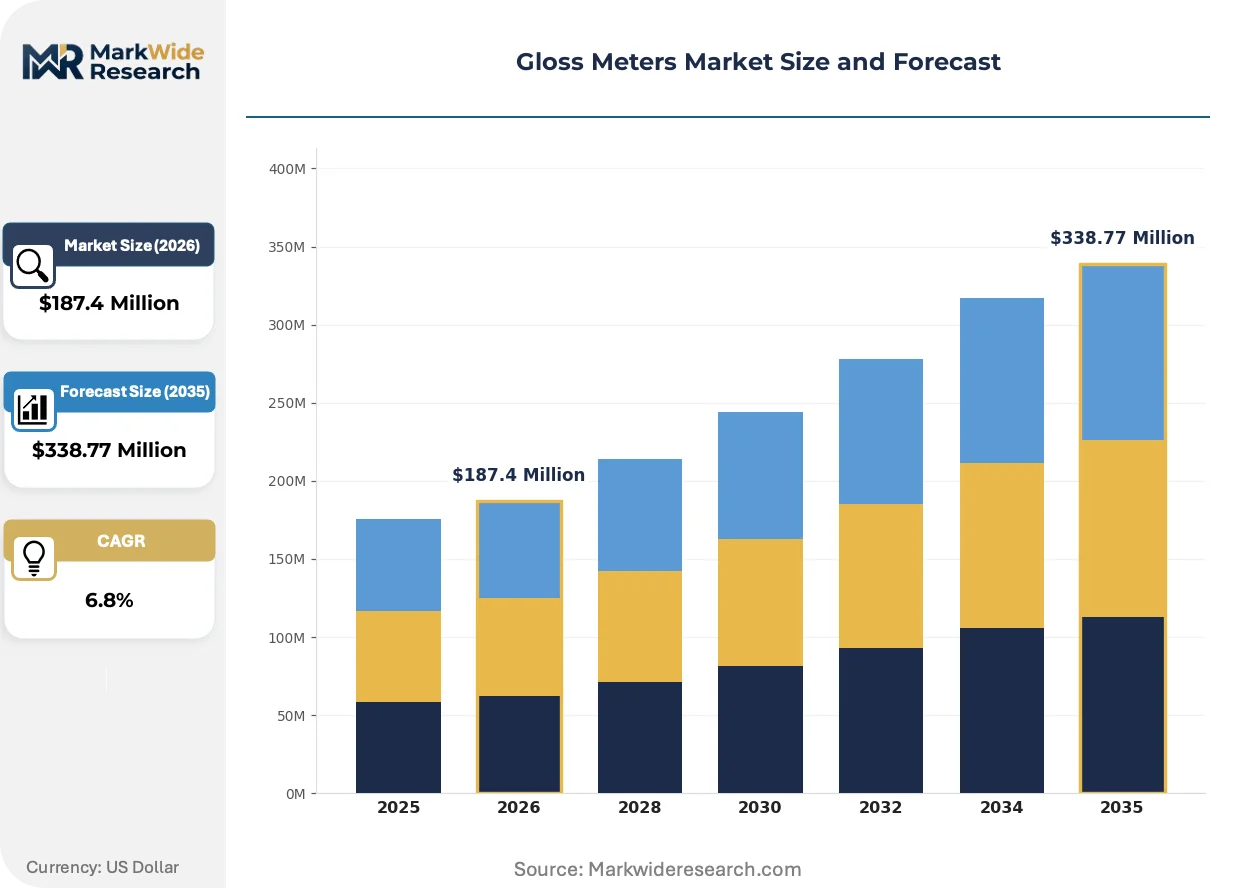
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Gloss Meter, Handheld Gloss Meter, Portable Gloss Meter, Benchtop Gloss Meter Technology: Optical, Digital, Laser, Spectrophotometric, Ultrasonic Application: Paints & Coatings, Plastics, Automotive OEMs, Textiles, Printing & Packaging End User: Quality Control Labs, Research Institutions, Manufacturing Plants, Calibration Services |
| Companies Covered | BYK Gardner, Elcometer, Konica Minolta, HORIBA, ElektroPhysik, TQC Sheen, Rhopoint Instruments, 3nh, Nippon Denshoku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gloss Meters Market Shifts & Advancements
Digital connectivity and multi-parameter sensing are collapsing the traditional boundary between plant-floor quality control and laboratory metrology, redrawing competitive terrain for instrument vendors.
Spectrophotometric gloss measurement is consolidating color, haze, and specular reflection into unified optical engines. Tier-one automotive suppliers in Stuttgart and Detroit are mandating these platforms for incoming coating inspection, compressing demand for standalone gloss-only devices. The technology is consolidating vendor relationships as buyers reduce supplier counts to simplify calibration chains.
REACH substance restrictions and the EU Green Deal's embodied carbon reporting requirements are forcing coating manufacturers to document surface finish stability across reformulated low-VOC chemistries. German automotive OEMs now require gloss retention data across accelerated weathering protocols, shifting instrument specifications toward extended measurement ranges. European protective coatings inspectors are responding by upgrading from 60°-only handheld units to triple-angle systems with onboard data logging.
Automotive procurement departments are unbundling instrument purchase from calibration service contracts, treating metrology as a recurring operational expense rather than capital equipment. Tier-two coating applicators in Ohio and Aichi Prefecture now lease gloss meters with guaranteed uptime SLAs, displacing traditional distributor sales models. This shift is most visible in North American collision repair networks where consolidated buying groups negotiate enterprise-wide instrument fleets.
Gloss Meters Market Segmentation
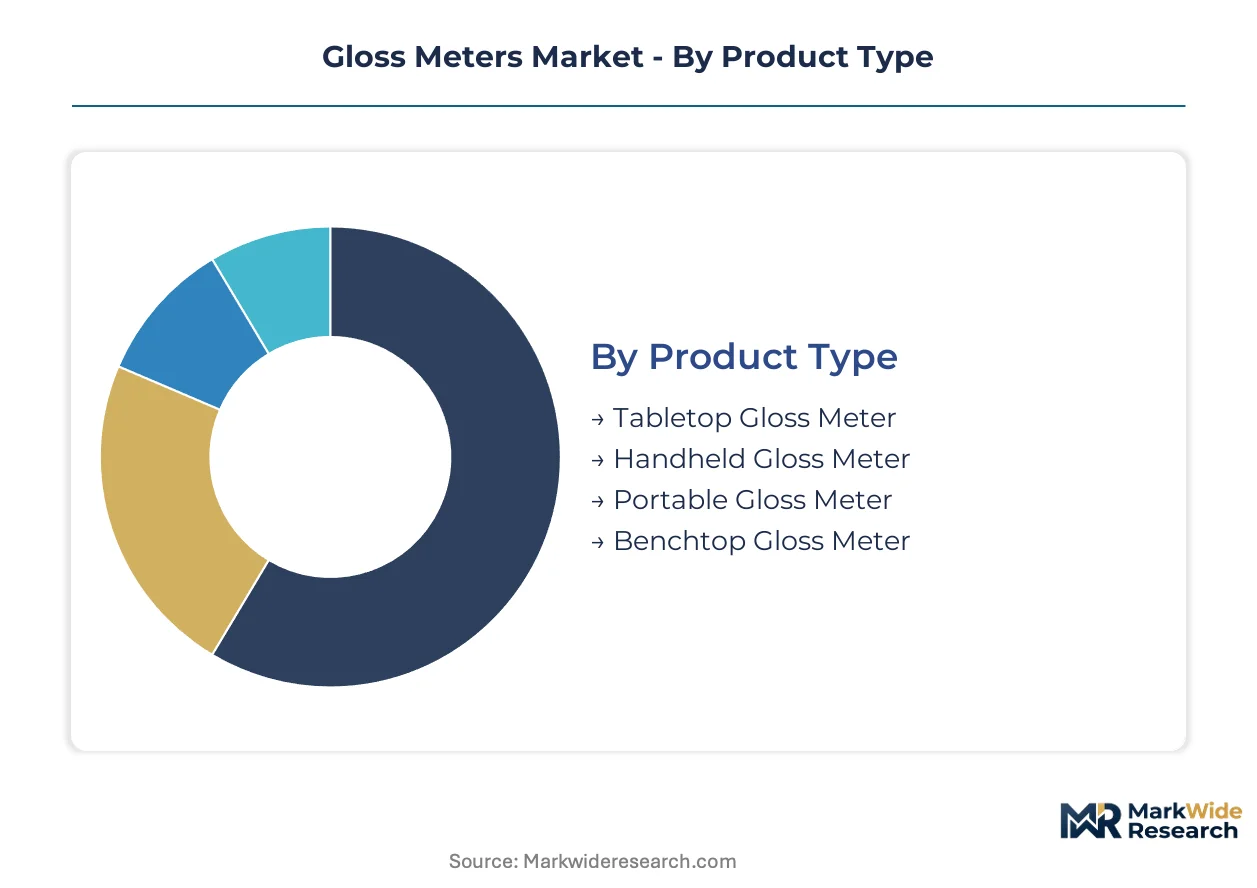
Segmentation in gloss meters reveals how measurement workflows fragment across factory floors, field sites, and controlled laboratories. Each category exposes different performance thresholds, connectivity requirements, and calibration burdens that reshape vendor priorities.
Product Type:
Handheld units dominate field verification where ISO 2813 compliance must travel to coating sites; benchtop systems anchor traceable measurement chains in fixed facilities.
- Handheld Gloss Meter:Battery-powered units with 20°/60°/85° geometry switching serve automotive OEM inspectors verifying body panels at assembly plants in Stuttgart and Detroit. German tier-one suppliers now mandate Bluetooth data logging for direct MES integration.
- Tabletop Gloss Meter:Laboratory-grade instruments with interferometer-stabilized optics anchor national metrology traceability chains. Japanese research institutions in Tsukuba cluster demand here for coating formulation R&D requiring ASTM D523 certification.
- Portable Gloss Meter:Mid-weight systems bridge field and lab with detachable measurement heads for protective coatings contractors. BIS-certified infrastructure projects in Mumbai drive procurement.
- Benchtop Gloss Meter:Fixed-installation units with environmental enclosures serve high-volume production lines. US automotive battery enclosure manufacturers specify these for 24/7 surface quality monitoring.
Handheld gloss meters lead volumes today; spectrophotometric-integrated portable units are gaining share fastest.
Technology:
Technology tiers separate legacy analog readouts from connected digital platforms and multi-parameter optical engines that collapse instrument counts.
- Spectrophotometric:Unified optical engines measure color, gloss, and haze through single apertures. REACH-compliant coating formulators in Germany adopt these to consolidate capital expenditure and simplify calibration chains.
- Digital:Microprocessor-controlled units with onboard storage and USB/Bluetooth outputs displace analog devices. US collision repair networks deploy these for EPA-compliant coating documentation.
- Optical:Conventional photodiode-based systems at fixed geometries serve price-sensitive protective coatings inspectors in emerging markets.
- Laser:Coherent light sources enable non-contact measurement of wet coatings and curved surfaces. Japanese automotive OEMs evaluate these for inline battery enclosure inspection.
- Ultrasonic:Alternative physics for specialized substrates where optical interference corrupts readings. Niche adoption in textured plastics quality control.
Digital platforms command the broadest installed base; spectrophotometric systems show the steepest expansion trajectory.
Application:
Application segments align with coating chemistry evolution, automotive electrification mandates, and packaging regulatory tightening.
- Automotive OEMs:EV body panels and battery enclosures require multi-angle gloss documentation under tightening surface quality mandates. German manufacturers specify 20° high-gloss and 85° matte measurements for unified appearance standards.
- Paints & Coatings:Industrial and decorative coating formulators need batch-to-batch consistency verification. REACH substance restrictions force reformulation cycles that demand accelerated weathering gloss retention data.
- Plastics:Injection molders and extruders verify surface finish for consumer electronics housings and automotive interior trim. Japanese suppliers lead in high-gloss black panel measurement.
- Printing & Packaging:FDA medical device packaging and food contact materials require documented surface finish stability. US converters face inspection intensity from EPA corrosion-resistant coating rules.
- Textiles:Synthetic leather and coated fabric manufacturers measure specular reflection for automotive seating and fashion applications. Smaller addressable volume with specialized geometry requirements.
Paints and coatings anchor current demand; automotive OEM applications are climbing the fastest.
End User:
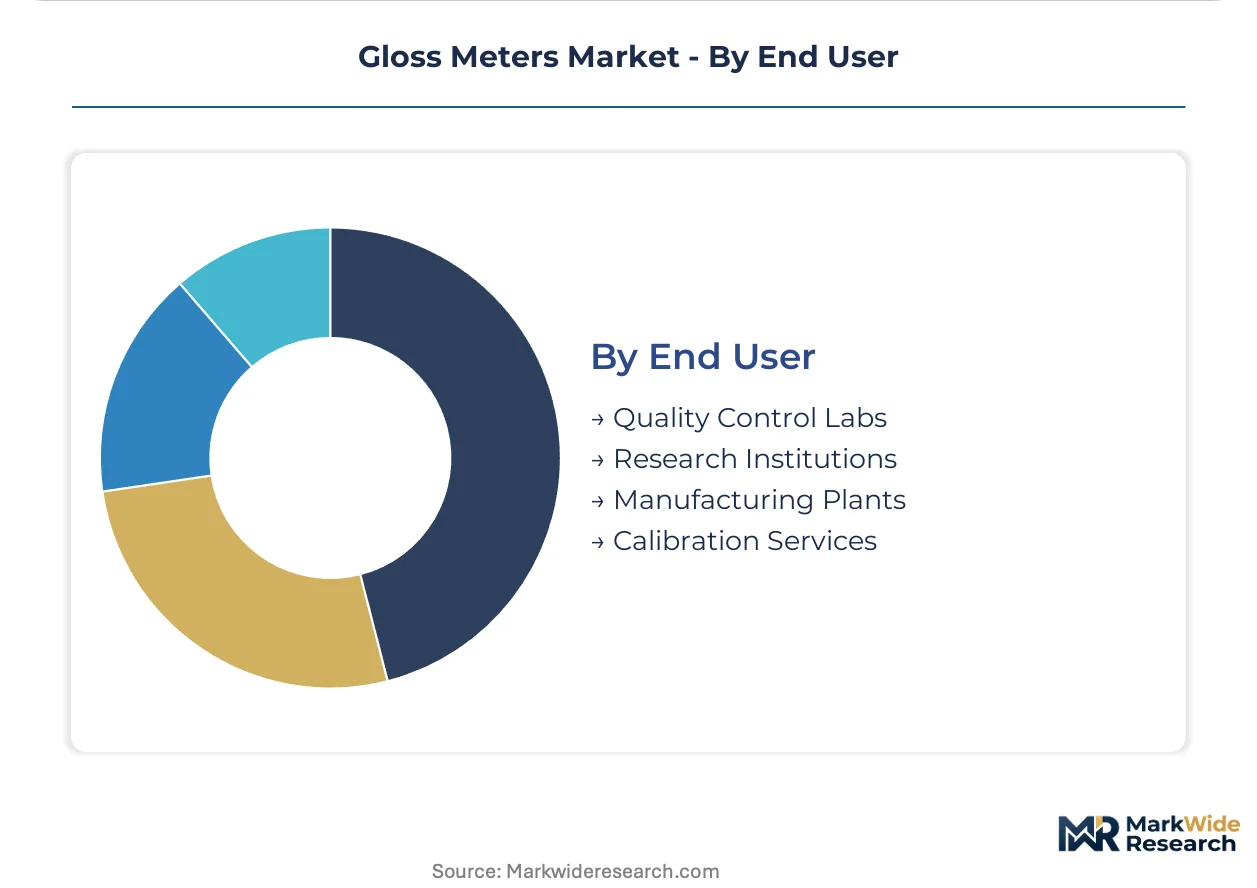
End user categories reflect capital intensity splits between operational quality control and research-grade metrology investment.
- Quality Control Labs:In-house testing facilities at coating manufacturers and automotive tier-one suppliers perform incoming inspection and batch release. ISO 17025 traceability requirements dominate procurement specifications.
- Manufacturing Plants:Plant-floor deployment for inline and at-line verification drives volume shipments. US and German automotive assembly plants standardize on handheld fleet models with enterprise calibration contracts.
- Research Institutions:National metrology institutes and university coating science programs require extended measurement ranges and custom geometry configurations. Calibration backlog at NIST and PTB delays procurement cycles.
- Calibration Services:Third-party metrology providers maintain reference standards and perform field certification. Emerging in India alongside BIS infrastructure buildout.
Manufacturing plants generate the highest unit volumes; quality control labs deliver the strongest margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision metrology talent clusters in Stuttgart, Detroit, and Nagoya anchor demand for surface quality verification instruments. These engineering concentrations drive specification-setting for coating inspection protocols across automotive supply chains.
Germany
Automotive OEM surface quality mandates from KBA and EU Green Deal embodied carbon reporting pull demand for triple-angle gloss documentation. REACH substance restrictions force coating reformulation cycles requiring extended measurement ranges. Stuttgart and Wolfsburg host tier-one supplier networks standardizing on Bluetooth-enabled handheld fleets.
United States
EPA corrosion-resistant coating rules and FDA medical device packaging requirements tighten surface finish documentation. NIST calibration backlogs delay new product launches by 12-18 months. Michigan and Ohio automotive battery enclosure manufacturers specify benchtop systems for 24/7 quality monitoring.
Japan
METI industrial standards and JIS certification protocols govern precision optical instrument specifications. PMDA medical device surface requirements extend into packaging materials. Tsukuba research institutions and Nagoya automotive clusters drive laboratory-grade tabletop demand for coating R&D.
India
BIS certification requirements for industrial coatings and PLI scheme incentives for domestic manufacturing create instrument demand clusters. CDSCO medical device packaging rules extend surface quality mandates. Mumbai and Chennai infrastructure buildouts drive protective coatings inspection procurement.
China
GB standards alignment with ISO 2813 and MIIT automotive quality mandates compress gloss tolerance bands. SAMR metrology framework enforcement tightens instrument certification. Yangtze River Delta coating formulators adopt spectrophotometric platforms to consolidate capital expenditure.
Gloss Meters Market Competitive Landscape
Top-tier vendors anchor reference standard setting, while mid-range specialists compete on price-to-performance recalibration. The vendor base stratifies across optical heritage groups, coating industry channel controllers, and colorimetry extenders. Three archetypes dominate: metrology standards custodians, protective coatings inspection specialists, and multi-parameter optical platform integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with cloud-connected service bundling displacing traditional distributor sales.
Among heritage metrology specialists, BYK Gardner and ElektroPhysik occupy positions as standards custodians with deep European coating industry roots. Elcometer exemplifies the protective coatings inspection archetype through channel control in corrosion-resistant applications. Konica Minolta and HORIBA sit within the optical platform integrator tier, extending colorimetry expertise into gloss measurement workflows. These five names represent the competitive core, with 3nh and Nippon Denshoku anchoring regional supply in Asian markets.
| Leading Market Players |
|---|
| BYK Gardner |
| Elcometer |
| Konica Minolta |
| HORIBA |
| ElektroPhysik |
| TQC Sheen |
| Rhopoint Instruments |
| 3nh |
| Nippon Denshoku |
| Others |
Supply & Pricing Matrix
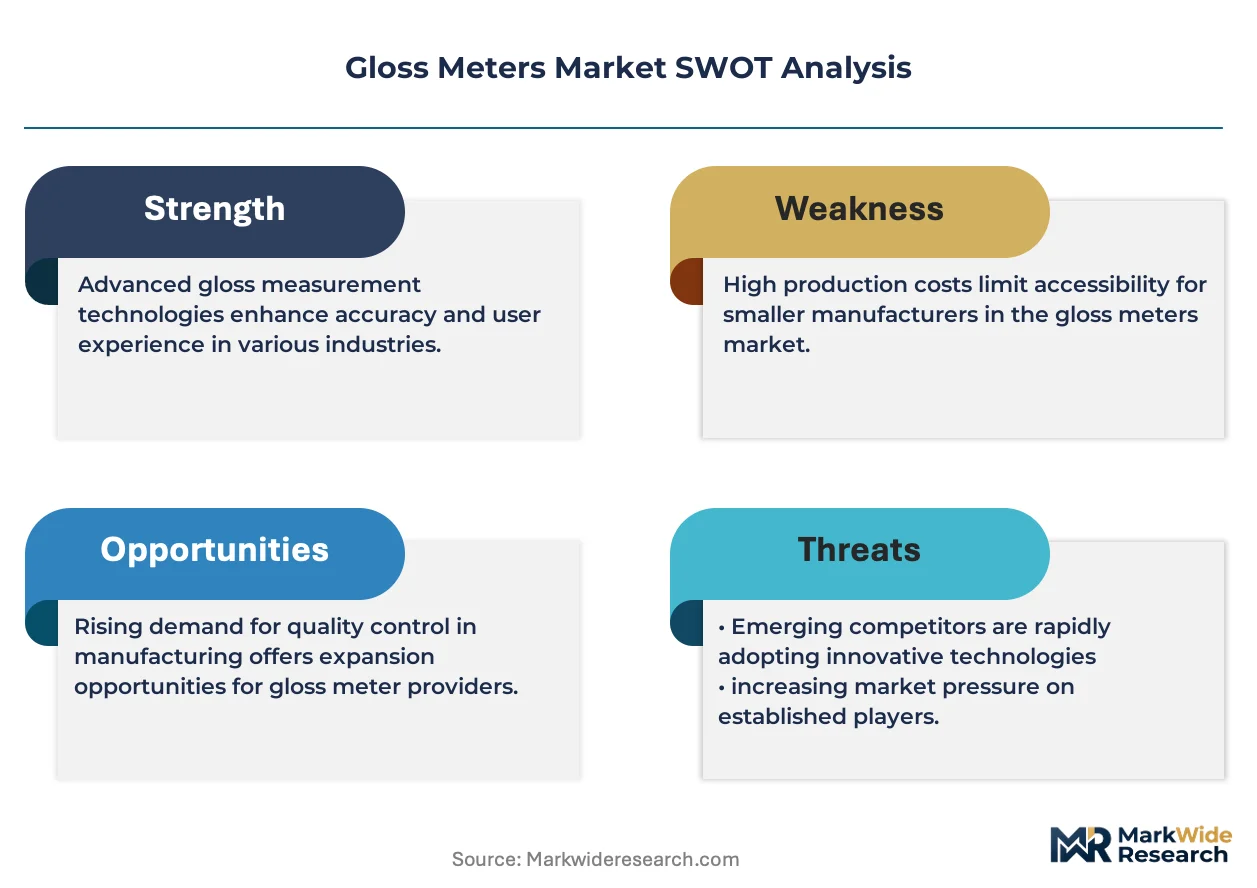
Automotive OEM unbundling of instrument purchase from calibration contracts is forcing vendors to restructure revenue models and absorb recurring service infrastructure costs. This procurement shift compresses upfront hardware margins while expanding lifetime value capture through subscription tiers.
Pricing Analysis
Bundled hardware-service contracts versus unbundled transactional sales now define the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified laboratory systems from Bluetooth-enabled field units and basic optical devices. Price differentiation rests on certification grade and after-sales calibration bundling. Cost compression in the economy tier is intensifying because smartphone-based visual tools erode entry-level demand. Protective coatings contractors in emerging markets exhibit the highest price sensitivity; research institutions purchasing interferometer-grade systems show the least.
Supply Chain Analysis
Precision interferometer-grade optics supply rests on German and Japanese specialty manufacturers. Gloss meter production draws from silicon photodiodes, stabilized light sources, and calibration reference tiles. German lens fabricators and Japanese optical component houses anchor upstream supply. Single-source vulnerability for mid-range instrument makers creates structural risk. Distribution runs through authorized metrology distributors and direct enterprise sales to automotive tier-one suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gloss Meters Market compounds steadily as automotive surface quality mandates tighten tolerance bands across coating supply chains. Regulatory documentation requirements create durable replacement demand.
For Market Incumbents: Lock in calibration service relationships before automotive procurement departments complete their shift to subscription models. Deepen backward integration into optical component supply to mitigate German and Japanese single-source exposure. BYK Gardner and Elcometer must anchor channel control in protective coatings inspection before cloud-native entrants capture fleet management contracts. For New Entrants and Emerging Players: The price-point gap between premium spectrophotometric platforms and economy handheld units offers white-space opportunity. Indian protective coatings infrastructure buildout around Mumbai and Chennai presents the most penetrable geography. Cloud-connected gloss meter-as-a-service models with blockchain-anchored audit trails provide a distinct go-to-market angle for penetrating automotive tier-one supplier networks. For Investors and Strategic Acquirers: Asymmetric upside sits with optical platform integrators extending colorimetry expertise into consolidated color-gloss-haze measurement. Five-to-ten year viability favors vendors mastering multi-parameter convergence and calibration chain simplification. Watch EU Battery Passport regulation implementation as the inflection signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Bundling | Subscription revenue models align with automotive procurement shifts toward operational expense treatment. |
| Spectrophotometric Platform Development | Unified optical engines collapse capital expenditure thresholds for REACH-compliant coating formulators in Germany. |
| Cloud-Connected Fleet Management | Blockchain-anchored audit trails penetrate automotive tier-one supplier networks requiring CSRD-linked documentation. |
| Indian Market Channel Establishment | BIS certification requirements and PLI scheme incentives create instrument demand clusters around Mumbai and Chennai. |
| Optical Component Supply Security | Backward integration into interferometer-grade optics mitigates single-source vulnerability from German and Japanese suppliers. |
Research Methodology
Coverage spans Germany, Japan, the United States, India, and China, with primary inputs from each market. The analysis combines interviews with quality control lab managers, automotive tier-one procurement officers, protective coatings contractors, and calibration service providers. Secondary validation draws from ISO 2813 documentation, ASTM D523 standards filings, EPA corrosion-resistant coating rules, and REACH substance restriction databases. Bottom-up shipment estimates and top-down market sizing triangulate to produce segment-level outputs.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions include product type, technology tier, application vertical, and end-user capital intensity. CAGRs derive from fitted growth curves against historical adoption patterns and regulatory mandate timelines. Automotive OEM surface quality specifications and EV battery enclosure standards serve as industry-specific forecast inputs.
Caveats apply where NIST and PTB calibration backlogs could materially shift the outlook for new product launch timelines. Forecasts reflect assumptions about ISO 17025 traceability requirement persistence and REACH compliance deadline adherence. A small set of named triggers—EU Battery Passport final rules, BIS infrastructure certification acceleration, and spectrophotometric platform price erosion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Video Extensometers Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Metrology and Inspection Equipment Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Test and Measurement Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Fluorometers Market
Test and Measurement
Tribometer Market
Test and Measurement
Continuous Friction Tester Market