
 Digital Video Extensometers Market | 2026-2036
Digital Video Extensometers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Video Extensometers Market Insights
ISO 9513 calibration certification is reorganizing competitive access in digital video extensometry, raising barriers for instrument suppliers without accredited metrology laboratories. Zwick Roell leverages its German testing heritage to sustain dominance in European aerospace qualification workflows. Instron anchors North American demand through deep integration with universal testing machine platforms. MTS competes in high-frequency dynamic applications where servo-hydraulic systems pair with optical strain verification.
Digital video extensometers are non-contact optical instruments that measure material deformation by tracking surface markers through high-resolution camera systems, typically achieving gauge-length resolutions below one micron for tensile, compression, and fatigue testing protocols. Their primary purpose is eliminating mechanical contact errors in strain measurement for advanced alloys, composites, and polymers. Desktop systems occupy the largest installed base in materials research laboratories, while multi-axis configurations represent the fastest-growing segment as biaxial and full-field strain analysis displace single-channel methods in automotive crash-simulation validation. Software integration capabilities now determine margin pools, with vendors bundling real-time DIC correlation engines and LIMS connectivity to defend pricing against portable entry-level alternatives.
ISO, the FDA's 21 CFR Part 11 framework for electronic records, and Germany's DAkkS accreditation system collectively shape instrument procurement criteria, validation protocols, and cross-border market access for suppliers. The FDA's emphasis on data integrity in pharmaceutical device testing funnels demand toward systems with embedded audit trails and encrypted measurement chains. Stakeholders must monitor how AI-enabled image processing algorithms challenge existing calibration paradigms and whether regulatory bodies will mandate new verification standards for machine-learning-assisted strain extraction.
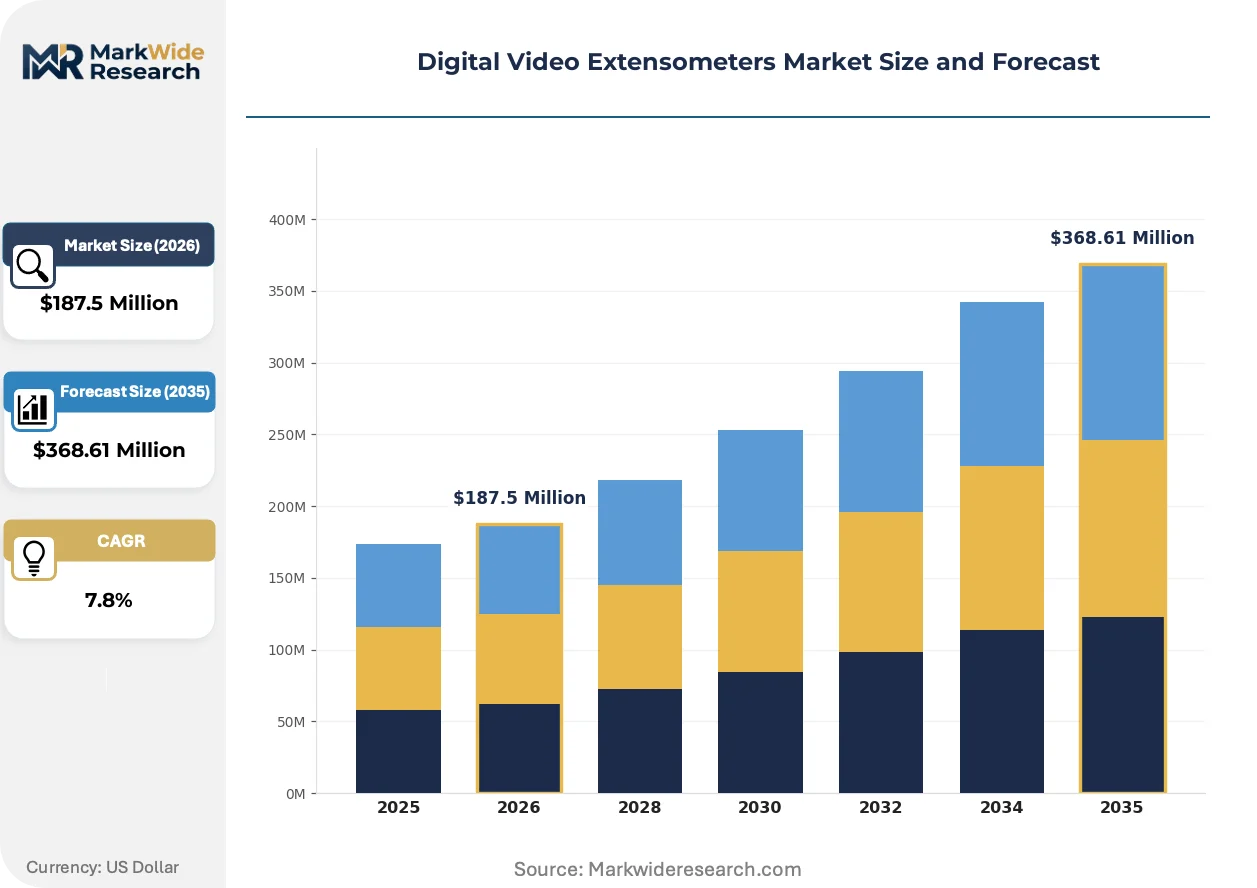
Market Dynamics
ISO 9513 calibration certification is reorganizing competitive access in digital video extensometry, raising barriers for instrument suppliers without accredited metrology laboratories and compressing margin pools for uncertified entrants.
Growth Catalysts
- NADCAP accreditation requirements:Aerospace manufacturers in Germany and the United States are expanding adoption of non-contact strain measurement systems to meet fatigue testing standards. This pulls demand toward certified optical extensometry in qualification workflows.
- Automotive OEM integration:Germany's automotive testing corridor around Stuttgart and Munich concentrates demand where manufacturers integrate optical extensometry into production quality loops for advanced alloys and composites.
- AI-enabled image processing:Machine-learning-assisted strain extraction algorithms are challenging existing calibration paradigms and creating new performance tiers in materials research applications.
Market Restraints
- Metrology laboratory concentration:ISO 9513 calibration infrastructure concentrates in Germany, the United States, and Japan, limiting supplier access for emerging market entrants lacking accredited facilities.
- High-resolution camera input costs:Specialized imaging sensors and precision optics create fixed cost barriers that scale poorly for portable entry-level system manufacturers.
- Mechanical extensometer substitution:Legacy contact-based strain measurement retains cost advantages in low-precision metals testing and educational laboratory settings.
Strategic Opportunities
- Biaxial and full-field strain analysis:Multi-axis configurations represent white space as automotive crash-simulation validation displaces single-channel methods in Germany and Japan.
- India's materials research expansion:Underpenetrated laboratory infrastructure and BIS standards alignment create entry paths for certified suppliers establishing local calibration partnerships.
- Real-time DIC-LIMS bundling:Software integration capabilities determine margin pools, with vendors embedding digital image correlation engines and laboratory information management connectivity to defend pricing.
Industry Challenges
- Machine-learning calibration verification:Regulatory bodies have not mandated new standards for AI-assisted strain extraction, creating uncertainty in validation protocols for pharmaceutical device testing under FDA 21 CFR Part 11.
- Cross-border DAkkS-FDA alignment:Germany's accreditation system and US electronic records frameworks impose divergent audit trail requirements, complicating instrument procurement for multinational testing laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Video Extensometers Market |
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $368.61 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Desktop, High-Precision, Multi-Axis Application: Material Testing, Structural Analysis, Manufacturing Quality Control, Research & Development End User: Aerospace, Automotive, Civil Engineering, Education Technology: Optical Measurement, Image Processing, Software Integration, Automated Systems |
| Companies Covered | Zwick Roell, Instron, Ametek, Shimadzu, MTS, Imetrum, Epsilon Tech, BESMAK, Qualitest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Video Extensometers Market Trends and Innovations
Digital video extensometry is actively splitting between high-end multi-axis research systems and streamlined portable units, with software-defined functionality replacing hardware differentiation as the primary value driver.
Multi-camera stereo-vision systems with sub-micron gauge-length resolution are bifurcating the installed base. Aerospace qualification laboratories in Germany and the United States adopt these configurations for fatigue testing protocols. Single-camera desktop units are compressing into price-sensitive materials education markets where mechanical extensometers previously dominated.
REACH substance restrictions and EU AI Act transparency requirements are reshaping instrument procurement in European automotive testing. Manufacturers must now document algorithmic decision pathways in strain measurement software. German OEMs are responding by demanding embedded audit trails and encrypted measurement chains from suppliers.
After-sales service unbundling is disrupting traditional capital equipment sales in North American research institutions. Universities and national laboratories now procure calibration contracts and software subscriptions separately from hardware. This pattern concentrates in US materials science departments facing compressed capital budgets and extended replacement cycles.
Digital Video Extensometers Market Segmentation
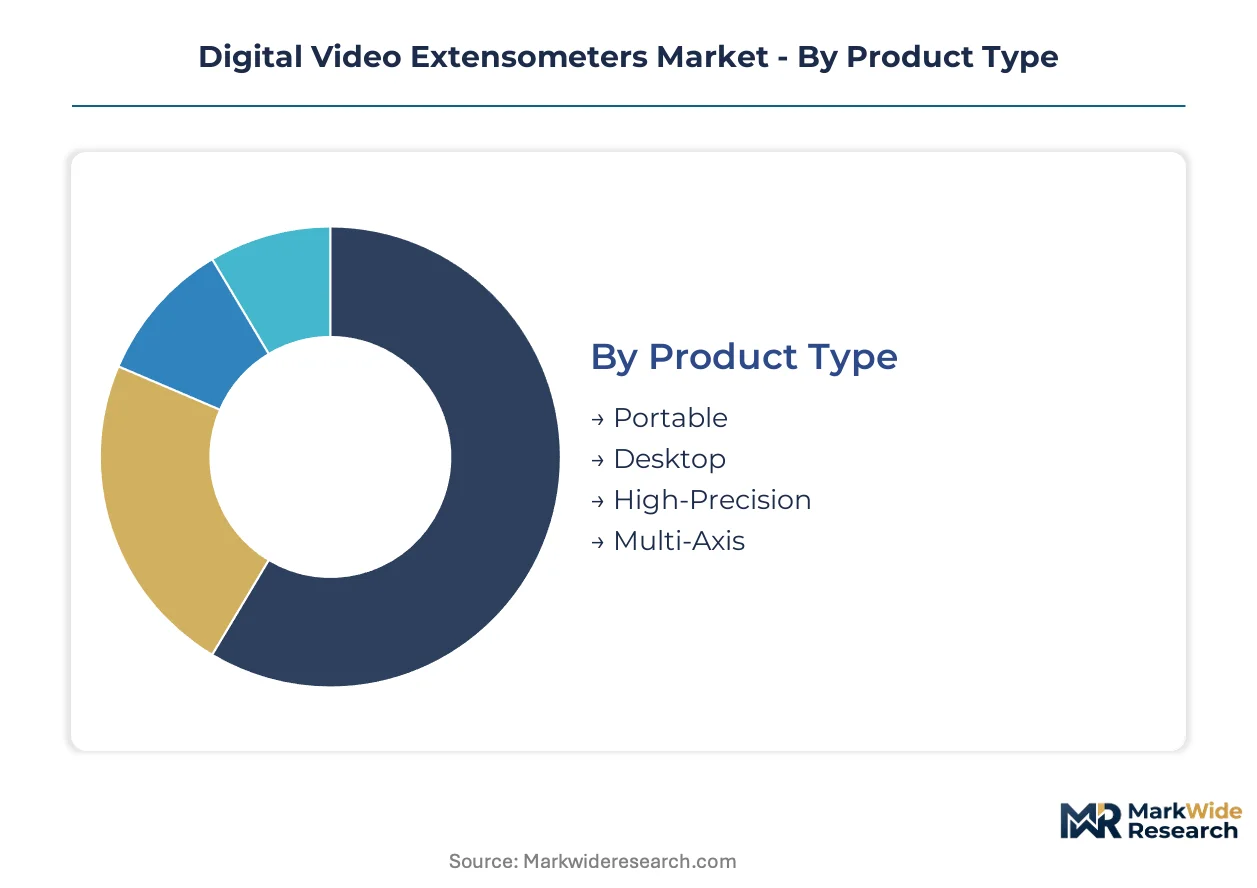
Digital video extensometer procurement patterns diverge sharply between contact-based substitutes and non-contact optical systems. Substitution pressure from legacy mechanical extensometers compresses margins in lower-resolution segments while driving premiumization in certified optical configurations.
Product Type:
Portable and desktop configurations face the most intense substitution pressure from mechanical extensometers in educational and low-precision metals testing environments.
- Portable:Battery-powered units with single-camera architectures target field inspections and on-site structural assessments. German automotive suppliers around Stuttgart deploy these for production-floor quality loops where mobility outweighs resolution requirements. Demand concentrates in cost-sensitive materials education markets where mechanical extensometers previously dominated.
- Desktop:Fixed-installation systems with sub-micron gauge-length resolution occupy the largest installed base in materials research laboratories. Aerospace qualification workflows in Germany and the United States pull demand toward these configurations for NADCAP-compliant fatigue testing protocols.
- High-Precision:Specialized configurations achieving resolutions below 0.5 micron for advanced alloy characterization.
- Multi-Axis:Stereo-vision architectures enabling biaxial and full-field strain analysis for automotive crash-simulation validation.
Desktop systems anchor the volume base while multi-axis configurations gain share at the steepest rate.
Application:
Cost tier stratification separates research-grade specifications from production-floor durability requirements across application categories.
- Material Testing:Tensile, compression, and fatigue protocols for metals, composites, and polymers. German OEMs in Munich integrate optical extensometry into qualification workflows for advanced alloys, pulling demand toward ISO 9513-certified systems.
- Structural Analysis:Full-field deformation mapping for civil infrastructure and aerospace components. Bridge monitoring applications in Japan and Germany drive adoption of multi-camera configurations with environmental sealing.
- Manufacturing Quality Control:Real-time strain verification integrated into production lines. Cost pressure from mechanical extensometer substitutes limits penetration in low-margin metals processing.
- Research & Development:Algorithm development and calibration methodology advancement in national laboratories. US materials science departments facing compressed capital budgets now unbundle hardware from software subscriptions.
Material testing commands the deepest installed base while structural analysis applications expand most quickly.
End User:
Customer type determines procurement authority structure, with aerospace and automotive segments demanding embedded audit trails and encrypted measurement chains.
- Aerospace:Fatigue testing laboratories requiring NADCAP accreditation for supplier qualification. German and US manufacturers expand optical extensometry adoption to meet non-contact strain measurement standards.
- Automotive:Crash-simulation validation and production quality loops. Stuttgart and Munich corridor OEMs integrate multi-axis systems for biaxial strain analysis in composite component development.
- Civil Engineering:Structural health monitoring and infrastructure assessment. Demand concentrates in Japan and Germany for seismic-resistant design validation.
- Education:University materials science laboratories with constrained capital budgets. Mechanical extensometer substitution pressure peaks in this segment.
Aerospace end users anchor the revenue base while automotive applications climb the fastest.
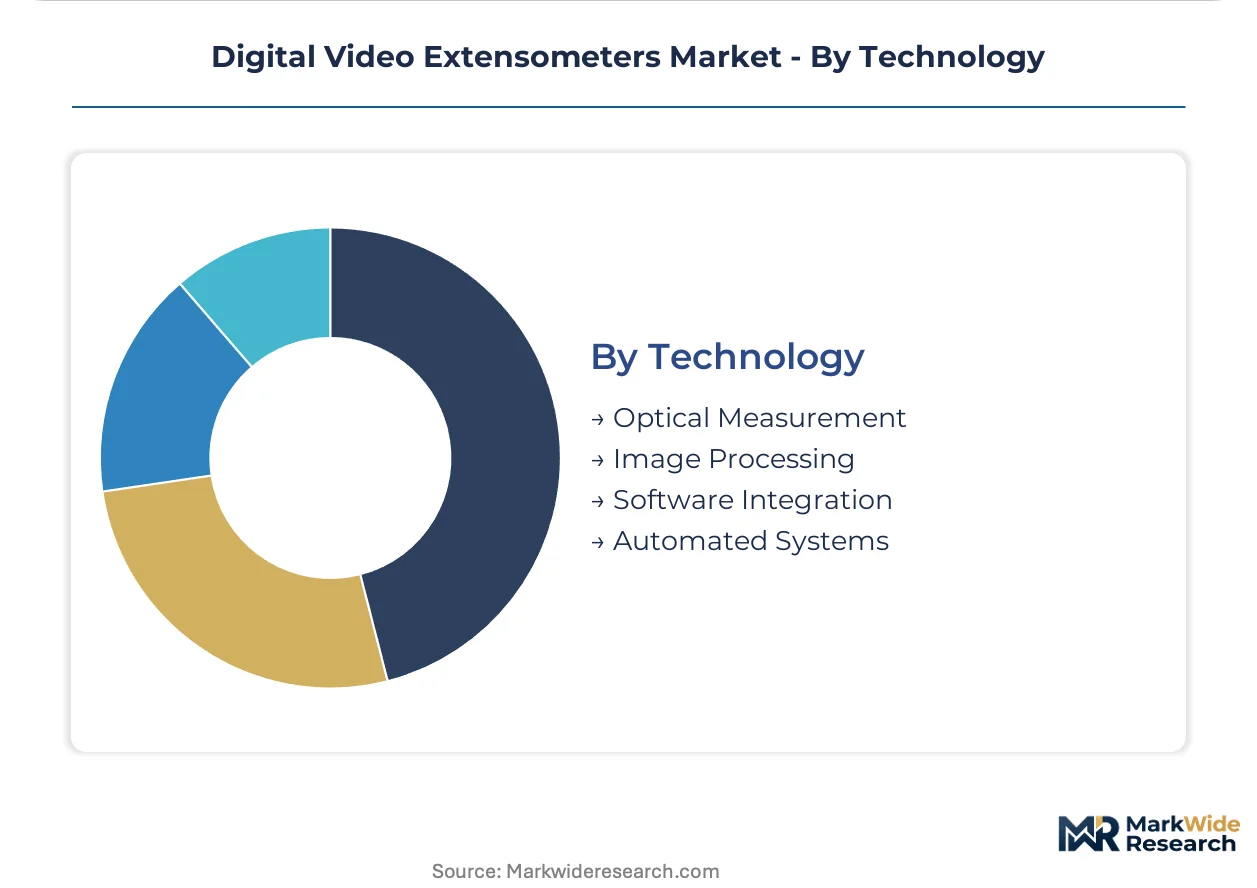
Technology:
Supply concentration in high-resolution camera sensors and precision optics shapes competitive access across technology categories.
- Optical Measurement:Camera-based surface marker tracking with stereo-vision triangulation. Sub-micron resolution capabilities differentiate premium configurations from portable alternatives.
- Image Processing:Real-time digital image correlation engines for strain field computation. AI-enabled algorithms challenge existing ISO 9513 calibration paradigms.
- Software Integration:LIMS connectivity and embedded audit trails for FDA 21 CFR Part 11 compliance. Margin pools concentrate in bundled offerings defending against entry-level portable competition.
- Automated Systems:Robotic specimen handling and unattended testing protocols. Integration with servo-hydraulic test frames from MTS and Instron creates platform lock-in effects.
Optical measurement underpins the technology foundation while software integration capabilities determine margin differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate in aerospace qualification laboratories and automotive OEM testing facilities, with procurement authority residing in NADCAP-accredited facilities and production-integrated quality loops rather than distributed research institutions.
United States
FAA certification requirements and NADCAP fatigue testing standards pull demand toward non-contact optical extensometry in aerospace manufacturing clusters. FDA's 21 CFR Part 11 framework mandates encrypted measurement chains and embedded audit trails for pharmaceutical device testing. Greater Boston and Pacific Northwest research corridors anchor adoption, where national laboratories unbundle hardware procurement from software subscriptions.
Germany
DAkkS accreditation and REACH substance restrictions reshape instrument procurement for automotive and aerospace applications. KBA type-approval processes for vehicle safety components integrate optical extensometry into crash-simulation validation. The Stuttgart-Munich automotive testing corridor concentrates OEM demand, with manufacturers embedding multi-axis systems into production quality loops for advanced alloy characterization.
Japan
METI industrial standards and JIS calibration protocols drive adoption in materials research and seismic-resistant structural validation. Bridge monitoring applications in Kanto and Kansai regions deploy multi-camera configurations with environmental sealing for civil infrastructure assessment. Tokyo-Osaka research institutions anchor the installed base in fatigue testing protocols for automotive and aerospace suppliers.
China
GB standards alignment and MIIT equipment certification create procurement pathways for imported optical measurement systems. Dual carbon goals accelerate materials research investment in advanced alloys and composites for lightweighting applications. Yangtze River Delta manufacturing clusters integrate video extensometry into quality control workflows for export-oriented automotive and electronics production.
India
BIS standards harmonization and PLI scheme incentives for advanced manufacturing create entry opportunities for certified instrument suppliers. CDSCO medical device testing requirements funnel demand toward systems with validated data integrity protocols. Maharashtra and Gujarat industrial corridors host emerging materials research infrastructure where local calibration partnerships determine competitive access.
Digital Video Extensometers Market Competitive Landscape
Player mix skews toward heritage testing equipment manufacturers with accredited metrology laboratories and software-integrated platform providers. Market structure exhibits tiered concentration, with premium-tier vendors bundling real-time DIC engines and LIMS connectivity against portable entry-level alternatives. Two strategic archetypes dominate: German-engineered precision instrument specialists and North American universal testing machine platform integrators. Competitive moves center on ISO 9513 calibration infrastructure expansion and after-sales service unbundling for research institution budget cycles.
Within the heritage precision tier, Zwick Roell leverages its German testing heritage to sustain positioning in European aerospace qualification workflows. Instron anchors North American demand through deep integration with universal testing machine platforms. MTS occupies the high-frequency dynamic applications segment where servo-hydraulic system pairing creates platform lock-in effects. These three exemplify how calibration accreditation and software bundling determine margin differentiation against uncertified portable entrants.
| Leading Market Players |
|---|
| Zwick Roell |
| Instron |
| Ametek |
| Shimadzu |
| MTS |
| Imetrum |
| Epsilon Tech |
| BESMAK |
| Qualitest |
| Others |
Pricing and Supply Chain Analysis
Long-term calibration service contracts lock in both supply access and price visibility for aerospace qualification laboratories in Germany and the United States, compressing margin flexibility for instrument suppliers without DAkkS or NADCAP-accredited metrology infrastructure.
Pricing Analysis
Cost-plus contracts with sensor cost indexation dominate procurement for high-resolution camera modules and precision optics. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9513-certified desktop systems from portable entry-level alternatives and multi-axis research configurations. Pricing pressure stems from mechanical extensometer substitution in educational markets where budget constraints override resolution requirements. University materials science departments exhibit highest price sensitivity, while NADCAP-accredited aerospace laboratories prioritize certification compliance over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites precision optics supply chains serving German and Japanese instrument manufacturers, creating vulnerability to maritime disruption. High-resolution CMOS sensors concentrate in Japan, South Korea, and Taiwan, while precision lens grinding clusters in Germany and Switzerland. Supply chain risk centers on single-source dependency for sub-micron gauge-length calibration artifacts. Distribution runs through authorized metrology service partners with DAkkS or A2LA accreditation, limiting direct manufacturer access to end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital video extensometer market sits in early-cycle expansion as automotive OEMs embed optical strain measurement into production quality loops, with biaxial and full-field analysis displacing legacy single-channel methods.
For Market Incumbents: Compound calibration infrastructure advantage by expanding DAkkS-accredited laboratory partnerships in Maharashtra and Gujarat industrial corridors. Defend margin pools through real-time DIC-LIMS bundling that portable entrants cannot replicate. Mechanical extensometer price erosion in education markets demands selective withdrawal from unprofitable segments.
For New Entrants and Emerging Players: Differentiate on AI-enabled image processing algorithms that challenge ISO 9513 calibration paradigms, creating performance tiers unaddressed by heritage vendors. India's underpenetrated materials research infrastructure offers the most penetrable geography, with CDSCO medical device testing requirements funneling demand toward validated data integrity protocols. Pursue local calibration joint ventures as the essential go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward software-integrated platform providers with embedded audit trail capabilities for FDA 21 CFR Part 11 compliance. Long-term viability over a multi-year window favors vendors bundling digital image correlation engines with laboratory information management connectivity. Watch regulatory mandating of machine-learning verification standards as the critical inflection signal for AI-assisted strain extraction technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | DAkkS-accredited laboratory partnerships in India unlock access to CDSCO-compliant medical device testing workflows. |
| Real-Time DIC Engine Integration | Embedded digital image correlation software defends pricing against portable entry-level alternatives in materials education markets. |
| Multi-Axis System Development | Stereo-vision architectures capture automotive crash-simulation validation demand from Stuttgart and Munich corridor OEMs. |
| After-Sales Service Unbundling | Separate calibration contracts and software subscriptions align with compressed capital budgets at US national laboratories. |
| AI-Assisted Strain Extraction R&D | Machine-learning algorithms challenge existing ISO 9513 paradigms, creating new performance tiers ahead of regulatory verification mandates. |
Research Methodology
A standing panel of aerospace qualification engineers, automotive testing laboratory managers, metrology service technicians, and university materials science department heads provided ongoing calibration for demand assumptions and technology adoption timelines. Primary fieldwork combined structured interviews with instrument procurement officers at NADCAP-accredited facilities and secondary validation against FDA 21 CFR Part 11 guidance documents, DAkkS accreditation registers, ISO 9513 calibration standards, and customs trade data for high-resolution camera sensor imports. Bottom-up installed base estimates triangulated against top-down market sizing from universal testing machine platform shipments.
Consistency checks validated volume and value outputs against aerospace manufacturing cluster expansion rates and automotive OEM R&D expenditure patterns across the projection horizon. Segmentation modeling incorporated product type, application protocol, end-user industry, and technology architecture dimensions. CAGRs derived from historical replacement cycles for mechanical extensometers and penetration curves for optical substitution in fatigue testing workflows. Industry-specific inputs included NADCAP audit frequency trends and REACH substance restriction compliance costs.
The analysis sits within stated boundaries; outcomes outside sustained aerospace qualification demand and automotive lightweighting investment trajectories would require recalibration. Forecasts reflect documented assumptions regarding ISO 9513 certification expansion timelines and AI-enabled algorithm regulatory acceptance. Practitioners should keep alternative scenarios live as machine-learning verification standards and cross-border DAkkS-FDA alignment protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
India Electrical Testing Services Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Roughness Tester Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Hardware-Assisted Verification Market