
 RTD Cocktails Market | 2026-2036
RTD Cocktails Market Size, Share, and Industry Trends Forecast 2026-2036
RTD Cocktails Market Outlook
Supermarket shelf space allocation is rewriting competitive access rules for RTD cocktail brands. Bacardi Limited leverages its Caribbean rum heritage to anchor premium canned portfolios in Latin American and European retail chains. Diageo plc competes through global distribution scale that sustains presence across multiple flavor and packaging tiers simultaneously. Suntory Global Spirits dominates Japanese convenience retail through localized formulations that navigate strict regional alcohol content caps.
RTD cocktails denote pre-mixed alcoholic beverages, typically formulated at 4-12% ABV, manufactured through batch blending, carbonation, and either tunnel pasteurization or cold-fill aseptic processing, then packaged for immediate consumption without bartender intervention. Canned cocktails lead volume due to aluminum recyclability and single-serve portability, while bottled variants command margin pools in gift and premium at-home occasions. Online retail channels represent the fastest-growing access point, though bars retain structural importance for trial and brand discovery.
The U.S. Alcohol and Tobacco Tax and Trade Bureau enforces formula approval and label accuracy requirements that determine which products enter interstate commerce. Japan's National Tax Agency governs liquor classification and tax tiers based on alcohol content and base spirit, directly shaping product architecture for brands targeting that market. The EU's Food Information to Consumers Regulation mandates detailed allergen and nutritional labeling that influences formulation decisions for export-bound producers. Stakeholders must monitor evolving container deposit schemes and single-use packaging restrictions across their priority geographies to anticipate cost and compliance shifts.
Market Dynamics
Supermarket shelf space allocation is rewriting competitive access rules for RTD cocktail brands, as aluminum can supply concentration and TTB formula approval bottlenecks force smaller entrants toward direct-to-consumer channels or regional retail partnerships.
Growth Catalysts
- Japan's liquor tax reforms:New ABV-based tier structures incentivize producers to optimize formulations for lower-tax brackets, expanding accessible price points in convenience retail.
- Carbonation and aseptic cold-fill processing:These technologies extend shelf stability without heat degradation of volatile flavor compounds, enabling cleaner ingredient labels.
- Millennial and Gen-Z cohorts:These demographics in the United States, United Kingdom, and Japan prioritize single-serve portability over traditional bottle formats, concentrating demand in canned portfolios.
Market Restraints
- Aluminum can supply concentration:North American can manufacturing capacity remains controlled by a tight supplier oligopoly, creating input bottlenecks during seasonal demand spikes.
- TTB interstate commerce requirements:Formula approval and label accuracy verification creates 90-180 day lead times that block rapid product iteration for new entrants.
- Wine and spirits home mixing:Low-cost substitute behavior persists among price-sensitive households, particularly in inflation-pressured European markets.
Strategic Opportunities
- Online retail channel expansion:E-commerce alcohol delivery platforms in the United States bypass traditional three-tier distribution constraints, opening direct consumer relationships.
- EU Food Information to Consumers Regulation alignment:Early compliance with allergen and nutritional labeling mandates positions exporters for seamless market entry as standards tighten.
- Low-ABV and zero-proof adjacent formulations:These variants capture occasion expansion beyond traditional alcohol consumption windows, appealing to wellness-oriented buyers.
Industry Challenges
- Flavor chemist and beverage formulation specialist scarcity:Talent gaps in alcohol-stable emulsion science delay product development cycles for mid-tier brands.
- Container deposit scheme fragmentation:Patchwork state-level requirements across the United States force SKUs with incompatible labeling and packaging specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTD Cocktails Market |
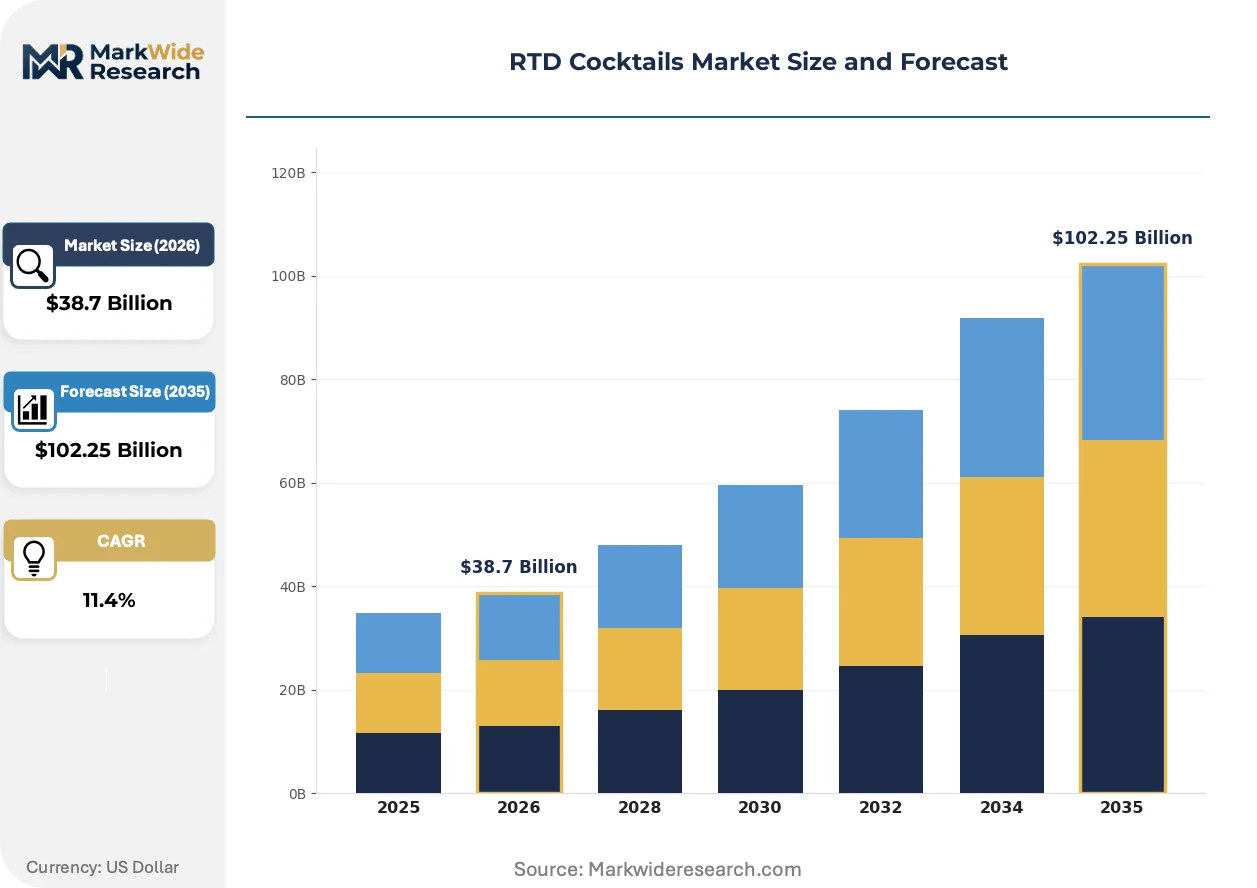
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Cocktails, Bottled Cocktails, Draft Cocktails, Wine-Based Cocktails Flavor Profile: Citrus, Berry, Tropical, Herbal Packaging Type: Glass, Plastic, Cans, Kegs Sales Channel: Supermarkets, Online Retail, Bars, Convenience Stores |
| Companies Covered | Bacardi Limited, Suntory Global Spirits, Diageo plc, Campari Group, Constellation Brands, Pernod Ricard, Brown-Forman Corporation, Asahi Breweries, Anheuser-Busch InBev, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTD Cocktails Market Strategic Shifts
Formulation science and packaging technology are compressing the traditional trade-off between shelf stability and ingredient transparency, while regulatory divergence across major markets forces parallel product architectures.
Aseptic cold-fill processing is collapsing the shelf-life gap between pasteurized and fresh-mix equivalents. Premium brands in the United States and Japan are adopting nitrogen-dosed canning lines that preserve volatile aromatic compounds without thermal degradation. This technology is collapsing the historical premium commanded by refrigerated fresh cocktails, forcing refrigerated case reset negotiations in upscale grocery.
The EU's Food Information to Consumers Regulation is mandating expanded allergen and nutritional disclosures that exceed TTB baseline requirements. Producers targeting European export must reformulate or dual-label, raising compliance costs. Brands with established EU-compliant portfolios are capturing shelf space as retailers reduce supplier complexity ahead of enforcement phase-ins.
Subscription-based curated cocktail boxes are displacing traditional trial purchases in urban United States markets. Younger consumers in New York and Los Angeles are prioritizing discovery experiences over brand loyalty, forcing legacy portfolios to unbundle variety packs. This behavior is most visible in the 25-34 demographic, where monthly subscription spend now rivals routine supermarket replenishment cycles.
RTD Cocktails Market Segmentation
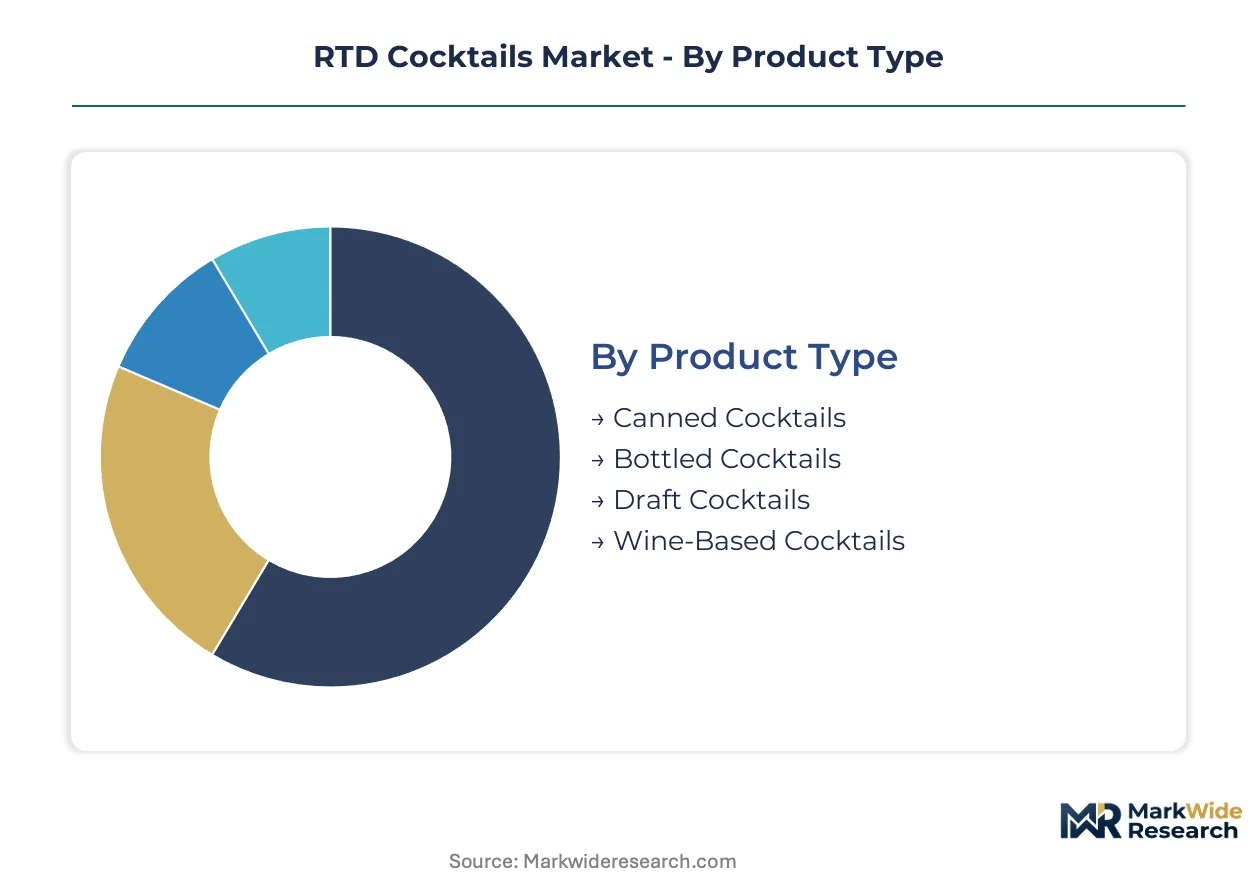
RTD cocktail segmentation reveals how packaging format, flavor architecture, and channel access determine margin capture. Producers must align production capabilities with the specific technical and regulatory demands of each segment cluster.
Product Type:
The use-case spectrum spans portable single-serve consumption through on-premise draft systems, with each format demanding distinct manufacturing infrastructure and distribution partnerships.
- Canned Cocktails:Aluminum vessels enable tunnel pasteurization and nitrogen dosing for extended shelf stability without flavor degradation. Demand concentrates in United States supermarket and convenience retail, driven by Millennial and Gen-Z preference for portable, recyclable single-serve formats.
- Bottled Cocktails:Glass packaging supports premium positioning through label real estate and perceived quality elevation. United Kingdom and Japanese consumers favor bottled variants for at-home entertaining and gift occasions, though higher shipping costs constrain e-commerce penetration.
- Draft Cocktails:Keg-based dispensing systems serve bars and restaurants seeking labor efficiency and portion consistency. The segment depends on cold-chain logistics partnerships and tap infrastructure investments by on-premise operators.
- Wine-Based Cocktails:Lower ABV formulations leverage wine tax classifications in certain jurisdictions to achieve price competitiveness. United States TTB formula approval requirements create distinct compliance pathways versus spirits-based alternatives.
The dominant share belongs to Canned Cocktails, while Draft Cocktails are closing the gap fastest through on-premise automation adoption.
Flavor Profile:
Cost tier differentiation separates mass-market accessible formulations from premium botanical complexity requiring specialized ingredient sourcing.
- Citrus:Lemon, lime, and grapefruit bases dominate volume through broad palate accessibility and cost-efficient natural flavor procurement. United States and United Kingdom retail shelves allocate disproportionate facing to citrus-forward portfolios.
- Berry:Raspberry, blackberry, and mixed berry formulations capture female-skewing demographics and seasonal summer demand spikes. Japanese convenience retail shows particular affinity for berry variants in lower-ABV tax-optimized formats.
- Tropical:Pineapple, coconut, and passionfruit profiles anchor vacation-occasion marketing and premium pricing. The segment requires stable emulsion chemistry to prevent oil separation in shelf-stable applications.
- Herbal:Botanical infusions including elderflower, lavender, and rosemary target wellness-oriented consumers seeking complexity without sweetness. Supply concentration in European botanical extract suppliers creates input cost volatility.
Citrus commands the volume base, though Herbal formulations are expanding most quickly through premium channel penetration.
Packaging Type:
Application requirements dictate material selection, with carbonation stability, light protection, and recycling infrastructure shaping regional preferences.
- Cans:Aluminum dominates RTD cocktail volume through infinite recyclability, lightweight logistics, and rapid chilling properties. North American can supply concentration creates procurement bottlenecks during peak summer demand.
- Glass:Amber and clear glass bottles serve premium positioning and wine-based formulations requiring UV protection. Higher weight increases freight costs and limits e-commerce viability.
- Plastic:PET and rPET formats enable shatter-resistant portability for outdoor and festival occasions. EU single-use packaging restrictions and container deposit schemes complicate multi-market deployment.
- Kegs:Stainless steel and disposable keg systems support draft cocktail programs in high-volume bars. The segment depends on cleaning and maintenance service infrastructure that concentrates in urban markets.
Cans hold the structural volume advantage, while Kegs are gaining share fastest through on-premise operational efficiency demands.
Sales Channel:
Customer type and purchase occasion separate routine replenishment from discovery-driven trial and immediate consumption needs.
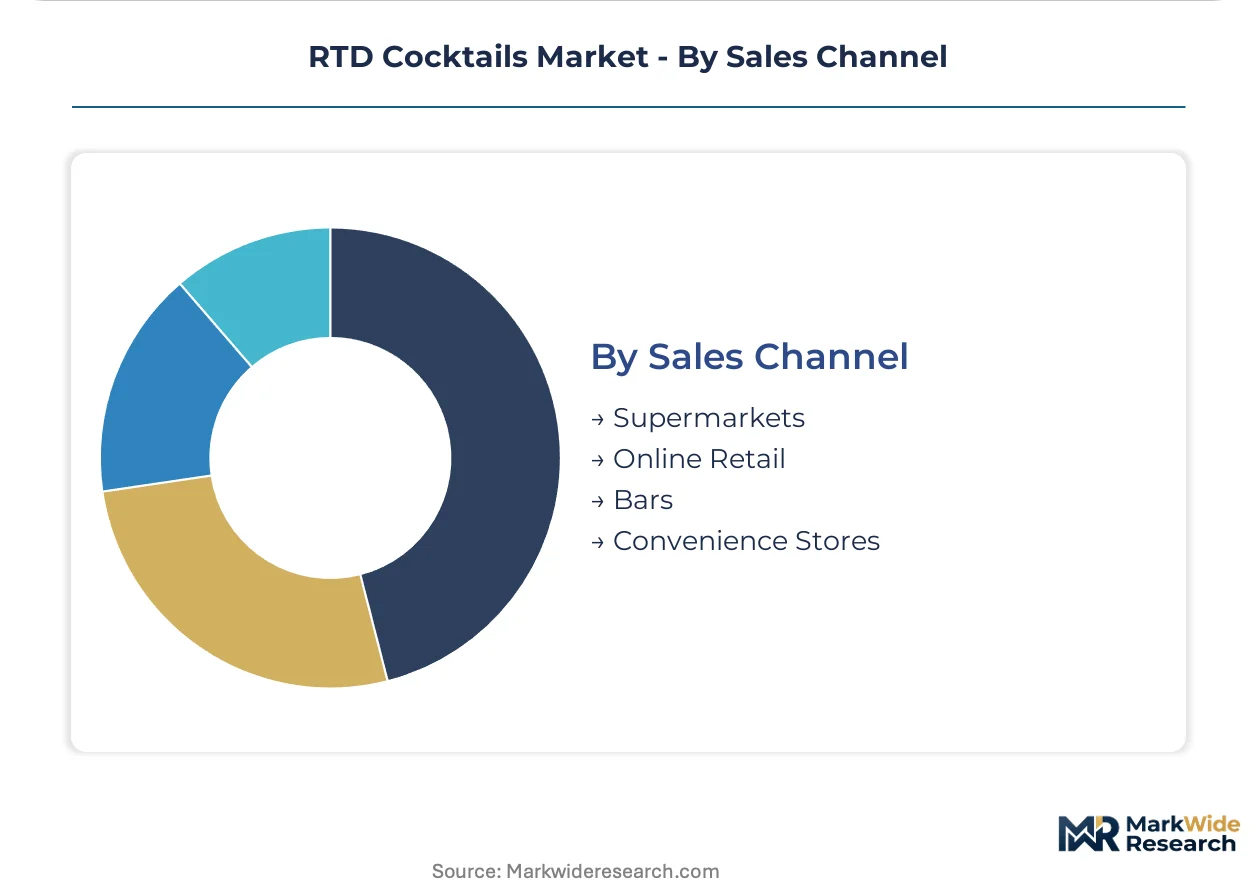
- Supermarkets:Grocery retail provides brand visibility and routine purchase integration with food shopping trips. United States and United Kingdom chains are reallocating shelf space toward RTD cocktails at the expense of beer and wine.
- Online Retail:E-commerce platforms bypass three-tier distribution constraints in the United States and enable subscription-based discovery models. Younger urban consumers in New York and Los Angeles prioritize curated variety packs over single-brand loyalty.
- Bars:On-premise trial remains critical for brand discovery and credibility establishment despite lower volume contribution. Japanese convenience retail integration blurs the bar-retail boundary through automated cocktail dispensers.
- Convenience Stores:Immediate consumption occasions and impulse purchase behavior drive placement in high-traffic urban locations. Suntory Global Spirits dominates Japanese convenience retail through localized formulations navigating strict ABV caps.
Supermarkets retain the dominant position, while Online Retail is climbing the fastest through regulatory arbitrage and direct consumer relationship building.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese convenience retail commands premium shelf placement fees that United States supermarkets cannot match, creating a pricing-power asymmetry that reshapes cross-border investment priorities. This divergence concentrates capital deployment toward regulatory-arbitrage opportunities in lower-tax ABV tiers.
United States
Millennial and Gen-Z consumers in New York and Los Angeles drive canned cocktail volume through subscription-based discovery platforms. The Alcohol and Tobacco Tax and Trade Bureau enforces 90-180 day formula approval timelines that block rapid product iteration. California's beverage formulation clusters in Los Angeles County anchor nitrogen-dosed canning line investments.
Japan
Convenience retail integration through automated cocktail dispensers blurs on-premise and off-premise boundaries in Tokyo and Osaka. The National Tax Agency's ABV-based liquor tax tiers incentivize producers to optimize formulations for lower-tax brackets. Suntory Global Spirits dominates Kanto region convenience stores through localized formulations navigating strict alcohol content caps.
United Kingdom
At-home entertaining occasions favor bottled variants in London and Southeast England, though higher shipping costs constrain e-commerce penetration. The Food Standards Agency implements allergen labeling requirements that exceed baseline TTB standards. Manchester and Birmingham retail chains are reallocating shelf space toward RTD cocktails at the expense of traditional beer and wine.
Germany
Wellness-oriented consumers in Berlin and Munich expand demand for herbal botanical formulations including elderflower and lavender. The Federal Ministry of Food and Agriculture enforces strict beverage ingredient disclosure requirements under EU Food Information to Consumers Regulation. Bavaria's brewing heritage clusters support contract manufacturing partnerships for spirits-based RTD entrants.
Australia
Festival and outdoor occasions in Sydney and Melbourne drive PET and rPET format demand despite EU-style single-use packaging scrutiny. The Australian Taxation Office governs excise tax classifications based on alcohol content and base spirit composition. Queensland's sugarcane processing infrastructure supplies rum-based formulation inputs for domestic canned cocktail production.
RTD Cocktails Market Competitive Environment
Heritage spirits conglomerates and multinational beverage platforms split the market through divergent route-to-market strategies. The vendor base concentrates around entities controlling either Caribbean rum provenance or Japanese convenience retail access. Three archetypes dominate: legacy distillers leveraging brand equity, brewing giants exploiting distribution scale, and regional specialists optimizing for local tax structures. Competitive moves center on supermarket shelf space negotiations and direct-to-consumer platform acquisitions.
Within the heritage distiller tier, Bacardi Limited and Suntory Global Spirits exemplify geographic anchoring strategies. Diageo plc occupies a position spanning multiple flavor and packaging tiers simultaneously through global distribution infrastructure. These three entities represent contrasting approaches to regulatory navigation—Caribbean rum heritage, Japanese convenience dominance, and multinational scale—each capturing distinct margin pools without direct segment overlap.
| Leading Market Players |
|---|
| Bacardi Limited |
| Suntory Global Spirits |
| Diageo plc |
| Campari Group |
| Constellation Brands |
| Pernod Ricard |
| Brown-Forman Corporation |
| Asahi Breweries |
| Anheuser-Busch InBev |
| Others |
Value Chain & Pricing Dynamics
North American aluminum can undercapacity during summer demand peaks forces RTD cocktail producers to commit to annual offtake contracts six months ahead of production, compressing margin flexibility and amplifying procurement risk for mid-tier brands lacking supplier financing access.
Pricing Analysis
The customization-premium spread separates standard canned formulations from nitrogen-dosed, small-batch variants targeting discovery-oriented subscribers. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by ABV optimization for Japan's liquor tax brackets and TTB formula approval tier. Cost compression in standard-tier citrus formulations is intensifying because wine-based substitutes capture price-sensitive households in inflation-pressured European markets. Subscription-based buyers in New York and Los Angeles exhibit lowest price sensitivity, while routine supermarket replenishment shoppers in the United Kingdom show highest elasticity.
Supply Chain Analysis
Extended payment terms from aluminum suppliers to can manufacturers now stretch 90-120 days, straining working capital for regional RTD entrants. Can manufacturing concentrates in the United States, Brazil, and Japan, with raw material dependencies spanning bauxite from Australia, coating chemicals from Germany, and nitrogen gas supply from domestic industrial gas networks. Single-source vulnerability in North American can body production creates acute exposure during seasonal demand spikes. Distribution runs through three-tier systems in the United States, direct-to-retail in Japan, and hybrid wholesale in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic cold-fill processing is collapsing the shelf-life premium historically commanded by refrigerated fresh cocktails, creating a technological inflection that rewards early capital deployment toward nitrogen-dosed canning infrastructure.
For Market Incumbents: Pre-empt subscription platform acquisition to capture discovery-oriented Millennial and Gen-Z cohorts before direct-to-consumer specialists consolidate urban markets. Secure multi-year aluminum can offtake agreements with Ball Corporation or Crown Holdings to defend against summer capacity crunches. TTB formula approval bottlenecks threaten rapid product iteration—build regulatory affairs teams in Washington DC to compress 90-180 day timelines. For New Entrants and Emerging Players: Establish a beachhead in herbal botanical formulations targeting wellness-oriented consumers in Berlin and Munich, where premium positioning remains underdeveloped relative to citrus and berry saturation. Japan's lower-ABV tax-optimized tiers offer the most penetrable regulatory arbitrage for new entrants with formulation chemistry capabilities. Launch through curated subscription boxes in Los Angeles and New York to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists controlling Japanese convenience retail access or Caribbean rum heritage supply chains, as these moats resist multinational replication over the forecast horizon. Acquisition targets should demonstrate established EU Food Information to Consumers Regulation compliance ahead of tightening enforcement. Watch for nitrogen-dosed canning line investment announcements as the signal indicating which mid-tier brands are capturing refrigerated case resets in upscale grocery.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Subscription models bypass three-tier distribution constraints in the United States, capturing Millennial discovery spend. |
| Nitrogen-Dosed Canning Line Investment | Aseptic cold-fill technology collapses shelf-life premiums, forcing refrigerated case negotiations in upscale grocery. |
| EU Regulatory Compliance Pre-Positioning | Early allergen and nutritional labeling alignment secures shelf space as retailers reduce supplier complexity. |
| Japanese Convenience Retail Partnership | Automated dispenser integration in Tokyo and Osaka blurs on-premise boundaries, capturing impulse purchase occasions. |
| Low-ABV Formulation Development | Japan's National Tax Agency tier optimization expands accessible price points in convenience retail channels. |
Study Parameters
Desk research of TTB formula approval databases, Japanese National Tax Agency liquor classification records, and EU Food Information to Consumers Regulation guidance documents preceded structured interviews with RTD brand managers, aluminum procurement directors, beverage formulation chemists, and supermarket category buyers. Secondary validation drew from customs trade data, Nielsen retail audit figures, and SEC filings of publicly traded beverage conglomerates. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Assumptions held fixed include current TTB interstate commerce requirements, Japan's ABV-based liquor tax tier structures, and EU single-use packaging enforcement timelines. Variables included aluminum price volatility, nitrogen-dosed canning line adoption rates, and subscription platform penetration in urban United States markets. The forecast framework modeled segmentation across packaging format, flavor architecture, ABV tier, and channel access. CAGRs derived from regression analysis of historical volume trajectories against demographic cohort shift patterns and regulatory change schedules.
Sensitivities concentrate around aluminum supply concentration, TTB approval timeline extensions, and Japan's liquor tax tier recalibration. Forecasts reflect documented assumptions about consumer occasion migration and channel shift velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Cordial Drink Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
North America Craft Beer Market