
 Global Structured Data Archiving and Application Retirement Market | 2026-2036
Global Structured Data Archiving and Application Retirement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Structured Data Archiving and Application Retirement Market Foresight
Mainframe COBOL expertise is collapsing across North America and Western Europe, forcing enterprises to accelerate legacy system decommissioning. IBM Corporation leverages decades of mainframe integration depth to sustain enterprise relationships during complex retirement engagements. Informatica competes through specialized data migration tooling that anchors multi-vendor archiving pipelines. Solix Technologies, Inc. differentiates via embedded compliance engines that occupy regulated verticals with stringent retention mandates.
Structured data archiving and application retirement encompasses the systematic extraction, transformation, and long-term preservation of transactional records from obsolete enterprise applications, typically employing compression ratios of 10:1 to 30:1 and immutable WORM storage protocols to satisfy legal hold requirements. The primary commercial purpose centers on cost reduction through software license termination while maintaining audit-ready data accessibility. Cloud-based deployment is capturing the fastest expansion as hyperscale infrastructure displaces capital-intensive on-premises retention farms. Archiving software retains the largest margin pool due to recurring subscription economics, though data migration solutions command premium pricing during enterprise ERP consolidation waves.
FDA 21 CFR Part 11 and HIPAA Security Rule shape healthcare sector demand by mandating tamper-evident record retention with complete audit trails. The EU GDPR and emerging CSRD reporting obligations force multinationals to maintain geographically distributed, defensible data archives with granular deletion capabilities. Stakeholders must weigh the operational risk of accelerated legacy retirement against the compliance exposure of retaining unmaintained applications beyond vendor support horizons.
Market Dynamics
EU AI Act retention mandates and GDPR deletion requirements are forcing multinationals to retire legacy SAP and Oracle systems faster than vendor support timelines allow, compressing migration windows from years to quarters.
Growth Catalysts
- Healthcare digitization mandates:FDA 21 CFR Part 11 and HIPAA Security Rule requirements for tamper-evident audit trails accelerate hospital system retirements. Providers must maintain decades of patient records with full provenance documentation.
- EU regulatory convergence:GDPR Article 17 right-to-erasure and CSRD reporting obligations create dual pressures for geographically distributed, defensible archives with granular deletion capabilities.
- Mainframe expertise collapse:North American and Western European COBOL programmer pools are shrinking, forcing enterprises to decommission unmaintained transactional systems before operational failure.
Market Restraints
- Migration cost volatility:Complex ERP data transformation requires specialized tooling and extended professional services engagements, creating budget overrun risk.
- Storage infrastructure concentration:Hyperscale cloud providers dominate immutable WORM storage supply, creating vendor lock-in exposure for regulated enterprises.
- Technical debt entanglement:Decades of undocumented customizations in legacy SAP instances obscure data lineage, extending discovery timelines.
Strategic Opportunities
- Asia-Pacific manufacturing expansion:Japanese automotive suppliers and South Korean electronics conglomerates face parallel SAP S/4HANA migration deadlines, creating regional service demand.
- AI-ready archive activation:Structured historical data reservoirs enable machine learning training datasets for predictive maintenance and fraud detection models.
- Subscription pricing penetration:Cloud-native archiving platforms displace capital-intensive on-premises retention farms through consumption-based economics.
Industry Challenges
- Forensic data archaeology:Enterprises lack personnel capable of interpreting schema from 1990s-era custom applications, forcing expensive reverse-engineering engagements.
- Validation timeline compression:FDA and EMA computer system validation requirements extend go-live schedules, conflicting with accelerated retirement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Structured Data Archiving and Application Retirement Market |
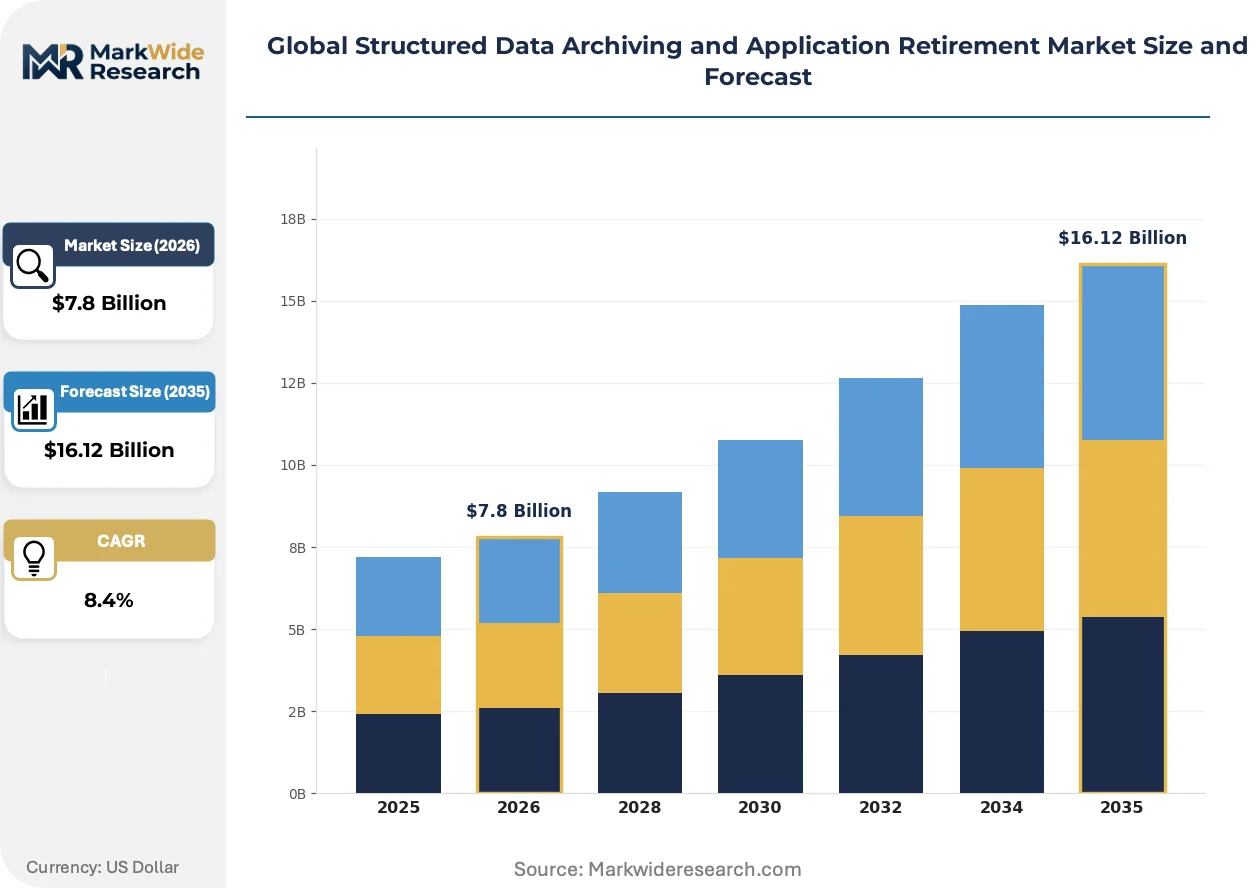
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Solution Offering: Archiving Software, Retirement Tools, Data Migration Solutions, Compliance Management, Backup Integration Application: Financial Services, Telecommunications, Manufacturing, Government Agencies, Education End User Type: Enterprises, Managed Service Providers, System Integrators, Technology Vendors |
| Companies Covered | IBM Corporation, Informatica, Microsoft Corporation, OpenText Corporation, Delphix, Data Migration Services AG, PBS Software, Solix Technologies, Inc., ZL Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Structured Data Archiving and Application Retirement Market Shifts & Advancements
Archival infrastructure is pivoting from passive storage vaults to active compliance engines, with embedded legal hold automation and real-time deletion orchestration becoming baseline requirements rather than premium features.
Immutable blockchain-anchored audit trails are fragmenting vendor competitive positioning in regulated verticals. Pharmaceutical manufacturers and medical device producers adopt distributed ledger verification to satisfy FDA 21 CFR Part 11 requirements. The technology compresses vendor differentiation to compliance automation depth rather than storage density.
EU AI Act risk classification rules are reshaping data retention architecture for machine learning training datasets. Enterprises must now demonstrate provenance and consent documentation for historical records repurposed as AI inputs. German automotive and industrial conglomerates face the steepest reconfiguration burden due to extensive legacy sensor data archives.
Buyer procurement patterns are consolidating around integrated platform decisions rather than best-of-breed point solutions. Healthcare systems and financial services institutions now require archiving vendors to bundle migration, compliance, and long-term preservation under single contracts. This concentration is most visible in US hospital networks undergoing Epic-centric electronic health record consolidations.
Global Structured Data Archiving and Application Retirement Market Segmentation
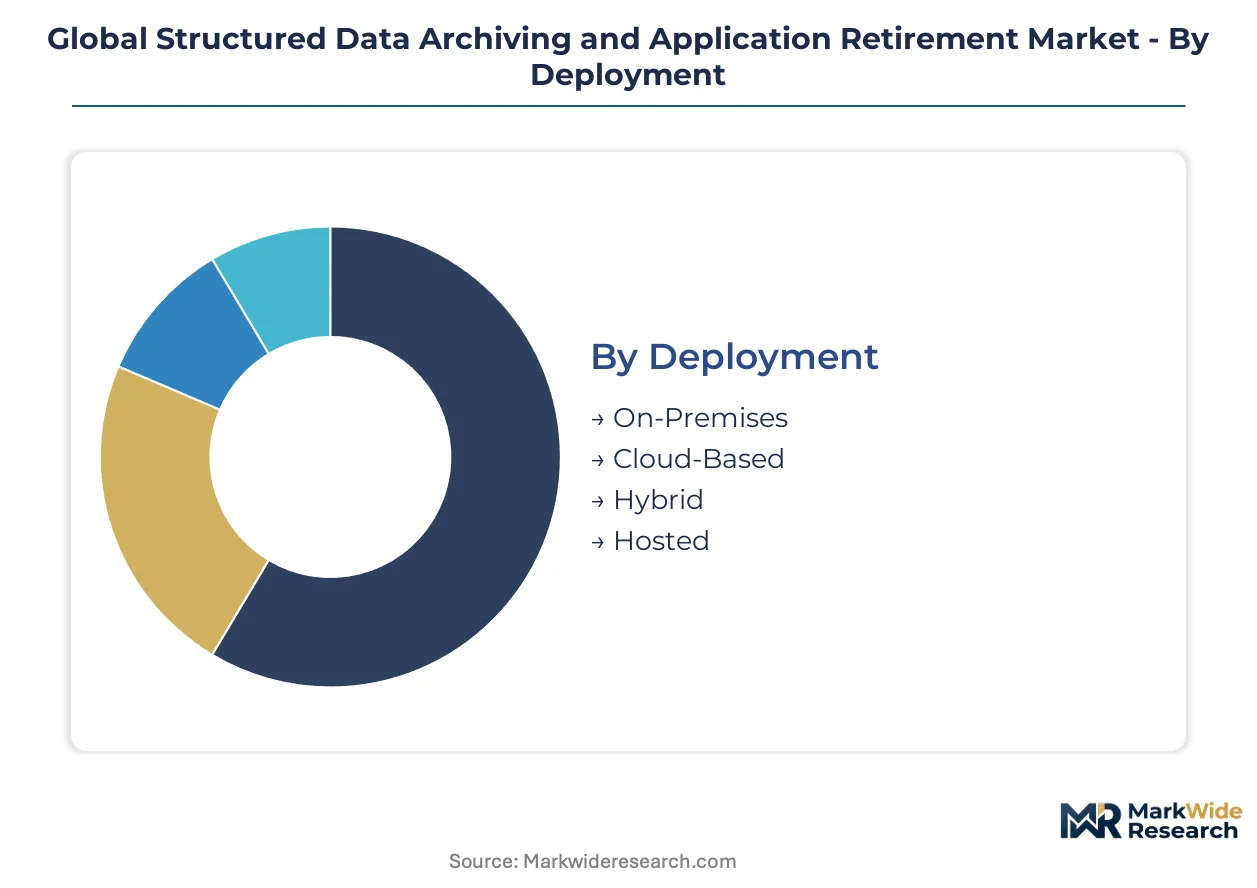
Structured data archiving and application retirement solutions address heterogeneous compliance burdens and infrastructure legacies across deployment modes, solution types, and vertical applications. Segmentation reveals where regulatory stringency concentrates purchasing power and which technology architectures capture migration budget allocation.
Deployment:
GDPR Article 17 right-to-erasure mandates and FDA 21 CFR Part 11 validation requirements create divergent infrastructure imperatives across deployment architectures, with regulated verticals demanding geographically controlled data sovereignty.
- On-Premises:Dedicated hardware installations within enterprise data centers deliver complete physical custody of archival records. German automotive manufacturers and Swiss pharmaceutical producers dominate demand, driven by Bundesdatenschutzgesetz and Swissmedic inspection protocols that prohibit cross-border data residency.
- Cloud-Based:Hyperscale infrastructure delivers consumption-scaled storage with embedded WORM compliance. US hospital networks undergoing Epic consolidations and Japanese electronics conglomerates facing METI data localization guidance represent the steepest adoption trajectory.
- Hybrid:Tiered architectures partition active legal holds on-premises while relegating cold archives to cloud tiers. French banking groups navigating CNIL audit requirements and Australian healthcare providers under TGA jurisdiction favor this model for cost-optimized compliance.
- Hosted:Third-party managed facilities deliver dedicated tenancy without capital deployment. Mid-market Canadian manufacturers and South Korean automotive suppliers utilize hosted arrangements to satisfy MFDS and KBA documentation mandates without internal infrastructure investment.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
Solution Offering:
Margin concentration follows recurring subscription economics in software layers, while project-based migration services capture premium pricing during ERP consolidation waves.
- Archiving Software:Compression engines achieving 10:1 to 30:1 reduction ratios with immutable retention policies form the core technology stack. US healthcare providers under HIPAA Security Rule enforcement and EU enterprises subject to CSRD reporting obligations drive subscription renewal rates.
- Retirement Tools:Application decommissioning platforms orchestrate license termination while preserving audit-ready data accessibility. German industrial conglomerates facing SAP S/4HANA migration deadlines represent concentrated demand as vendor support horizons contract.
- Data Migration Solutions:Schema transformation and lineage reconstruction services address technical debt entanglement in legacy ERP instances.
- Compliance Management:Embedded legal hold automation and real-time deletion orchestration satisfy dual GDPR retention and erasure pressures.
- Backup Integration:Consolidated recovery point management reduces redundant infrastructure spend across primary and archival storage tiers.
Recurring revenue concentrates in Archiving Software; project urgency elevates Data Migration Solutions.
Application:
Vertical-specific regulatory frameworks dictate archival architecture requirements, with financial and healthcare sectors imposing the most stringent audit trail specifications.
- Financial Services:SEC record-keeping rules and Basel III data retention mandates require tamper-evident transaction archives with complete provenance documentation. US broker-dealers and EU credit institutions under ECB supervision represent the largest contract values.
- Telecommunications:FCC retention requirements and GDPR subscriber data obligations force carriers to maintain granular deletion capabilities across decades of call detail records.
- Manufacturing:FDA 21 CFR Part 11 for medical device producers and ISO 13485 quality system records drive pharmaceutical and industrial archiving spend.
- Government Agencies:National archival statutes and freedom-of-information response obligations create long-tail retention requirements with public audit exposure.
- Education:FERPA student record protections and research data management policies shape institutional procurement with constrained budget elasticity.
Contract value peaks in Financial Services; procurement velocity accelerates in Manufacturing.
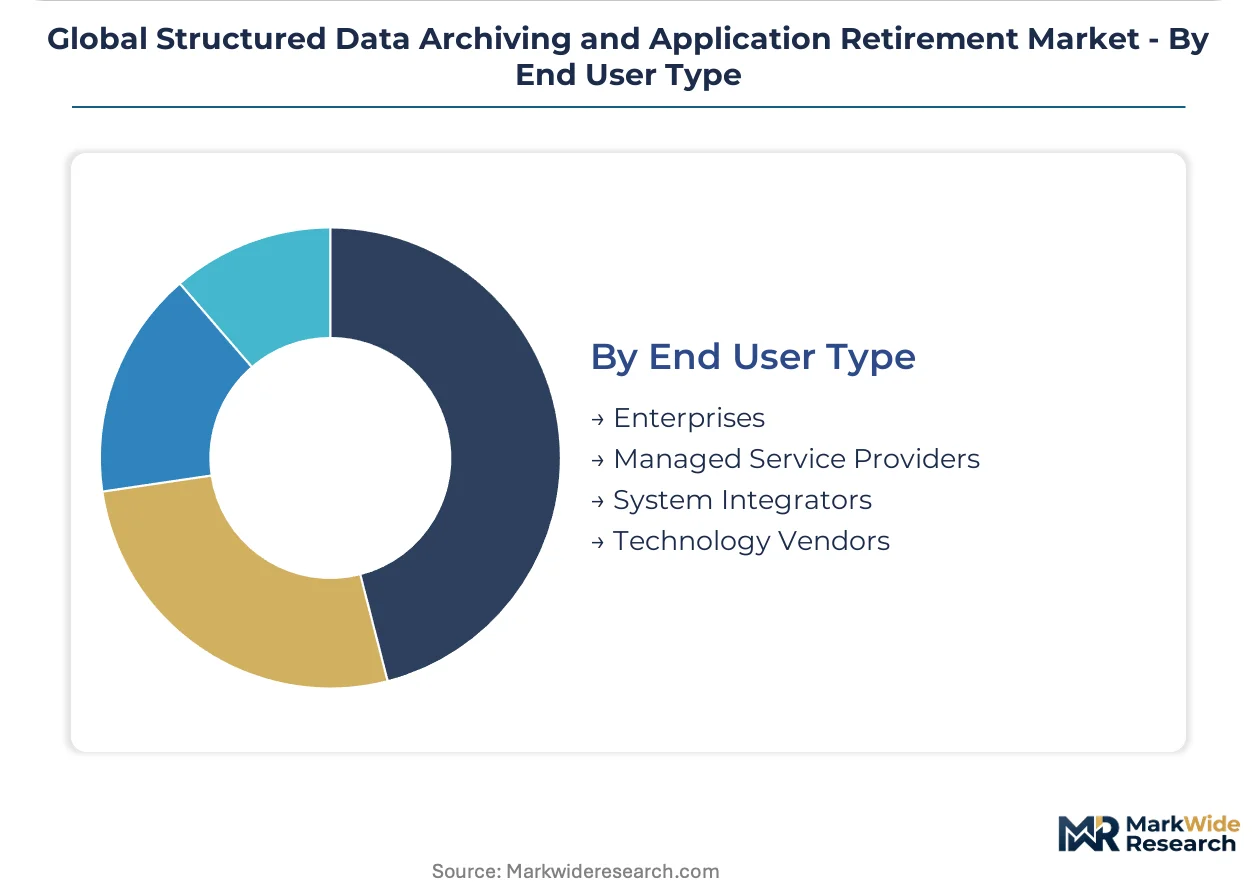
End User Type:
Channel structure determines solution packaging complexity, with direct enterprise engagements demanding integrated platforms and intermediary routes favoring modular components.
- Enterprises:Direct procurement by Fortune 500 manufacturers and healthcare systems requires single-contract bundling of migration, compliance, and preservation functions. German automotive conglomerates and US hospital networks undergoing Epic-centric consolidations exemplify this pattern.
- Managed Service Providers:MSPs aggregate archival services for mid-market clients lacking internal compliance expertise. Canadian professional services firms and Australian regional healthcare networks utilize MSP intermediaries to satisfy TGA and Health Canada requirements.
- System Integrators:SI partnerships anchor complex ERP retirement engagements requiring multi-vendor orchestration.
- Technology Vendors:OEM embedding arrangements extend archiving capabilities into adjacent infrastructure management platforms.
Deal size concentrates in Enterprises; volume expansion favors Managed Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 and HIPAA Security Rule enforcement anchor United States demand, while EU AI Act retention mandates and GDPR Article 17 obligations accelerate European procurement timelines. German automotive conglomerates and US hospital networks undergoing Epic-centric consolidations represent the steepest adoption trajectories.
United States
Hospital networks decommissioning legacy patient record systems drive cloud-based archiving procurement. FDA 21 CFR Part 11 mandates tamper-evident audit trails with complete provenance documentation. The Epic-centric consolidation wave across Midwest and Southeast health systems compresses migration windows from years to quarters.
Germany
Automotive and industrial conglomerates face SAP S/4HANA migration deadlines that outpace vendor support horizons. Bundesdatenschutzgesetz and EU AI Act risk classification rules force reconfiguration of legacy sensor data archives. Stuttgart and Munich industrial clusters concentrate demand for geographically controlled data sovereignty solutions.
Japan
Electronics conglomerates and automotive suppliers navigate parallel ERP modernization timelines under METI data localization guidance. Pharmaceutical manufacturers adopt immutable blockchain-anchored audit trails to satisfy PMDA inspection protocols. Osaka and Nagoya manufacturing hubs generate concentrated demand for hybrid deployment architectures.
United Kingdom
Financial services institutions under FCA and Prudential Regulation Authority supervision require tamper-evident transaction archives. GDPR retention and erasure pressures persist post-Brexit through UK GDPR alignment. The City of London and Edinburgh banking clusters drive procurement of embedded legal hold automation platforms.
Switzerland
Pharmaceutical producers and private banking institutions demand complete physical custody of archival records under Swissmedic and FINMA protocols. Bundesdatenschutzgesetz-equivalent cantonal regulations prohibit cross-border data residency for sensitive records. Basel and Zurich life sciences clusters anchor premium-tier on-premises deployment demand.
Global Structured Data Archiving and Application Retirement Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around platform bundling rather than point solutions. Technology conglomerates with decades of enterprise integration depth sustain relationships during complex retirement engagements. Specialist vendors occupy regulated verticals through embedded compliance engines. Competitive dynamics center on strategic partnerships with system integrators and geographic expansion into Asia-Pacific manufacturing hubs.
Within the integrated platform tier, IBM Corporation and Microsoft Corporation exemplify technology conglomerates leveraging enterprise software ecosystems to anchor archiving engagements. Informatica occupies a position among data migration specialists whose tooling anchors multi-vendor pipelines. Solix Technologies, Inc. represents the compliance-focused archetype, with embedded regulatory engines targeting healthcare and financial services verticals.
| Leading Market Players |
|---|
| IBM Corporation |
| Informatica |
| Microsoft Corporation |
| OpenText Corporation |
| Delphix |
| Data Migration Services AG |
| PBS Software |
| Solix Technologies, Inc. |
| ZL Technologies |
| Others |
Supply & Pricing Matrix
Cloud-native subscription models displacing perpetual license deployments simultaneously redistribute supply geography toward hyperscale data center regions and compress pricing economics for on-premises hardware vendors. This substitution dynamic concentrates buyer leverage in North American and Western European enterprise procurement functions while fragmenting legacy infrastructure vendor pricing power.
Pricing Analysis
Geographic price spreads of 40-60% separate German automotive procurement from US hospital network contracting for equivalent archiving software tiers. Three-tier pricing structure across premium compliance-integrated, standard cloud-native, and economy migration-only levels dominates contract structures. Price differentiation hinges on FDA 21 CFR Part 11 certification grade and embedded legal hold automation depth. Pricing pressure stems from hyperscale cloud providers bundling archival storage with compute contracts. Mid-market Canadian manufacturers exhibit highest price sensitivity; Swiss pharmaceutical producers under FINMA supervision demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of compliance documentation and validation certificates precedes migration engagements, contrasting with just-in-time provisioning of cloud storage capacity. Supply concentrates in the United States, Germany, and Ireland for archival software development; India and Poland for professional services delivery. Component dependencies include immutable WORM storage hardware, schema transformation engines, and blockchain-anchored audit trail modules. Single-source vulnerability runs through hyperscale cloud infrastructure concentration. Distribution runs through direct enterprise sales for Fortune 500 accounts; MSP intermediaries for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
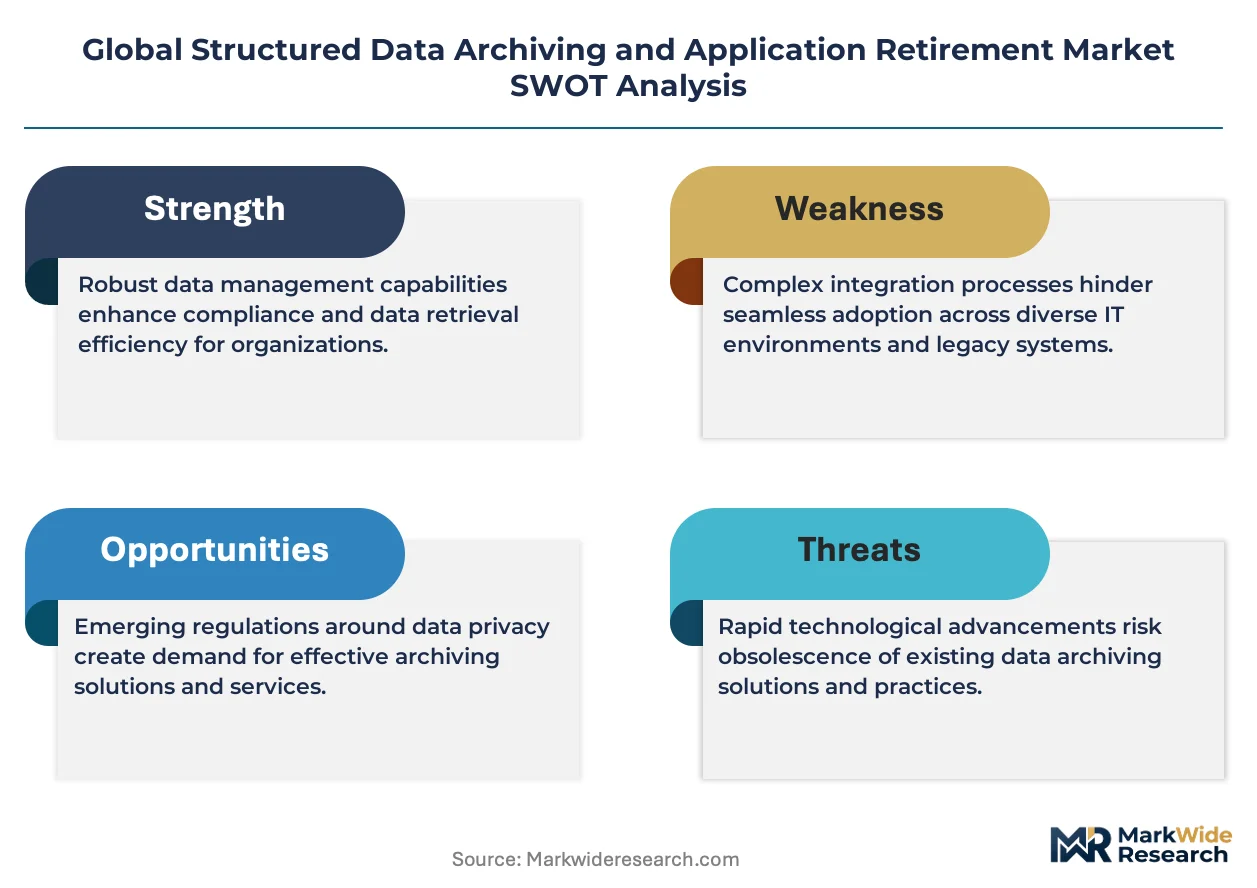
Buyer power is concentrating through US hospital network Epic-centric consolidation and German automotive SAP S/4HANA migration waves, compressing vendor margins and favoring platform bundling over point solutions.
For Market Incumbents: Compound compliance automation depth in healthcare and financial services verticals to defend against emerging cloud-native entrants. Deepen embedded regulatory engines for EU AI Act risk classification requirements. Anchor multi-year enterprise relationships through integrated migration-preservation-compliance contracts that increase switching costs. For New Entrants and Emerging Players: Mid-market managed service provider channels represent the most penetrable white-space where incumbents under-serve with direct sales models. Target Canadian manufacturers and Australian healthcare providers lacking internal compliance expertise. Pursue OEM embedding arrangements with adjacent infrastructure management platforms to bypass direct competitive confrontation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed data migration specialists holding SAP and Oracle retirement tool portfolios. Long-term viability centers on recurring subscription conversion from project-based services. Acquisition target archetype: compliance-focused vendors with FDA-validated installations in pharmaceutical verticals. Watch FDA 21 CFR Part 11 enforcement intensity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic-centric hospital consolidations demand bundled migration-compliance-preservation contracts. |
| Compliance Engine Deepening | EU AI Act risk classification rules force reconfiguration of legacy sensor data archives. |
| Geographic Expansion | Japanese automotive suppliers and South Korean electronics conglomerates face parallel SAP deadlines. |
| Strategic Partnership | System integrator alliances anchor complex ERP retirement engagements requiring multi-vendor orchestration. |
| Acquisition of Specialist Firm | Blockchain-anchored audit trail capabilities satisfy FDA 21 CFR Part 11 for pharmaceutical manufacturers. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings. Conversations with CTOs, IT procurement officers, compliance directors, and system integration partners inform deployment preference and vendor selection criteria. Secondary sources include SEC 10-K disclosures, FDA 510(k) and 21 CFR Part 11 validation records, EMA inspection reports, and hyperscaler infrastructure capex announcements. Bottom-up contract value analysis triangulates against top-down market sizing across deployment modes and vertical applications.
Sensitivity analysis around regulatory timeline compression and mainframe expertise availability shapes scenario outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution offering type, vertical application, and end-user channel structure. CAGRs derive from weighted average of historical vendor revenue trajectories and forward-looking procurement survey data. Forecast inputs incorporate SAP S/4HANA migration deadline schedules and FDA enforcement intensity indices.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EU GDPR Article 17, and EU AI Act implementation regimes; material policy shifts would require re-modeling. Specific risks include accelerated legacy system failure before migration completion and hyperscale cloud provider market concentration. Revision becomes warranted when FDA warning letter issuance rates or SAP support termination announcements cross historical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
UAE ICT Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
Product As a Service Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Self-Service Kiosk Market