
 Cold and Flu Supplements Market | 2026-2036
Cold and Flu Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Cold and Flu Supplements Market Intelligence
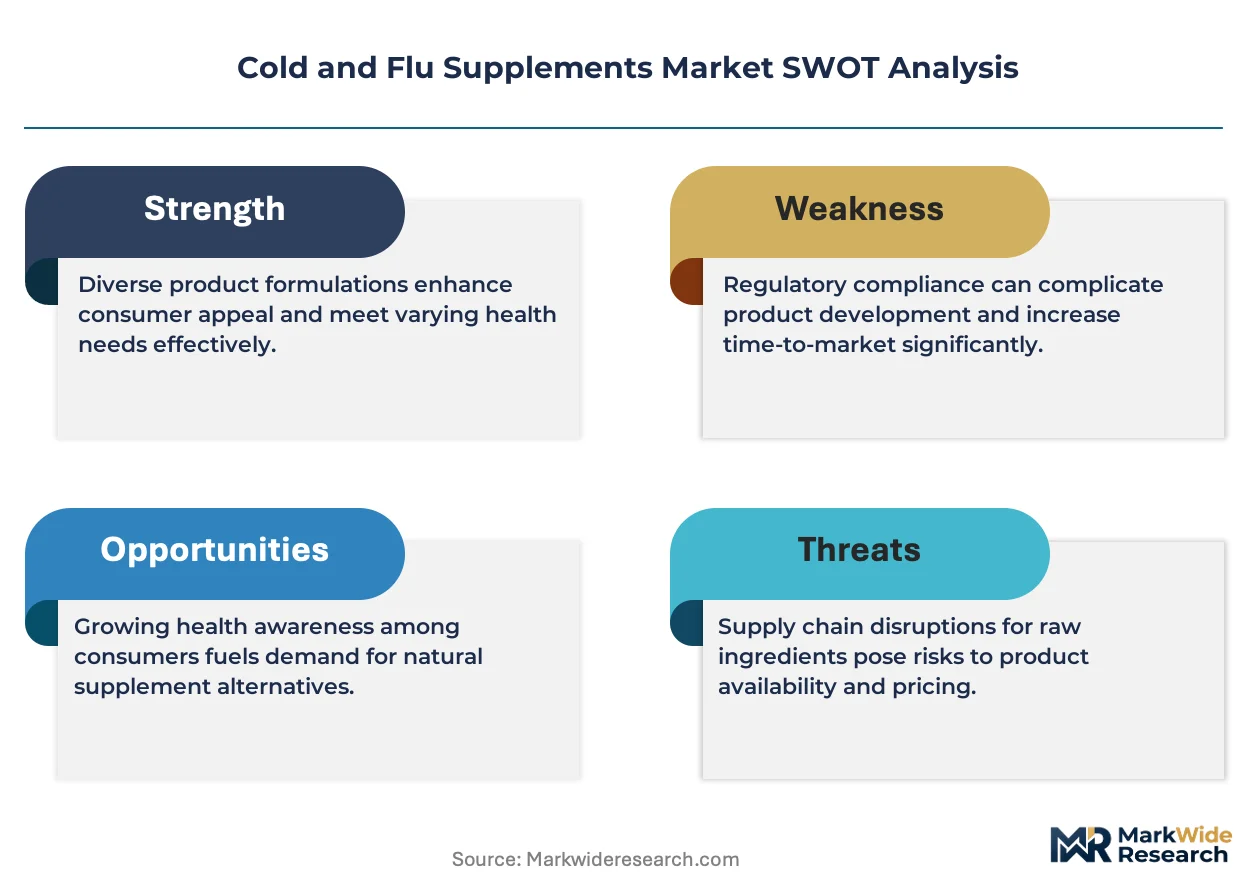
Sourcing volatility for key botanicals like elderberry and echinacea is recalibrating the supply chain for natural ingredients. This shift pressures manufacturers to secure reliable, high-quality raw material streams to ensure product consistency. Bayer AG leverages its pharmaceutical background to validate the efficacy of its supplement formulations. Haleon plc sustains its market presence through powerful branding and extensive distribution across global pharmacy networks. Meanwhile, NOW Foods specializes in the natural products channel, appealing to consumers seeking non-GMO and certified organic options.
Cold and flu supplements are over-the-counter products designed to support immune function or alleviate symptoms associated with common respiratory infections. Formulations often include specific dosages of active ingredients, such as 500-1000mg of Vitamin C or standardized extracts of Echinacea purpurea. The primary purpose is preventative care and symptom duration reduction, not curing the underlying viral infection. While Vitamin C and Zinc remain foundational ingredients, elderberry-based products represent the fastest-growing segment. Product formats like gummies and powders are gaining share from traditional caplets, especially among children and adults who dislike swallowing pills.
The regulatory environment is defined by national and regional bodies that govern dietary supplements and health claims. In the United States, the FDA enforces regulations under the Dietary Supplement Health and Education Act (DSHEA). In Europe, the European Food Safety Authority (EFSA) scrutinizes health claims, requiring significant scientific evidence. These frameworks compel manufacturers to invest in clinical data to support their marketing assertions. Future market position will hinge on a company's ability to navigate divergent international standards and provide credible scientific validation for its products.
Market Dynamics
The market's structure is defined by the growing consumer preference for botanical ingredients like elderberry, which is colliding with stricter regulatory demands for scientific evidence. This dynamic forces manufacturers to balance natural product marketing with the high costs of clinical validation.
Growth Catalysts
- Preventative Health Focus:A consumer shift towards proactive immune support, especially in Germany, drives demand for supplements beyond periods of active illness.
- Child-Friendly Formats:The expansion of palatable delivery systems like gummies successfully penetrates the pediatric market, expanding the overall consumer base.
- Botanical Substantiation:Growing clinical data for ingredients like elderberry helps manufacturers meet the evidence requirements of regulators like the US FDA.
Market Restraints
- Botanical Supply Volatility:Unpredictable harvests for ingredients like elderberry create price instability and supply chain risk, impacting production consistency for manufacturers.
- Divergent Global Regulations:Conflicting health claim rules between the US FDA and Europe's EFSA increase compliance costs and marketing complexity for brands.
- Substitution from Functional Foods:Fortified foods and beverages with immune-support ingredients offer a direct alternative, diverting consumer spending away from pill-based supplements.
Strategic Opportunities
- Asia-Pacific Market Development:Countries like South Korea and Australia show rising interest in preventative health, creating white-space opportunities for Western brands.
- Personalized Nutrition Services:Integrating diagnostic data to create customized supplement regimens offers a high-value service model beyond standard product sales.
- Direct-to-Consumer Models:Subscription-based e-commerce enables brands to own the customer relationship, gather data, and improve margins by bypassing retail intermediaries.
Industry Challenges
- Clinical Trial Investment:The high cost and long timelines associated with conducting robust clinical trials to substantiate health claims pose a significant financial barrier for smaller brands.
- Combating Misinformation:Brands face the continuous challenge of educating consumers on realistic product benefits and differentiating scientifically-backed formulations from unsubstantiated online health fads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold and Flu Supplements Market |
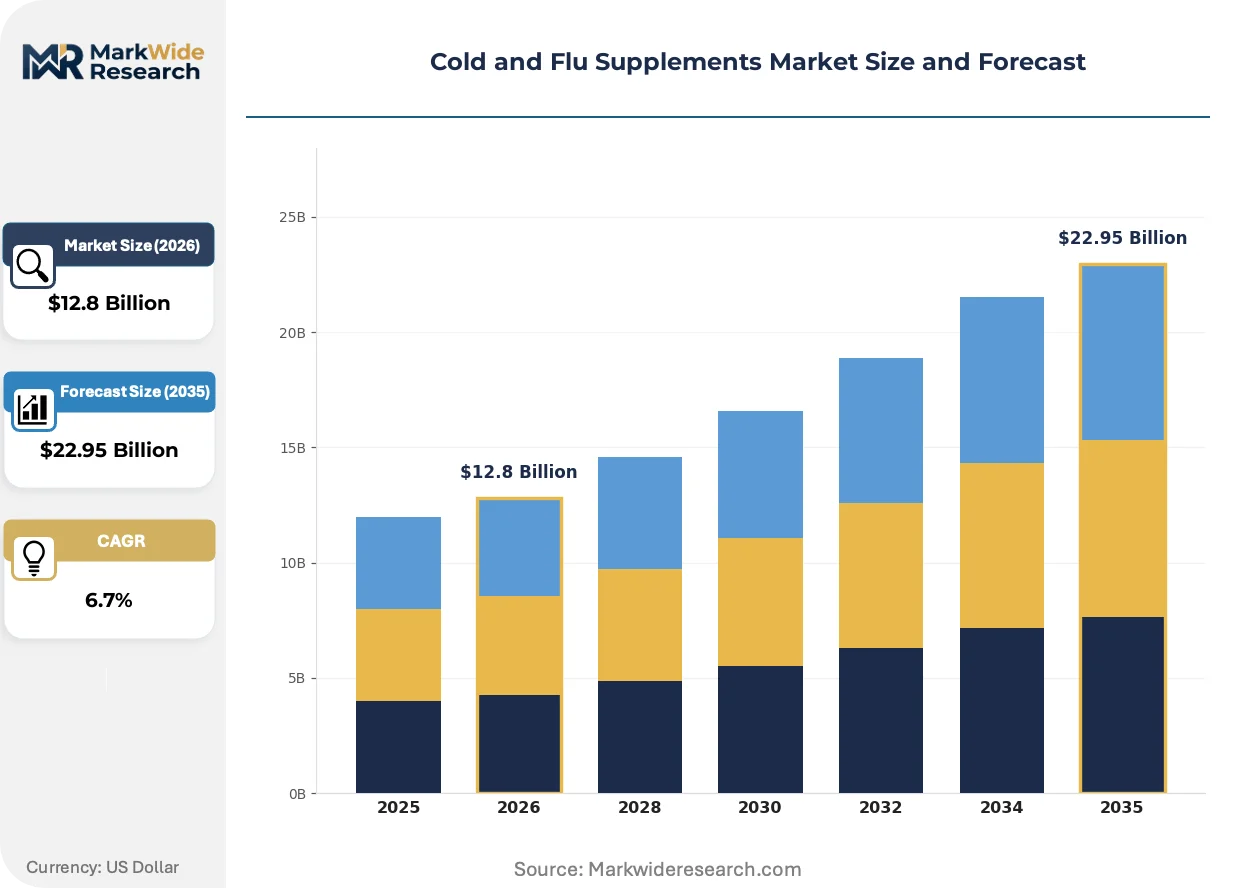
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caplets, Powders, Liquids, Gummies Active Ingredient: Vitamin C, Zinc, Elderberry, Echinacea Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores Target Demographic: Adults, Children, Seniors, Pregnant Women |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Bayer AG, Reckitt Benckiser Group plc, Haleon plc, Nestle S.A., NOW Foods, Nordic Naturals, Himalaya Wellness Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold and Flu Supplements Market Strategic Shifts & Innovations
Product innovation is moving beyond basic vitamins toward targeted, multi-ingredient formulations backed by clinical data. This evolution reflects a more discerning consumer demanding transparent sourcing and proven efficacy in their supplement choices.
Multi-ingredient synergy formulas combine several active compounds like Vitamin C, zinc, and elderberry into a single dose, designed to provide comprehensive immune support. Health-conscious consumers and families are rapidly adopting these all-in-one solutions for convenience and perceived enhanced effectiveness. This trend toward complex, synergistic blends is overtaking the market for single-ingredient supplements, forcing brands to reformulate their product lines.
The US FDA is intensifying its enforcement under the Dietary Supplement Health and Education Act (DSHEA), requiring more rigorous scientific evidence for health-related claims. This regulatory pressure compels manufacturers to invest heavily in clinical trials to validate product efficacy, increasing R&D costs. The dietary supplement segment, particularly brands making specific claims about symptom duration, is most affected, leading to more cautious marketing language.
Consumers are increasingly prioritizing transparency, scrutinizing product labels for ingredient origin, non-GMO verification, and organic certifications. This behavior disrupts traditional purchasing habits based on brand name alone, giving an advantage to specialized brands in the natural products channel. This preference for clean-label products is particularly pronounced among Millennial and Gen Z consumers in North America and Western Europe.
Cold and Flu Supplements Market Segmentation
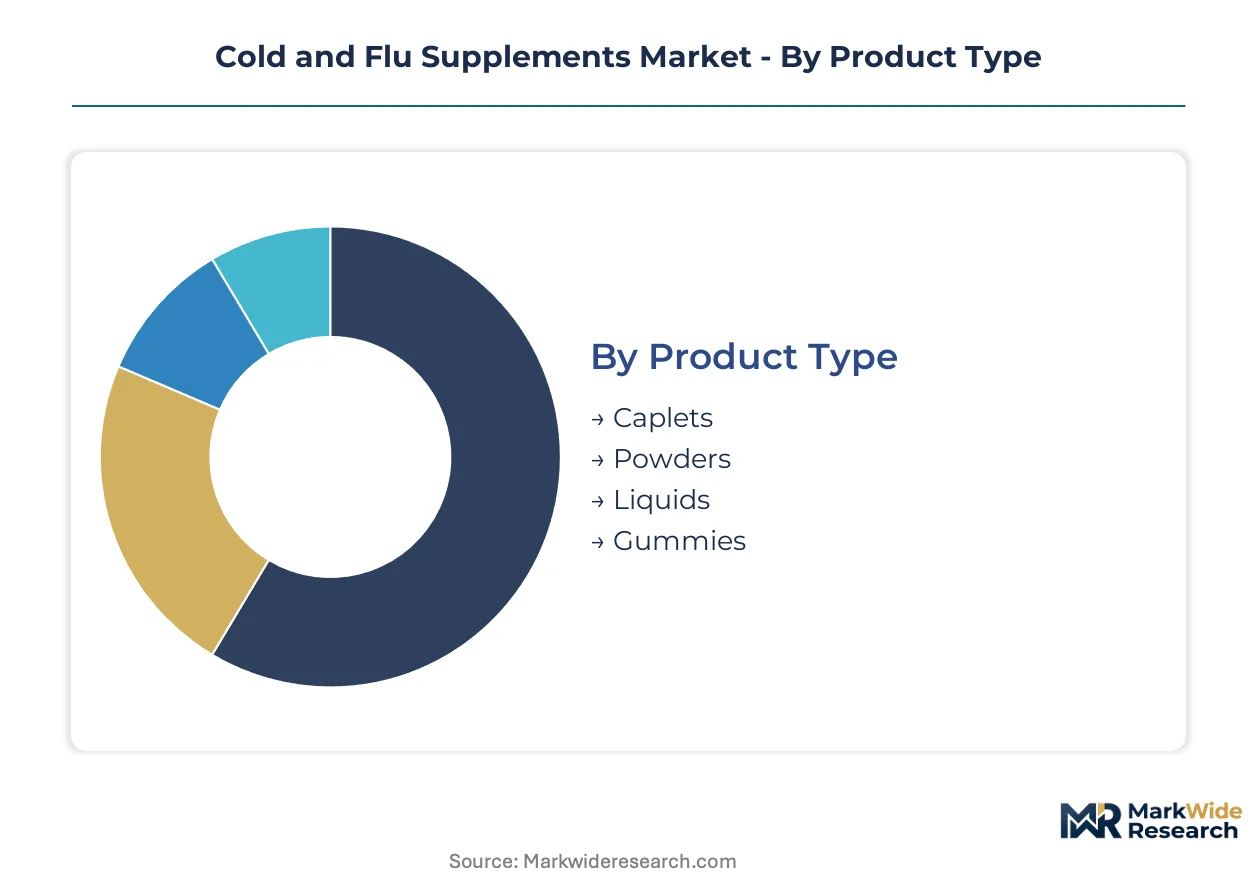
Market segmentation for cold and flu supplements provides a granular view of consumer preferences and manufacturer strategies. This detailed breakdown helps stakeholders understand where demand concentrates and how product innovation aligns with specific user needs.
Product Type:
Supply concentration in product type for cold and flu supplements reflects manufacturing capabilities and consumer convenience. Manufacturers are adapting production lines to meet evolving consumer preferences for ease of consumption.
- Gummies:These chewable formulations offer a palatable and convenient delivery method, particularly popular among children and adults who prefer not to swallow pills. Demand for gummy supplements is concentrating in the pediatric demographic, driven by child-friendly flavors and formats.
- Powders:Designed for mixing into beverages, powders provide a customizable dosage and rapid absorption of active ingredients. Consumers seeking quick-acting immune support, especially those with active lifestyles, are driving demand for powder formats.
- Caplets:Traditional pill-form supplements remain a staple, offering precise dosing and a familiar format for many long-term users.
- Liquids:Liquid supplements provide an alternative for individuals with difficulty swallowing or those preferring faster absorption.
Today's leader: Caplets. Tomorrow's challenger: Gummies.
Active Ingredient:
Application-specific demand drives differentiation within active ingredients for cold and flu supplements. Each ingredient targets distinct aspects of immune support or symptom relief.
- Elderberry:Products containing elderberry extracts are experiencing significant market expansion due to perceived immune-boosting properties and growing scientific interest. This ingredient represents the fastest-growing trajectory, particularly in European markets where natural remedies are favored.
- Vitamin C:A foundational immune support ingredient, Vitamin C formulations are widely available in various dosages and product types. Demand for Vitamin C remains robust across all demographics, driven by its established role in immune health.
- Zinc:This essential mineral is frequently included in formulations to support immune function and reduce the duration of cold symptoms.
- Echinacea:Known for its traditional use in immune support, Echinacea remains a popular botanical ingredient in many supplement blends.
Elderberry-based products are experiencing the steepest expansion trajectory.
Distribution Channel:
Customer type and purchasing habits shape the distribution landscape for cold and flu supplements. Accessibility and trust influence where consumers acquire these health products.
- Online Retail:E-commerce platforms offer convenience, competitive pricing, and a wide selection, appealing to digitally-savvy consumers. Online retail is gaining share fastest as consumer purchasing shifts towards digital channels across North America and Europe.
- Pharmacies:These channels benefit from consumer trust in professional health advice and the immediate availability of products. Pharmacies remain a primary point of sale, especially for consumers seeking expert recommendations.
- Supermarkets:Grocery stores provide easy access to supplements during routine shopping trips, catering to consumers seeking convenience.
- Health Stores:Specialized health stores attract consumers prioritizing natural, organic, and non-GMO certified products.
Online retail is gaining share fastest as consumer purchasing shifts.
Target Demographic:
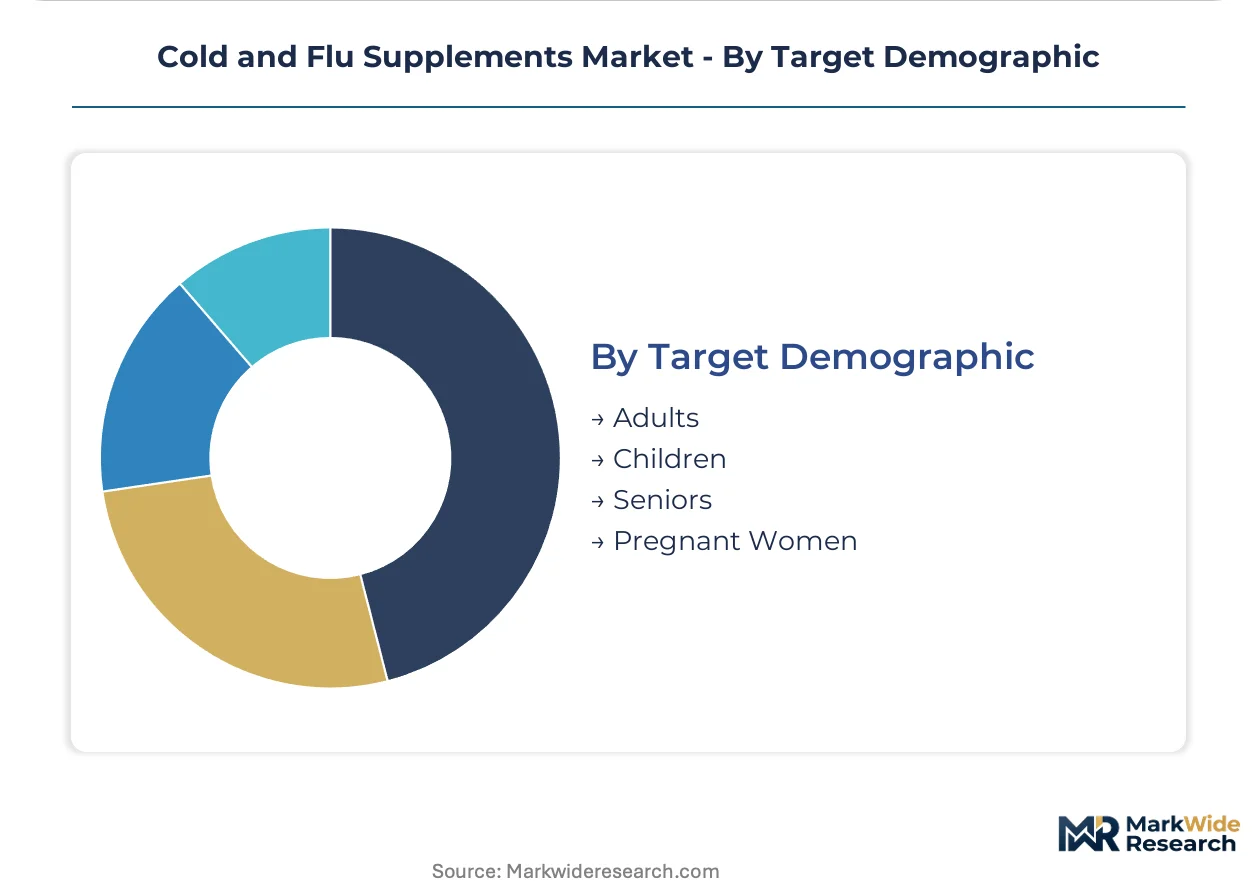
Margin potential varies significantly across target demographic segments for cold and flu supplements. Formulations and marketing efforts are tailored to meet distinct needs.
- Children:This demographic drives demand for palatable forms like gummies and flavored liquids, often with specific dosages for younger bodies. The children's demographic is climbing the fastest due to palatable product forms and parental focus on preventative health.
- Adults:The largest consumer segment, adults seek both preventative and symptom-alleviating supplements, often favoring multi-ingredient formulas. Preventative health focus in countries like Germany drives adult demand for year-round immune support.
- Seniors:Older adults often require specific formulations to support aging immune systems or manage co-morbidities.
- Pregnant Women:This segment requires carefully formulated supplements, often with specific physician recommendations, due to sensitivity considerations.
The children's demographic is climbing the fastest due to palatable product forms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production for cold and flu supplements is recalibrating as manufacturers navigate divergent regulatory landscapes. Compliance costs and market access considerations influence sourcing and manufacturing decisions. This dynamic creates opportunities for regions with streamlined regulatory pathways or strong consumer demand for specific product attributes.
United States
Demand for child-friendly gummy formats drives significant market expansion in the United States. The US FDA enforces stringent regulations under the Dietary Supplement Health and Education Act (DSHEA). California's nutraceutical hub sees extensive R&D into clinically validated botanical formulations.
Germany
Consumers in Germany prioritize preventative health, fueling consistent demand for immune-supporting supplements. The European Food Safety Authority (EFSA) requires robust scientific evidence for health claims across the EU. Berlin's biotech cluster contributes to innovation in natural ingredient extraction and formulation.
South Korea
Rising interest in preventative health and natural remedies shapes the South Korean cold and flu supplement market. The Ministry of Food and Drug Safety (MFDS) regulates dietary supplements with a focus on safety and efficacy. Seoul's vibrant consumer market adopts personalized nutrition services and advanced supplement delivery systems.
Australia
Health-conscious consumers in Australia increasingly seek non-GMO and organic certified cold and flu supplements. The Therapeutic Goods Administration (TGA) provides a comprehensive regulatory framework for complementary medicines. Melbourne's health and wellness sector focuses on ingredient transparency and sustainable sourcing practices.
India
A large consumer base and growing awareness of immune health support demand for traditional and modern cold and flu supplements in India. The Food Safety and Standards Authority of India (FSSAI) governs dietary supplements, emphasizing product safety and labeling. Mumbai's pharmaceutical manufacturing centers are expanding production capabilities for accessible supplement formats.
Cold and Flu Supplements Market Key Industry Players
North American producers anchor one tier, focusing on consumer-friendly formats like gummies; European pharmaceutical giants hold significant market share with clinically validated formulations. The competitive landscape shows a blend of large multinational corporations and specialized natural product companies. Strategic archetypes include pharmaceutical-backed brands, natural channel specialists, and agile direct-to-consumer players. Portfolio diversification through multi-ingredient formulas and geographic expansion into emerging markets are dominant competitive moves, alongside strategic partnerships to secure raw material supply.
Within the pharmaceutical-backed brands tier, Bayer AG and Haleon plc exemplify companies leveraging extensive R&D and global distribution networks. Bayer AG, a German-based AG, occupies a position emphasizing scientific validation for its supplement formulations. UK-based Haleon plc sustains its market presence through powerful branding and broad access across pharmacy networks. NOW Foods, a US-based natural products specialist, represents the growing segment appealing to consumers seeking non-GMO and certified organic options. These companies collectively anchor different segments of the cold and flu supplements market.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Bayer AG |
| Reckitt Benckiser Group plc |
| Haleon plc |
| Nestle S.A. |
| NOW Foods |
| Nordic Naturals |
| Himalaya Wellness Company |
| Others |
Cost & Logistics Intelligence
Stricter health claim substantiation rules are forcing manufacturers to invest heavily in clinical data, which in turn elevates product development costs and influences pricing strategies. This dynamic compels supply chains to prioritize reliable, high-quality ingredient sourcing to justify premium price points.
Pricing Analysis
Retailer markups significantly influence the final consumer price for cold and flu supplements across various distribution channels. The dominant pricing model remains per-unit transactional, though contract-based long-term agreements secure bulk ingredient purchases. Price differentiation stems from the certification level, such as non-GMO or organic, and the strength of a brand's scientific validation. Pricing pressure stems from the availability of lower-cost functional foods offering similar immune support ingredients. The children's demographic exhibits lower price sensitivity due to parental focus on preventative health, while general adult consumers are more price-sensitive for basic Vitamin C formulations.
Supply Chain Analysis
Botanical ingredient supply rests heavily on agricultural regions in Europe for elderberry and echinacea, alongside China for Vitamin C and zinc manufacturing. Key raw material dependencies include standardized extracts of elderberry and echinacea, coupled with pharmaceutical-grade Vitamin C and zinc compounds. Unpredictable harvests for botanicals like elderberry create significant commodity price volatility, posing a structural supply chain risk. Downstream, distribution runs through a hybrid model combining online retail for convenience and pharmacies for professional advice, with supermarkets providing broad access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold and flu supplements market presents a clear margin-expansion story, driven by a consumer shift towards premium, clinically validated, multi-ingredient formulations.
For Market Incumbents:
Deploy strategic partnerships to secure reliable, high-quality botanical raw material streams, mitigating supply volatility. Invest heavily in clinical trials to substantiate specific health claims, differentiating products from the growing threat of functional food alternatives. Focus R&D on multi-ingredient synergy formulas, offering comprehensive immune support. Leverage existing global pharmacy networks to maintain broad market presence against new entrants.
For New Entrants and Emerging Players:
Capture white-space opportunities in Asia-Pacific markets like South Korea and Australia, where preventative health interest is rising. Target the children's demographic with innovative, palatable product formats such as gummies in under-served regions. Implement direct-to-consumer (DTC) models to own the customer relationship, gather crucial data, and enhance margins. Emphasize transparent sourcing and certified organic options to appeal to discerning Millennial and Gen Z consumers.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized natural products companies demonstrating robust clinical data and secure, ethical botanical sourcing. The long-term viability of this market is strong, supported by sustained consumer trends toward proactive immune support. Consider acquisition targets with strong intellectual property in multi-ingredient formulations or unique delivery systems. A key signal to watch is increased regulatory approvals from bodies like the US FDA for specific botanical health claims, indicating market maturation and validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Multi-ingredient synergy formulas | Combines active compounds for comprehensive immune support, appealing to health-conscious consumers. |
| Regulatory Approval Pathway: EFSA approval for elderberry claims | Validates product efficacy for European markets, building consumer trust and market access. |
| Strategic Partnership: Botanical sourcing agreements | Secures reliable supply of key ingredients like elderberry, stabilizing production costs. |
| Geographic Expansion: Asia-Pacific market entry | Taps into rising preventative health interest in countries like South Korea and Australia. |
| Premium Tier Introduction: Personalized nutrition services | Offers high-value, customized supplement regimens, moving beyond standard product sales. |
Research Approach
Multiple input streams — primary interviews, secondary research, and econometric modeling — were reconciled to construct a comprehensive market view. This involved combining insights from industry stakeholders with validation against published data. The study engaged supplement manufacturers, ingredient suppliers, regulatory experts, and pharmacy chain buyers to gather granular market intelligence.
Historical market performance was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, active ingredient, distribution channel, target demographic, and regional demand patterns. Compound annual growth rates were derived from an analysis of market growth drivers, restraints, and the competitive landscape. Consumer health trends and regulatory changes for health claims served as critical forecast inputs.
Botanical supply disruptions, new regulatory mandates, and shifts in consumer health priorities are the dominant revision risks for these market forecasts. Forecasts reflect a documented set of assumptions regarding market evolution and technological adoption. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Diabetes Supplements Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Mens Health Supplements Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Global Beauty Supplements Market
Dietary Supplements
Glucosamine Salt Market
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Vitamin D Deficiency Treatment Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Global Vitamin D Therapy Market