
 Global Broadband Services Market | 2026-2036
Global Broadband Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Broadband Services Market Foresight
The EU Electronic Communications Code is consolidating wholesale access obligations across member states, forcing infrastructure unbundling that lowers barriers for new retail providers. AT&T leverages its fiber footprint to sustain metro dominance in the United States. Deutsche Telekom anchors European expansion through open-access fiber platforms in Germany and adjacent markets.
Broadband services deliver high-speed internet access through wireline and wireless transmission technologies, typically defined by minimum throughput thresholds of 25 Mbps download and 3 Mbps upload under FCC benchmarks. Fiber optic deployment leads capital allocation due to superior latency and symmetrical bandwidth, while fixed wireless access captures fastest-growth status where trenching costs prove prohibitive. DSL segments occupy mature, declining positions as operators sunset copper infrastructure. Gigabit Ethernet and passive optical network technologies concentrate margin pools in enterprise and wholesale tiers.
The FCC in the United States enforces broadband speed benchmarks and rural deployment subsidies through the Universal Service Fund, while EMA and national regulators across Europe monitor net neutrality and wholesale pricing transparency. India's TRAI imposes tariff floors and interconnection rules that shape competitive intensity among mobile and fixed providers. Stakeholders must monitor spectrum auction outcomes and open-access regulatory rulings as determinants of capital efficiency.
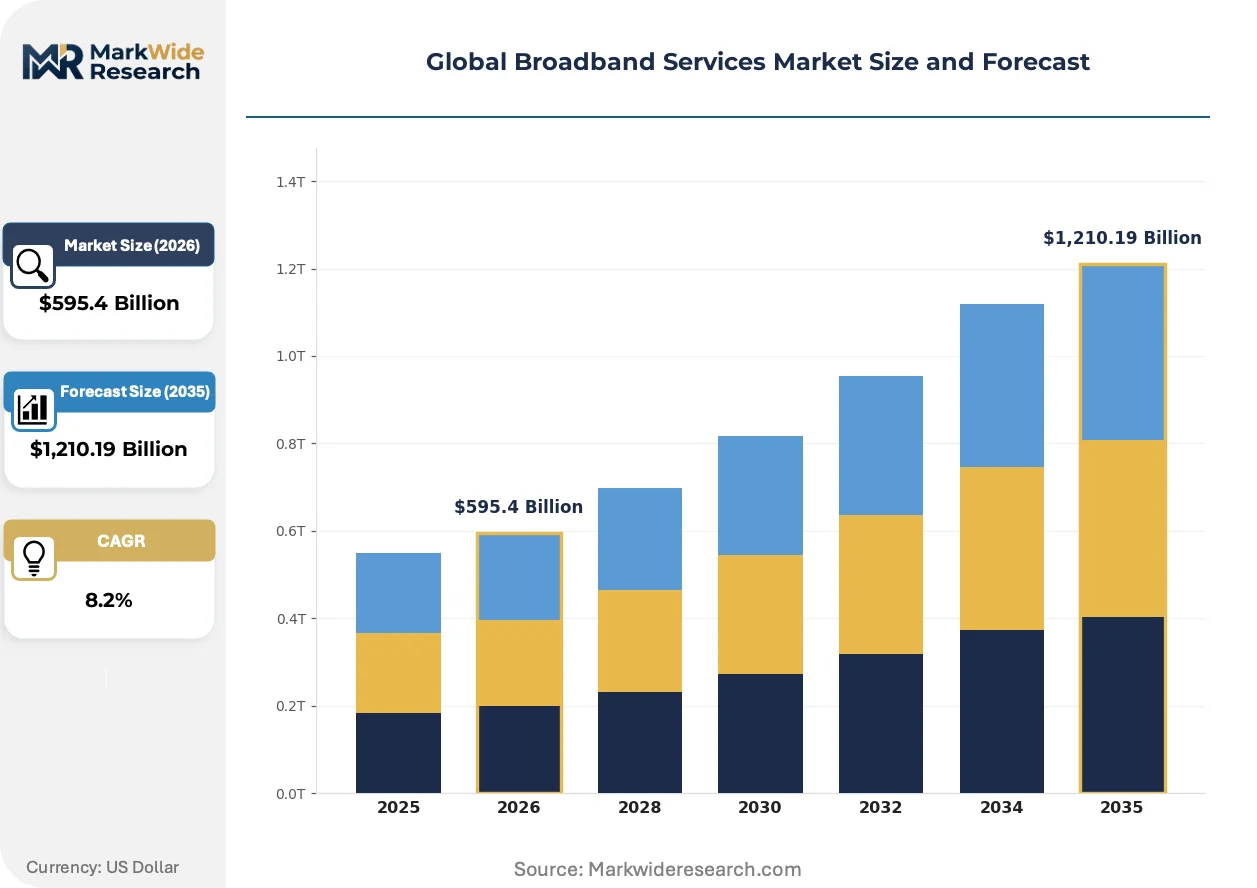
Market Dynamics
Open-access fiber mandates across the European Union are consolidating wholesale access economics and forcing infrastructure unbundling, while fiber-to-the-home deployment accelerates in India and Brazil, creating divergent competitive pressures between regulated European markets and emerging economies with government-backed rural connectivity programs.
Growth Catalysts
- EU Electronic Communications Code:Wholesale access obligations lower barriers for new retail providers, expanding addressable market for infrastructure-light entrants across member states.
- Fixed Wireless Access:Where trenching costs prove prohibitive, FWA captures fastest-growth status by bypassing last-mile fiber construction entirely.
- India:Reliance Jio and BharatNet initiatives compress rural-to-urban connectivity gaps, concentrating subscriber additions in urban corridors.
Market Restraints
- Copper infrastructure sunsetting:DSL segments occupy mature, declining positions as operators face stranded asset costs during technology transitions.
- Right-of-way regulations:Municipal permitting delays and pole attachment disputes extend fiber deployment timelines in dense urban environments.
- Geographic concentration of trenching capacity:Specialized fiber installation crews cluster in metropolitan regions, creating supply bottlenecks for rural builds.
Strategic Opportunities
- Brazil:Residential fiber optic deployment accelerates among subscriber bases previously served by coaxial or wireless alternatives.
- Gigabit Ethernet convergence:Enterprise and wholesale tiers concentrate margin pools as symmetrical bandwidth demands from cloud services reshape service tiering.
- Passive Optical Network technology:Splitter architecture reduces optical line terminal port costs, enabling denser subscriber economics in greenfield deployments.
Industry Challenges
- Fiber splicing technician shortage:Specialized fusion splicing and optical time-domain reflectometry skills constrain deployment velocity across multiple markets.
- Interconnection tariff complexity:India's TRAI-mandated floors and termination charges create pricing rigidities that compress retail margin flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Broadband Services Market |
| Market Size in 2026 | $595.4 Billion |
| Market Size in 2035 | $1,210.19 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fiber Optic, DSL, Cable Modem, Satellite, Fixed Wireless, 5G Customer Type: Residential, Small Office Home Office, Large Enterprise, Government, Educational Institutions Technology: Asymmetric Digital Subscriber Line, Gigabit Ethernet, Passive Optical Network, Cable Broadband, Millimeter Wave, LTE Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Telecom Operators, Value Added Resellers |
| Companies Covered | AT&T, Comcast Corporation, Verizon Communications, China Mobile, Deutsche Telekom, Charter Communications, Reliance Jio, Orange S.A., Vodafone Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Broadband Services Market Shifts & Advancements
Network function virtualization and software-defined access are decoupling hardware from service delivery, enabling operators to compress provisioning cycles and introduce service tiers without physical infrastructure swaps.
XGS-PON technology is modularizing optical access platforms by allowing operators to upgrade bandwidth symmetrically to 10 Gbps without replacing passive optical splitters or outside plant fiber. Tier-1 operators in Germany and the United States are standardizing on XGS-PON for new greenfield builds, with Deutsche Telekom and AT&T both selecting the technology for metro fiber overbuilds. This modularization compresses upgrade cycles from decade-long hardware refreshes to software-configurable capacity expansions.
The FCC's broadband speed benchmark enforcement through the Universal Service Fund is redirecting subsidy eligibility toward fiber and high-capacity fixed wireless, disqualifying legacy DSL from rural deployment support. Infrastructure operators must now certify 100/20 Mbps minimums to access funding pools, accelerating copper retirement timelines. Rural electric cooperatives in the United States are responding by forming broadband subsidiaries to capture these capital injections.
Enterprise procurement of managed Wi-Fi and security bundles is displacing standalone connectivity contracts, with buyers consolidating vendor relationships around integrated service platforms. Channel partners and system integrators capture increasing share of customer lifecycle value, particularly in multi-dwelling unit and hospitality verticals. This bundling trend is most visible in United States metropolitan markets where property managers negotiate master service agreements covering entire building portfolios.
Global Broadband Services Market Segmentation
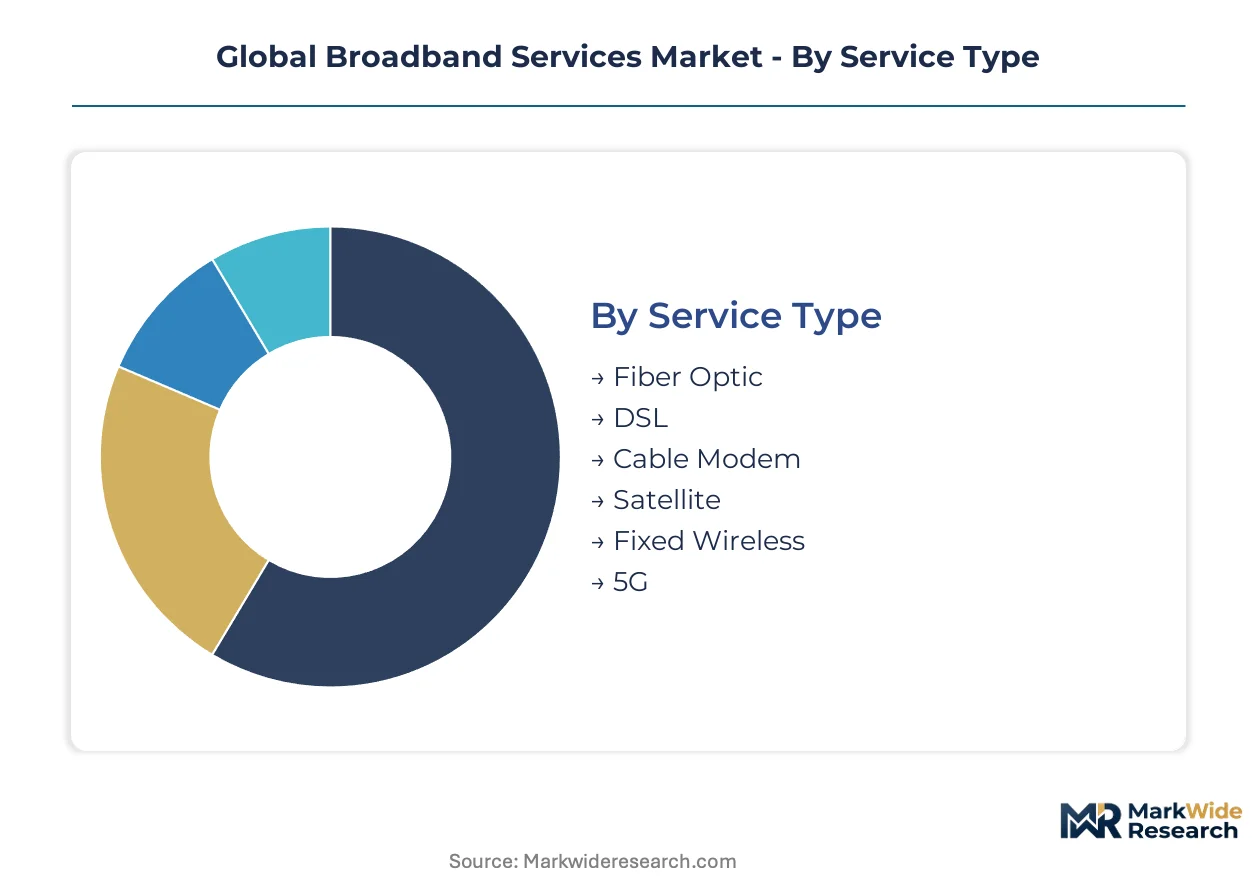
Broadband service segmentation reveals divergent capital allocation patterns across infrastructure technologies and customer tiers. Operators prioritize fiber-to-the-home for residential density while reserving fixed wireless for rapid enterprise deployment in underserved corridors.
Service Type:
Technology performance specifications define competitive positioning across last-mile delivery methods.
- Fiber Optic:Symmetrical bandwidth delivery through glass-core transmission enables gigabit-plus throughput with sub-5ms latency. Deployment concentrates in urban corridors of India and Brazil where government subsidies and private capital align on greenfield construction.
- Fixed Wireless:Point-to-multipoint radio links bypass trenching requirements entirely, capturing subscriber additions where fiber construction economics fail. Regulatory clarity on spectrum allocation determines deployment velocity across municipal jurisdictions.
- DSL:Copper-pair infrastructure occupies sunset status as operators face stranded asset costs during technology transitions.
- Cable Modem:Hybrid fiber-coaxial architecture delivers asymmetric bandwidth through shared spectrum allocation.
- Satellite:Geostationary and low-earth-orbit constellations serve ultra-rural pockets beyond terrestrial infrastructure reach.
- 5G:Millimeter-wave and sub-6GHz cellular networks enable fixed wireless substitution with higher mobility integration.
Fiber Optic leads on scale; Fixed Wireless leads on momentum.
Customer Type:
Revenue concentration varies sharply by contract value, installation complexity, and service-level agreement requirements.
- Residential:Mass-market subscriptions generate volume economics through standardized installation and self-service provisioning. Reliance Jio and BharatNet initiatives in India compress rural-to-urban connectivity gaps, concentrating subscriber additions in dense urban corridors.
- Large Enterprise:Dedicated fiber circuits with guaranteed throughput and latency SLAs command premium pricing. Cloud service dependency drives symmetrical bandwidth procurement across financial services and healthcare verticals.
- Small Office Home Office:Hybrid work permanence sustains demand for business-grade reliability in residential-scale packages.
- Government:Universal service obligations and rural connectivity mandates shape procurement specifications and subsidy eligibility.
- Educational Institutions:Campus-wide Wi-Fi backhaul and e-learning infrastructure requirements drive bulk bandwidth contracts.
Residential dominates addressable market breadth; Large Enterprise dominates margin contribution.
Technology:
Protocol standards determine upgrade pathways, equipment interoperability, and vendor lock-in exposure.
- Passive Optical Network:Splitter architecture reduces optical line terminal port costs through shared infrastructure. XGS-PON standardization enables symmetrical 10 Gbps upgrades without outside plant replacement, with Deutsche Telekom and AT&T selecting the technology for metro fiber overbuilds.
- Gigabit Ethernet:Dedicated fiber connectivity delivers uncontended bandwidth for latency-sensitive applications. Enterprise and wholesale tiers concentrate margin pools as symmetrical demands from cloud services reshape service tiering.
- Asymmetric Digital Subscriber Line:Copper-pair modulation occupies mature, declining positions as operators sunset legacy infrastructure.
- Cable Broadband:DOCSIS protocol evolution extends coaxial lifespan through spectrum efficiency improvements.
- Millimeter Wave:High-frequency radio links enable dense urban capacity without fiber trenching.
- LTE:4G cellular infrastructure provides fallback coverage and rural fixed wireless substitution.
Passive Optical Network anchors greenfield deployment; Gigabit Ethernet commands premium tier pricing.
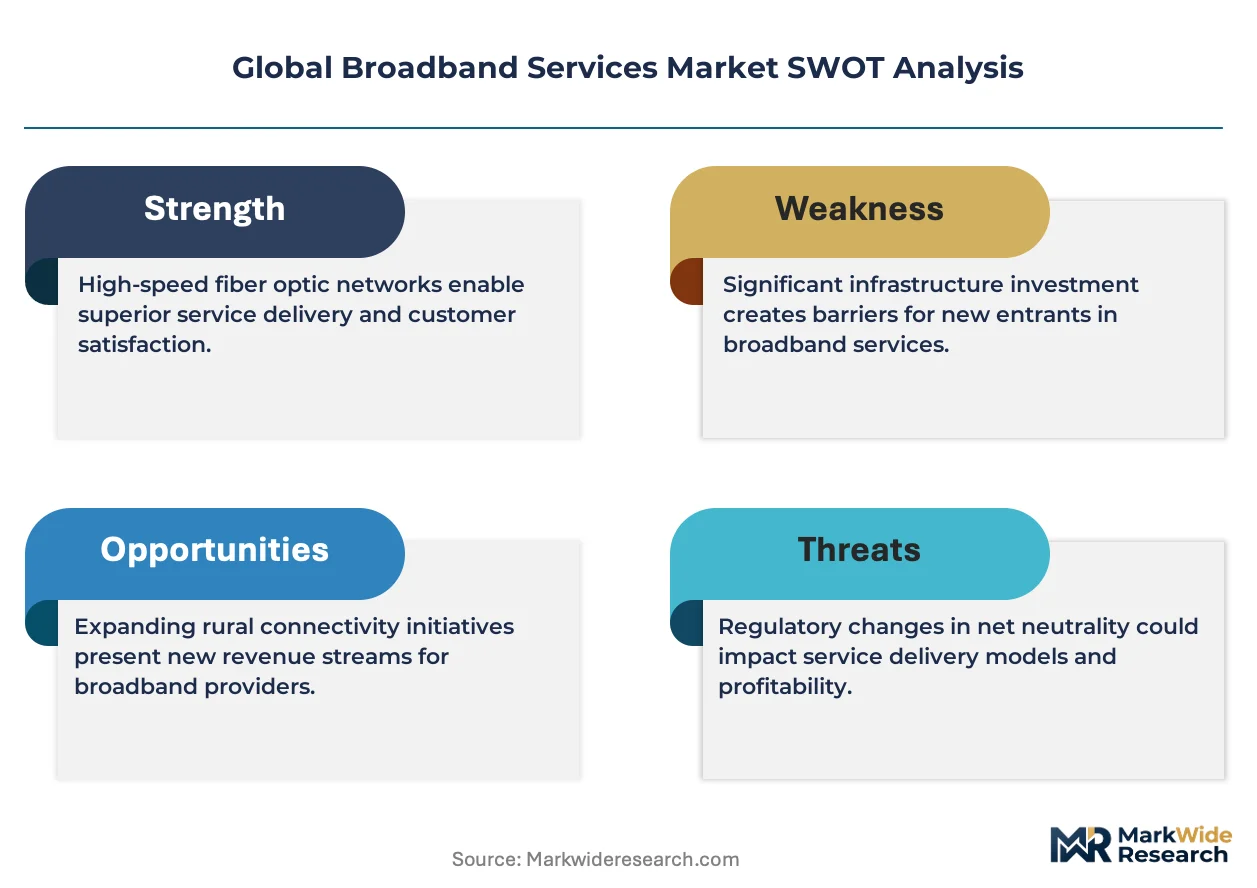
Distribution Channel:
Channel economics determine customer acquisition costs and lifecycle value capture.
- Telecom Operators:Vertically integrated providers bundle connectivity with mobile, television, and managed services. Master service agreements with property managers in United States metropolitan markets consolidate entire building portfolios under single-vendor relationships.
- Online Platforms:Digital-native provisioning compresses sales cycles and enables self-service tier selection. Channel partners and system integrators capture increasing share of customer lifecycle value through managed Wi-Fi and security bundles.
- Direct Sales:Enterprise-focused field teams negotiate custom SLAs and dedicated circuit installation.
- Retail Stores:Physical presence supports consumer education and equipment distribution in markets with low digital literacy.
- Value Added Resellers:System integrators layer managed services atop connectivity for multi-dwelling unit and hospitality verticals.
Telecom Operators retain scale advantage; Online Platforms gain share fastest in digitally mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadband infrastructure originated in the United States through cable television network repurposing and early DSL deployments, with subsequent scaling across Western Europe and East Asia through government-subsidized fiber programs. Market development now diverges between mature economies retiring legacy copper and emerging markets building greenfield fiber-to-the-home networks.
United States
Metro fiber overbuilds concentrate subscriber growth in dense urban corridors, while rural electric cooperatives form broadband subsidiaries to capture Universal Service Fund capital injections. The FCC enforces 100/20 Mbps minimums for subsidy eligibility, accelerating copper retirement timelines. AT&T anchors deployment in Texas and California metro markets, with Charter Communications expanding hybrid fiber-coaxial capacity across the Southeast.
Germany
Deutsche Telekom's open-access fiber platforms reshape wholesale access economics across German metro regions and adjacent Central European markets. The EU Electronic Communications Code mandates infrastructure unbundling, lowering barriers for retail providers entering Bavaria and North Rhine-Westphalia. Industrial clusters around Munich and Stuttgart drive enterprise gigabit Ethernet procurement for manufacturing automation.
India
Reliance Jio's aggressive fiber-to-the-home pricing compresses rural-to-urban connectivity gaps, concentrating subscriber additions in Maharashtra and Karnataka urban corridors. TRAI imposes tariff floors and interconnection rules that shape competitive intensity among fixed and mobile providers. BharatNet government initiatives extend optical fiber to village panchayats across Gujarat and Tamil Nadu.
Brazil
Residential fiber optic deployment accelerates among subscriber bases previously served by coaxial or wireless alternatives, particularly in São Paulo and Rio de Janeiro metropolitan regions. ANVISA and national telecommunications regulators monitor wholesale pricing transparency for infrastructure access. Specialized fiber installation crews cluster in southeastern states, creating supply bottlenecks for northern and northeastern rural builds.
China
China Mobile anchors massive-scale fiber deployment through government-coordinated infrastructure programs, with MIIT setting aggressive gigabit city targets across Yangtze River Delta and Pearl River Delta clusters. Dual carbon goals reshape equipment procurement specifications toward energy-efficient optical line terminals. Shenzhen and Hangzhou metro regions concentrate passive optical network manufacturing and deployment expertise.
Global Broadband Services Market Competitive Landscape
The competitive structure tilts toward vertically integrated telecom operators with deep infrastructure ownership and government-aligned national champions with subsidized deployment capacity. Market concentration varies sharply by geography: fragmented retail competition overlays consolidated wholesale infrastructure in European open-access regimes, while emerging markets exhibit duopolistic fiber deployment. Three archetypes dominate—incumbent telecom operators with legacy copper transitions, cable operators leveraging hybrid fiber-coaxial upgrades, and mobile-first entrants building fixed wireless and fiber convergence. Dominant competitive moves include fiber footprint expansion through municipal franchise negotiations and strategic partnerships with property managers for multi-dwelling unit master service agreements.
Within the incumbent operator tier, Deutsche Telekom and Orange S.A. exemplify European open-access platform strategies, while AT&T represents North American metro fiber concentration. Among mobile-first disruptors, Reliance Jio occupies a distinctive position bridging India's rural connectivity mandates with urban fiber economics. These three anchors illustrate divergent capital allocation patterns—European wholesale infrastructure unbundling, U.S. metro density exploitation, and emerging market government-partnered greenfield construction.
| Leading Market Players |
|---|
| AT&T |
| Comcast Corporation |
| Verizon Communications |
| China Mobile |
| Deutsche Telekom |
| Charter Communications |
| Reliance Jio |
| Orange S.A. |
| Vodafone Group |
| Others |
Supply & Pricing Matrix
Sovereign-backed national champions and private-equity-rolled-up fiber specialists anchor capital deployment patterns across broadband infrastructure markets, concentrating supply-side pricing power in metropolitan construction corridors while government subsidy programs compress rural deployment margins through mandated tariff floors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments residential subscriptions by bandwidth tier and service-level guarantees, with fiber-to-the-home commanding premium positioning over fixed wireless and legacy DSL. Price differentiation rests on latency specifications and symmetrical upload capacity, while cost compression in economy tiers intensifies due to Reliance Jio's aggressive subscriber acquisition pricing in India. Small office home office segments exhibit highest price sensitivity; large enterprise buyers prioritize SLA reliability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for optical line terminals and passive optical network equipment concentrate refurbishment activity in Shenzhen and Hangzhou manufacturing clusters, with secondary markets emerging for decommissioned DSL infrastructure across Eastern Europe. Component sourcing draws from Chinese optical component foundries, Japanese precision laser manufacturers, and German fiber splicing equipment specialists. Single-source vulnerability in specialized fusion splicing technician labor constrains deployment velocity. Distribution runs through vertically integrated telecom operators and value-added resellers layering managed services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Electronic Communications Code's wholesale access mandates compound addressable market expansion for infrastructure-light entrants, forcing unbundling economics that reshape competitive positioning across member states.
For Market Incumbents: Deploy open-access fiber platforms to monetize passive infrastructure while containing retail margin erosion from unbundling mandates. Defensive consolidation through municipal franchise negotiations secures multi-dwelling unit master service agreements against fixed wireless substitution threats. Capacity addition in India and Brazil greenfield corridors captures government-subsidized rural connectivity programs. For New Entrants and Emerging Players: Capture underserved enterprise corridors in Brazil's northern and northeastern states where fiber installation crew shortages delay incumbent deployment schedules. White-space targeting of small office home office managed Wi-Fi bundles displaces standalone connectivity contracts in United States metropolitan markets. Channel partnership with property managers enables rapid building portfolio penetration without franchise negotiation delays. For Investors and Strategic Acquirers: Valuations sit cheapest among rural electric cooperative broadband subsidiaries capturing Universal Service Fund capital injections. Long-term viability framing centers on fiber footprint density in metro corridors with enterprise gigabit Ethernet concentration. Monitor FCC broadband speed benchmark enforcement as inflection indicator for copper retirement acceleration and subsidy eligibility redirection.| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Platform Standardization | Deutsche Telekom and AT&T selections validate modular upgrade pathways without outside plant replacement. |
| Municipal Franchise Negotiation | Master service agreements with property managers consolidate multi-dwelling unit portfolios under single-vendor relationships. |
| Fixed Wireless Access Deployment | Spectrum auction outcomes determine deployment velocity where trenching economics fail in rural corridors. |
| Managed Wi-Fi Bundle Integration | Channel partners capture increasing customer lifecycle value in hospitality and multi-dwelling verticals. |
| Rural Electric Cooperative Subsidiary Formation | Universal Service Fund eligibility redirects capital injections toward fiber and high-capacity fixed wireless. |
Research Methodology
Direct dialogue with network planning executives, wholesale access managers, regulatory affairs specialists, and fiber construction contractors combined with secondary validation against FCC Universal Service Fund disbursement records, TRAI tariff filings, EU Electronic Communications Code implementation directives, and operator capex disclosures. Bottom-up subscriber addition modeling triangulates against top-down infrastructure investment forecasts.
Bottom-up demand modeling aggregates service-tier subscriptions by technology and customer segment, while top-down analysis benchmarks capital deployment against regulatory subsidy pools across the projection horizon. Segmentation dimensions include service type, customer tier, protocol standard, and distribution channel. CAGRs derive from subscriber growth trajectories and average revenue per user compression patterns, with inputs from spectrum auction schedules and open-access platform rollout timelines.
Spectrum allocation delays, municipal permitting disputes, and fiber splicing technician labor shortages are the dominant revision risks to deployment velocity assumptions. Practitioners should monitor right-of-way regulation changes and wholesale pricing transparency rulings for early signals of competitive intensity shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Ireland Telecom Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Global 4G LTE Market
Telecommunications
Telecom Services Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Satcom Terminal Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Mexico Telecom Market
Telecommunications
Singapore MVNO Market
Telecommunications
Global Esim Market
Telecommunications
DECT System Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
France Telecom Market
Telecommunications
Tetra Terminals Market