
 Online Tutoring Market | 2026-2036
Online Tutoring Market Size, Share, and Industry Trends Forecast 2026-2036
Online Tutoring Market Analysis
India's ed-tech infrastructure build-out is rewriting competitive dynamics for live instruction delivery. Byju's leverages its content library depth to anchor premium positioning in competitive exam preparation. Varsity Tutors sustains marketplace liquidity through geographic density in U.S. metropolitan areas. Chegg Inc. differentiates by integrating AI-assisted homework tools with human tutor escalation pathways.
Online tutoring denotes synchronous and asynchronous educational instruction delivered through internet-connected platforms, typically incorporating video streaming, digital whiteboards, file sharing protocols, and session recording for knowledge reinforcement and progress tracking. Its primary purpose is to provide personalized academic support, skill remediation, and test readiness outside traditional institutional schedules. Test preparation services command premium pricing due to high-stakes outcome sensitivity among college-bound students. Mobile app platforms are capturing the fastest growth trajectory as smartphone-first learners in emerging economies bypass desktop dependency. Group classes concentrate margin pressure on per-student economics while scaling instructor utilization rates.
The U.S. Department of Education enforces FERPA compliance requirements that constrain how tutoring platforms handle student performance data and communication records. India's BIS certification mandates and CDSCO-adjacent quality benchmarks for educational technology content are raising market access barriers for unverified foreign operators. The EU GDPR framework imposes strict consent protocols on data collection from minor users, directly affecting platform registration flows and parental permission architectures. Stakeholders must monitor regulatory divergence across jurisdictions to determine whether to pursue unified platform architectures or market-specific compliance builds.
Market Dynamics
Live instruction platforms face margin compression as generative AI tools automate homework assistance and assessment grading, forcing incumbents to restructure tutor compensation models and session pricing architectures.
Growth Catalysts
- K-12 Digital Procurement:United States school districts are expanding supplemental instruction contracts to address learning loss recovery mandates. Federal ESSER fund allocations sustain multi-year platform licensing agreements.
- EU AI Act Compliance:Algorithmic transparency requirements for educational content recommendation engines are accelerating platform investments in explainable AI architectures. Operators restructuring systems gain competitive positioning in European markets.
- Smartphone-First Learners:Mobile-native instruction delivery in India captures urban middle-class households bypassing desktop infrastructure. Compressed data consumption and regional language interfaces drive subscription conversion.
Market Restraints
- Instructor Supply Volatility:Qualified STEM tutors command wage premiums exceeding platform gross margins. Freelance marketplaces face retention erosion as top performers migrate to direct-to-consumer arrangements.
- Data Localization Mandates:India's draft data protection framework and Russia's server requirements fragment cloud infrastructure investments. Multi-jurisdiction operators absorb redundant hosting costs.
- Free Substitute Proliferation:YouTube tutorial libraries and open-source Khan Academy resources constrain pricing power in foundational subject categories. Premium positioning requires differentiated outcome guarantees.
Strategic Opportunities
- Corporate Reskilling Contracts:Enterprise learning and development budgets are absorbing executive coaching and technical certification programs. B2B procurement channels offer annual recurring revenue stability absent in consumer subscriptions.
- Neurodivergent Instruction Design:Specialized platforms serving ADHD and autism spectrum learners address underserved demand. Regulatory recognition of accessibility standards in the United States and United Kingdom creates procurement preferences.
- AI-Human Escalation Protocols:Hybrid models routing automated tutoring to live instructors based on confusion detection capture price-insensitive segments. Technical integration of natural language processing with video streaming infrastructure differentiates platform economics.
Industry Challenges
- FERPA Compliance Architecture:United States K-12 platforms must engineer granular parental consent workflows and data deletion protocols. Development timelines extend 6-12 months for district procurement eligibility.
- Tutor Credential Verification:Cross-border instruction delivery faces authentication complexity for academic degrees and teaching licenses. Platform liability exposure increases with unverified instructor claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Tutoring Market |
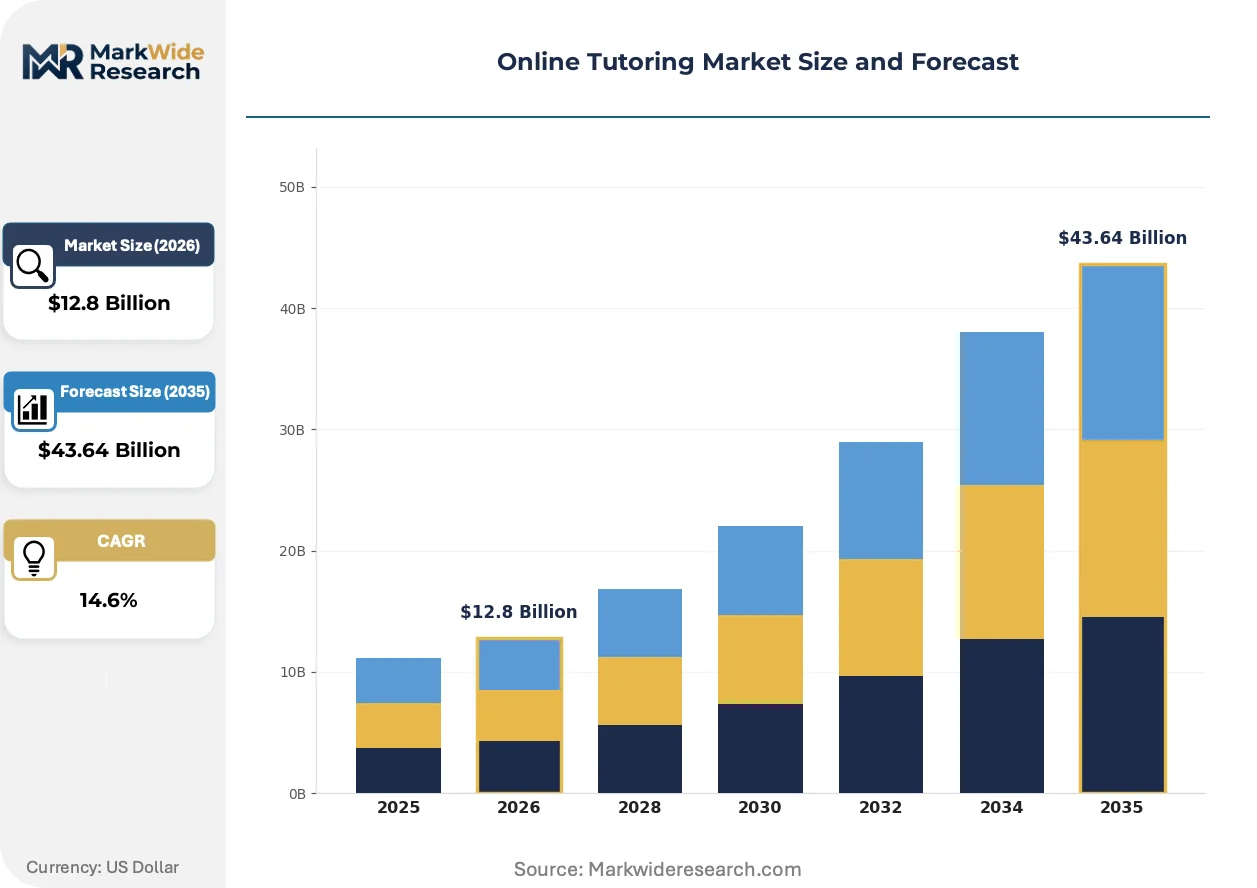
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: 1-on-1 Tutoring, Group Classes, Test Preparation, Homework Help Platform: Web-based, Mobile App, Video Conferencing, Interactive Whiteboard Subject Area: Math, Science, Language Arts, Computer Programming Target Audience: Elementary Students, High School Students, College Students, Adult Learners |
| Companies Covered | Kumon Institute of Education Co. Ltd., Varsity Tutors, Chegg Inc., TutorMe, Tutor.com, Byju's, Sylvan Learning Inc., Wyzant, Kaplan Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Tutoring Market Emerging Trajectories
Instruction delivery is fragmenting across synchronous video, asynchronous AI feedback, and immersive simulation environments. Platform operators are converging these modalities into unified learner journeys.
Immersive virtual reality classrooms are virtualizing laboratory science and vocational training modules previously requiring physical equipment presence. Technical universities in South Korea and Germany are piloting haptic feedback integration for engineering disciplines. Hardware cost curves and 5G latency improvements are virtualizing capital-intensive instruction formats at scale.
GDPR Article 8 implementations across European member states are mandating verifiable parental consent mechanisms for minor user registration. Platforms serving under-16 learners must reengineer onboarding flows with multi-step verification architectures. German and French regulators are enforcing the strictest interpretations, delaying product launches for non-compliant operators.
Subscription fatigue among Indian urban households is compressing annual contract durations toward monthly or session-pack models. Test preparation segments retain longer commitments due to examination date certainty. Platform revenue predictability is deteriorating as consumer preference rotates toward pay-per-use flexibility over auto-renewal obligations.
Online Tutoring Market Segmentation
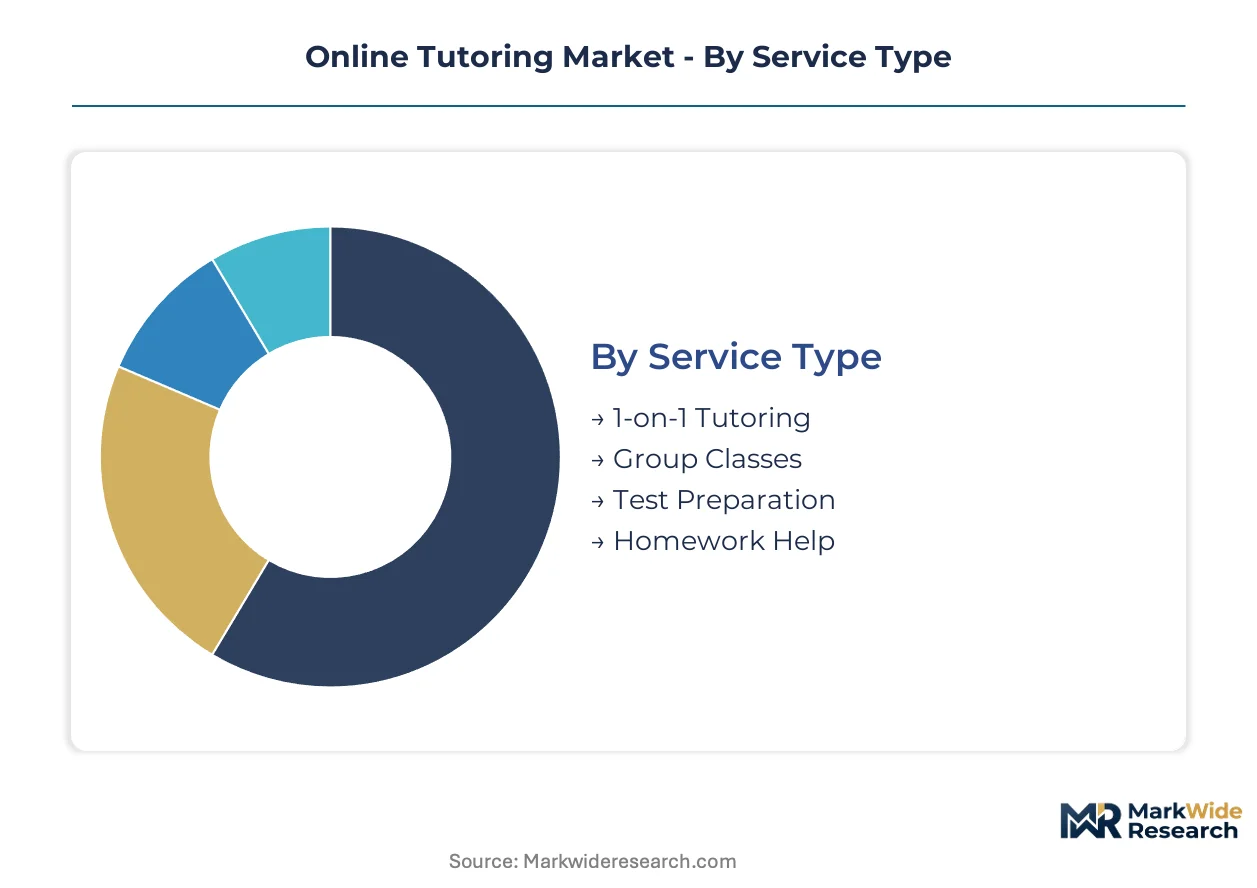
Service configuration and platform architecture determine unit economics and customer acquisition costs in online tutoring. Segment boundaries blur as hybrid delivery models merge synchronous instruction with automated feedback loops.
Service Type:
Instruction intensity varies from personalized remediation to scalable group formats, with pricing power correlating to outcome accountability.
- 1-on-1 Tutoring:Dedicated instructor-learner sessions command premium rates based on customized pacing and immediate error correction. Demand concentrates among affluent households in India and the United States preparing for competitive examinations where score improvements justify per-hour premiums.
- Test Preparation:High-stakes examination readiness services bundle diagnostic assessment, curriculum alignment, and progress analytics. College-bound students in South Korea and China sustain multi-month commitments due to rigid examination calendars and university admission thresholds.
- Group Classes:Scalable cohort instruction spreads instructor costs across 8-25 learners, compressing per-student pricing. Margin pressure intensifies as platforms compete on class size and peer matching quality.
- Homework Help:On-demand problem-solving assistance targets immediate academic support needs. Freemium models struggle with conversion as generative AI tools substitute for foundational query resolution.
The dominant share belongs to 1-on-1 Tutoring, while Test Preparation is closing the gap fastest.
Platform:
Technical infrastructure choices shape geographic reach and session fidelity requirements.
- Mobile App:Smartphone-native delivery captures first-time internet users in emerging economies with compressed data footprints. Urban middle-class households in India and Indonesia drive subscription conversion through regional language interfaces and offline content caching.
- Video Conferencing:Real-time audiovisual streaming remains the default modality for relationship-dependent instruction. Bandwidth constraints in rural Brazil and Nigeria limit addressable market penetration without adaptive bitrate protocols.
- Web-based:Browser-accessible platforms reduce friction for institutional procurement requiring no device installation. United States school district IT policies favor this architecture for security audit compliance.
- Interactive Whiteboard:Collaborative canvas tools enable visual problem-solving in mathematics and diagram-heavy sciences. Technical integration complexity elevates development costs relative to commodity video infrastructure.
Mobile App platforms are expanding most quickly, while Video Conferencing retains the largest installed base.
Subject Area:
Curriculum alignment and instructor credential requirements fragment competitive dynamics across disciplines.
- Math:Symbolic notation and step-by-step reasoning demand specialized digital whiteboard tools. Automated grading engines from Carnegie Learning and similar providers compress pricing for foundational arithmetic through algebra.
- Computer Programming:Code execution environments and project-based portfolios attract adult career switchers. Corporate reskilling contracts in Germany and Poland sustain B2B procurement volumes.
- Science:Laboratory simulation and visual demonstration requirements elevate platform technical specifications. Virtual reality pilots in South Korean technical universities address equipment access inequality.
- Language Arts:Writing feedback and literary analysis resist full automation, preserving human instructor value. Parental demand in China's tier-one cities drives premium positioning for native speaker conversation practice.
Math commands the dominant share, while Computer Programming is climbing the fastest.
Target Audience:
Developmental stage determines session duration tolerance, parental involvement intensity, and payment authority.
- High School Students:Examination pressure and college admission timelines concentrate demand in structured test preparation formats. United States districts allocate ESSER funds toward supplemental instruction for learning loss recovery.
- Elementary Students:Foundational skill remediation requires gamification and parental oversight interfaces. GDPR Article 8 compliance mandates complicate European platform registration flows for this cohort.
- College Students:Course-specific tutoring and career certification support attract self-funded learners with flexible scheduling needs. Subscription fatigue compresses contract durations toward pay-per-use models.
- Adult Learners:Professional reskilling and executive coaching command enterprise procurement budgets. Outcome-based pricing structures align platform incentives with certification completion rates.
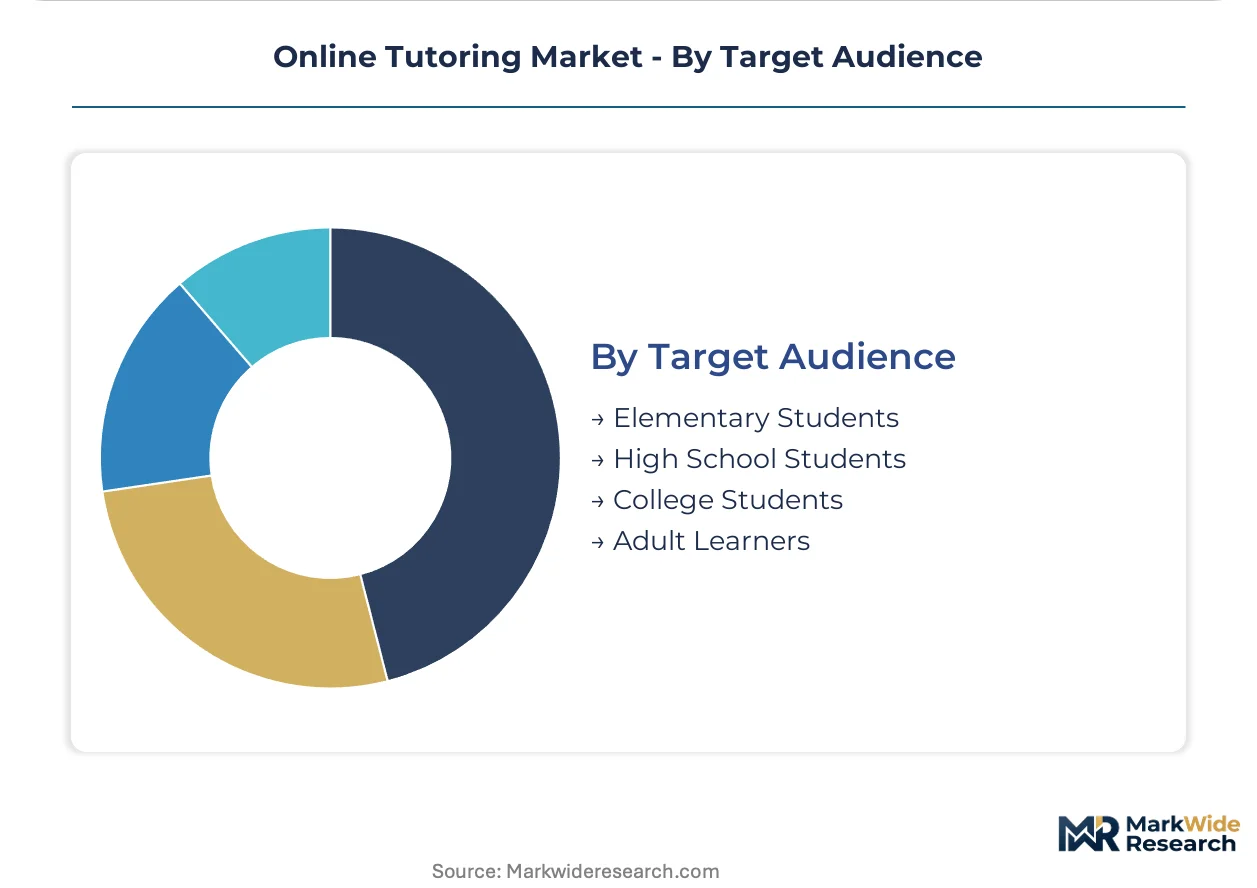
High School Students represent the dominant segment, while Adult Learners are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States households prioritize 1-on-1 test preparation with human instructor accountability. Indian families favor mobile-first STEM subscriptions at compressed price points. European procurement emphasizes GDPR-compliant institutional licensing over direct-to-consumer models.
United States
K-12 school districts channel ESSER funds into multi-year supplemental instruction contracts. FERPA compliance mandates granular parental consent workflows and data deletion protocols. Platform operators in California and Texas metropolitan areas compete for district procurement eligibility through security audit certifications.
India
Urban middle-class households in Delhi-NCR and Mumbai drive paid subscription growth for competitive exam preparation. BIS certification requirements and CDSCO-adjacent quality benchmarks raise market access barriers for unverified foreign operators. Byju's leverages content library depth to anchor premium positioning in Bangalore and Hyderabad.
Germany
Technical universities pilot immersive virtual reality classrooms for engineering disciplines requiring laboratory access. GDPR Article 8 implementations mandate verifiable parental consent mechanisms for minor user registration. Haptic feedback integration pilots concentrate in Munich and Stuttgart industrial clusters.
South Korea
Hagwon culture sustains multi-month commitments for high-stakes college admission examinations. MFDS-aligned quality frameworks shape educational technology procurement standards. Seoul-based platforms virtualize capital-intensive science instruction through 5G-enabled streaming infrastructure.
United Kingdom
Regulatory recognition of accessibility standards creates procurement preferences for neurodivergent instruction design. GDPR consent protocols complicate platform registration flows for elementary-age learners. London and Southeast England concentrate executive coaching and professional reskilling contract volumes.
Online Tutoring Market Vendor Landscape
Capability concentration sits with specialized content libraries and AI-human escalation protocols; scale advantage sits with geographic density and institutional procurement relationships. The market structures around three tiers: legacy test preparation incumbents, mobile-native emerging economy platforms, and AI-augmented homework assistance tools. Strategic moves center on restructuring tutor compensation models and pursuing corporate reskilling contracts for revenue stability.
Within the mobile-native platform tier, Byju's exemplifies content-anchored premium positioning through competitive exam preparation depth. Among AI-augmented service providers, Chegg Inc. and TutorMe occupy positions emphasizing automated homework tools with human escalation pathways. Varsity Tutors represents marketplace liquidity models sustained through metropolitan geographic density.
| Leading Market Players |
|---|
| Kumon Institute of Education Co. Ltd. |
| Varsity Tutors |
| Chegg Inc. |
| TutorMe |
| Tutor.com |
| Byju's |
| Sylvan Learning Inc. |
| Wyzant |
| Kaplan Inc. |
| Others |
Supply Flow & Price Mechanics
Bangalore's instructor marketplace density shapes downstream pricing power for live STEM instruction. Platform operators in India's ed-tech cluster absorb wage premiums from qualified tutors while compressing consumer-facing subscription rates to sustain urban middle-class conversion.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement in United States K-12 districts, while spot session purchases concentrate in direct-to-consumer markets. Three-tier pricing structure across premium, standard, and economy levels separates certified exam preparation from automated homework assistance and peer-to-peer marketplace matching. Cost compression in economy tiers is intensifying because generative AI tools substitute for foundational query resolution. College-bound students in South Korea and China exhibit least price sensitivity due to rigid university admission thresholds, while subscription fatigue among Indian urban households drives highest sensitivity toward monthly or session-pack flexibility.
Supply Chain Analysis
Upstream feedstock of qualified STEM instructors draws from India, the Philippines, and Eastern European university systems. Platform infrastructure rests on cloud computing capacity, video streaming codecs, and interactive whiteboard software licenses. Single-source vulnerability concentrates in specialized tutor credential verification services that cross-border operators depend on for district procurement eligibility. Distribution runs through mobile app stores for emerging economy consumer segments and direct enterprise sales teams for corporate reskilling contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The online tutoring market represents high-growth disruption as generative AI forces restructuring of tutor compensation models and session pricing architectures across incumbent platforms.
For Market Incumbents: Pre-empt margin erosion by restructuring tutor compensation toward outcome-based models that align instructor incentives with student completion metrics. Invest in AI-human escalation protocols that route automated tutoring to live instructors based on confusion detection, preserving premium positioning against pure AI substitutes. Pursue backward integration into proprietary content libraries to reduce licensing costs and deepen competitive moats.
For New Entrants and Emerging Players: Build out neurodivergent instruction design capabilities serving ADHD and autism spectrum learners, where regulatory recognition of accessibility standards in the United States and United Kingdom creates procurement preferences. Target corporate reskilling contracts in Germany and Poland for technical certification programs, where enterprise learning and development budgets offer annual recurring revenue stability absent in consumer subscriptions. Deploy B2B sales teams with outcome-based pricing structures that align platform incentives with certification completion rates.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with demonstrated AI-human integration protocols and established institutional procurement relationships over pure marketplace liquidity plays. Long-term viability hinges on regulatory compliance architecture across FERPA, GDPR Article 8, and India's draft data protection framework. Monitor ESSER fund exhaustion timelines as inflection indicator for United States K-12 district contract renewal velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Human Escalation Protocol Development | Technical integration of NLP with video streaming differentiates platform economics against pure automation competitors. |
| Corporate Reskilling Contract Pursuit | B2B procurement channels in Germany and Poland offer revenue stability through enterprise technical certification programs. |
| Neurodivergent Instruction Design Investment | Regulatory recognition of accessibility standards creates procurement preferences in United States and United Kingdom markets. |
| Content Library Backward Integration | Proprietary curriculum depth anchors premium positioning in competitive exam preparation segments against licensed-content competitors. |
| GDPR Article 8 Compliance Architecture | Verifiable parental consent mechanisms enable product launch eligibility across German and French regulatory jurisdictions. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with platform executives, district procurement officers, and tutor marketplace operators; and secondary validation against SEC filings, App Annie mobile engagement metrics, and hyperscaler capex disclosures for cloud infrastructure trends. Bottom-up triangulation across service type, platform architecture, and target audience segmentation was cross-checked with top-down market sizing from federal ESSER fund allocation data and European regulatory compliance cost estimates.
Forecast inputs considered instructor supply elasticity, smartphone penetration curves, and AI substitution rates across foundational versus advanced instruction tiers. Segmentation dimensions modeled include service intensity, technical infrastructure choice, curriculum discipline, and learner developmental stage. CAGRs were derived from enrollment velocity trends and pricing power trajectories rather than simple extrapolation. Platform switching costs and parental payment authority patterns served as industry-specific forecast modifiers throughout the projection horizon.
Stress conditions across ESSER fund exhaustion timelines, GDPR enforcement variance across member states, and generative AI capability advancement were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against district procurement database trends and mobile app store revenue estimates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Digital Marketing Courses Market
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Online K-12 Education Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Massive Open Online Courses Market
Distance Learning and Online Education
E-Learning Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Europe Digital Education Market
Distance Learning and Online Education
GCC E-Learning Market
Distance Learning and Online Education
Global Digital Education Market