
 GCC E-Learning Market | 2026-2036
GCC E-Learning Market Size, Share, and Industry Trends Forecast 2026-2036
GCC E-Learning Market Intelligence
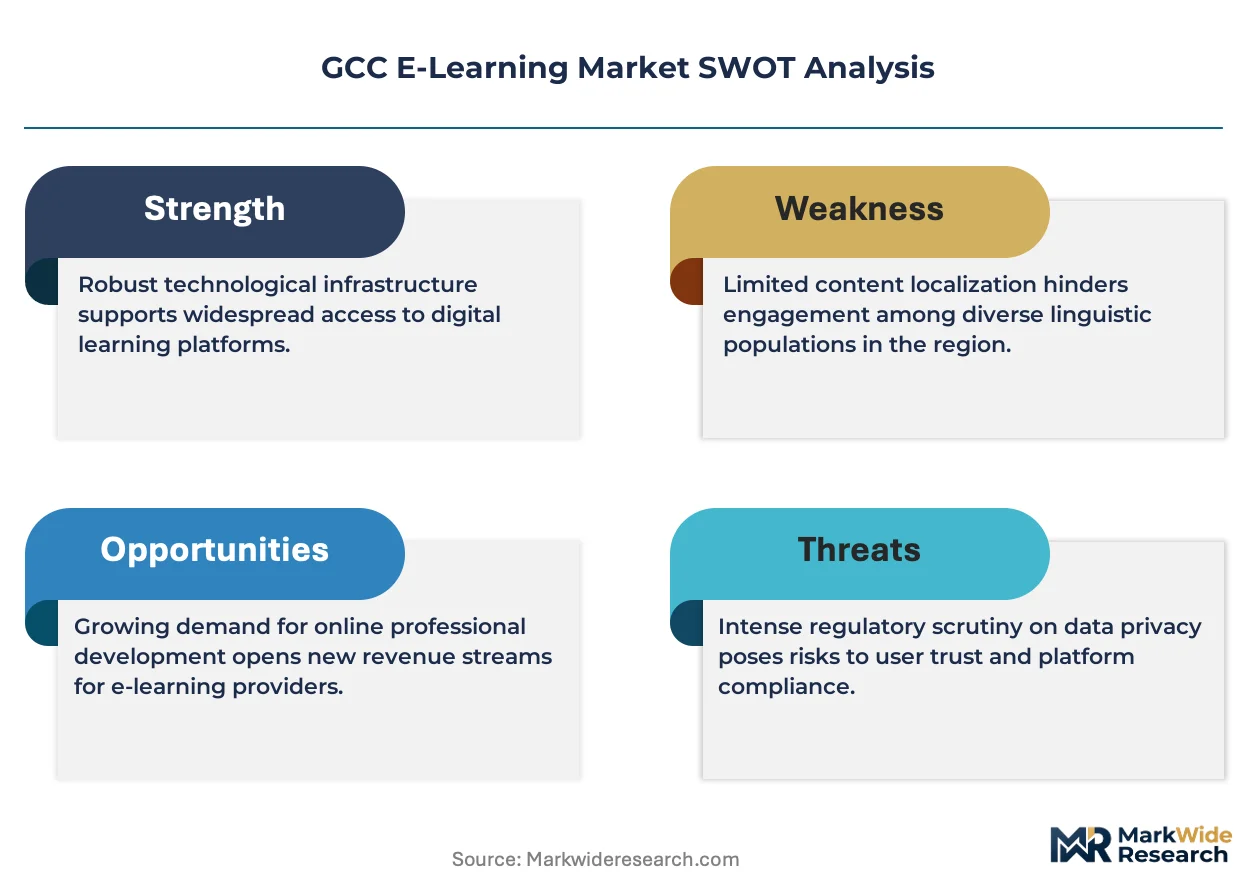
ISO 21001 certification for educational organizations is collapsing as a baseline market-access filter across the GCC. Pearson Plc leverages its institutional relationships to sustain premium content licensing across Saudi universities. Coursera Inc. competes aggressively on credential recognition with regional accreditation bodies. Simplilearn specializes in technology upskilling modules that anchor corporate training budgets in Dubai and Riyadh.
GCC e-learning encompasses digitally delivered educational content and training systems accessed through web platforms, mobile applications, and virtual classroom environments, typically requiring cloud infrastructure with sub-200ms latency thresholds and Arabic-English multilingual interfaces to serve dispersed learner populations across six member states. Its primary commercial purpose centers on workforce capability building and formal credentialing outside traditional campus boundaries. Virtual classrooms and mobile learning represent the fastest-expanding delivery modes as bandwidth infrastructure improves across the Gulf. AI-driven platforms command disproportionate R&D investment from vendors seeking to automate personalized learning pathways and predictive dropout interventions.
Saudi Arabia's Ministry of Education and the UAE's Ministry of Education enforce curriculum digitization mandates that directly shape platform procurement specifications and content localization requirements. Saudi Data and Artificial Intelligence Authority guidelines and UAE Information Assurance standards further constrain cross-border data handling and student privacy architectures. Stakeholders must monitor evolving national AI strategies that will determine which platform capabilities become compulsory versus merely preferred in upcoming government tenders.
Market Dynamics
National AI curriculum mandates across Saudi Arabia and the UAE are compressing platform procurement cycles while elevating technical specifications for adaptive learning engines and Arabic NLP capabilities.
Growth Catalysts
- Saudi Data and Artificial Intelligence Authority guidelines:Government tenders now require AI-driven personalization modules, forcing platform upgrades across K-12 procurement channels.
- Corporate training budgets in Dubai and Riyadh:Technology upskilling mandates at major employers are redirecting L&D spend toward certified digital credential programs.
- ISO 21001 certification collapse:The baseline quality standard is becoming table stakes, opening procurement to specialized vendors with narrower vertical expertise.
Market Restraints
- Cloud infrastructure concentration:Sub-200ms latency requirements tie vendors to three dominant hyperscale providers, limiting price negotiation leverage.
- Cross-border data friction:UAE Information Assurance standards impose architectural constraints that inflate platform development costs for multi-country deployments.
- Legacy LMS substitution threat:Established on-premise systems at Saudi universities resist full migration despite cloud-native feature gaps.
Strategic Opportunities
- Kuwait and Oman public sectors:These markets show 40% lower platform penetration than Saudi Arabia and the UAE, creating first-mover whitespace for localized content plays.
- Mobile-first microlearning:Smartphone-dominant learner populations in Bahrain and Qatar favor bite-sized credential stacking over traditional course structures.
- Virtual classroom convergence with workforce platforms:Integration with HRIS and talent management systems opens enterprise accounts previously locked to standalone training tools.
Industry Challenges
- Arabic NLP engineering scarcity:Platform vendors struggle to recruit computational linguists capable of building dialect-robust adaptive tutoring engines.
- Multi-jurisdiction compliance timelines:Simultaneous alignment with Saudi SDAIA guidelines and UAE IA standards extends product certification cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC E-Learning Market |
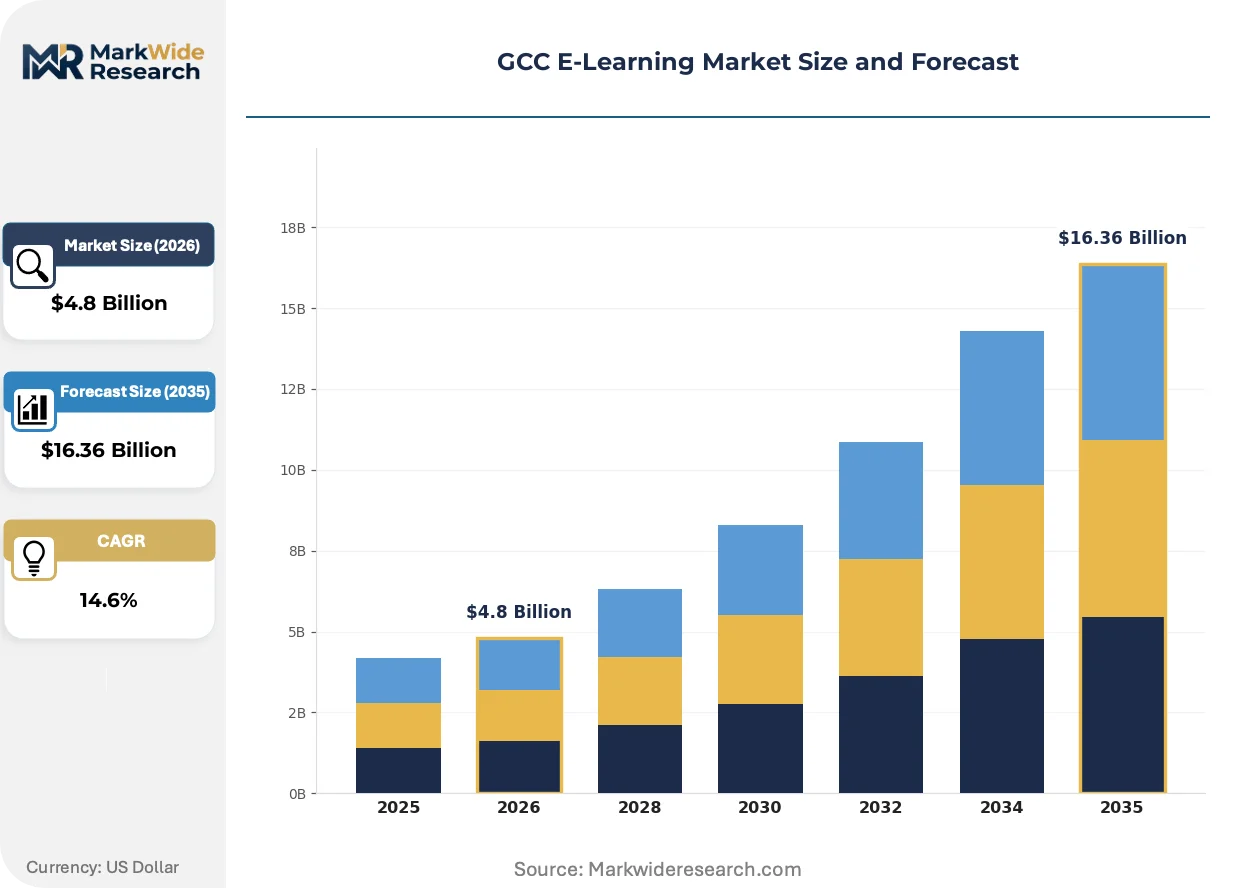
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Online Courses, Virtual Classrooms, Mobile Learning, Blended Learning End User: Students, Corporates, Educational Institutions, Government Agencies Content Type: Videos, Text, Interactive Modules, Assessments Technology: Learning Management Systems, Mobile Apps, Gamification Tools, AI-Driven Platforms |
| Companies Covered | Pearson Plc, Houghton Mifflin Harcourt Co., Coursera Inc., Simplilearn, John Wiley and Sons Inc., Articulate Global Inc., Docebo Inc., XpertLearning, GEMS Group Holdings Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC E-Learning Market Strategic Shifts & Innovations
Generative AI is compressing content production economics while regulatory mandates across the Gulf Cooperation Council are hardening data sovereignty requirements for student information systems.
Adaptive learning algorithms powered by transformer architectures are displacing rule-based competency mapping in Saudi Arabia's K-12 sector. The Ministry of Education's procurement specifications now prioritize real-time knowledge-gap identification over static curriculum sequencing. This capability compression is forcing legacy platform vendors to license AI modules or exit government tenders.
UAE Information Assurance standards now mandate in-country data residency for all student biometric and behavioral analytics. Platform operators must rearchitect cloud deployments to satisfy these constraints or forfeit Ministry of Education contracts. Vendors are responding by establishing dedicated UAE-based infrastructure zones with localized encryption key management.
Corporate buyers in Dubai and Riyadh are unbundling content licensing from platform subscriptions, creating direct procurement relationships with specialized module providers. This disintermediation fragments vendor relationships that previously consolidated through single-platform contracts. The shift is most visible in technology upskilling categories where employers prioritize vendor-neutral certification alignment over integrated learning management.
GCC E-Learning Market Segmentation
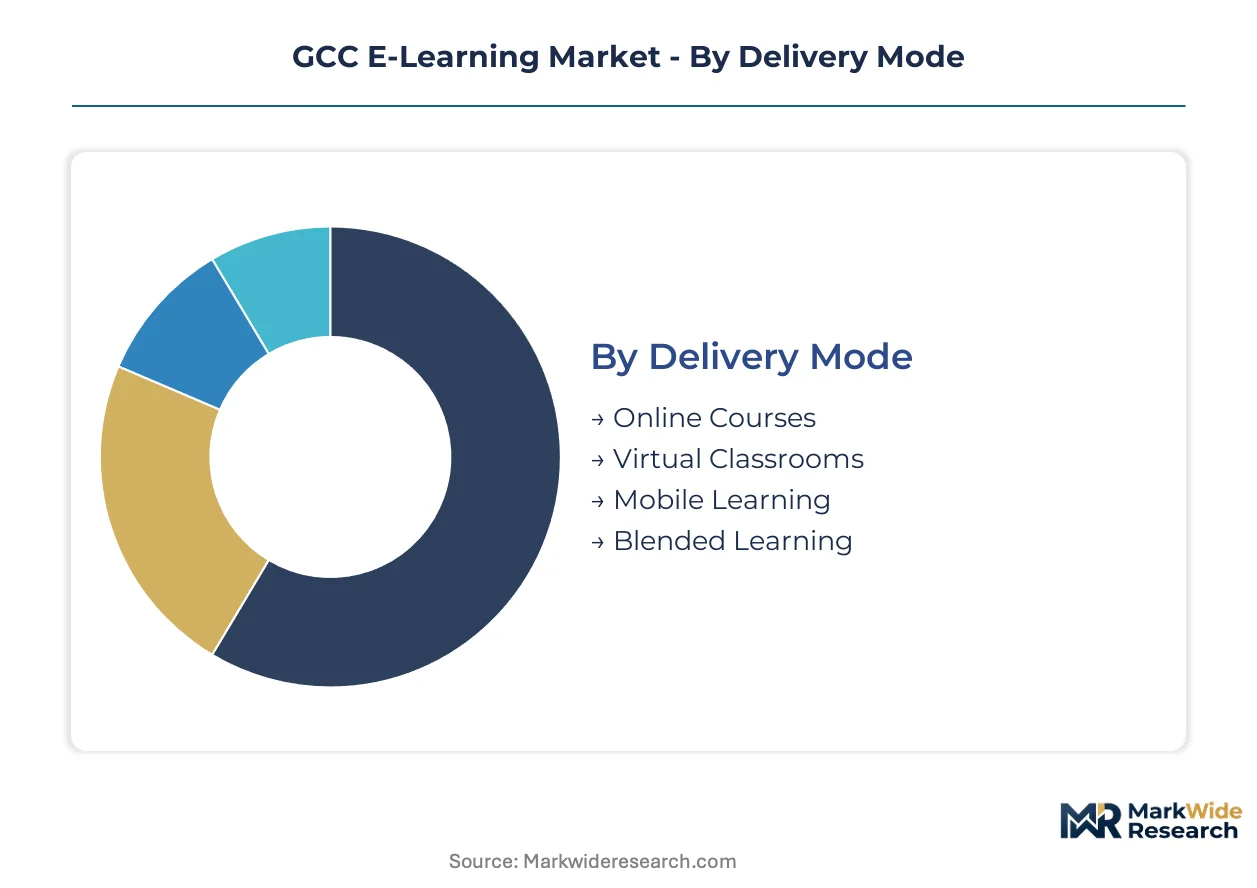
Delivery mode selection in the GCC determines cloud infrastructure requirements and latency thresholds. Content type preferences shape localization budgets and Arabic NLP investment priorities. Technology choices directly constrain procurement eligibility under Saudi SDAIA and UAE IA standards.
Delivery Mode:
Virtual classrooms face acute substitution pressure from mobile-first microlearning platforms as smartphone penetration climbs across Bahrain and Qatar.
- Online Courses:Self-paced modules delivered through web platforms with progress tracking and certificate issuance. Saudi Arabia's K-12 sector concentrates procurement here due to Ministry of Education mandates for curriculum digitization, though bandwidth limitations in rural governorates constrain synchronous features.
- Virtual Classrooms:Real-time video conferencing environments with breakout rooms and interactive whiteboards. Dubai and Riyadh corporate training budgets prioritize these for cohort-based technology upskilling, where employer mandates require live instructor verification.
- Mobile Learning:Smartphone-optimized bite-sized content with offline sync capabilities. Qatar and Bahrain learner populations favor credential stacking over traditional course structures.
- Blended Learning:Hybrid models combining physical campus sessions with digital components. UAE higher education clusters deploy these to satisfy accreditation body requirements for contact hours.
Online courses retain volume leadership; mobile learning holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade platforms from mass-market offerings across government and corporate procurement channels.
- Students:Individual learners accessing credential programs through institutional licenses or direct subscription. Saudi Arabia's K-12 sector and UAE higher education clusters drive platform investments here.
- Corporates:Employer-sponsored training programs with HRIS integration requirements. Technology upskilling mandates at major Dubai and Riyadh employers redirect L&D spend toward certified digital credential programs.
- Educational Institutions:Universities and schools licensing platforms for curriculum delivery. Legacy on-premise LMS substitution threats persist despite cloud-native feature gaps.
- Government Agencies:Public sector entities with sovereign data residency requirements. Kuwait and Oman show 40% lower platform penetration, creating whitespace for localized content plays.
Educational institutions retain volume leadership; government agencies hold the steepest expansion curve.
Content Type:
Application-specific requirements differentiate assessment-heavy compliance training from video-dominant soft skills programs.
- Videos:Streaming lecture content with adaptive bitrate delivery for variable bandwidth conditions. Corporate training programs across Saudi Arabia and the UAE accelerate platform investments here.
- Text:Digital documents and readings with annotation tools. Arabic-English multilingual interfaces serve dispersed learner populations across all six member states.
- Interactive Modules:Simulations and branching scenarios with real-time feedback. AI-driven personalization modules are becoming compulsory in government tenders under Saudi SDAIA guidelines.
- Assessments:Proctored examinations and competency validation tools. UAE Information Assurance standards mandate in-country data residency for student biometric analytics.
Video content retains volume leadership; interactive modules hold the steepest expansion curve.
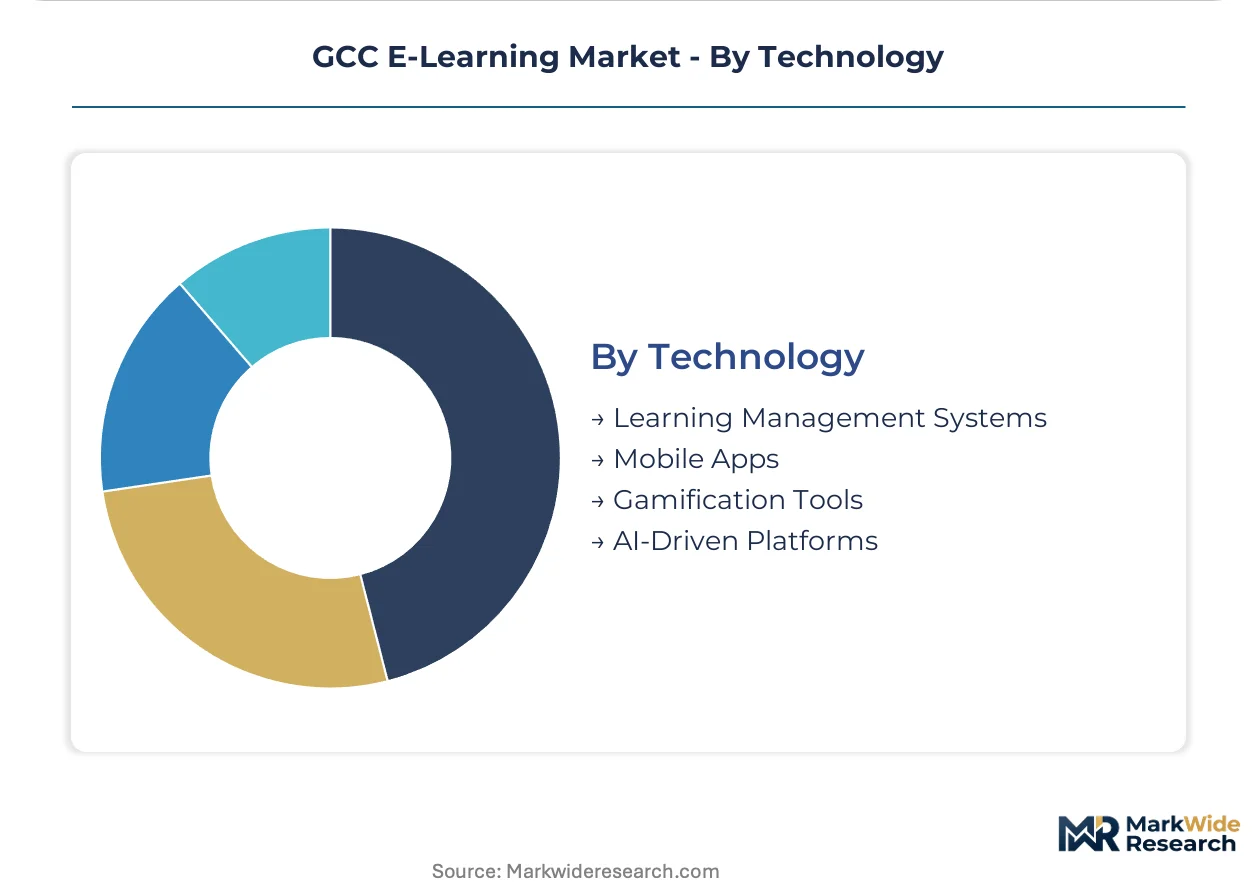
Technology:
Supply concentration among three dominant hyperscale providers limits price negotiation leverage for learning management system deployments.
- Learning Management Systems:Centralized platforms for course administration, enrollment, and progress tracking. Established on-premise systems at Saudi universities resist full migration despite cloud-native feature gaps.
- Mobile Apps:Native iOS and Android applications with push notifications and offline content sync. Smartphone-dominant populations in Bahrain and Qatar favor bite-sized credential stacking.
- Gamification Tools:Badge systems, leaderboards, and reward mechanics for engagement. Corporate buyers unbundle these from platform subscriptions, creating direct procurement relationships.
- AI-Driven Platforms:Adaptive tutoring engines with Arabic NLP and predictive dropout interventions. Multi-jurisdiction compliance timelines extend product certification cycles by 8-12 months.
Learning management systems retain volume leadership; AI-driven platforms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Ministry of Education and the UAE's Ministry of Education enforce curriculum digitization mandates that directly shape platform procurement specifications and content localization requirements across the Gulf Cooperation Council.
Saudi Arabia
K-12 sector procurement drives the largest platform investments in the region. The Saudi Data and Artificial Intelligence Authority guidelines require AI-driven personalization modules in all government tenders. Riyadh anchors corporate training budgets where technology upskilling mandates redirect employer L&D spend toward certified digital credential programs.
United Arab Emirates
Higher education clusters in Dubai concentrate demand for virtual classroom deployments with live instructor verification. UAE Information Assurance standards mandate in-country data residency for student biometric analytics. Dubai and Abu Dhabi host the region's densest concentration of corporate training platforms integrated with HRIS systems.
Kuwait
Public sector platform penetration runs 40% below Saudi and UAE levels, creating whitespace for localized content plays. The country's national education regulator has begun issuing digital curriculum mandates modeled on Saudi specifications. Kuwait City represents the primary concentration for emerging government e-learning tenders.
Oman
Government agency procurement channels show similar underpenetration relative to regional leaders. National digital transformation agendas are elevating technical specifications for adaptive learning engines in upcoming platform tenders. Muscat serves as the administrative center where procurement criteria are being rewritten to align with GCC-wide AI curriculum standards.
Qatar
Smartphone-dominant learner populations favor bite-sized credential stacking over traditional course structures. The country's sovereign wealth-backed education initiatives are accelerating mobile-first microlearning platform adoption. Doha's corporate training market exhibits strong demand for vendor-neutral certification alignment in technology upskilling categories.
GCC E-Learning Market Key Industry Players
Listed leaders compete with private specialists across content licensing and platform delivery dimensions in the GCC e-learning market. The vendor base organizes around three strategic archetypes: global publishers with institutional relationships, pure-play platform operators, and regional specialists with Arabic content capabilities. Market consolidation pressure operates through content unbundling trends and hyperscale cloud infrastructure concentration. Competitive moves center on AI module licensing partnerships and sovereign data zone establishment.
Among global publishers, Pearson Plc and John Wiley and Sons Inc. exemplify the premium content licensing archetype that sustains position across Saudi university procurement channels. Coursera Inc. occupies a position within the credential recognition tier where competition with regional accreditation bodies determines platform selection. Simplilearn represents the technology upskilling specialist archetype anchoring corporate training budgets in Dubai and Riyadh.
| Leading Market Players |
|---|
| Pearson Plc |
| Houghton Mifflin Harcourt Co. |
| Coursera Inc. |
| Simplilearn |
| John Wiley and Sons Inc. |
| Articulate Global Inc. |
| Docebo Inc. |
| XpertLearning |
| GEMS Group Holdings Ltd. |
| Others |
Cost & Logistics Intelligence
Cloud-native platform substitution for legacy on-premise LMS deployments is simultaneously compressing supply geography toward three dominant hyperscale providers and fragmenting pricing economics across certification-tiered service levels. This infrastructure consolidation reshapes vendor margin structures as latency requirements below 200 milliseconds tether procurement to concentrated cloud zones.
Pricing Analysis
Certification level (ISO 21001, SDAIA compliance, UAE IA standards) creates the primary spread between premium enterprise tiers and economy self-service offerings. Three-tier pricing structure across premium, standard, and economy levels dominates, with AI-driven personalization modules commanding 40-60% uplifts over baseline subscriptions. Pricing pressure stems from corporate buyers unbundling content licensing from platform subscriptions, forcing vendors to compete on module-level economics. Government agencies exhibit lowest price sensitivity due to sovereign data requirements, while mid-market educational institutions face acute budget constraints.
Supply Chain Analysis
Inventory and lead-time compression distinguishes cloud-native deployments from legacy system migrations, with provisioning cycles measured in days versus quarters for on-premise installations. Supply concentrates in the United States (AWS, Microsoft Azure), Western Europe (localized GDPR-compliant zones), and the United Arab Emirates (sovereign data residency infrastructure). Platform development draws from specialized Arabic NLP engineering talent pools, transformer architecture licensing, and hyperscale compute capacity. Single-source vulnerability runs through concentrated hyperscale provider relationships. Distribution runs through direct enterprise sales teams and government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors must defend against substitution by open-source adaptive learning engines and generative AI content tools that erode proprietary content moats.
For Market Incumbents: Fortify position through backward integration into Arabic NLP capabilities and dedicated UAE sovereign data zones, neutralizing compliance-driven procurement disadvantages. Deepen vertical integration into assessment proctoring and biometric analytics to capture high-margin government contracts. Prioritize ISO 21001 certification maintenance as table stakes while accelerating SDAIA guideline alignment ahead of tender cycles.
For New Entrants and Emerging Players: ISO 21001 fast-track certification unlocks Kuwait and Oman public sector whitespace where platform penetration trails regional leaders by 40%. Target mobile-first microlearning segments in Qatar and Bahrain where smartphone-dominant populations favor credential stacking. Pursue direct corporate procurement relationships with technology upskilling module specialization, bypassing consolidated platform intermediation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional content specialists holding Arabic curriculum libraries and established Ministry of Education relationships. Five-to-ten year viability hinges on AI curriculum mandate compliance rather than content volume. Watch for SDAIA guideline expansion into mandatory predictive dropout intervention specifications as the inflection signal for platform capability consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Module Licensing Partnership | Accelerates SDAIA compliance for legacy platform vendors facing government tender exclusion. |
| Sovereign Data Zone Establishment | Satisfies UAE Information Assurance residency mandates for student biometric analytics. |
| Arabic NLP Capability Acquisition | Addresses computational linguist scarcity constraining adaptive tutoring engine development. |
| Corporate Content Unbundling | Captures direct procurement relationships as employers separate platform from module licensing. |
| Kuwait-Oman Market Entry | Exploits 40% underpenetration in public sector platform adoption relative to Saudi and UAE benchmarks. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with e-learning platform executives, government procurement officers, and corporate L&D directors; and secondary validation through Saudi Ministry of Education tender documentation, UAE Information Assurance standards filings, and hyperscale cloud provider regional capex disclosures. Bottom-up triangulation across delivery mode, end user, content type, and technology segments anchored volume estimates, while top-down cross-checks against national digital transformation budget allocations ensured consistency.
Across the projection horizon, the analytical framework modeled segmentation dimensions including deployment architecture, organization scale, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement cycle compression and AI curriculum mandate implementation timelines. Forecast inputs incorporated cloud infrastructure latency requirement evolution and Arabic NLP engineering capacity constraints.
Decision-makers should treat outputs as directional under assumptions of sustained government digitization spending and hyperscale provider market concentration; material deviation in either would warrant model refresh. Specific risks include regulatory timeline slippage for multi-jurisdiction compliance and generative AI disruption of content production economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Distance Learning and Online Education
United States E-Learning Market
Distance Learning and Online Education
GCC Massive Open Online Course (MOOC) Market
Distance Learning and Online Education
Europe MOOC Market
Distance Learning and Online Education
E-Learning Services Market
Distance Learning and Online Education
Online Tutoring Market
Distance Learning and Online Education
Cloud-Based Training Software Market
Distance Learning and Online Education
Saudi Arabia E-Learning Market
Distance Learning and Online Education
MOOC Market
Distance Learning and Online Education
Remote Learning Technology Spending Market
Distance Learning and Online Education
Global Self-Paced E-Learning Market
Distance Learning and Online Education
Online Tutoring Services Market
Distance Learning and Online Education
Global Virtual Classroom Market
Distance Learning and Online Education
Europe E-Learning Market
Distance Learning and Online Education
Global Online Tutoring Software Market
Distance Learning and Online Education
Homeschooling Market
Distance Learning and Online Education
Online K-12 Education Market