
 Automotive Heater Fan Motor Market | 2026-2036
Automotive Heater Fan Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Heater Fan Motor Market Insights
Software-defined thermal management is decoupling hardware sales from recurring service revenue in the automotive heater fan motor ecosystem. Brose Fahrzeugteile GmbH & Co. KG leverages its European OEM relationships to anchor premium cabin comfort contracts. Mahle GmbH sustains R&D intensity across brushless motor architectures for next-generation HVAC modules. Nidec Corporation dominates high-volume DC motor production for Asian vehicle assemblers seeking cost-optimized thermal components.
An automotive heater fan motor is an electromechanical device that converts electrical energy into rotational force to drive impeller blades, typically operating at 12V or 48V in passenger vehicles and generating airflow rates between 300-800 cubic feet per minute for cabin heating, ventilation, and defrosting functions. Brushless motors are capturing margin pools as OEMs prioritize energy efficiency and acoustic performance in electric vehicle platforms. Blower motors remain the largest product category by installed base, though radiator fans are accelerating fastest with the spread of battery thermal management systems. The OEM channel controls the highest value contracts, while aftermarket suppliers compete on replacement cycle density and regional distribution reach.
NHTSA, EPA, and California Air Resources Board shape motor efficiency mandates and material compliance for US-bound production, with CARB's zero-emission vehicle rules indirectly pressuring thermal system power budgets. EMA and REACH in Europe enforce chemical safety in motor windings and rare-earth magnet compositions, raising certification barriers for non-compliant suppliers. Stakeholders must monitor how dual regulatory pressures from emissions authorities and safety agencies redefine motor specification thresholds before committing to platform-specific thermal architectures.
Market Dynamics
Software-defined thermal management is decoupling hardware sales from recurring service revenue, forcing motor suppliers to restructure contract economics around lifetime performance guarantees rather than unit shipments.
Growth Catalysts
- 48V electrical architecture migration:European premium OEMs are mandating 48V blower motors to support cabin preconditioning without draining high-voltage battery packs, expanding addressable motor value per vehicle.
- REACH chemical safety enforcement:ECHA restrictions on hexavalent chromium in motor laminations are accelerating substitution toward silicon steel grades that improve efficiency ratings.
- Battery thermal management proliferation:Radiator fan motors now manage battery pack cooling loads, doubling motor count per electric vehicle platform versus internal combustion equivalents.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in Chinese refining corridors, exposing brushless motor supply chains to export quota volatility.
- Copper winding cost exposure:Motor stators require high-purity copper conductors, and LME price swings directly compress gross margins on fixed-price OEM contracts.
- NHTSA acoustic compliance thresholds:Cabin noise regulations limit maximum fan speeds, capping airflow performance in certain vehicle classes and constraining motor specification flexibility.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for electric vehicle component localization create captive demand for thermally rated DC motor production within domestic tariff walls.
- Predictive maintenance service bundling:Motor-integrated vibration sensors enable condition-based replacement scheduling, converting aftermarket parts sales into recurring diagnostic subscriptions.
- Heat pump HVAC convergence:Reversible refrigeration cycles in electric vehicles require bidirectional fan motors, opening specification windows for multi-quadrant drive electronics.
Industry Challenges
- Motor control firmware certification timelines:Functional safety validation under ISO 26262 for ASIL-rated blower systems extends development cycles by 8-14 months.
- Legacy 12V platform coexistence:Suppliers must maintain dual voltage product lines during the 12V-to-48V transition, fragmenting engineering resources and tooling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Heater Fan Motor Market |
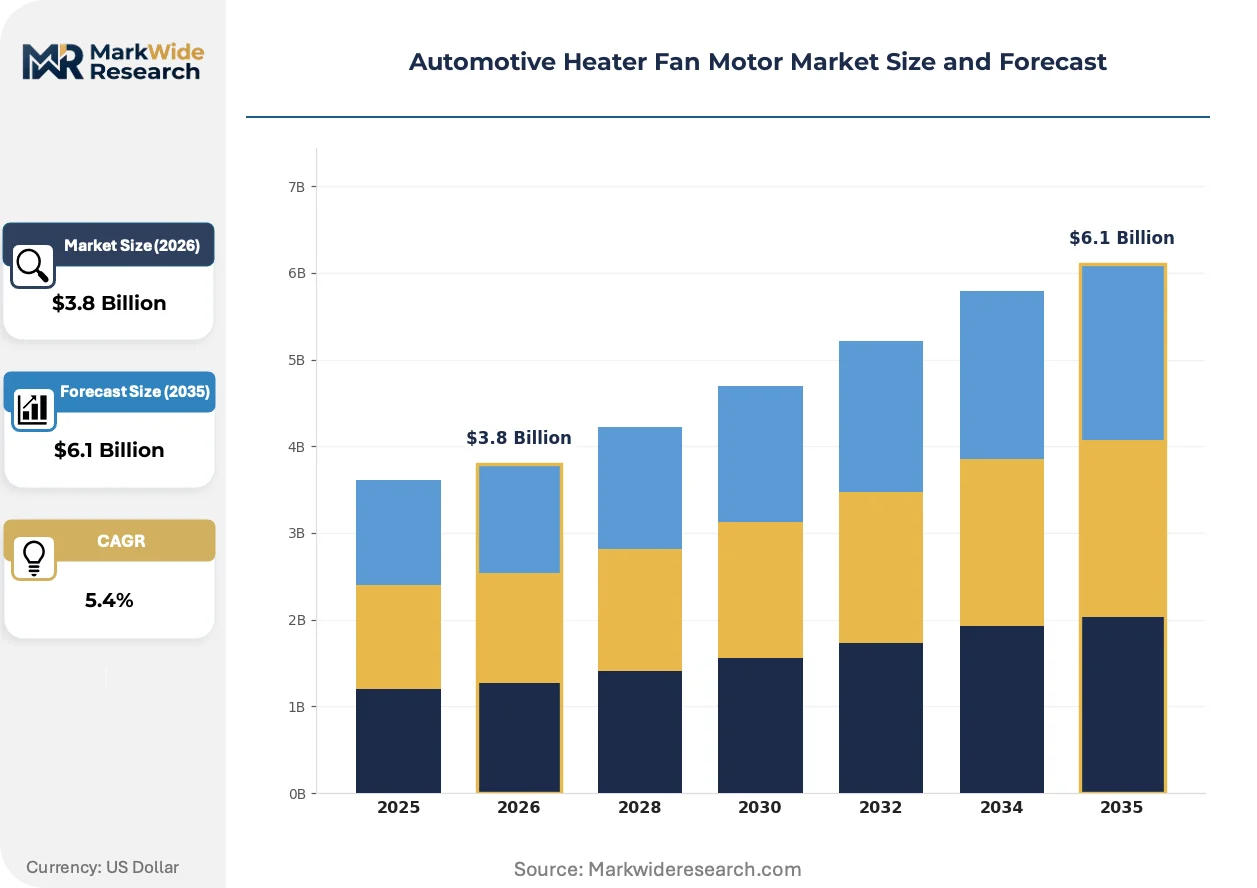
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blower Motors, Cabin Fans, Radiator Fans, Squirrel Cage Fans Technology: AC Motors, DC Motors, Brushless Motors, Stepper Motors End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Installation: Front Installation, Rear Installation, Under Dash Installation, Panel Mount |
| Companies Covered | Brose Fahrzeugteile GmbH & Co. KG, Mahle GmbH, Nidec Corporation, Denso Corporation, Valeo, Bosch, Johnson Electric, Mabuchi, Mitsuba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Heater Fan Motor Market Trends and Innovations
Electrification of vehicle thermal systems is collapsing the boundary between cabin comfort and battery thermal management, creating unified motor specification requirements that span previously separate engineering silos.
Brushless DC motor technology is consolidating position in premium electric vehicle platforms by eliminating brush wear and enabling precise speed control through field-oriented algorithms. German and Korean OEMs now specify brushless blowers as standard equipment for noise-sensitive cabin architectures. This consolidation is compressing brushed motor margins in the aftermarket as fleet operators extend replacement intervals.
EPA emissions rules are tightening motor efficiency minimums for US-bound production, indirectly pressuring thermal system power budgets that compete with drivetrain energy demands. Tier 1 suppliers must now submit certified efficiency maps across operating speed ranges. The blower motor segment faces the steepest compliance costs due to its continuous-duty operational profile.
Fleet procurement departments are centralizing thermal component sourcing through long-term service agreements that bundle motor supply with installation labor and warranty administration. Direct OEM-to-fleet contracting is displacing traditional aftermarket distribution in commercial vehicle segments. This pattern is most visible in North American last-mile delivery vehicle deployments where uptime guarantees dominate supplier selection criteria.
Automotive Heater Fan Motor Market Segmentation
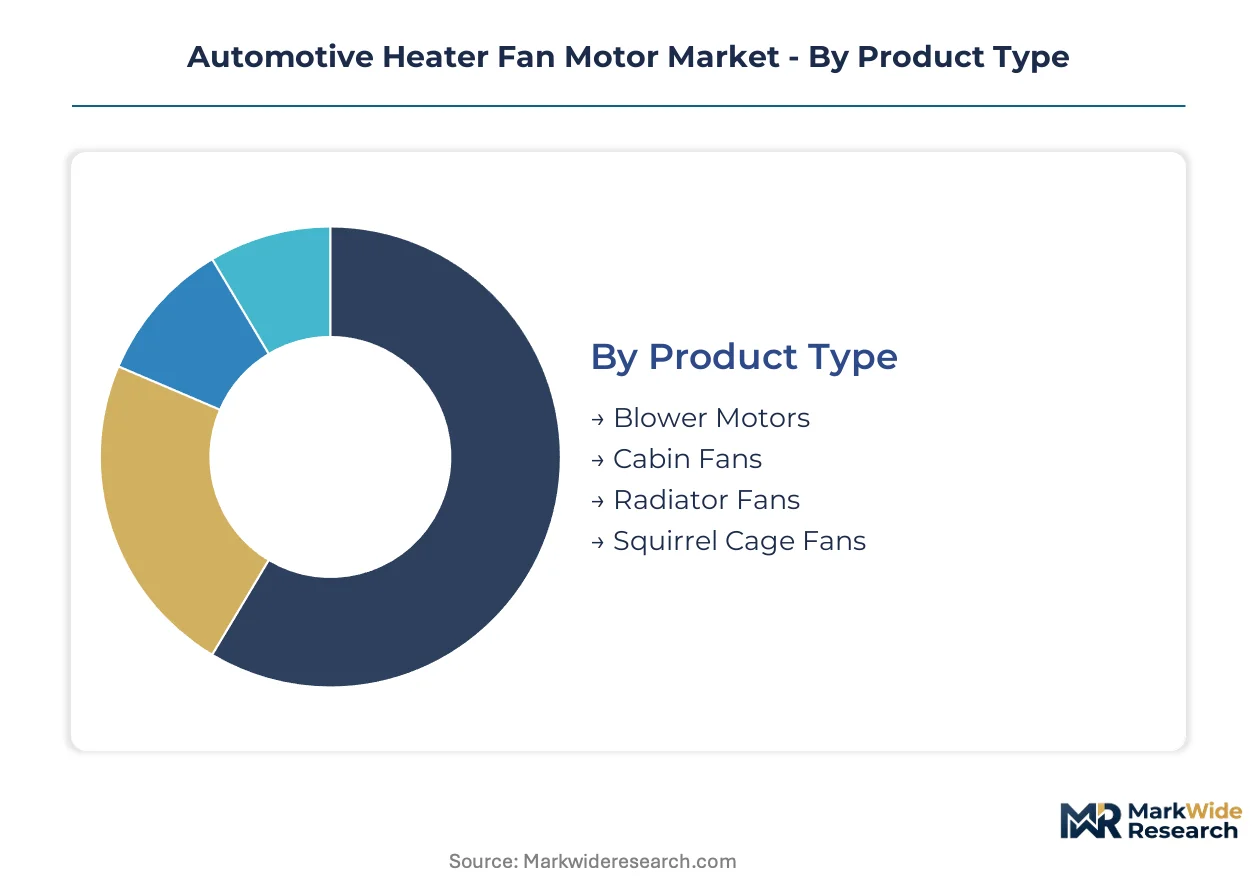
Automotive heater fan motor segmentation reveals how capital allocation, technical complexity, and regulatory pressure fragment across distinct engineering and commercial boundaries. Suppliers must align R&D budgets and manufacturing footprints to the specific performance tiers and certification requirements governing each segment category.
Product Type:
Capital intensity varies sharply across product categories, with radiator fan motors requiring the most substantial upfront tooling investments due to thermal validation and sealed-environment testing protocols.
- Blower Motors:These core cabin HVAC components integrate multi-speed resistors or PWM controllers to modulate airflow across 300-800 CFM ranges. Demand concentrates in German premium passenger vehicle platforms where acoustic performance specifications drive brushless motor adoption. NHTSA defrost timing requirements enforce minimum airflow rates that constrain motor downsizing.
- Radiator Fans:High-temperature operation near engine bays or battery packs demands IP67 sealing and continuous-duty thermal ratings. Battery electric vehicle platforms in Stuttgart and Munich manufacturing corridors specify dual-motor redundancy for thermal runaway protection. EPA cooling efficiency mandates are tightening power consumption thresholds for these continuous-duty applications.
- Cabin Fans:Auxiliary ventilation units for rear seating zones or commercial vehicle sleeper compartments.
- Squirrel Cage Fans:Legacy blower architectures retaining cost advantage in heavy-duty truck aftermarket replacement cycles.
Most installed capacity flows through Blower Motors. Expansion is steepest in Radiator Fans.
Technology:
Margin structures diverge most dramatically by motor technology, with brushless architectures commanding premium pricing despite higher controller costs.
- Brushless Motors:Electronically commutated designs eliminate mechanical wear and enable field-oriented control algorithms for precise speed modulation. Korean and German OEMs specify these exclusively for electric vehicle platforms where cabin noise budgets fall below 35 decibels. REACH compliance on magnet compositions adds certification overhead that filters out smaller suppliers.
- DC Motors:Brushed permanent-magnet designs dominate high-volume Asian vehicle assembly through cost-optimized ferrite magnet configurations. Chinese and Indian production corridors favor these for 12V legacy platforms where replacement cycle density sustains aftermarket revenue. Copper winding exposure to LME price volatility compresses margins on fixed-price contracts.
- AC Motors:Induction architectures limited to heavy-duty commercial applications with 24V electrical systems.
- Stepper Motors:Precision positioning applications in blend door actuation rather than primary airflow generation.
Brushless Motors capture the highest unit values. DC Motors retain volume leadership across cost-sensitive vehicle categories.
End User:
Contract economics and technical integration depth separate end-user channels more than volume scale alone.
- OEMs:Original equipment manufacturers specify motors at platform development stage, locking in multi-year supply agreements with embedded lifetime performance guarantees. European premium brands in Germany's manufacturing corridor mandate ISO 26262 ASIL-rated blower systems with 8-14 month certification timelines. These contracts bundle hardware with diagnostic software licenses.
- Aftermarket:Replacement parts distribution competes on regional warehouse density and same-day availability to minimize vehicle downtime. North American last-mile delivery fleets are consolidating procurement through direct supplier agreements that displace traditional distributor networks. Price transparency through digital cataloging erodes brand premiums.
- Tier-1 Suppliers:Thermal system integrators sourcing motors for HVAC module assembly.
- Vehicle Assemblers:Contract manufacturers with limited engineering specification authority.
OEMs concentrate engineering value. Aftermarket channels are consolidating fastest through fleet procurement centralization.
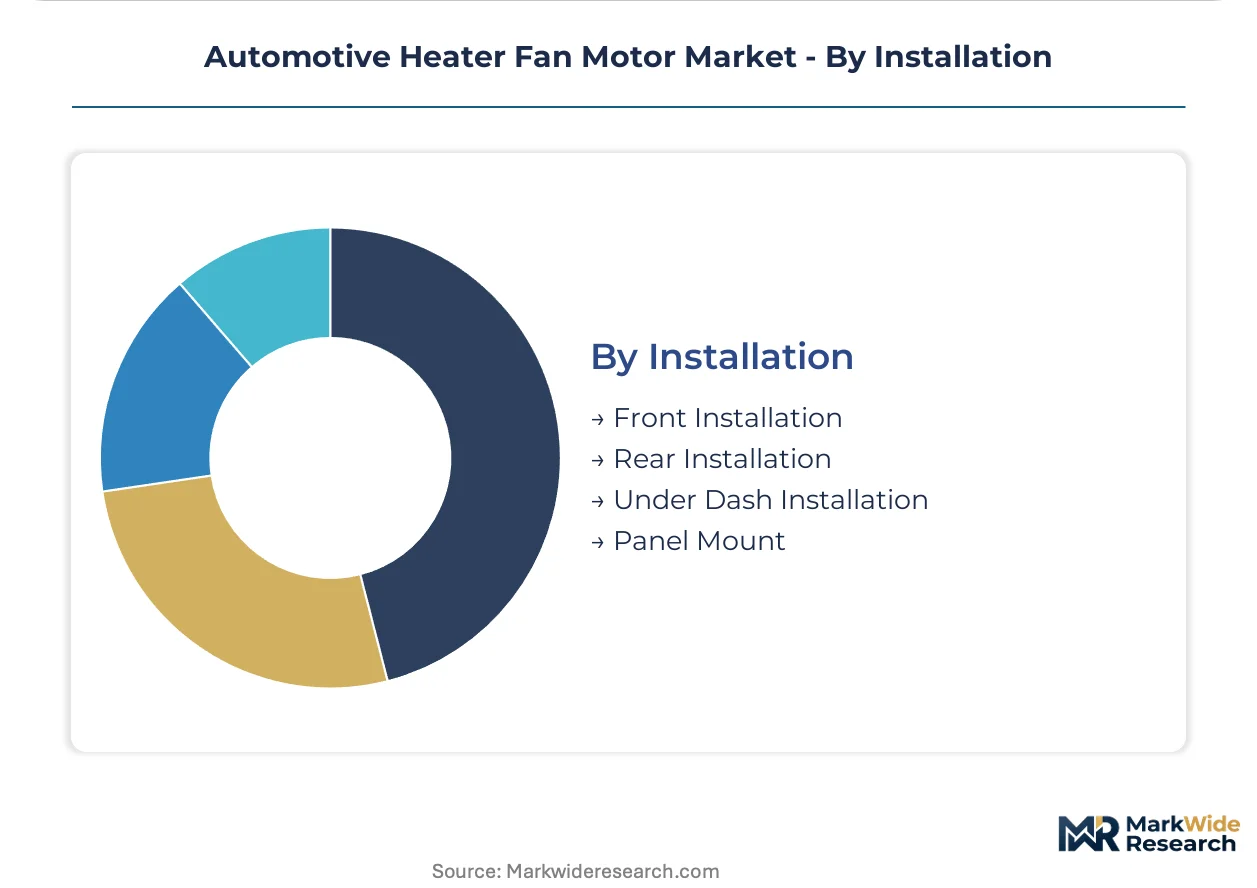
Installation:
Packaging constraints and service accessibility requirements create distinct specification profiles by mounting location.
- Front Installation:Engine bay or firewall-mounted motors serving primary HVAC plenums face the most severe thermal cycling and vibration exposure. These locations require reinforced bearing assemblies and extended temperature range electronics. NHTSA crash safety standards govern mounting bracket integrity for these forward-mounted components.
- Under Dash Installation:Concealed blower units behind instrument panels demand compact radial envelope designs with service access through glove box apertures. German and Japanese OEMs prioritize these configurations for premium cabin aesthetics. Acoustic isolation mounting adds material cost but satisfies cabin noise regulations.
- Rear Installation:Auxiliary units for third-row or cargo area climate zones.
- Panel Mount:Surface-mounted fans in commercial vehicle cabs or specialty equipment.
Front Installation carries the highest reliability specification burden. Under Dash Installation is expanding with premium interior packaging trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium electric vehicle motor engineering while China scales high-volume production for cost-optimized platforms. This divergence shapes supplier investment priorities across manufacturing corridors.
Germany
Stuttgart and Munich anchor OEM specification authority for brushless blower systems in Mercedes-Benz and BMW electric platforms. KBA enforces acoustic compliance thresholds that filter out non-certified suppliers. Baden-Württemberg manufacturing clusters specialize in ASIL-rated motor control firmware with extended validation timelines.
United States
NHTSA cabin defrost timing mandates and EPA motor efficiency minimums tighten specification windows for Detroit Three thermal programs. Michigan and Ohio assembly corridors demand dual-voltage product lines during the 12V-to-48V transition. Fleet procurement centralization in last-mile delivery segments displaces traditional aftermarket distribution networks.
China
MIIT new energy vehicle production quotas expand radiator fan motor counts per platform for battery thermal management. Yangtze River Delta and Pearl River Delta manufacturing basins concentrate ferrite magnet DC motor output for domestic OEMs. Dual carbon goals pressure motor efficiency ratings across export-bound production.
Japan
METI technology roadmaps prioritize noise-sensitive brushless architectures for Toyota and Honda electric platforms. Nagoya and Tokyo-Yokohama engineering centers develop field-oriented control algorithms for precision speed modulation. JIS standards govern rare-earth magnet composition compliance in motor windings.
India
PLI scheme incentives for electric vehicle component localization create captive demand for thermally rated DC motor production. Tamil Nadu and Maharashtra automotive corridors attract tier-1 supplier investments behind tariff walls. BIS efficiency certification requirements filter import-dependent supply chains.
Automotive Heater Fan Motor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM-direct relationships concentrating value in premium cabin comfort contracts while aftermarket channels compete on replacement density. The supplier base organizes around three archetypes: European engineering-led specialists, Asian scale-driven fabricators, and diversified tier-1 thermal system integrators. Competitive moves center on dual-voltage platform readiness and predictive maintenance service bundling to convert hardware sales into recurring revenue streams.
Among the European specialist tier, Brose Fahrzeugteile GmbH & Co. KG and Mahle GmbH exemplify engineering-intensive positioning anchored in German OEM relationships. Nidec Corporation occupies a scale-driven position within Asian manufacturing corridors. These three represent distinct competitive vectors: specification authority, thermal system integration depth, and high-volume cost optimization.
| Leading Market Players |
|---|
| Brose Fahrzeugteile GmbH & Co. KG |
| Mahle GmbH |
| Nidec Corporation |
| Denso Corporation |
| Valeo |
| Bosch |
| Johnson Electric |
| Mabuchi |
| Mitsuba |
| Others |
Pricing and Supply Chain Analysis
48V electrical architecture migration is simultaneously inflating motor unit values and concentrating supply among dual-voltage-capable manufacturers in Germany and Japan. This technical transition forces suppliers to absorb parallel tooling investments while OEMs exploit specification leverage during platform consolidation.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing basin are reshaping price floors for ferrite-magnet DC motors serving cost-optimized vehicle platforms. Three-tier pricing structure across premium brushless, standard DC, and economy brushed architectures reflects certification grade divergence under ISO 26262 and REACH magnet compliance. Cost compression in the DC tier is intensifying because LME copper volatility squeezes fixed-price OEM contracts. Fleet procurement departments exhibit highest price sensitivity through centralized long-term service agreements, while German premium OEMs prioritize acoustic performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Detroit anchor hub-and-spoke patterns for just-in-sequence delivery to thermal module assembly plants. Manufacturing concentrates in Germany, China, and Japan, with each corridor specializing in distinct motor architectures aligned to local OEM specifications. Rare-earth magnet supply draws from Chinese refining capacity, while silicon steel laminations and copper windings feed from South Korean and Chilean sources. Single-source vulnerability in neodymium processing exposes brushless motor production to export quota disruption. Distribution runs through tier-1 thermal system integrators rather than direct OEM supply in most contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive heater fan motor demand is shifting toward premium brushless specifications as electric vehicle cabin noise budgets tighten below 35 decibels. This quality migration favors engineering-intensive suppliers with ASIL-rated firmware certification capabilities.
For Market Incumbents: Acquire motor control firmware development teams to secure ASIL-rated blower system certification timelines. Consolidate specification authority by embedding lifetime performance guarantees into OEM platform contracts, countering emerging software-defined thermal management entrants that threaten hardware-centric revenue models. Deepen backward integration into rare-earth magnet supply through Japanese or European alternative sourcing partnerships. For New Entrants and Emerging Players: Enter via India's PLI scheme electric vehicle component localization incentives, where tariff walls create captive demand for thermally rated DC motor production. Target the North American last-mile delivery fleet aftermarket, where procurement centralization is displacing traditional distributor networks and opening direct supplier contracting opportunities. Lead with predictive maintenance service bundling using motor-integrated vibration sensors to convert parts sales into recurring diagnostic subscriptions. For Investors and Strategic Acquirers: Valuations sit cheapest among brushed DC motor specialists serving legacy 12V platforms facing replacement cycle compression. Long-term viability hinges on dual-voltage product line readiness and software-defined thermal management service revenue conversion. Monitor NHTSA acoustic compliance threshold tightening as the inflection signal that accelerates brushless motor specification mandates across mid-market vehicle tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Voltage Platform Standardization | Enables single supplier qualification across 12V legacy and 48V electric vehicle programs. |
| Rare-Earth Magnet Supply Agreement | Secures neodymium and dysprosium access outside Chinese export quota exposure. |
| Software-Defined Thermal Investment | Positions hardware suppliers for recurring diagnostic subscription revenue streams. |
| Geographic Manufacturing Footprint | PLI scheme qualification in India and MIIT quota alignment in China secure regional market access. |
| Predictive Maintenance Partnership | Fleet uptime guarantees convert aftermarket parts sales into long-term service contracts. |
Research Methodology
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each automotive manufacturing corridor. The approach combines structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and thermal system R&D heads with secondary validation. Sources include vehicle production databases, IHS Markit registration data, NHTSA and EPA regulatory filings, ECHA REACH substance restrictions, and MIIT new energy vehicle production disclosures. Bottom-up motor unit demand modeling triangulates against top-down thermal system market sizing.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions include product type, motor technology, end-user channel, installation location, and regional production cluster. CAGRs derive from fitted growth curves applied to platform-level motor content assumptions, incorporating 48V architecture penetration rates and battery thermal management motor count inflation. Industry-specific inputs include OEM platform launch timelines and REACH chemical compliance phase-in schedules.
The model holds under stable regulatory enforcement timelines and continued electric vehicle production quota expansion; deviation in rare-earth export restrictions or NHTSA acoustic threshold acceleration would shift brushless motor adoption curves. Forecasts reflect documented assumptions around platform standardization and dual-voltage transition pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Blower Motor Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Global Motor Soft Starter Market
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Air Motor Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Electric Traction Motor Market
Electric Motor
Frameless Motor Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market