
 High Speed Motor Market | 2026-2036
High Speed Motor Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Motor Market Analysis
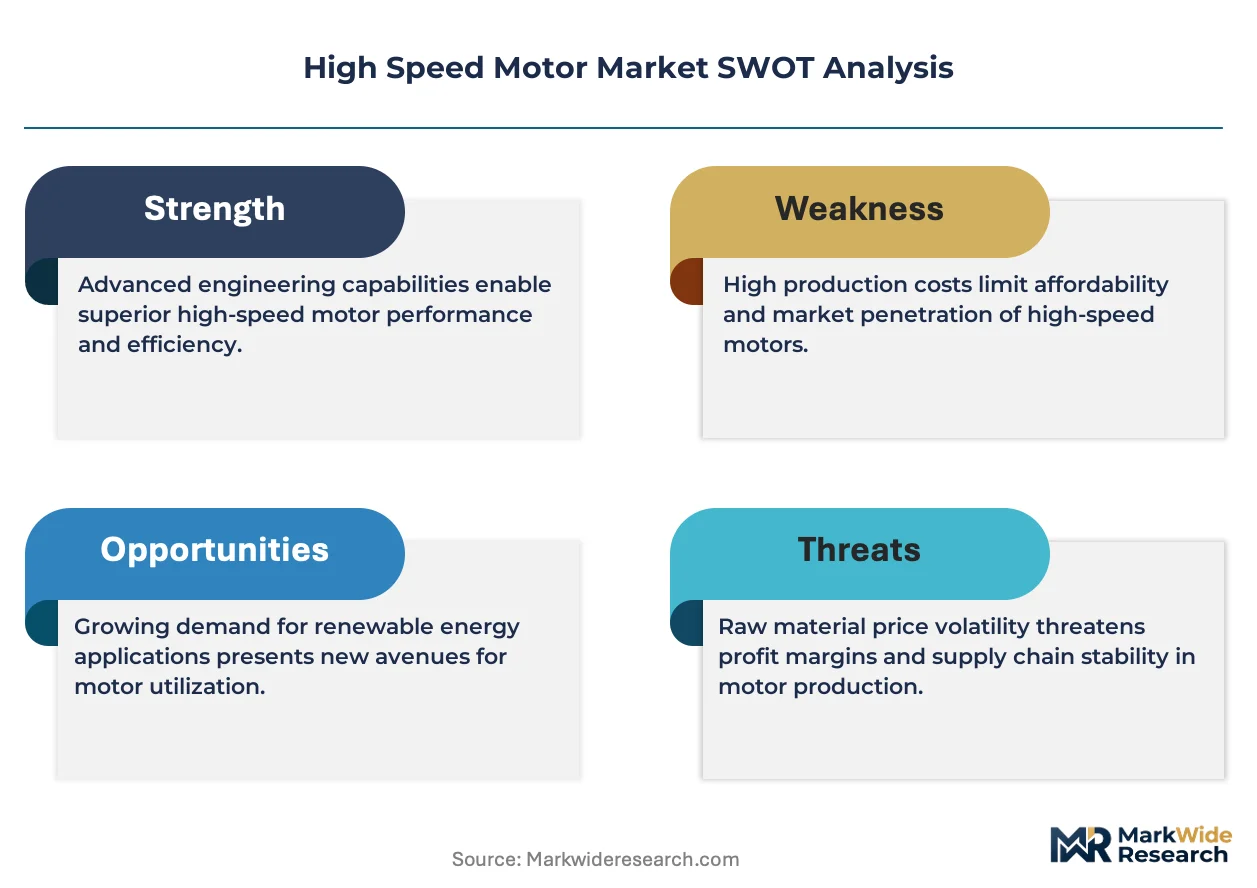
The high speed motor supply base is consolidating around two distinct performance tiers. Premium manufacturers with integrated magnetic material supply chains and in-house winding automation now capture the aerospace and precision CNC segments, while commodity-grade producers compete on cost for standard industrial pump and fan applications. ABB leverages its IEC standards leadership and European service infrastructure to anchor large industrial accounts. Siemens sustains technology differentiation through its digital twin integration for motor commissioning. Nidec Corporation dominates compact brushless architectures for robotics and medical centrifuge OEMs.
High speed motors rotate above 10,000 RPM and typically employ permanent magnet rotors with carbon fiber retaining sleeves or solid alloy construction to withstand centrifugal stress, serving applications where power density and dynamic response outweigh capital cost. AC motor configurations lead installed base across HVAC and compressor duty cycles due to mature variable frequency drive compatibility. Brushless DC architectures represent the fastest-expanding product category as silicon carbide power electronics enable higher switching frequencies and reduced rotor losses. CNC machine tool spindles and aerospace starter-generator applications concentrate margin pools above 100 HP ratings where thermal management and bearing longevity create qualification barriers.
The European Union F-Gas Regulation and Ecodesign directives tighten efficiency thresholds for motors integrated into refrigeration compressors and heat pump systems. The US Department of Energy minimum efficiency standards and FAA airworthiness certification requirements for electric propulsion systems shape dual compliance burdens for suppliers serving both industrial and aerospace end users. Japan METI energy conservation standards and JIS C 4212 premium efficiency classifications add a third regulatory layer for manufacturers with Asia-Pacific assembly footprints. Stakeholders must monitor rare earth supply chain restructuring and permanent magnet recycling mandates as these material constraints increasingly determine qualification timelines and total cost of ownership models.
Market Dynamics
Silicon carbide power electronics is consolidating motor-inverter architectures, collapsing the traditional separation between high-speed motor suppliers and drive system integrators into unified propulsion platforms.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for hydrofluorocarbon refrigerants accelerate replacement of fixed-speed compressor motors with variable-speed high-speed units in heat pump and commercial refrigeration systems across Germany, France, and Italy.
- Aerospace electrification:FAA airworthiness certification pathways for electric propulsion systems create qualified demand for integrated motor-generator units in regional aircraft and urban air mobility platforms.
- Permanent magnet material innovations:Reduced-dysprosium NdFeB formulations and grain-boundary diffusion techniques cut rotor material costs while maintaining coercivity at 180°C operating temperatures.
Market Restraints
- Rare earth supply concentration:Chinese processing facilities control approximately 90 percent of separated heavy rare earth output, exposing non-Chinese motor manufacturers to export quota volatility and price spikes in terbium and dysprosium.
- Bearing technology limitations:Ceramic hybrid and magnetic bearing systems required for sustained operation above 30,000 RPM remain cost-prohibitive for sub-50 HP industrial applications, capping addressable market expansion.
- Japan METI efficiency standards:JIS C 4212 premium efficiency classifications impose testing and documentation burdens that extend qualification timelines by 8-14 months for imported motor assemblies.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for capital goods manufacturing attract high-speed spindle motor investments serving the country's expanding CNC machine tool and textile machinery sectors.
- Medical centrifuge OEM demand:Brushless DC architectures with integrated position sensing capture replacement cycles in diagnostic laboratory equipment where noise suppression and vibration control justify premium positioning.
- Solid-state battery formation:Emerging gigafactory investments in Germany and the United States require precision winding and coating equipment powered by compact high-speed torque motors with sub-millisecond response profiles.
Industry Challenges
- Electromagnetic compatibility certification:IEC 61800-3 and FCC Part 15 testing for conducted emissions from SiC inverters adds 4-6 months to product launch schedules and requires specialized anechoic chamber access.
- Thermal management engineering talent:Scarcity of specialists combining computational fluid dynamics expertise with permanent magnet rotor stress analysis delays development programs for 150+ HP aerospace starter-generator applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Motor Market |
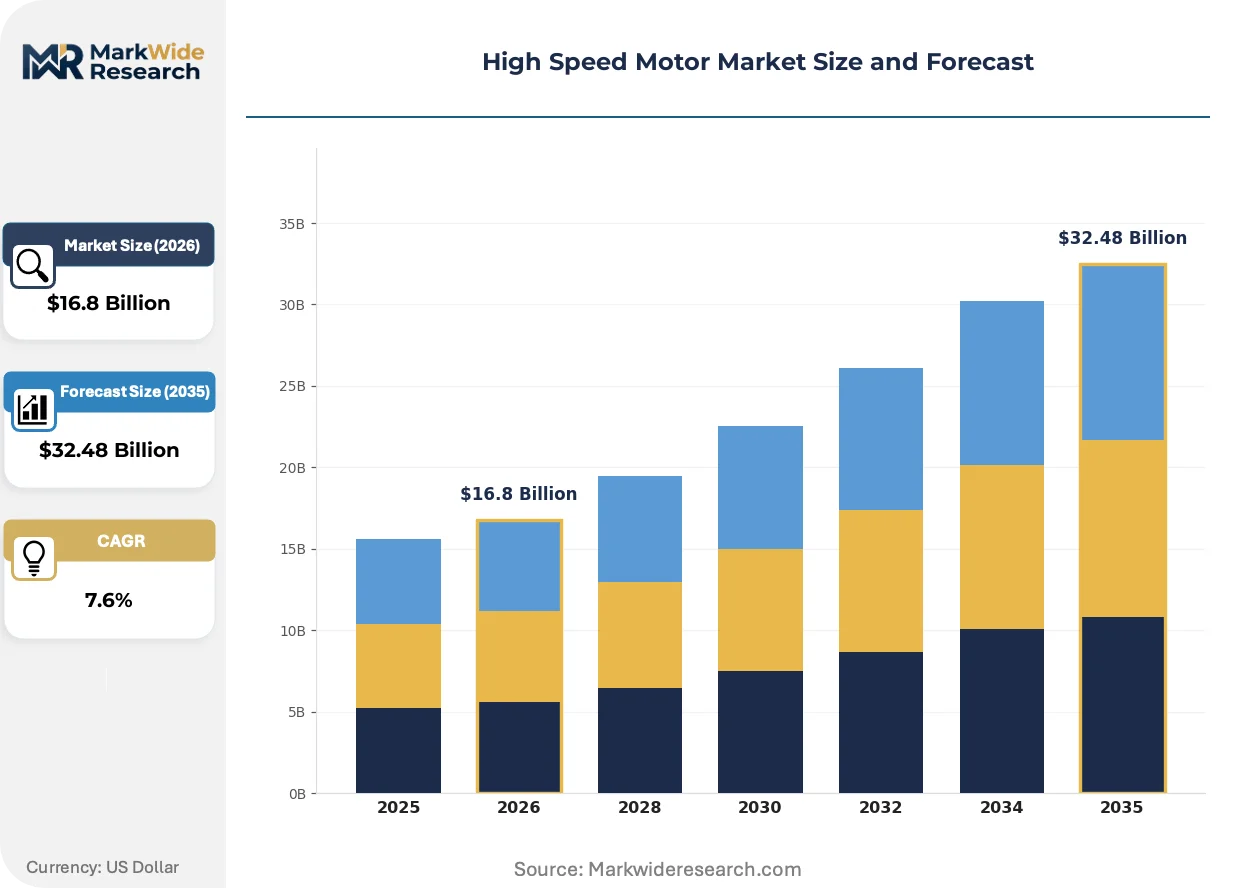
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $32.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Brushless Motors, Synchronous Motors End User: Aerospace, Automotive, Industrial Machinery, HVAC Power Rating: Above 100 HP, 50 HP to 100 HP, 10 HP to 50 HP, Below 10 HP Application: Robotics, Pumps, Compressors, CNC Machines |
| Companies Covered | ABB, Nidec Corporation, Siemens, Hitachi, Toshiba Corporation, Regal Rexnord Corporation, Mitsubishi Electric Corporation, Meidensha Corporation, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Motor Market Emerging Trajectories
Advanced manufacturing techniques and power electronics integration are collapsing traditional boundaries between motor hardware and control systems. Three developments dominate competitive positioning.
Carbon fiber retaining sleeve manufacturing is consolidating around automated filament winding and resin transfer molding processes that cut rotor assembly cycle times by half. Aerospace tier-one suppliers and precision CNC OEMs in Germany and Japan now specify these rotors as standard for applications above 15,000 RPM. The technology is consolidating supplier tiers by eliminating small machine shops lacking composite processing capabilities.
The EU F-Gas Regulation and accompanying Ecodesign directives mandate minimum seasonal performance factors for integrated heat pump systems. Motor manufacturers must now certify combined motor-compressor efficiency rather than standalone motor metrics. Refrigeration OEMs in Italy and Poland are responding by qualifying only integrated motor-inverter packages from suppliers with in-house power electronics design.
Buyer concentration among aerospace propulsion integrators and medical device OEMs compresses qualification cycles and shifts negotiation leverage toward volume-commitment contracts with technical assistance clauses. Distributors serving smaller industrial accounts face margin compression as direct procurement portals from ABB, Siemens, and Nidec capture standard product demand. This pattern is most visible in the United States, where consolidated hospital purchasing organizations and defense prime contractors now account for over 60 percent of brushless DC motor procurement in the 10-100 HP range.
High Speed Motor Market Segmentation
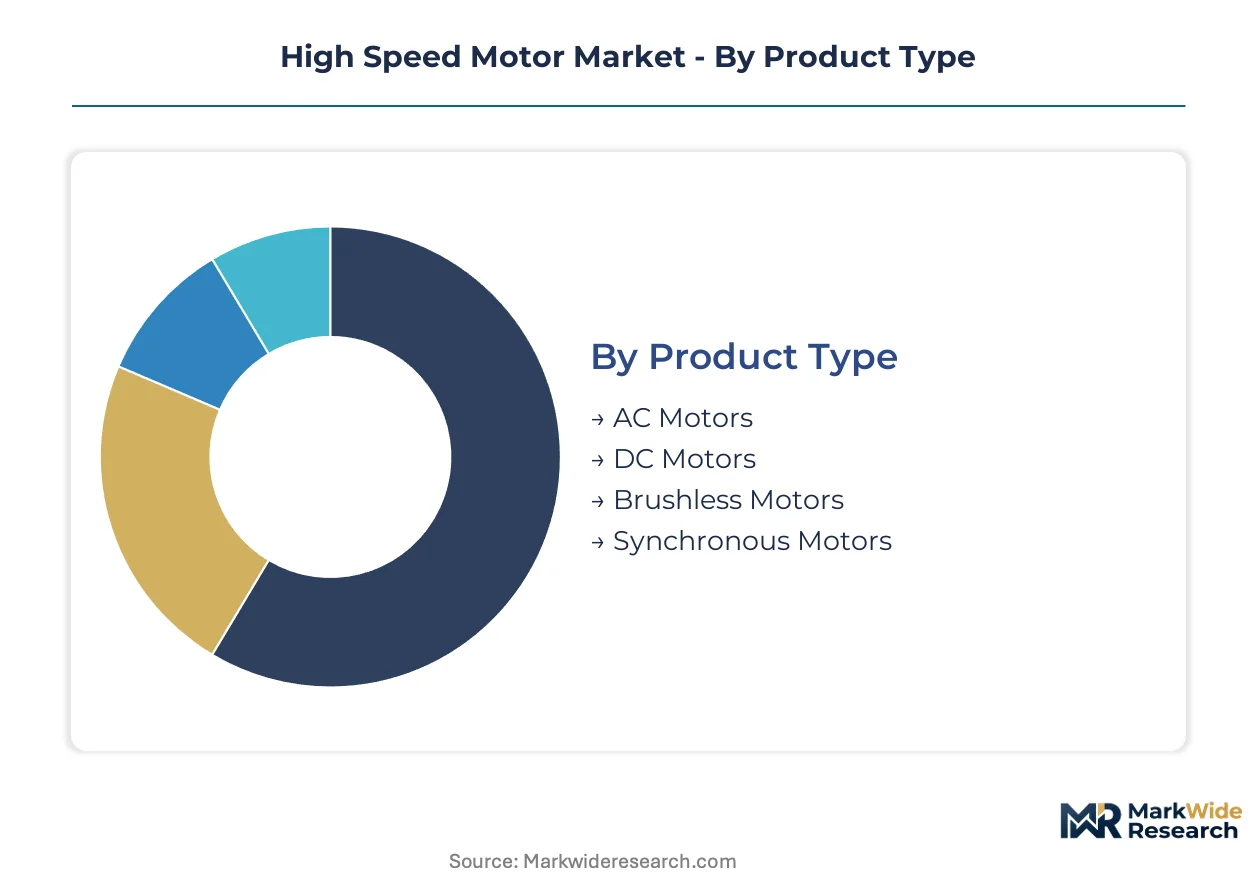
High speed motor procurement patterns diverge sharply across technical specifications and end-use requirements. Capital allocation, qualification timelines, and supplier relationships vary fundamentally by segment, making granular classification essential for strategic positioning.
Product Type:
Permanent magnet rotor fabrication and inverter integration costs concentrate capital expenditure most heavily in electronically commutated architectures.
- AC Motors:Squirrel-cage and wound-rotor designs dominate HVAC compressor and large industrial fan installations. Mature variable frequency drive ecosystems in Germany and the United States sustain volume procurement for fixed-speed replacement cycles.
- DC Motors:Brushed architectures with mechanical commutation retain niche positions in cost-sensitive pump applications. Winding maintenance requirements and brush wear limit deployment in continuous-duty aerospace and medical equipment.
- Brushless Motors:Electronically commutated permanent magnet designs integrate Hall-effect or resolver position sensing for precise torque control. Silicon carbide inverter compatibility enables switching frequencies above 20 kHz, cutting rotor losses in aerospace starter-generator and robotic joint applications.
- Synchronous Motors:Reluctance and permanent magnet synchronous configurations achieve highest efficiency at fixed speed ratios. Grid-tied compressor installations in Japan and precision spindle duty in German machine tool OEMs anchor demand for synchronous architectures above 50 HP.
AC motors absorb the bulk of installed capacity; brushless motors are expanding most quickly.
End User:
Certification burdens and technical assistance requirements stratify customer relationships from transactional to multi-year development partnerships.
- Aerospace:FAA airworthiness certification and DO-160G environmental qualification impose 18-36 month validation timelines. Integrated motor-generator units for electric propulsion and starter-generator applications concentrate procurement among US and European defense primes and emerging urban air mobility platforms.
- Automotive:Traction motor and electric turbocharger applications demand automotive-grade reliability metrics. Nidec and ABB anchor supply relationships with German and Japanese OEMs pursuing 800V architectures and solid-state battery formation equipment.
- Industrial Machinery:CNC machine tool spindles, textile winding equipment, and precision positioning systems require sub-arcminute runout tolerances. German and Japanese machinery OEMs specify ceramic hybrid bearings and carbon fiber retaining sleeves as standard above 15,000 RPM.
- HVAC:Heat pump and commercial refrigeration compressor duty cycles prioritize seasonal efficiency over peak performance. EU F-Gas Regulation phase-down mandates accelerate variable-speed motor adoption in integrated compressor packages from Italian and Polish refrigeration OEMs.
Industrial machinery absorbs the bulk of installed capacity; aerospace is expanding most quickly.
Power Rating:
Thermal management engineering and bearing system costs escalate disproportionately above 100 HP, collapsing supplier tiers to vertically integrated specialists.
- Above 100 HP:Liquid-cooled stator housings and magnetic or oil-film bearing systems become mandatory. Aerospace starter-generator and large industrial compressor applications in Germany and the United States concentrate procurement among ABB, Siemens, and specialized aerospace tier-two suppliers.
- 50 HP to 100 HP:Ceramic hybrid bearing systems and forced-air cooling balance performance against capital cost. Precision CNC spindle and mid-size heat pump compressor OEMs in Japan and Italy drive specification standardization.
- 10 HP to 50 HP:Brushless DC architectures with integrated silicon carbide inverters dominate robotics and medical centrifuge applications. Nidec Corporation and Japanese precision motor specialists capture volume through direct OEM relationships.
- Below 10 HP:Standardized frame sizes and mature winding automation enable cost-competitive supply for pump and fan applications. Chinese and Taiwanese producers compete on price for commodity industrial duty.
10-50 HP ratings absorb the bulk of installed capacity; above 100 HP is expanding most quickly.
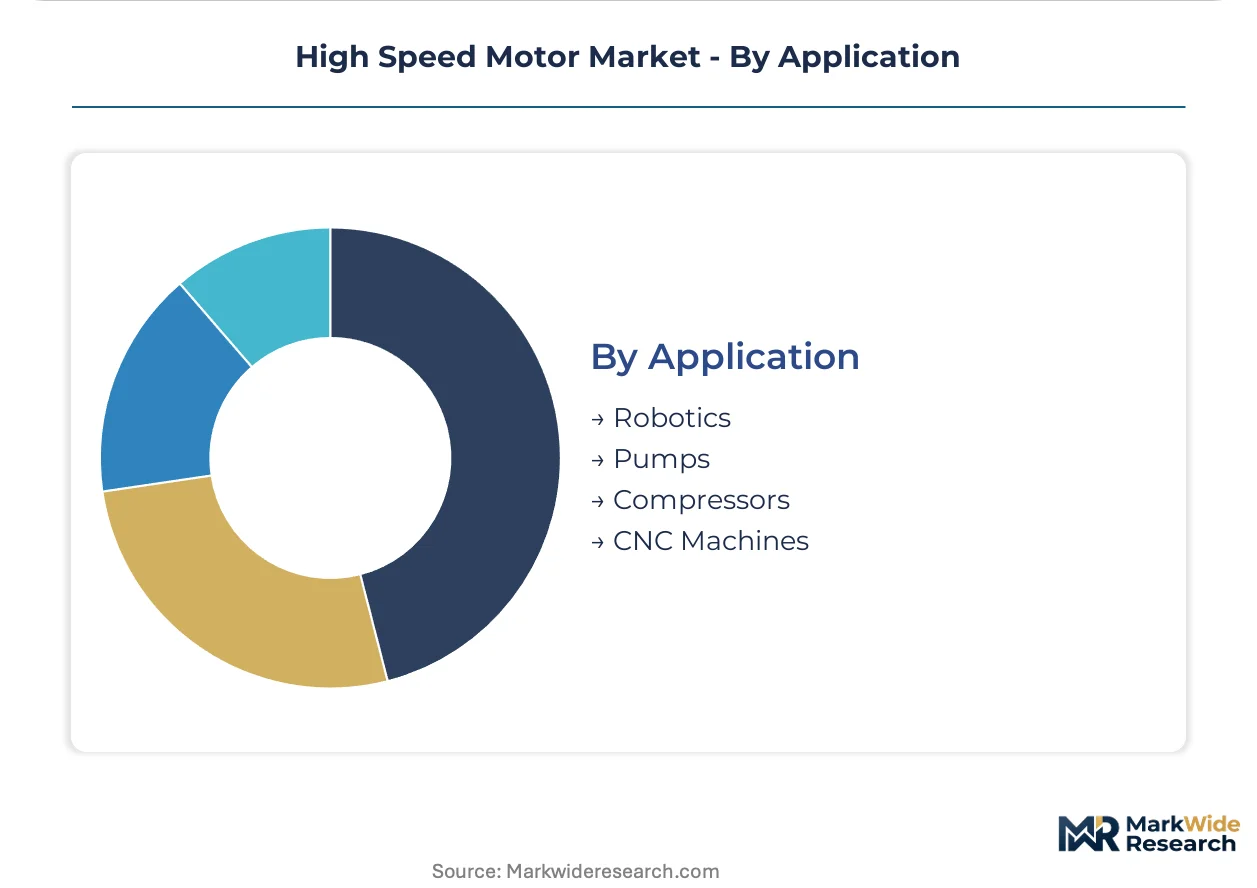
Application:
Motion control bandwidth and positioning accuracy requirements determine inverter specification and feedback sensor integration intensity.
- Robotics:Direct-drive torque motors and compact brushless servos achieve sub-millisecond response for collaborative and industrial arm joints. German and Japanese automation OEMs specify integrated encoder feedback and safety-rated torque limiting.
- Pumps:Centrifugal and positive displacement pump duty prioritizes efficiency at fixed operating points. Variable-speed high-speed motors displace turbine drives in US and Middle East oilfield injection and pipeline applications.
- Compressors:Refrigeration and air compression duty cycles demand robust bearing systems for continuous operation. EU F-Gas Regulation compliance drives integrated motor-inverter package adoption from Italian and German compressor OEMs.
- CNC Machines:Spindle motors require angular contact bearing arrangements and thermal stability for micron-level part precision. German machine tool builders specify motorized spindle packages with integrated liquid cooling and tool clamping mechanisms.
Compressor applications absorb the bulk of installed capacity; robotics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision motor manufacturing for German machine tool OEMs demanding carbon fiber retaining sleeve integration above 15,000 RPM.
United States
Aerospace electrification programs in Seattle and Wichita drive integrated motor-generator procurement for electric propulsion certification. FAA airworthiness pathways under DO-160G environmental standards impose 18-36 month validation timelines. Defense primes in Connecticut and California concentrate qualified supplier relationships for starter-generator applications above 100 HP.
Germany
EU F-Gas Regulation phase-down mandates accelerate variable-speed compressor motor replacement across Bavarian and Baden-Württemberg heat pump manufacturing clusters. Ecodesign directives require combined motor-compressor efficiency certification rather than standalone metrics. Siemens and ABB anchor integrated motor-inverter supply relationships with Italian refrigeration OEMs through Stuttgart-based technical centers.
Japan
METI energy conservation standards and JIS C 4212 premium efficiency classifications extend qualification timelines for imported assemblies by 8-14 months. Nagoya precision machinery corridors and Tokyo medical device clusters concentrate brushless DC demand for robotic joints and diagnostic centrifuges. Nidec Corporation captures direct OEM relationships through in-house winding automation and silicon carbide inverter compatibility.
India
PLI scheme incentives for capital goods manufacturing attract high-speed spindle motor investments serving Pune and Bangalore CNC machine tool expansion. Central Electricity Authority efficiency notifications align with state-level industrial power tariff structures. Gujarat textile machinery corridors and Tamil Nadu automotive component clusters drive 10-50 HP brushless motor procurement for precision winding applications.
China
Rare earth processing concentration in Jiangxi and Inner Mongolia controls approximately 90 percent of separated heavy rare earth output for permanent magnet rotor supply. MIIT industrial motor efficiency standards and dual carbon goals tighten procurement specifications for compressor and pump applications. Yangtze River Delta manufacturing zones concentrate cost-competitive production for sub-10 HP standardized frame sizes serving domestic HVAC replacement cycles.
High Speed Motor Market Vendor Landscape
Premium-margin players sit above commodity-margin players across permanent magnet supply chain integration and bearing system qualification thresholds. The supply base consolidates around two performance tiers: vertically integrated specialists with in-house magnetic material processing and composite rotor fabrication capture aerospace and precision CNC segments, while standardized frame producers compete on automation scale for industrial pump and fan duty. Three archetypes dominate: European industrial conglomerates with IEC standards leadership, Japanese precision motor specialists with compact brushless architectures, and Chinese cost-optimized producers. Competitive moves center on silicon carbide inverter integration partnerships and carbon fiber retaining sleeve manufacturing automation.
Among diversified industrial conglomerates, ABB and Siemens exemplify the integrated solutions archetype through European service infrastructure and digital commissioning platforms. Nidec Corporation occupies a distinct position as a compact brushless specialist serving robotics and medical equipment OEMs through direct technical relationships. These three anchors represent the premium-tier competitive vector where qualification barriers and certification timelines protect margin structures against commoditization pressure.
| Leading Market Players |
|---|
| ABB |
| Nidec Corporation |
| Siemens |
| Hitachi |
| Toshiba Corporation |
| Regal Rexnord Corporation |
| Mitsubishi Electric Corporation |
| Meidensha Corporation |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and Japan anchor premium-tier pricing through captive carbon fiber retaining sleeve fabrication and in-house NdFeB magnet processing, while private-equity-rolled-up industrial motor portfolios compete on automation scale for standardized sub-50 HP frames. This ownership dispersion creates divergent supply behaviors: integrated specialists defend margin through technical assistance bundling, while consolidated commodity producers absorb rare earth price volatility to maintain volume commitments.
Pricing Analysis
Value-based pricing anchored to aerospace qualification timelines and heat pump seasonal performance factors dominates premium tiers. Three-tier pricing structure across aerospace-certified, industrial-precision, and commodity HVAC levels separates motor-inverter packages by certification burden and bearing system specification. Pricing pressure stems from Chinese rare earth export quota volatility feeding rotor material cost uncertainty. HVAC compressor OEMs in Italy and Poland exhibit highest price sensitivity due to Ecodesign margin compression, while FAA-certified aerospace programs accept premium positioning for validated reliability.
Supply Chain Analysis
Ocean freight cost spikes and Red Sea routing disruptions have intensified inventory carrying costs for European distributors sourcing wound stator assemblies from East Asian contract manufacturers. Permanent magnet supply concentrates in China, with Japanese and German specialists maintaining strategic dysprosium and terbium stockpiles. Carbon fiber prepreg and silicon carbide wafers constitute critical input dependencies. Single-source vulnerability in heavy rare earth separation exposes non-Chinese motor manufacturers to qualification delays. Distribution runs through direct OEM technical relationships for aerospace and medical segments, with industrial distributors capturing standardized HVAC and pump replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet supply concentration and aerospace certification bottlenecks constrain effective capacity, propping pricing power for qualified suppliers. Stakeholders should weight strategic positioning against these supply-inelastic segments.
For Market Incumbents: Lock in multi-year offtake agreements with Jiangxi rare earth processors before export quota tightening accelerates. Defend margin position by deepening backward integration into grain-boundary diffusion magnet fabrication, countering emerging Korean and Vietnamese entrants pursuing silicon carbide inverter partnerships. Prioritize FAA certification maintenance for starter-generator applications above 100 HP where technical assistance clauses sustain pricing. For New Entrants and Emerging Players: Begin with India's PLI-subsidized CNC spindle motor segment, where qualification timelines remain shorter than aerospace or medical tiers. Target solid-state battery formation equipment suppliers in Germany and the United States requiring compact torque motors with sub-millisecond response. Pursue direct technical relationships with mid-size heat pump OEMs in Poland seeking second-source motor-inverter packages. For Investors and Strategic Acquirers: Distressed-cycle entries favor Japanese precision motor specialists with JIS C 4212 certification infrastructure and established Nagoya medical device corridor relationships. Long-term viability hinges on silicon carbide inverter compatibility and carbon fiber rotor fabrication automation. Watch FAA electric propulsion certification pathway acceleration as the inflection signal for aerospace segment demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Retaining Sleeve Automation | Automated filament winding cuts rotor assembly cycle times for German CNC OEMs. |
| Silicon Carbide Inverter Integration | SiC compatibility enables switching frequencies above 20 kHz for aerospace starter-generators. |
| Rare Earth Magnet Recycling Investment | Permanent magnet recovery mandates from EU regulators reshape qualification timelines. |
| FAA Electric Propulsion Certification | DO-160G validation pathways create qualified demand for integrated motor-generator units. |
| India PLI Scheme Manufacturing Footprint | Capital goods incentives attract spindle motor investments for Pune CNC expansion. |
Methodological Framework
Document review covered FAA airworthiness filings, EU Ecodesign implementing measures, METI energy conservation notifications, and MIIT industrial motor standards, complemented by interviews with aerospace propulsion engineers, HVAC compressor procurement leads, CNC machine tool OEM technical directors, and rare earth magnet supply specialists. Secondary validation drew from IEC efficiency classification databases, carbon fiber composite trade flow data, and silicon carbide semiconductor market disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Installed base and revenue projections reflect a demand-side model incorporating power rating tier migration, end-use electrification intensity, and regulatory compliance deadlines. Segmentation dimensions span product architecture, power rating band, application motion control requirements, and regional manufacturing cluster concentration. CAGRs derived from historical replacement cycle analysis and emerging technology adoption curves, with silicon carbide inverter penetration and aerospace electrification program commitments serving as primary forecast inputs.
Underlying measurement precision varies by segment; aerospace and medical centrifuge applications carry tighter precision than commodity HVAC replacement cycles due to concentrated buyer visibility. Forecasts reflect documented assumptions regarding rare earth supply stability, certification timeline continuity, and inverter cost trajectories. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
EV Traction Motor Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Global Hub Motors Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Air Motor Market
Electric Motor
North America Electric Motor Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
Voice Coil Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Electric AC Motors Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Large Synchronous Motor Market