
 Australia Solar E-Bike Market | 2026-2036
Australia Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Solar E-Bike Market Insights
A multi-source procurement strategy is shifting toward vertically integrated battery and photovoltaic subsystem control among Australian solar e-bike assemblers. Giant Manufacturing Co. leverages its Taiwan-based manufacturing footprint to sustain cost advantages in frame and motor sourcing. Dyson Bikes anchors its competitive position through domestic assembly operations and direct-to-consumer channel control. Specialized Bicycle Components differentiates via premium component integration and dealer network density in Sydney and Melbourne.
Australia solar e-bikes constitute electrically assisted bicycles incorporating photovoltaic panels for supplementary battery charging, typically achieving 15-25 watt peak output from integrated or accessory-mounted solar arrays designed to extend range for commuter and recreational applications. Commuter e-bikes occupy the dominant volume position, reflecting infrastructure investments in Brisbane and Perth cycling corridors. Lithium-ion batteries command the primary technology tier, displacing lead acid alternatives through energy density advantages and alignment with Australian Design Rules weight restrictions. Solar charging methods represent the fastest-growing configuration segment, though AC charging retains majority share due to urban apartment dweller access constraints.
The Department of Infrastructure administers Australian Design Rules specifying 250-watt motor power limits and pedal-assist operation requirements, while state-level road authorities enforce helmet mandates and pathway access permissions that vary across jurisdictions. TGA and Electrical Safety Office frameworks govern battery transport and charger certification, creating compliance complexity for importers of integrated solar-battery systems. Stakeholders must monitor evolving state subsidy programs and utility tariff structures that will determine total cost-of-ownership advantages against conventional e-bike alternatives.
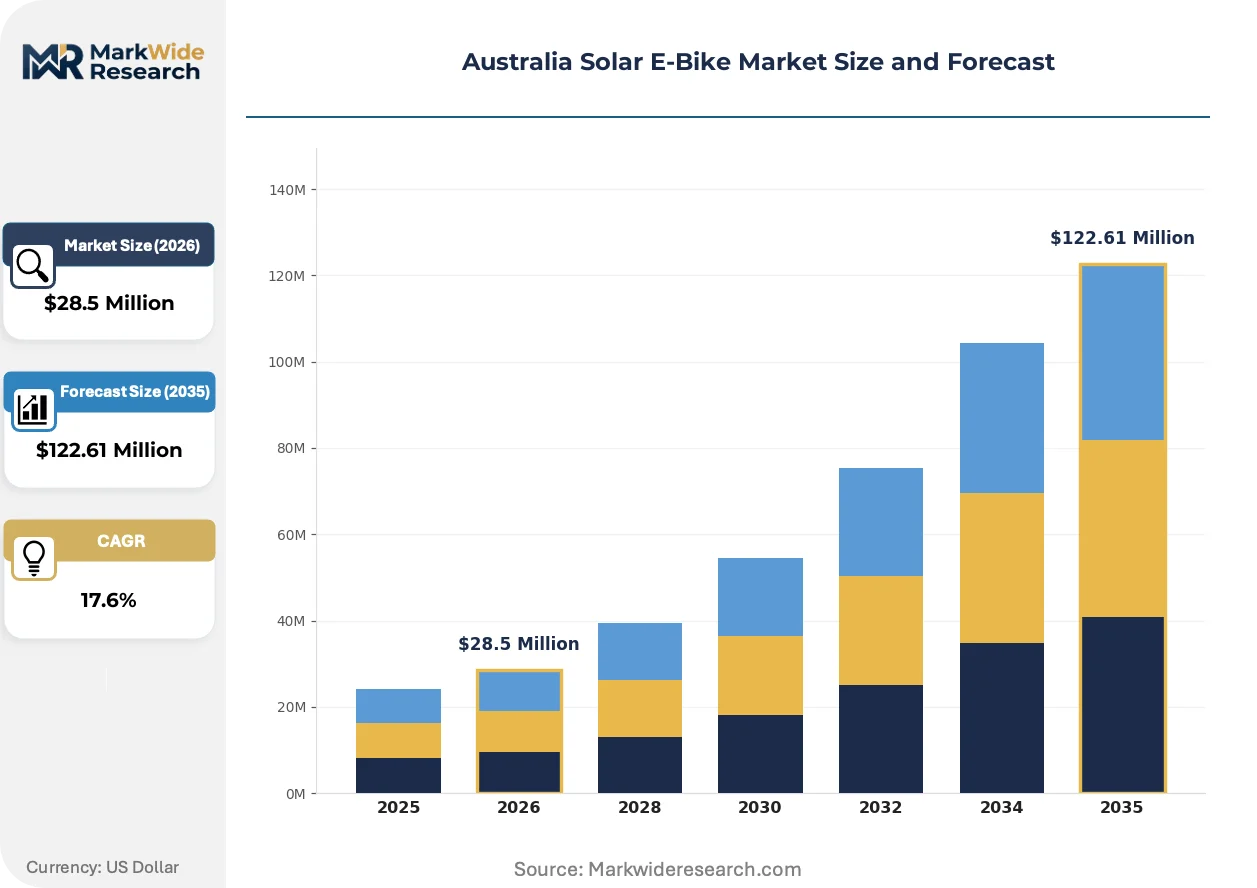
Market Dynamics
The Australian solar e-bike market pivots on tightening power-output thresholds within Australian Design Rules, forcing assemblers to recalibrate motor-battery-solar integration while state infrastructure investments in Victoria and New South Wales accelerate commuter adoption curves.
Growth Catalysts
- State cycling infrastructure programs:Victoria's arterial bike corridors and New South Wales's separated pathway networks reduce perceived commuter risk and expand addressable rider base.
- Australian Design Rules weight restrictions:The 250-watt motor ceiling and pedal-assist mandate favor lithium-ion chemistry adoption over lead-acid alternatives through energy density requirements.
- Photovoltaic efficiency gains:Monocrystalline cell improvements enable 15-25 watt peak output from frame-integrated solar arrays without compromising bicycle aesthetics or handling.
Market Restraints
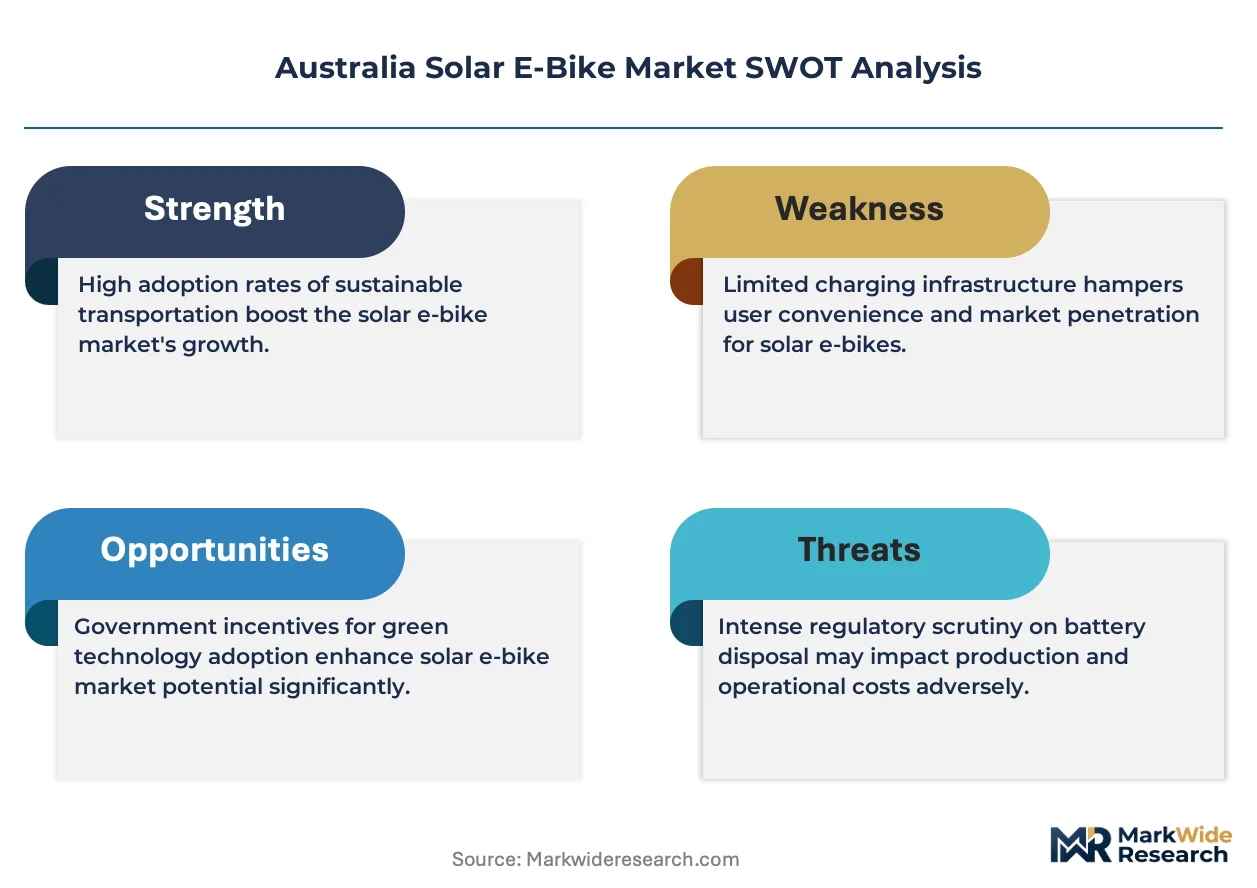
- Battery cell supply concentration:Australian assemblers depend on East Asian cylindrical cell manufacturers, exposing procurement to shipping cost volatility and currency fluctuation.
- Apartment dweller charging access:AC charging infrastructure gaps in multi-unit residential buildings constrain solar e-bike utility for urban core demographics despite solar supplementation.
- TGA transport certification complexity:Integrated solar-battery systems face lithium-ion dangerous goods classification requirements that inflate logistics costs and documentation burden.
Strategic Opportunities
- Western Australia recreational trail expansion:The Munda Biddi Trail and Perth Hills network extensions create demand for long-range solar-assisted touring configurations.
- Queensland state subsidy alignment:Emerging e-mobility incentive frameworks could reduce total cost-of-ownership gaps against conventional bicycles.
- Direct-to-consumer channel maturation:Domestic assembly operations enable configuration customization and post-sale service bundling unavailable through traditional dealer networks.
Industry Challenges
- Electrical Safety Office charger certification timelines:Multi-month approval windows for integrated solar charging systems delay product launch cycles and compress selling seasons.
- Solar array-battery management system integration:Firmware calibration across photovoltaic input variability, lithium-ion charge profiles, and motor controller demand requires specialized embedded systems expertise scarce in Australian labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Solar E-Bike Market |
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $122.61 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding E-Bikes, Mountain E-Bikes, Cruiser E-Bikes, Commuter E-Bikes Battery Type: Lithium-ion Batteries, Lithium Polymer Batteries, Lead Acid Batteries, Nickel Cadmium Batteries Charging Method: Solar Charging, AC Charging, DC Fast Charging, Wireless Charging End User: Outdoor Enthusiasts, Urban Commuters, Delivery Services, Recreational Users |
| Companies Covered | Giant Manufacturing Co., Specialized Bicycle Components, Trek Bicycle Corporation, Merida Bikes Australia, Dyson Bikes, Leon Cycle Pty Ltd, Earth Electric Bikes, The Electric Bicycle Co Pty Ltd, VelectriX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Solar E-Bike Market Trends and Innovations
Solar e-bike evolution in Australia centers on intelligent energy management, regulatory compliance automation, and channel restructuring that collapses traditional distribution layers.
Maximum Power Point Tracking (MPPT) circuitry embedded within battery management systems is automating solar harvest optimization across variable irradiance conditions. Urban commuter segment buyers in Brisbane and Melbourne are specifying these controllers in premium configurations. This automation is compressing range anxiety and enabling smaller solar array footprints without sacrificing daily charge contribution.
The Department of Infrastructure's Australian Design Rules amendment process is tightening pedal-assist sensor calibration requirements. Manufacturers must now submit third-party verification of torque-signal responsiveness and cutoff thresholds. The commuter e-bike category faces the steepest compliance burden, with assemblers pre-emptively redesigning controller firmware to exceed draft thresholds.
Subscription-based battery health monitoring is displacing upfront extended warranty purchases among fleet operators and high-mileage commuters. Brisbane-based courier services and Melbourne food delivery aggregators are piloting per-kilometer battery performance guarantees. This shift concentrates most visibly in capital city commercial applications where utilization rates justify predictive maintenance expenditure.
Australia Solar E-Bike Market Segmentation
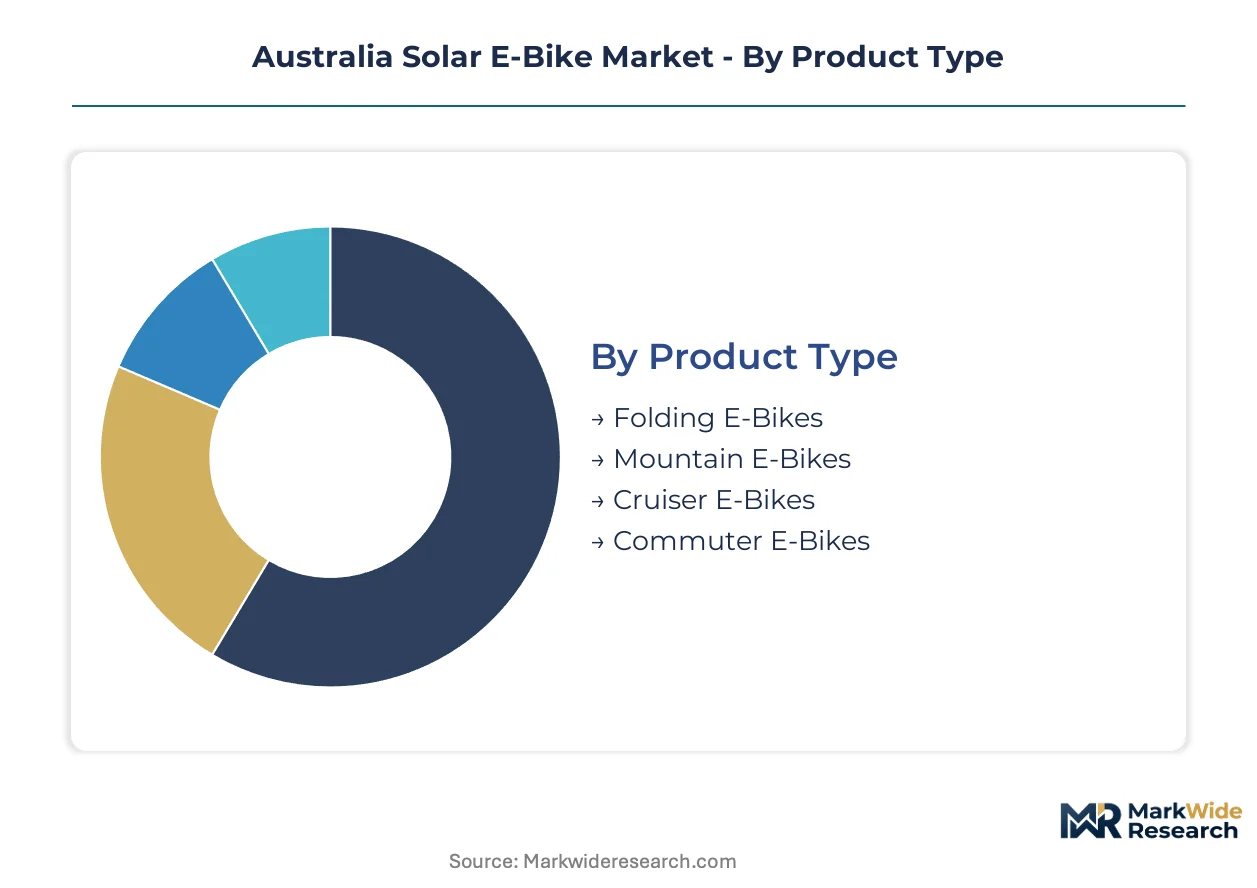
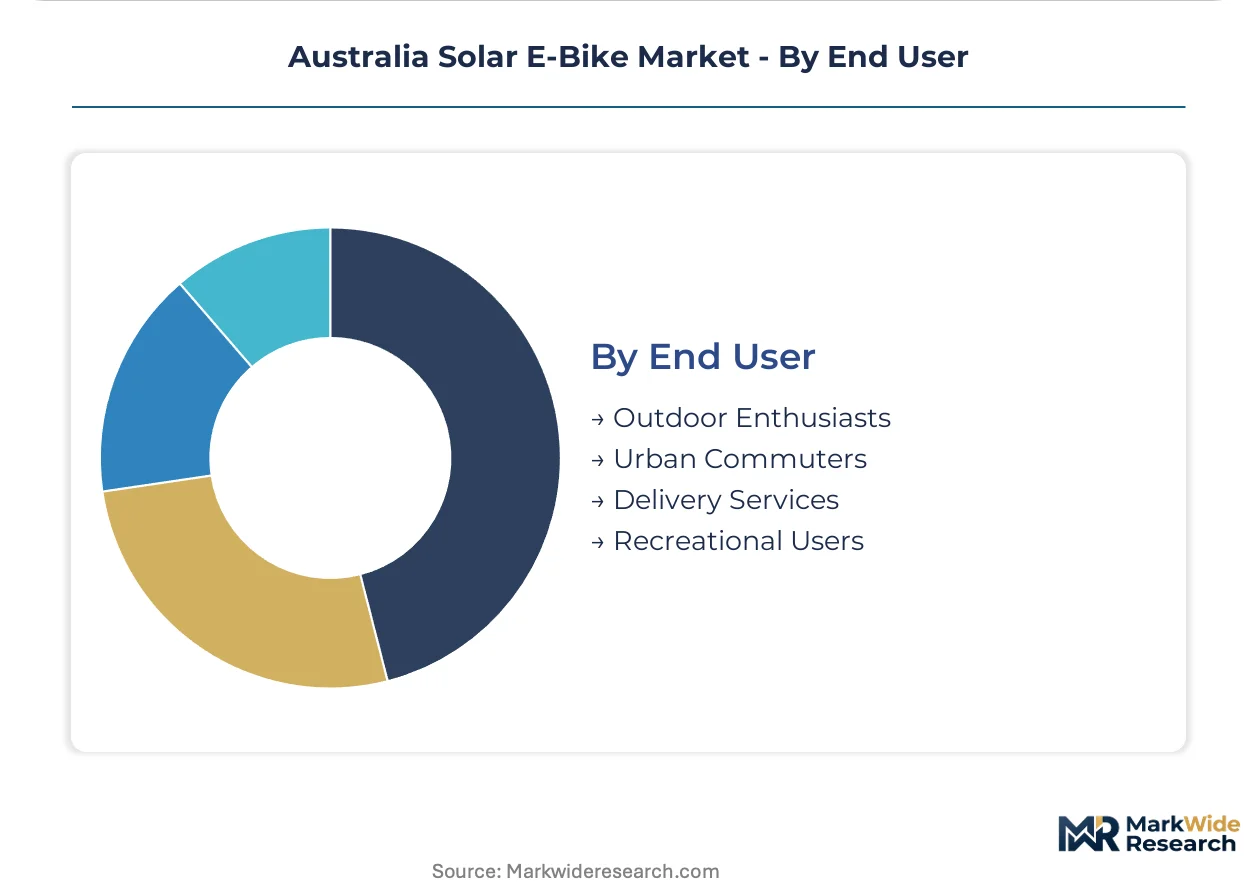
Australian solar e-bike segmentation reveals how regulatory frameworks and infrastructure access shape purchasing patterns across rider profiles. The Department of Infrastructure's Australian Design Rules create divergent compliance burdens that stratify product development priorities and channel economics.
Product Type:
Certification complexity under Australian Design Rules varies sharply across frame architectures, with motor integration and weight distribution triggering different testing protocols for each configuration.
- Commuter E-Bikes:Step-through and diamond-frame designs optimized for 250-watt pedal-assist compliance dominate Melbourne and Sydney arterial corridor usage. Victoria's separated pathway investments and New South Wales's cycle highway expansions concentrate demand among daily riders seeking weather-protected solar array mounting positions.
- Folding E-Bikes:Hinge mechanisms and compact wheelbases accommodate apartment storage constraints in Brisbane and Perth high-density precincts. Frame-integrated solar panels face structural trade-offs that limit peak output to the lower end of the 15-25 watt range.
- Mountain E-Bikes:Suspension travel and ruggedized solar array housings target Western Australia's Munda Biddi Trail and Perth Hills recreational networks.
- Cruiser E-Bikes:Upright riding positions and aesthetic-focused solar integration appeal to coastal recreational users in Queensland.
Commuter e-bikes sit at the top of the volume ranking, with folding e-bikes climbing the fastest as apartment dweller access constraints intensify.
Battery Type:
Energy density requirements under Australian Design Rules weight restrictions have eliminated chemistry options that cannot achieve competitive range-to-mass ratios.
- Lithium-ion Batteries:Cylindrical 18650 and 21700 cell configurations from East Asian manufacturers power the majority of solar e-bike fleets. The TGA's lithium-ion dangerous goods classification for integrated solar-battery systems elevates logistics costs but preserves chemistry dominance through unmatched cycle life and charge rate compatibility with photovoltaic input.
- Lithium Polymer Batteries:Pouch cell architectures enable custom form factors that conform to frame-integrated solar array mounting geometries. Electrical Safety Office certification timelines extend for these configurations due to thermal runaway testing requirements specific to flexible packaging.
- Lead Acid Batteries:Sealed lead-acid variants persist in price-sensitive regional markets but face displacement as weight penalties violate practical solar array mounting limits.
- Nickel Cadmium Batteries:Industrial recycling infrastructure and memory effect limitations restrict adoption to legacy fleet retrofits.
Lithium-ion batteries command the highest shipment volumes, with lithium polymer batteries expanding most quickly as frame integration aesthetics gain priority.
Charging Method:
Utility tariff structures and residential access patterns segment charging infrastructure investment across ownership models.
- Solar Charging:Frame-integrated monocrystalline arrays with MPPT circuitry automate harvest optimization across variable Australian irradiance. This configuration attracts courier services and food delivery aggregators in Brisbane and Melbourne seeking to minimize grid dependency during high-utilization shifts.
- AC Charging:Standard wall-socket interfaces retain majority share due to apartment dweller access constraints in Sydney and Melbourne urban cores. Multi-unit residential building infrastructure gaps limit solar e-bike utility despite supplementary photovoltaic input.
- DC Fast Charging:High-amperage stations target commercial fleet depots with centralized battery swap protocols.
- Wireless Charging:Inductive pad systems remain experimental, constrained by alignment precision requirements and efficiency losses.
AC charging maintains volume leadership, while solar charging gains share fastest among commercial operators with exposed parking assets.
End User:
Utilization intensity and route predictability determine warranty structures and battery health monitoring service attach rates.
- Urban Commuters:Daily riders traversing Melbourne's arterial bike corridors and Sydney's separated pathway networks generate the highest per-unit accessory revenue. Subscription-based battery health monitoring concentrates in this segment where predictive maintenance expenditure justifies against range degradation.
- Delivery Services:Brisbane-based courier services and Melbourne food delivery aggregators pilot per-kilometer battery performance guarantees. High daily mileage and stop-start route profiles accelerate solar array payback periods through reduced grid charging frequency.
- Outdoor Enthusiasts:Long-range touring configurations for Western Australia's trail networks prioritize solar autonomy over speed.
- Recreational Users:Weekend riders in Queensland coastal precincts drive aesthetic-focused solar integration with lower utilization sensitivity to charging infrastructure gaps.
Urban commuters anchor volume rankings, with delivery services recording the steepest expansion trajectory as fleet electrification mandates advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Melbourne's arterial bike corridor network anchors Australian solar e-bike demand concentration. State-level infrastructure investments and regulatory calibration create divergent adoption trajectories across capital cities and regional centers.
New South Wales
Sydney's separated pathway expansions and the NSW cycle highway program reduce commuter risk perception. The state's road authority enforces helmet mandates alongside pathway access permissions that vary by local jurisdiction. Industrial assembly activity clusters in Sydney's inner west, where domestic operators configure solar-battery integrations for metropolitan delivery fleets.
Victoria
Melbourne's arterial bike corridors and the Victorian government's cycling infrastructure program generate the highest per-capita solar e-bike penetration. State-level subsidies for active transport equipment reduce total cost-of-ownership gaps against conventional bicycles. Manufacturing and assembly operations concentrate in Melbourne's northern suburbs, where firms calibrate motor-battery-solar systems to Australian Design Rules thresholds.
Queensland
Brisbane's subtropical climate maximizes solar array efficiency for year-round commuter applications. The state's emerging e-mobility incentive frameworks could accelerate adoption curves if aligned with federal tax treatment. Courier services and food delivery aggregators in Brisbane's CBD pilot per-kilometer battery performance guarantees for high-utilization commercial fleets.
Western Australia
Perth's expanding recreational trail networks and the Munda Biddi Trail extension create demand for long-range touring configurations. The state's road authority maintains distinct pathway access regulations that affect solar e-bike route planning. Regional assembly operations in Perth serve resource sector fly-in-fly-out workers seeking solar-assisted commuting solutions.
South Australia
Adelaide's compact urban form and cycling-friendly topography support solar e-bike utility for short-distance commuting. The state's electrical safety regulator maintains certification timelines that affect product launch cycles for integrated solar charging systems. Limited local assembly presence positions Adelaide as a distribution endpoint rather than a production node.
Australia Solar E-Bike Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channel control and domestic assembly specialization. The market structure fragments across Taiwan-based manufacturing footprints, Australian domestic assemblers, and premium component integrators. Three archetypes dominate: scale-driven frame and motor sourcers, configuration-customizing domestic operators, and premium dealer-network players. Competitive moves concentrate on vertical integration into battery management systems and geographic expansion through state-level subsidy alignment.
Within the domestic assembly tier, Dyson Bikes exemplifies direct-to-consumer channel control, while Giant Manufacturing Co. anchors scale-driven sourcing from Taiwan-based production. Specialized Bicycle Components occupies a position within the premium integration archetype, leveraging dealer network density in Sydney and Melbourne. These three firms represent divergent strategic responses to Australian Design Rules compliance burdens and state infrastructure investment patterns.
| Leading Market Players |
|---|
| Giant Manufacturing Co. |
| Specialized Bicycle Components |
| Trek Bicycle Corporation |
| Merida Bikes Australia |
| Dyson Bikes |
| Leon Cycle Pty Ltd |
| Earth Electric Bikes |
| The Electric Bicycle Co Pty Ltd |
| VelectriX |
| Others |
Pricing and Supply Chain Analysis
Family-owned domestic assemblers anchor Australian solar e-bike supply, translating their limited balance-sheet flexibility into conservative pricing discipline and selective vertical integration into battery management systems. Their capital constraints prevent aggressive price wars while reinforcing procurement loyalty to established East Asian cell suppliers.
Pricing Analysis
Input-cost pass-through from lithium-ion cylindrical cells and monocrystalline photovoltaic arrays dominates pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels separates dealer-network brands with Australian Design Rules certification investment from direct-to-consumer domestic assemblers and import-only economy entrants. Pricing pressure stems from currency fluctuation against the Taiwanese dollar and Korean won, squeezing margin buffers for firms without captive assembly operations. Delivery services and fleet operators exhibit highest price sensitivity due to per-kilometer total cost-of-ownership calculations, while recreational users in Queensland coastal markets absorb premium positioning for aesthetic-integrated solar configurations.
Supply Chain Analysis
Australian Design Rules compliance requirements function as de facto local-content rules, forcing domestic assembly investment for market access despite no explicit domestic-content mandates. Manufacturing concentration centers on Taiwan for frame and motor sourcing, South Korea and Japan for cylindrical lithium-ion cells, and China for photovoltaic wafer processing. Australian assemblers depend on East Asian cell manufacturers for energy density compliance, exposing procurement to shipping cost volatility and port congestion. Single-source vulnerability concentrates in 21700 cell supply from Korean producers. Distribution runs through direct-to-consumer channels for domestic assemblers and dealer networks for premium tier brands, with courier fleet sales bypassing traditional retail layers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian solar e-bike demand compounds steadily as state cycling infrastructure programs in Victoria and New South Wales expand addressable commuter corridors, creating predictable replacement cycles and accessory revenue streams.
For Market Incumbents: Lock in battery management system firmware expertise through targeted hiring from scarce Australian embedded systems labor pools. Secure long-term cell supply agreements with Korean manufacturers before currency volatility intensifies procurement cost unpredictability. Preemptively redesign controller architectures to exceed draft Australian Design Rules torque-signal thresholds, converting compliance burden into competitive moat against import-only competitors lacking domestic engineering presence. For New Entrants and Emerging Players: Courier fleet operators in Brisbane and Melbourne represent the most penetrable segment, with per-kilometer battery performance guarantees creating service-attachment opportunities unavailable to incumbent transactional sellers. Western Australia's Munda Biddi Trail recreational network remains underpenetrated for long-range touring configurations. Pursue direct-to-consumer channel partnerships with commercial parking asset owners to circumvent apartment dweller charging access constraints that limit incumbent growth. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic assemblers with established Electrical Safety Office certification track records and negative working capital cycles from prepaid fleet orders. Long-term viability hinges on sustained state subsidy program alignment and utility tariff structures favoring solar supplementation. Monitor Queensland e-mobility incentive framework finalization as inflection signal for accelerated adoption curves and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Management System In-House Development | Captures firmware calibration expertise scarce in Australian labor markets and required for Australian Design Rules compliance. |
| Direct-to-Consumer Channel Expansion | Bypasses dealer margin layers and enables configuration customization for Melbourne and Sydney delivery fleet specifications. |
| Queensland State Subsidy Alignment | Positions product portfolios for emerging e-mobility incentive frameworks reducing total cost-of-ownership gaps. |
| East Asian Cell Supply Agreement | Locks in cylindrical 21700 procurement from Korean manufacturers before currency volatility compresses margins. |
| MPPT Circuitry Premium Tier Integration | Automates solar harvest optimization for Brisbane courier services seeking minimized grid dependency during high-utilization shifts. |
Research Methodology
Multiple input streams — structured interviews with solar e-bike assemblers and component procurement leads, regulatory filing analysis through the Department of Infrastructure and Electrical Safety Office, and state infrastructure program documentation — were reconciled to construct demand and supply estimates. Primary fieldwork engaged domestic assembly operations managers, dealer network principals in Sydney and Melbourne, fleet procurement officers at Brisbane courier services, and battery management system firmware engineers. Secondary validation drew upon Australian Design Rules amendment drafts, TGA lithium-ion transport classification guidelines, Victorian and New South Wales cycling infrastructure investment disclosures, and customs import records for photovoltaic-equipped bicycle classifications. Bottom-up unit shipment estimates from assembly operations were triangulated against top-down addressable commuter population calculations across capital city cycling corridors.
Data-stream reconciliation applied across the projection horizon segmented volume and value outputs by product type, battery chemistry, charging method configuration, and end-user utilization intensity. CAGRs were derived from infrastructure investment pipeline analysis and regulatory threshold evolution rather than extrapolation of historical growth rates. Forecast inputs incorporated state-level subsidy program probability-weighting, utility tariff trajectory assumptions for apartment dweller grid charging access, and photovoltaic efficiency improvement curves from monocrystalline cell manufacturers.
Revisions become necessary when Australian Design Rules amendment timelines accelerate, East Asian cell supply disruptions materialize, or Queensland e-mobility incentive frameworks deviate from draft structures. Forecasts reflect documented assumptions regarding infrastructure completion schedules and currency stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Global Motor Management Market
Electric Motor
GCC Electric Motor Market
Electric Motor
EV Traction Motor Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
Electric Traction Motor Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Starter Motor Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Kayak Trolling Motor Market