
 Motors for Robot Body and Robot Wheels Market | 2026-2036
Motors for Robot Body and Robot Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Motors for Robot Body and Robot Wheels Market Foresight
The EU AI Act is realigning the cost-of-entry calculus for robot motor suppliers serving European deployers. Nidec Corporation leverages its fractional-horsepower motor portfolio to anchor supply relationships with Asian robot OEMs building export platforms. Maxon Motor AG differentiates through Swiss-precision brushless DC motors optimized for surgical and collaborative robot joints. Yaskawa Electric Corporation dominates servo amplifier integration, bundling motion control with motor hardware to deepen account control.
Motors for robot body and robot wheels encompass electromechanical actuators that convert electrical energy into precise mechanical motion, typically operating at voltage ranges from 12V to 48V DC for mobile platforms and up to 400V AC for industrial articulated arms. These motors integrate encoders, gearheads, and thermal management systems to deliver positional accuracy within 0.1 degrees and continuous torque outputs spanning millinewton-meters to hundreds of newton-meters. Servo motors lead the motor type category due to closed-loop feedback requirements in collaborative and industrial robot arms where repeatability standards are exacting. The application dimension shows autonomous vehicles as the fastest-expanding demand pool, driven by last-mile delivery robot fleets and agricultural autonomous tractors where wheel torque density and IP-rated sealing determine motor selection.
The EU Machinery Directive and CE marking requirements enforced by national market surveillance authorities in France, Germany, and Italy mandate functional safety certifications for motors deployed in human-robot collaborative environments. In the United States, OSHA workplace safety guidelines and FCC electromagnetic compatibility rules shape product design and market access for wheeled service robots operating in commercial buildings. The analysis indicates stakeholders must monitor evolving battery-electric voltage architectures and silicon carbide inverter pairing standards that will redefine motor thermal envelopes and efficiency benchmarks.
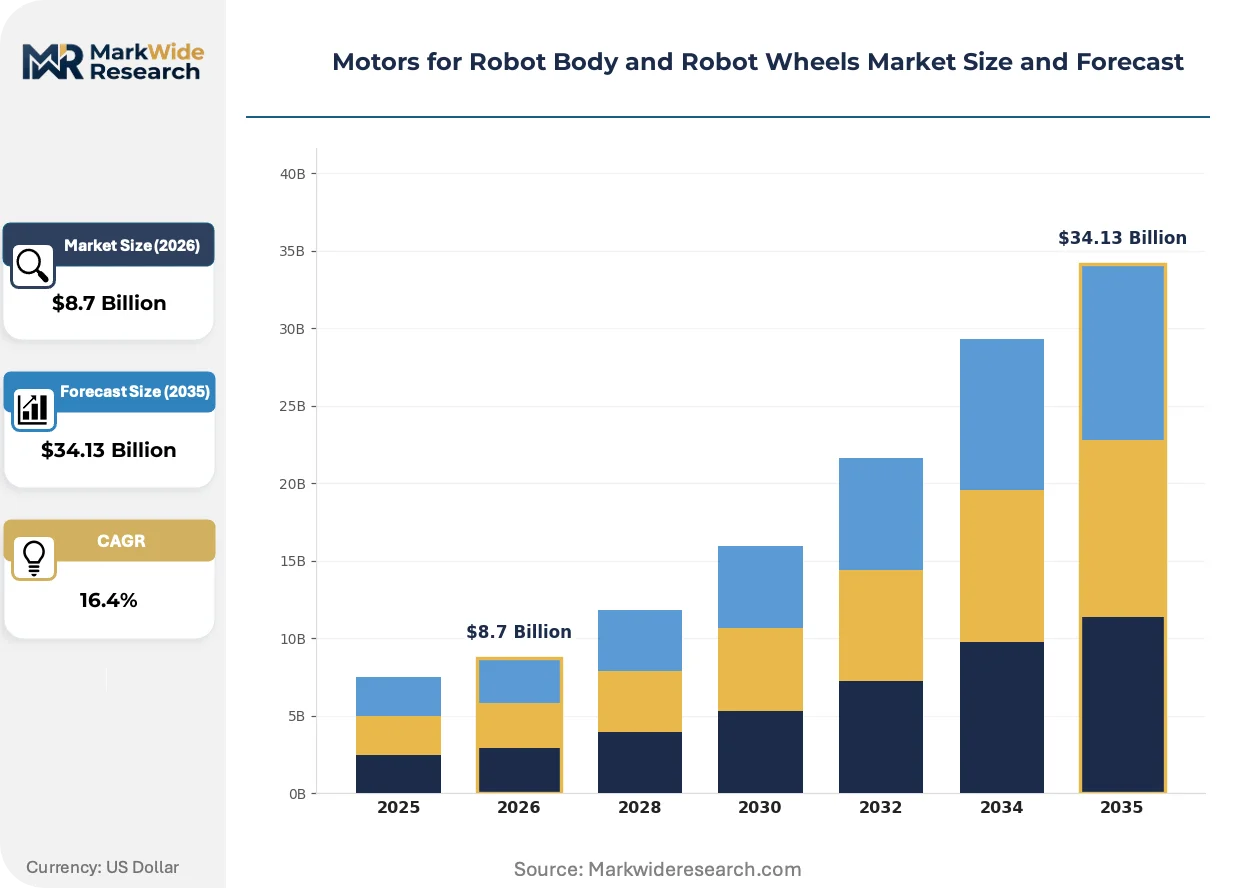
Market Dynamics
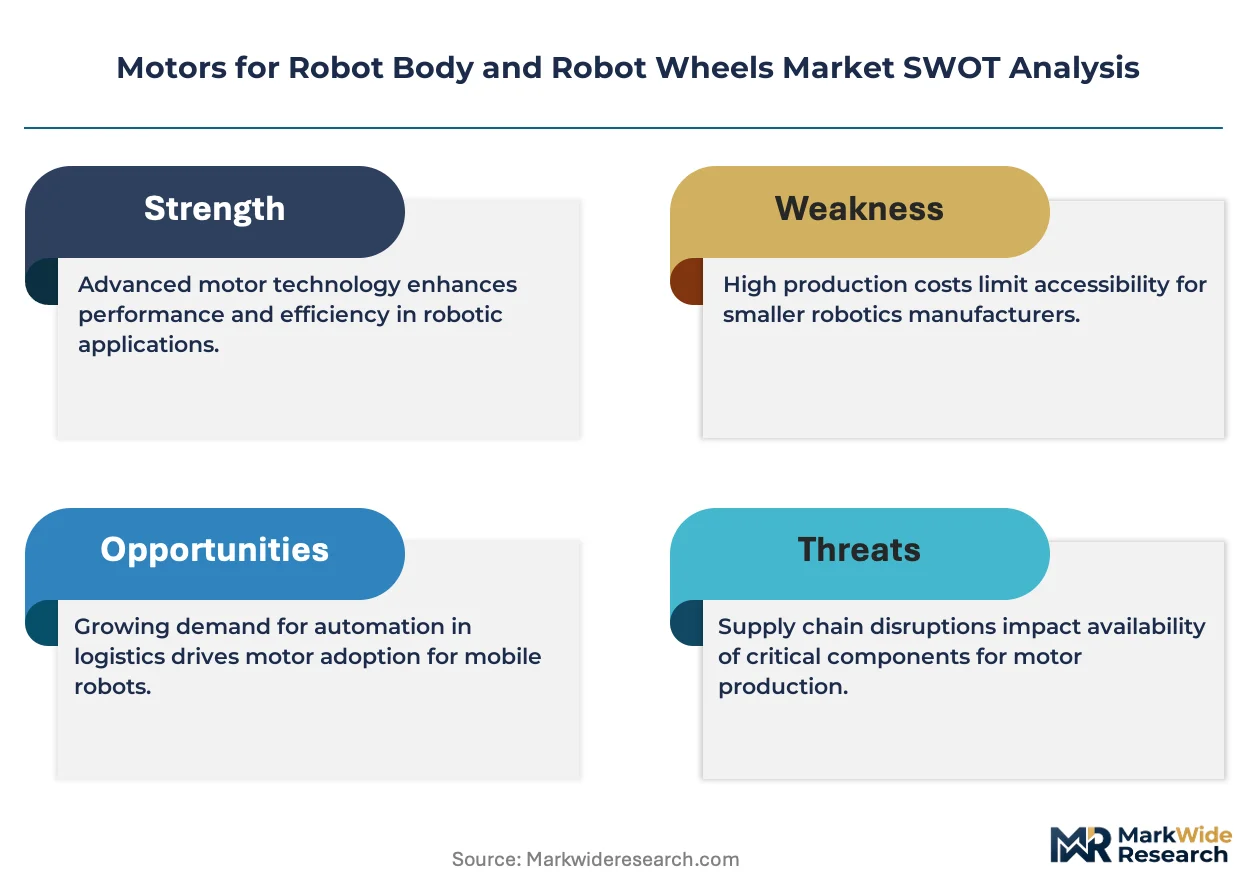
Silicon carbide inverter pairing standards are redefining motor thermal envelopes and efficiency benchmarks, forcing suppliers to redesign winding architectures and cooling systems for next-generation robot platforms.
Growth Catalysts
- EU AI Act:Tightened conformity requirements for autonomous systems near human workers are accelerating demand for certified servo motors with integrated safety encoders in German automotive and intralogistics facilities.
- Last-mile delivery fleets:Warehousing operators scaling autonomous mobile robot deployments require high-torque-density wheel motors with IP-rated sealing for outdoor operation.
- Battery-electric voltage architectures:The shift from 24V to 48V DC platforms is automating motor selection criteria toward higher-efficiency brushless DC designs.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies on Chinese processing capacity create input cost volatility and geopolitical exposure for permanent-magnet motor manufacturers.
- Functional safety certification timelines:CE marking and EU Machinery Directive compliance processes extend product qualification cycles by 12-18 months for collaborative robot motor suppliers.
- Hydraulic actuation in heavy payload segments:Industrial material handling above 500kg continues favoring fluid power systems where electric motor torque density remains insufficient.
Strategic Opportunities
- Agricultural autonomous tractors:Wheel torque density requirements in precision farming equipment create white space for sealed, high-torque direct-drive motor modules.
- US Inflation Reduction Act:Domestic content incentives for battery-electric industrial equipment are reshaping motor sourcing toward North American winding and magnet assembly operations.
- Digital twin integration:Convergence of motor telemetry with predictive maintenance platforms enables outcome-based service models for fleet operators managing thousand-unit robot deployments.
Industry Challenges
- Embedded software certification:IEC 61508 functional safety compliance for motor control firmware requires specialized safety engineering talent that remains scarce in European and North American labor pools.
- Legacy system integration:Retrofitting servo motors into existing robotic cells with proprietary fieldbus protocols demands custom adapter development and extended commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motors for Robot Body and Robot Wheels Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: DC Motor, Servo Motor, Stepper Motor, Linear Motor Control Method: Open Loop, Closed Loop, PWM Control, Feedback Control Application: Industrial Robots, Service Robots, Autonomous Vehicles, Educational Robots Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Nidec Corporation, Yaskawa Electric Corporation, Maxon Motor AG, Faulhaber Group, Oriental Motor Co., Ltd., Panasonic Corporation, ABB Ltd, Beckhoff Automation, Moog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motors for Robot Body and Robot Wheels Market Shifts & Advancements
Three forces are compressing product development cycles in robot motor supply: wide-bandgap semiconductor integration, predictive maintenance platform adoption, and modular motor-gearbox-encoder subassemblies.
Integrated silicon carbide power modules are automating thermal management design in high-frequency servo drives. Automotive tier-one suppliers adopting 800V architectures for electric vehicles are transferring inverter expertise to industrial robot motor controllers, compressing efficiency benchmarks previously set by silicon IGBT designs. This convergence is enabling continuous torque densities above 10 Nm/kg in compact joint actuators.
The EU AI Act's risk-classification framework for autonomous systems is mandating redundant position sensing and fail-safe braking in collaborative robot motors deployed near human workers. German automotive OEMs and French logistics providers are requiring SIL-3 certified encoders as standard procurement specifications, disqualifying uncertified suppliers from new platform bids. National market surveillance authorities in Italy are accelerating enforcement of these requirements through unannounced factory inspections.
Direct procurement relationships between end-use fleet operators and motor suppliers are disintermediating traditional distribution channels in high-volume segments. Amazon Robotics and Ocado Group are establishing captive engineering teams to specify custom wheel motor architectures, bypassing robot OEMs in component selection. This pattern is most visible in North American and British warehousing markets where thousand-unit fleet standardization justifies dedicated supplier development programs.
Motors for Robot Body and Robot Wheels Market Segmentation
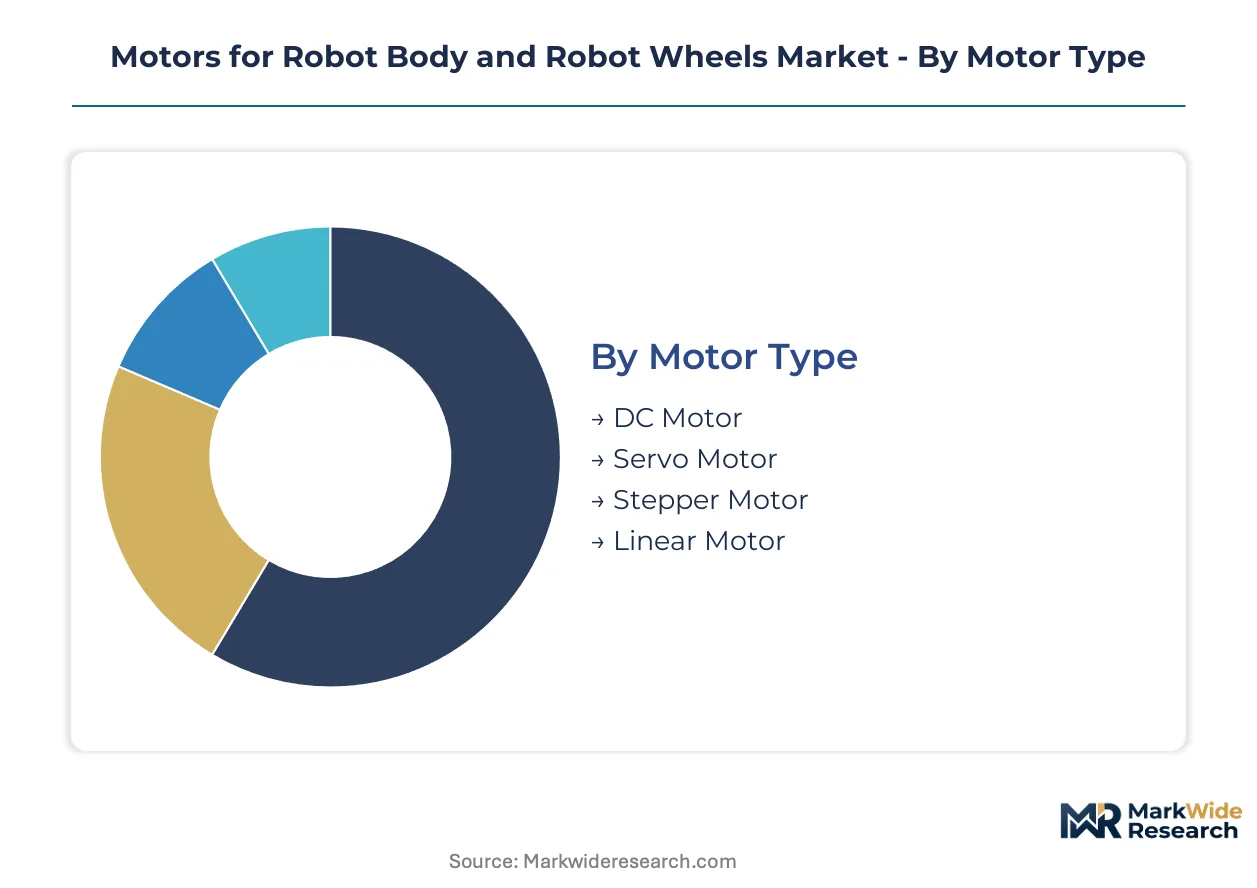
Motor specification dictates thermal envelope, feedback architecture, and safety certification requirements across robot platforms. Segmentation by motor type, control method, application, and power rating reveals where component suppliers must align winding designs with end-use duty cycles.
Motor Type:
Rotary electromagnetic actuators differentiate by commutation method, magnet material, and positional feedback integration.
- Servo Motor:Brushless DC designs with integrated encoders deliver closed-loop positional accuracy within 0.1 degrees. Demand concentrates in German automotive assembly cells and French logistics facilities where EU AI Act compliance mandates SIL-3 certified feedback systems.
- DC Motor:Brushed and brushless permanent-magnet configurations operate at 12V to 48V for mobile platforms. Last-mile delivery robot fleets in North American warehousing specify IP-rated sealed variants for outdoor wheel propulsion.
- Stepper Motor:Hybrid stepper designs with microstepping drives suit low-cost educational robot joints and precision positioning stages where absolute encoder cost is prohibitive.
- Linear Motor:Direct-drive electromagnetic actuators eliminate mechanical transmission for Cartesian robot axes and semiconductor handling equipment requiring micron-level repeatability.
Mature deployment sits with DC motors in cost-sensitive mobile platforms. Newer deployment is concentrated in servo motors for collaborative robot joints requiring functional safety certification.
Control Method:
Feedback architecture determines trajectory accuracy, power efficiency, and compliance with machinery safety directives.
- Closed Loop:Encoder-based position feedback enables real-time error correction for collaborative robot arms and surgical platforms. EU Machinery Directive enforcement in Italy and Germany accelerates procurement of certified closed-loop servo systems.
- Feedback Control:Multi-sensor fusion incorporating current, temperature, and position sensing supports predictive maintenance in thousand-unit autonomous mobile robot fleets.
- PWM Control:Pulse-width modulation of MOSFET or silicon carbide inverters governs speed and torque in battery-electric wheel motors for agricultural autonomous tractors.
- Open Loop:Stepper motor drive without position verification persists in educational robots and low-payload pick-and-place systems where cost minimization outweighs accuracy requirements.
Volume concentration favors open-loop controllers in entry-level educational segments. Steepest expansion trajectory belongs to feedback control architectures integrating motor telemetry with fleet management platforms.
Application:
End-use duty cycles range from continuous industrial operation to intermittent service deployment and outdoor autonomous navigation.
- Autonomous Vehicles:Last-mile delivery robots and agricultural tractors demand wheel motors with torque density above 10 Nm/kg and IP67 sealing for dust and moisture ingress protection.
- Industrial Robots:Six-axis articulated arms and SCARA platforms specify servo motors with harmonic drive gearheads for repetitive assembly operations in German and Japanese automotive plants.
- Service Robots:Hospitality and healthcare wheeled platforms prioritize acoustic signature reduction and brushless designs for human-robot collaborative environments.
- Educational Robots:STEM kit manufacturers drive demand for low-cost DC motors with plastic gearboxes and minimal thermal management.
Established procurement patterns center on industrial robots in automotive manufacturing. Emerging demand clusters in autonomous vehicles where battery-electric voltage architectures are redefining motor efficiency benchmarks.
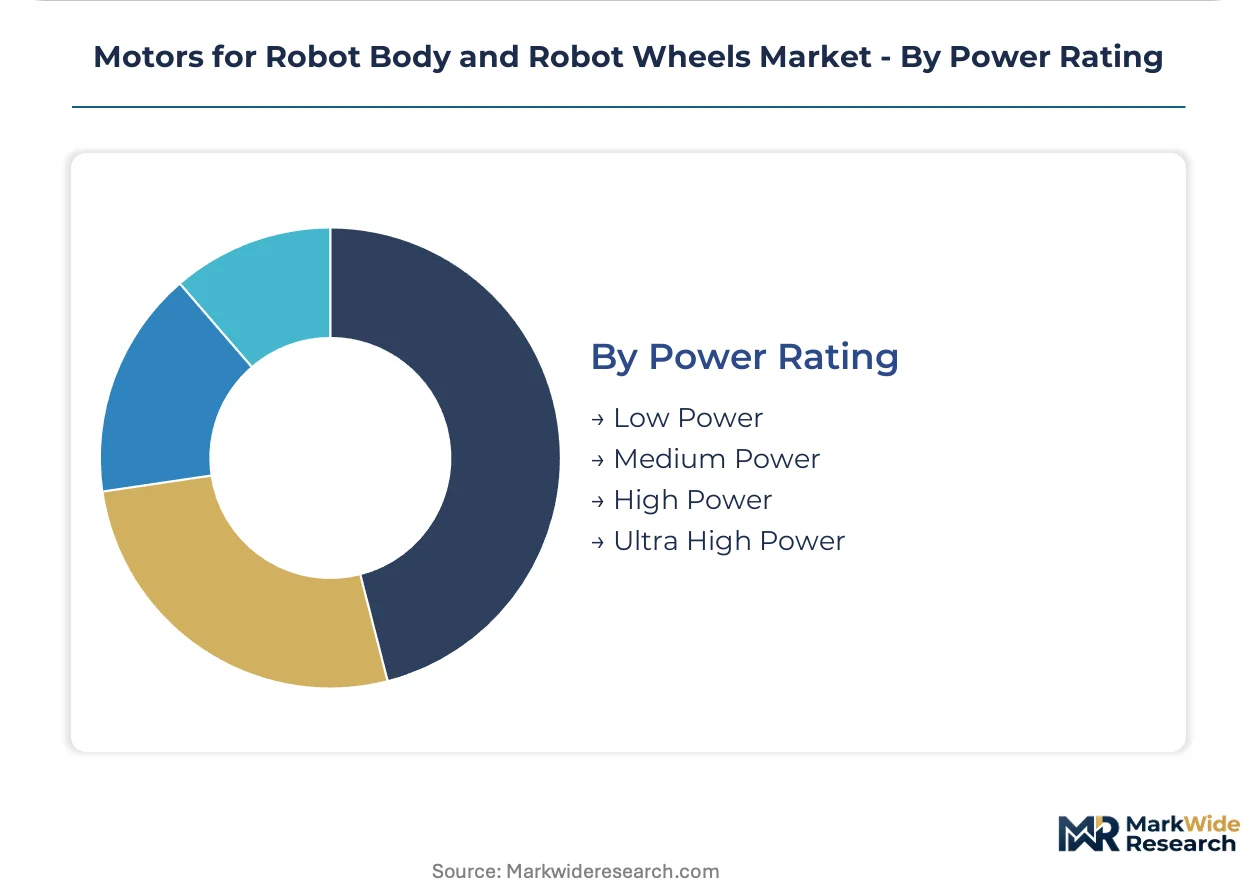
Power Rating:
Thermal dissipation capacity and winding gauge scale with continuous and peak torque requirements.
- Medium Power:100W to 500W continuous output serves collaborative robot joints and autonomous mobile robot wheel drives where compact envelope and moderate torque density balance cost and performance.
- High Power:500W to 2kW designs with liquid cooling support industrial material handling arms and outdoor autonomous tractors operating at 48V DC or 400V AC.
- Low Power:Sub-100W motors with integrated gearheads dominate educational robot kits and small service robot mobility bases.
- Ultra High Power:Above 2kW direct-drive motors with forced air or liquid cooling address heavy-payload industrial automation where hydraulic displacement faces electrification pressure.
Procurement volume aggregates in medium power ratings for collaborative and mobile robot platforms. Technology investment is concentrating in high power segments where silicon carbide inverter pairing enables thermal envelope expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free trade zones in Bavaria and Baden-Württemberg concentrate precision motor manufacturing for European robot OEMs. Shenzhen's Qianhai Special Economic Zone anchors brushless DC motor assembly for Asian mobile robot exporters. These tax-advantaged clusters amplify regional specialization in servo and wheel motor supply chains.
Germany
Automotive OEMs in Stuttgart and Munich scale servo-driven collaborative robot cells for final assembly operations. EU Machinery Directive enforcement by KBA and federal state authorities mandates SIL-3 certified encoders for human-robot collaborative environments. The Mittelstand belt in Baden-Württemberg hosts precision gearhead manufacturers supplying harmonic drive integrations for six-axis arms.
United States
Amazon Robotics and FedEx Ground deploy thousand-unit autonomous mobile robot fleets in Midwestern distribution hubs. OSHA workplace safety guidelines and FCC electromagnetic compatibility rules shape wheeled service robot designs for commercial buildings. Greater Boston's robotics corridor concentrates venture-backed startups specifying custom 48V DC wheel architectures for last-mile delivery platforms.
China
MIIT industrial robot subsidy programs accelerate domestic servo motor adoption in Yangtze River Delta manufacturing clusters. GB standards for robot safety and NMPA-equivalent machinery certification tighten conformity requirements for collaborative platforms. Shenzhen and Dongguan electronics assemblers integrate fractional-horsepower motors into export-bound educational and service robot kits.
Japan
METI's Society 5.0 initiative funds human-robot collaborative installations in Aichi Prefecture automotive plants. JIS standards for industrial robot safety align with IEC 61508 functional safety benchmarks for motor control systems. Kansai region precision manufacturers supply compact servo actuators for surgical robot joints requiring sub-millimeter positioning repeatability.
South Korea
MFDS-equivalent industrial safety regulators enforce CE-parallel certification for collaborative robot motors deployed in Incheon and Gwangju electronics factories. Government smart factory subsidies drive servo amplifier integration in Daegu-Gyeongbuk manufacturing hubs. Seoul Capital Area system integrators specify high-torque-density wheel motors for semiconductor cleanroom autonomous transport vehicles.
Motors for Robot Body and Robot Wheels Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across motor type and control integration tiers. The supplier base organizes around three strategic archetypes: Japanese and Swiss precision specialists, diversified Asian electronics conglomerates, and European automation platform vendors. Competitive positioning hinges on silicon carbide inverter pairing capabilities and functional safety certification depth. M&A activity targets encoder and sensor suppliers, while greenfield capacity concentrates in Vietnamese and Mexican export zones.
Among precision motor specialists, Maxon Motor AG and Faulhaber Group exemplify Swiss and German engineering heritage in compact servo actuation. Nidec Corporation anchors the diversified industrial electronics tier with fractional-horsepower motor portfolios scaled across consumer, industrial, and mobility applications. These three companies represent distinct competitive positions: precision-focused European specialists versus volume-scaled Asian conglomerates versus integrated automation platform vendors such as Yaskawa Electric Corporation.
| Leading Market Players |
|---|
| Nidec Corporation |
| Yaskawa Electric Corporation |
| Maxon Motor AG |
| Faulhaber Group |
| Oriental Motor Co., Ltd. |
| Panasonic Corporation |
| ABB Ltd |
| Beckhoff Automation |
| Moog Inc. |
| Others |
Supply & Pricing Matrix
Neodymium and dysprosium price indices from Chinese processing facilities cascade through permanent-magnet motor supply chains, compressing margins in economy-tier brushed DC designs while reinforcing premium positioning for certified servo systems with rare-earth-independent winding architectures.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to SIL-3 certified servo motors with integrated safety encoders demanded by German automotive OEMs under EU Machinery Directive enforcement. Pricing stratifies across premium certified, standard industrial, and economy mobile-platform tiers differentiated by encoder grade and thermal management sophistication. Cost compression in economy DC wheel motors intensifies as warehousing fleet operators consolidate thousand-unit procurement contracts. Educational robot kit manufacturers exhibit highest price sensitivity, while surgical robot OEMs prioritize positioning repeatability over unit cost.
Supply Chain Analysis
CE marking and EU Machinery Directive qualification gates filter supplier participation, extending product development cycles for uncertified entrants attempting European market access. Magnet wire winding and precision gearhead manufacturing concentrates in Germany, Japan, and Switzerland. Rare-earth magnet processing draws from Chinese separation facilities, with copper rotor bar sourcing anchored in Chilean mining operations. Single-source vulnerability in neodymium oxide supply creates exposure to export restriction shocks. Distribution runs through robot OEM specification teams and direct fleet-operator procurement channels in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with functional safety certification depth, as EU AI Act enforcement and CE marking mandates force uncertified component vendors toward acquisition or exit.
For Market Incumbents: To counter silicon carbide inverter integration by automotive-tier suppliers transferring expertise to industrial robotics, deepen encoder certification portfolios and establish captive magnet wire winding in Vietnam or Mexico export zones. Acquire distressed sensor suppliers to consolidate feedback architecture control. For New Entrants and Emerging Players: Agricultural autonomous tractor wheel modules present a technology-first wedge with torque density requirements unmet by incumbent hydraulic displacement suppliers. Target North American precision farming equipment OEMs with sealed direct-drive architectures. Pursue joint development agreements bypassing traditional robot OEM specification gates. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier servo specialists with incomplete SIL certification pipelines in Baden-Württemberg and Aichi Prefecture manufacturing clusters. Five-to-ten-year viability hinges on silicon carbide pairing capabilities and software-defined motor control firmware assets. Monitor unannounced factory inspections by Italian national market surveillance authorities as enforcement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | SIL-3 encoder integration secures German automotive platform specifications under EU AI Act risk classification. |
| Rare-Earth Magnet Supply Diversification | Non-neodymium winding architectures reduce Chinese processing dependency for collaborative robot joint motors. |
| Silicon Carbide Inverter Pairing | Wide-bandgap semiconductor integration compresses thermal envelopes beyond silicon IGBT efficiency benchmarks. |
| Direct Fleet-Operator Procurement Channel | Amazon Robotics and Ocado Group captive engineering teams disintermediate traditional robot OEM distribution. |
| Predictive Maintenance Platform Integration | Motor telemetry convergence enables outcome-based service contracts for thousand-unit autonomous mobile robot fleets. |
Research Methodology
Trade flow databases, industrial robot production statistics, and rare-earth magnet pricing indices formed the secondary backbone, supplemented by primary interviews with servo motor R&D directors, warehouse automation procurement leads, and precision gearhead manufacturing engineers. Bottom-up unit economics triangulated against top-down market sizing across motor type, control method, application, and power rating segmentation dimensions.
Historical trendline analysis of automotive electrification technology transfer patterns informed the projection framework across the modeling period. Segmentation modeling incorporated motor commutation architecture, feedback system certification tier, end-use duty cycle intensity, and regional regulatory cluster adoption velocity. CAGRs derived from fitted growth curves adjusted for technology substitution effects in hydraulic-to-electric actuation transitions.
Several conditions sit outside the modeled scope, including geopolitical trade restriction scenarios and breakthrough superconducting motor commercialization timelines. Forecasts embed assumptions regarding EU Machinery Directive enforcement consistency and silicon carbide inverter cost curves. A model refresh is warranted upon material change in rare-earth export licensing regimes or 800V automotive architecture adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
EV Traction Motor Market
Electric Motor
Europe Electric Commercial Vehicle Battery Pack Market
Electric Motor
Electric AC Motors Market
Electric Motor
US Solar E-Bike Market
Electric Motor
UK Solar E-Bike Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Global Motor Management Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Industrial Smart Motor Market
Electric Motor
Electric Drives Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Global Electric Motors for Electric Vehicle Market