
 Handheld XRF Analyzers Market | 2026-2036
Handheld XRF Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld XRF Analyzers Market Outlook
China's expanding semiconductor fabrication capacity is reshaping regional demand for elemental purity verification. Bruker Corporation leverages its European-installed base to sustain aftermarket service revenue across German automotive labs. Thermo Fisher Scientific anchors North American government procurement through EPA-aligned calibration protocols. SciAps, Inc. competes on detector miniaturization for confined-space industrial deployments.
Handheld XRF analyzers are portable spectrometers that bombard samples with primary X-ray radiation to induce characteristic fluorescent emission, measuring elemental composition from magnesium to uranium with detection limits reaching single-digit parts per million. These instruments serve mining geologists, scrap yard operators, and hazmat teams requiring immediate material identification without destructive sampling. Portable units dominate unit shipments due to battery-operated field utility, while smartphone-compatible configurations represent the fastest-expanding margin pool as Bluetooth-enabled sensors displace standalone displays. Mining applications generate the largest revenue share through blast-hole assay workflows, though materials recycling is accelerating fastest as London Metal Exchange pricing volatility drives real-time scrap sorting.
EPA methods 6200 and 3050 govern soil screening protocols that dictate detector resolution requirements for US environmental remediation contracts. REACH Annex XVII restrictions on heavy metals in consumer products compel European manufacturers to deploy inline XRF verification, while China's GB standards for electronic waste recycling mandate comparable elemental analysis. Stakeholders must monitor silicon drift detector yield rates and RoHS scope expansion timelines to calibrate R&D allocation between sensitivity improvements and form factor reduction.
Market Dynamics
The handheld XRF analyzer market is experiencing structural compression as silicon drift detector yield improvements collide with expanding RoHS enforcement scope, forcing manufacturers to choose between sensitivity investments and form factor reduction.
Growth Catalysts
- REACH Annex XVII heavy metal restrictions:European consumer goods manufacturers deploy inline XRF verification to comply with hazardous substance limits, creating installed base expansion across German and French production facilities.
- London Metal Exchange pricing volatility:Scrap metal recyclers in East Asian manufacturing corridors invest in real-time elemental analysis to optimize sorting margins and reduce commodity exposure.
- Smartphone-compatible sensor modules:Bluetooth-enabled XRF peripherals are virtualizing display hardware, opening field deployment in confined industrial spaces previously inaccessible to standalone units.
Market Restraints
- Silicon drift detector supply concentration:Japanese and German component specialists control high-purity silicon crystal supply, exposing analyzer manufacturers to input cost volatility and allocation constraints.
- EPA Method 6200 resolution thresholds:US environmental remediation contracts mandate detector specifications that exclude lower-tier hardware, fragmenting addressable demand across certification tiers.
- Laboratory-grade benchtop systems:Centralized testing facilities in mature markets retain preference for higher-precision stationary equipment, limiting portable unit penetration in regulated quality assurance workflows.
Strategic Opportunities
- China's GB electronic waste standards:Mandatory elemental analysis for e-waste recycling creates compliance-driven demand across Guangdong and Jiangsu processing clusters.
- Drone-mounted XRF payloads:Integration with unmanned aerial platforms enables rapid mine site surveying without personnel exposure to hazardous terrain.
- India's BIS precious metal certification:Hallmarking mandates for jewelry retail are expanding assay verification requirements beyond traditional laboratory infrastructure.
Industry Challenges
- Calibration technician scarcity:Field service networks struggle to recruit personnel capable of maintaining EPA-aligned calibration protocols across dispersed environmental remediation sites.
- Multi-jurisdiction certification timelines:Analyzer manufacturers face divergent approval pathways between FCC electromagnetic compliance, CE marking, and China's MIIT radio equipment regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld XRF Analyzers Market |
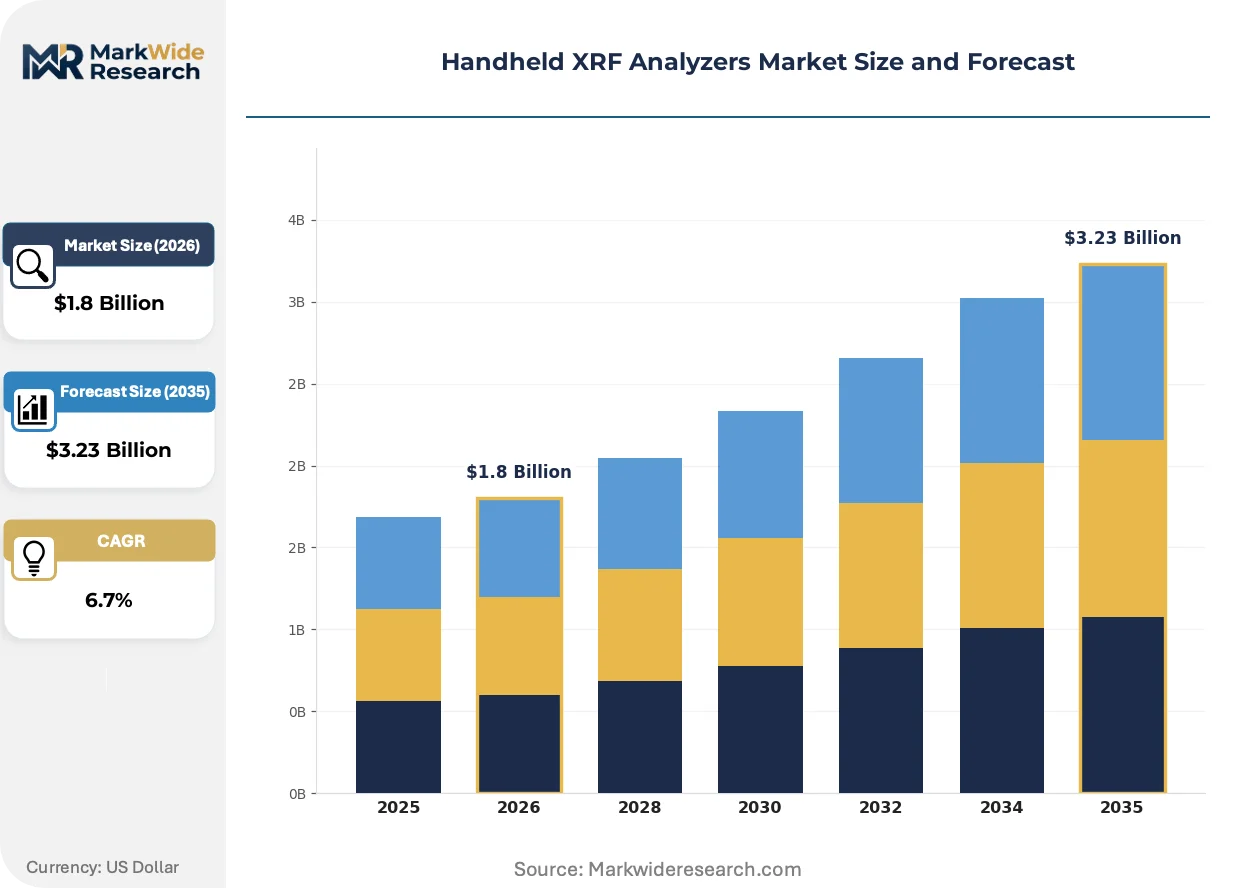
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Desktop, Integrated, Smartphone-Compatible Application: Mining, Environmental Testing, Materials Recycling, Construction Technology: X-Ray Fluorescence, Energy Dispersive X-Ray Spectroscopy, Wavelength Dispersive X-Ray Spectroscopy, Optical Emission Spectroscopy End User: Government Agencies, Private Laboratories, Manufacturing Industries, Research Institutions |
| Companies Covered | Thermo Fisher Scientific Inc., Bruker Corporation, Olympus Corporation, Hitachi High-Tech Analytical Science, AMETEK Inc., HORIBA Ltd., Rigaku Corporation, Oxford Instruments plc, SciAps, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld XRF Analyzers Market Strategic Shifts
Detector miniaturization is converging with wireless data architectures to reshape how elemental analysis moves through industrial workflows. Three developments are compressing traditional hardware margins while opening new deployment contexts.
Silicon drift detector arrays are virtualizing the signal processing chain that previously required dedicated onboard electronics. Mining geologists in Australian and Chilean operations are adopting smartphone-tethered configurations to reduce field kit weight. This architecture is virtualizing the display and control layer, enabling sub-kilogram form factors that penetrate blast-hole assay workflows previously served by heavier standalone units.
EU F-Gas Regulation phase-down schedules are restricting refrigerant options for detector cooling systems, compelling manufacturers to redesign thermal management around solid-state alternatives. Industrial equipment suppliers in German automotive labs are accelerating qualification of thermoelectrically cooled detectors to maintain analytical performance without banned refrigerants. The transition is compressing development cycles for European-market product variants while creating specification divergence from US and Asian hardware lines.
Service unbundling is separating hardware ownership from analytical capability access. Scrap yard operators in US Midwest metal recycling clusters are migrating toward subscription-calibration models that transfer detector maintenance liability to OEM service networks. This shift is visible most acutely in high-volume ferrous sorting facilities where uptime guarantees outweigh capital ownership preferences.
Handheld XRF Analyzers Market Segmentation
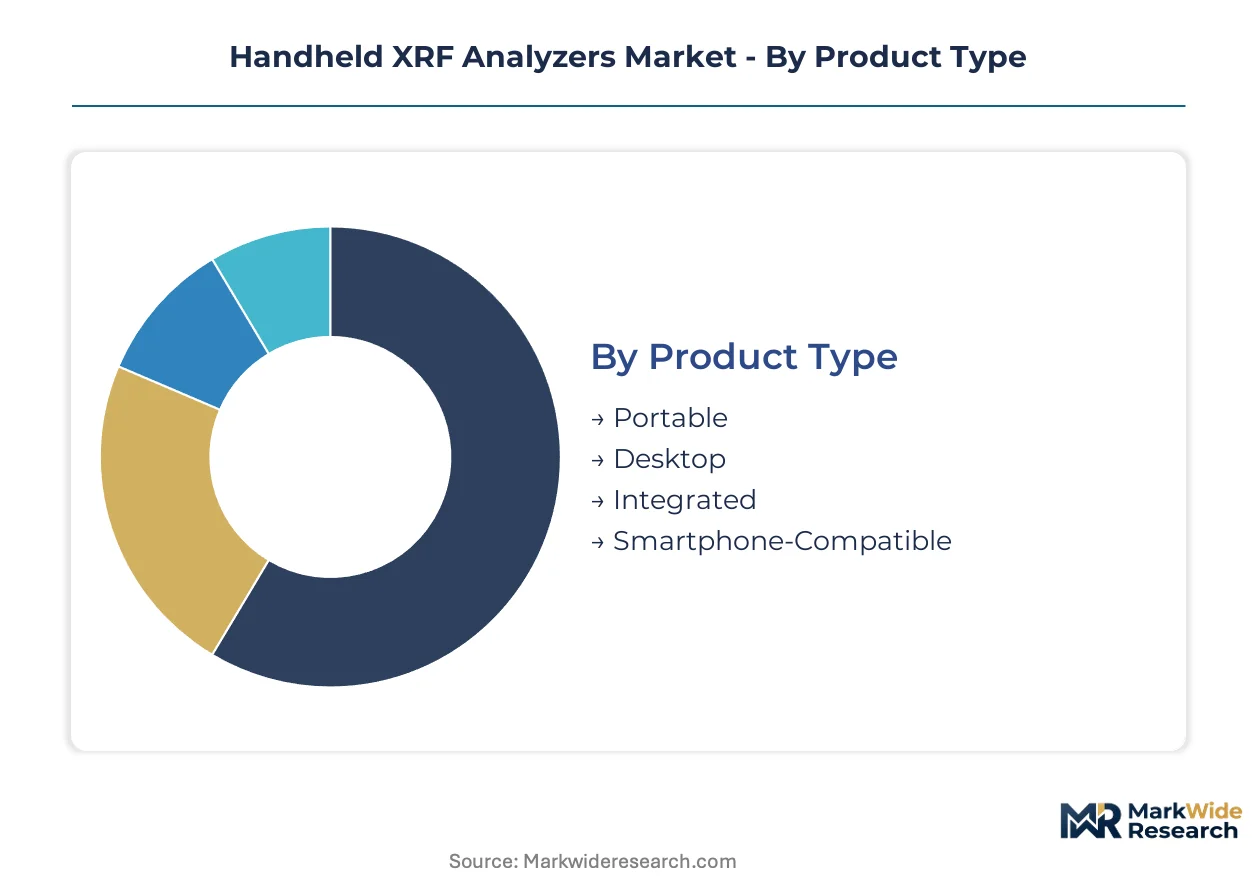
Handheld XRF analyzers serve divergent operational contexts, from blast-hole geochemistry to regulatory compliance screening. Understanding how product configurations, analytical methods, and user requirements intersect reveals where hardware margins concentrate and where commoditization pressures build fastest.
Product Type:
Use-case spectrum spans field-deployable rugged units through smartphone-tethered modules that virtualize display hardware entirely.
- Portable:Battery-operated units with sealed housings dominate mining and environmental remediation workflows. Australian and Chilean geologists prioritize sub-2kg form factors for all-day field carry. Demand concentrates in East Asian scrap metal corridors where London Metal Exchange pricing volatility drives real-time sorting investments.
- Smartphone-Compatible:Bluetooth-enabled detector peripherals eliminate dedicated display electronics, enabling deployment in confined industrial spaces. German automotive labs are qualifying these configurations for inline REACH compliance verification where workstation footprint constraints exclude standalone hardware.
- Desktop:Stationary configurations with enhanced thermal stability serve laboratory calibration reference functions. Research institutions in Japan deploy these for detector standardization protocols.
- Integrated:Fixed-mount systems embed directly into production lines for continuous materials verification. Chinese electronics manufacturers integrate these for GB standards compliance in e-waste recycling streams.
The dominant share belongs to Portable, while Smartphone-Compatible is closing the gap fastest.
Application:
Commercial intensity varies sharply between commodity-driven bulk analysis and regulatory-mandated trace detection.
- Mining:Blast-hole assay workflows demand magnesium-to-uranium coverage with single-digit ppm detection limits. Operations in Western Australia and northern Chile drive replacement cycles tied to exploration budget cycles.
- Materials Recycling:Scrap yard operators require rapid alloy identification to optimize ferrous and non-ferrous sorting margins. Facilities in Germany's Ruhr Valley and US Midwest industrial corridors are expanding adoption following EU REACH and domestic EPA enforcement intensification.
- Environmental Testing:Soil screening under EPA Method 6200 mandates specific detector resolution thresholds that fragment addressable demand across certification tiers. US remediation contractors face procurement constraints from calibration technician scarcity.
- Construction:Lead paint and hazardous materials assessment in renovation workflows. US housing stock remediation and European heritage building restoration create intermittent demand spikes.
Mining retains the largest revenue footprint, though Materials Recycling exhibits the steepest expansion trajectory.
Technology:
Detector architecture selection determines sensitivity ceilings, cooling requirements, and unit economics across deployment contexts.
- X-Ray Fluorescence:Primary radiation excitation with silicon drift detector signal capture serves the broadest elemental range. Japanese and German component specialists control high-purity silicon crystal supply, exposing manufacturers to input allocation constraints.
- Energy Dispersive X-Ray Spectroscopy:Solid-state detector arrays with multi-channel analyzers enable rapid multi-element quantification. EU F-Gas Regulation phase-down schedules are forcing thermoelectric cooling redesigns for European-market variants.
- Wavelength Dispersive X-Ray Spectroscopy:Crystal dispersion optics deliver superior resolution for light element detection. Benchtop configurations retain preference in centralized testing facilities where precision outweighs portability requirements.
- Optical Emission Spectroscopy:Arc or spark excitation for metallic samples complements XRF in alloy verification workflows. Steel mills in India's Maharashtra and Gujarat states deploy hybrid analytical protocols.
X-Ray Fluorescence commands the installed base, while Energy Dispersive X-Ray Spectroscopy is gaining share fastest through miniaturization advances.
End User:
Procurement authority and technical specification authority often diverge, complicating vendor sales cycles.
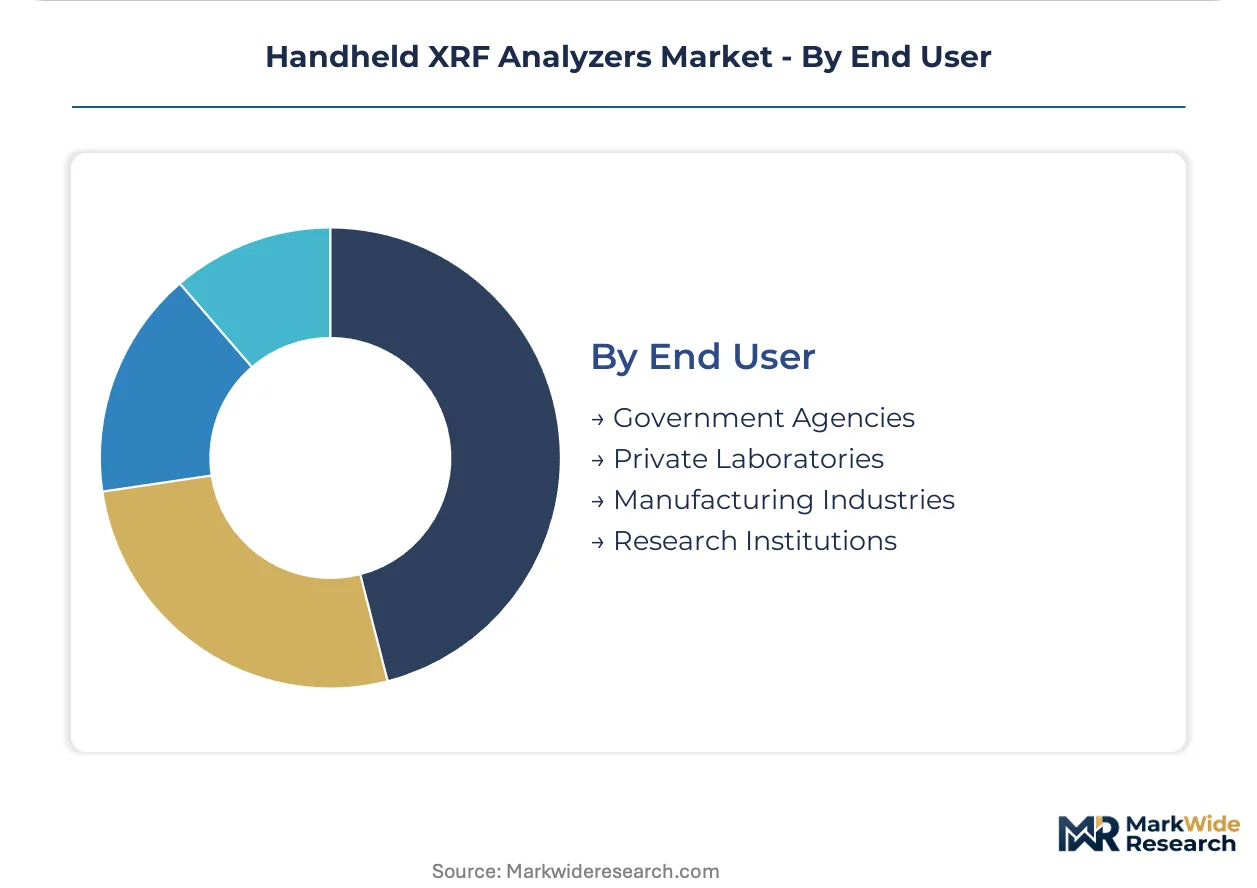
- Government Agencies:EPA-aligned calibration protocols and FCC electromagnetic compliance requirements structure US federal and state procurement. Environmental remediation contracts mandate detector specifications that exclude lower-tier hardware.
- Manufacturing Industries:Inline quality verification for RoHS and REACH compliance drives private capital deployment. Electronics assemblers in China's Guangdong and Jiangsu provinces face mandatory GB standards adherence.
- Private Laboratories:Commercial testing services balance throughput volume against capital equipment utilization rates. Centralized facilities in mature markets retain preference for higher-precision stationary systems.
- Research Institutions:Detector standardization and method development activities support academic and government laboratory networks. Calibration reference material production concentrates in national metrology institutes.
Manufacturing Industries hold the dominant procurement volume, while Government Agencies are expanding specifications fastest through regulatory scope expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Method 6200 governs soil screening protocols that structure detector procurement across US environmental remediation contracts. Bruker Corporation leverages its German-installed base to sustain aftermarket service revenue in automotive labs. East Asian manufacturing corridors concentrate demand for inline RoHS verification.
United States
Environmental remediation contractors drive detector demand through EPA-aligned procurement mandates. FCC electromagnetic compliance requirements fragment addressable supply across certification tiers. Midwest industrial clusters around Detroit and Chicago expand scrap metal sorting investments following domestic enforcement intensification.
Germany
Automotive manufacturers deploy inline XRF verification for REACH Annex XVII heavy metal compliance. EU F-Gas Regulation phase-down schedules compel thermoelectric cooling redesigns for European-market variants. Ruhr Valley recycling facilities accelerate real-time alloy identification to optimize ferrous sorting margins.
China
Electronics assemblers face mandatory GB standards adherence for e-waste recycling verification. MIIT radio equipment regulations create divergent approval pathways from FCC and CE marking requirements. Guangdong and Jiangsu processing clusters concentrate compliance-driven demand for integrated production-line systems.
Japan
Metrology institutes anchor detector standardization protocols for regional calibration reference materials. METI industrial policy supports high-purity silicon crystal supply concentration among domestic component specialists. Tokyo and Osaka research networks drive method development for academic and government laboratory applications.
Australia
Mining geologists in Western Australia prioritize sub-2kg form factors for all-day blast-hole assay field carry. TGA-equivalent equipment safety frameworks structure procurement for mineral exploration workflows. Pilbara iron ore operations drive replacement cycles tied to exploration budget fluctuations.
Handheld XRF Analyzers Market Competitive Environment
Scientific instrumentation conglomerates and analytical technology specialists split the market across divergent capability vectors. Consolidation pressure concentrates around detector miniaturization investments and aftermarket service network scale. Two archetypes dominate: diversified life science platforms leveraging cross-divisional distribution, and focused spectroscopy houses competing on detector yield rates. Competitive moves center on strategic partnerships for silicon drift detector supply security and geographic expansion into China's GB standards compliance market.
Within the diversified platform tier, Thermo Fisher Scientific Inc. and Bruker Corporation exemplify archetypes anchoring North American and European procurement respectively. SciAps, Inc. occupies a position among detector miniaturization specialists competing for confined-space industrial deployments. Olympus Corporation and Hitachi High-Tech Analytical Science represent Japanese-origin houses with regional channel density in East Asian manufacturing corridors.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bruker Corporation |
| Olympus Corporation |
| Hitachi High-Tech Analytical Science |
| AMETEK Inc. |
| HORIBA Ltd. |
| Rigaku Corporation |
| Oxford Instruments plc |
| SciAps, Inc. |
| Others |
Value Chain & Pricing Dynamics
Japanese and German silicon drift detector specialists anchor upstream supply, concentrating margin capture among component manufacturers while analyzer assemblers face persistent input allocation constraints. Pricing power downstream reflects this crystal supply bottleneck, with detector yield rates determining tier positioning across hardware portfolios.
Pricing Analysis
Geographic price spreads separate North American EPA-certified configurations from Asian-market variants lacking Method 6200 alignment. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector resolution grade and calibration protocol bundling. Cost compression in mid-tier units is intensifying because smartphone-compatible peripherals eliminate dedicated display electronics. Scrap metal recyclers in US Midwest industrial corridors exhibit highest price sensitivity, while German automotive labs prioritize certification-grade precision over unit economics.
Supply Chain Analysis
Export-control regimes restricting high-purity silicon crystal technology limit detector manufacturing equipment flows to select Asian fabrication facilities. Component supply concentrates in Japan, Germany, and South Korea, drawing from high-purity silicon ingot and precision cryostat cooling module inputs. Single-source vulnerability persists around thermoelectric cooler assemblies qualified for EU F-Gas Regulation compliance. Distribution runs through OEM direct sales for mining and environmental remediation verticals, with channel partners serving fragmented scrap recycling and construction inspection segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks mining exploration budget cycles, with Western Australian iron ore investment waves and Chilean copper expansion programs driving replacement demand peaks.
For Market Incumbents: Harden silicon drift detector supply security through long-term offtake agreements with Japanese crystal growers, insulating against allocation shocks that threaten production continuity. Deepen aftermarket service network density across German REACH compliance corridors to capture recurring calibration revenue streams. Prioritize thermoelectric cooling qualification ahead of F-Gas Regulation phase-down deadlines to maintain European market access.
For New Entrants and Emerging Players: Pursue smartphone-compatible detector peripheral architectures that bypass standalone hardware development capital requirements. India's BIS precious metal hallmarking mandates present the most penetrable regulatory entry point, with jewelry retail assay verification extending beyond traditional laboratory infrastructure. Lead with subscription-calibration business models that transfer maintenance liability to OEM networks, matching scrap yard operator preferences emerging in US Midwest metal recycling clusters.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed spectroscopy houses that consolidated regional channel networks during prior mining downturns. Five-to-ten year viability hinges on RoHS enforcement scope expansion sustaining compliance-driven replacement cycles. Monitor China's GB electronic waste standards implementation velocity across Guangdong and Jiangsu processing clusters as the primary inflection signal for integrated production-line system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Drift Detector Supply Agreement | Long-term crystal offtake secures production continuity against Japanese supplier allocation constraints. |
| Thermoelectric Cooling Redesign | Eliminates F-Gas refrigerant dependency to maintain EU market access under phase-down schedules. |
| Smartphone Peripheral Launch | Bluetooth-enabled modules penetrate confined-space deployments previously inaccessible to standalone units. |
| Aftermarket Service Network Expansion | Subscription-calibration models capture recurring revenue from scrap yard operators prioritizing uptime guarantees. |
| China GB Standards Certification | Mandatory e-waste elemental analysis creates compliance-driven demand across electronics manufacturing clusters. |
Study Parameters
The analysis maps portable, smartphone-compatible, desktop, and integrated product configurations, each validated through primary interviews with mining geologists, scrap yard operations managers, environmental remediation contractors, and German automotive lab quality directors. Secondary sources include EPA Method 6200 documentation, EU REACH Annex XVII regulatory filings, China GB standards publications, and London Metal Exchange pricing volatility datasets. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Assumption sets held detector yield improvement trajectories and RoHS enforcement scope expansion constant while varying mining exploration budget cycles and scrap metal commodity price volatility across sensitivity scenarios. Segmentation dimensions modeled include product type, application vertical, detector technology architecture, and end-user procurement authority. CAGRs derive from fitted growth curves calibrated to historical replacement cycles and regulatory compliance deadline clustering.
Sensitivities concentrate around silicon drift detector supply disruptions, REACH scope expansion timelines, and China's GB standards enforcement intensity. Forecasts reflect documented assumptions regarding EPA procurement continuity and EU F-Gas Regulation phase-down adherence. Material shifts in export control regimes governing high-purity silicon crystal technology or abrupt RoHS directive amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Bolometer Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Analytical Ultracentrifuge Systems Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Global Laboratory Electronic Balance Market