
 Enterprise-Grade Saas Market | 2026-2036
Enterprise-Grade Saas Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise-Grade Saas Market Insights
North America is narrowing its infrastructure advantage as hyperscaler regions in India and Brazil add sovereign cloud capacity. Microsoft anchors its position through Azure's multi-tenant architecture and compliance certifications across 90 jurisdictions. Salesforce differentiates through its Einstein AI layer embedded across Sales Cloud and Service Cloud. Oracle sustains database-to-application stickiness with autonomous cloud infrastructure.
Enterprise-grade SaaS denotes multi-tenant software delivered via subscription, engineered with 99.99% uptime SLAs, SOC 2 Type II certification, and API-first architecture for enterprise system interoperability. The model replaces perpetual licensing with consumption-based pricing, enabling IT departments to shift capital expenditure to operational expenditure. Hybrid cloud deployment captures the fastest expansion as regulated industries demand data residency without sacrificing elasticity. CRM solution types lead revenue contribution due to customer data monetization priorities. Healthcare and finance verticals concentrate margin pools because sector-specific compliance modules command pricing premiums over horizontal alternatives.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively reshape vendor qualification criteria, forcing providers to document algorithmic transparency and incident response protocols before contract execution. India's Digital Personal Data Protection Act and Brazil's LGPD add parallel compliance layers for multinational deployments. Stakeholders must evaluate whether vendor roadmaps prioritize federated identity architectures that satisfy fragmented sovereignty requirements without fragmenting user experience.
Market Dynamics
Data sovereignty mandates are fragmenting procurement criteria across multinational enterprises, forcing vendors to architect federated identity systems that satisfy jurisdictional residency requirements without degrading cross-border operational continuity.
Growth Catalysts
- EU AI Act compliance deadlines:European banking regulators now require algorithmic transparency documentation before contract execution, accelerating replacement of legacy on-premise systems with certified cloud-native ERP suites.
- API-first interoperability mandates:Healthcare networks in Germany demand SOC 2 Type II certified platforms that integrate patient data across hospital systems without compromising HIPAA-equivalent protections.
- Hybrid elasticity requirements:Mittelstand manufacturers prioritize consumption-based pricing models that preserve capital expenditure flexibility while meeting ISO 27001 data residency protocols.
Market Restraints
- Multi-jurisdiction certification costs:Simultaneous GDPR, LGPD, and Digital Personal Data Protection Act compliance creates prohibitive audit overhead for mid-market SaaS providers lacking dedicated legal-ops infrastructure.
- Hyperscaler concentration risk:Three cloud infrastructure providers control sovereign capacity expansion in Brazil and India, creating single-point-of-failure exposure for regulated financial services deployments.
- Legacy system entrenchment:Perpetual license ERP installations in Japanese automotive supply chains resist API-based integration due to proprietary data formats predating REST architecture standards.
Strategic Opportunities
- Underpenetrated sovereign cloud zones:Saudi Arabia's SFDA and UAE's MOHAP are establishing healthcare data localization frameworks that lack compliant multi-tenant vendors, creating first-mover positioning for certified entrants.
- Convergence of edge computing and zero-trust architecture:Manufacturing facilities in Bavaria require real-time ERP processing with sub-20ms latency, driving demand for distributed tenant nodes that maintain centralized compliance dashboards.
- Outcome-based pricing innovation:Insurance carriers in Switzerland now contract CRM platforms against measurable customer retention metrics rather than seat-based subscriptions, opening margin expansion through performance-linked fee structures.
Industry Challenges
- Cloud-native talent scarcity:Kubernetes security engineering and federated identity architecture expertise concentrates in Silicon Valley and Bangalore, creating recruitment bottlenecks for European SaaS vendors scaling sovereign cloud operations.
- Cross-border data transfer friction:Schrems II litigation uncertainty complicates EU-US data flows, forcing enterprises to maintain redundant infrastructure stacks that inflate operational complexity without proportional capability gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise-Grade Saas Market |
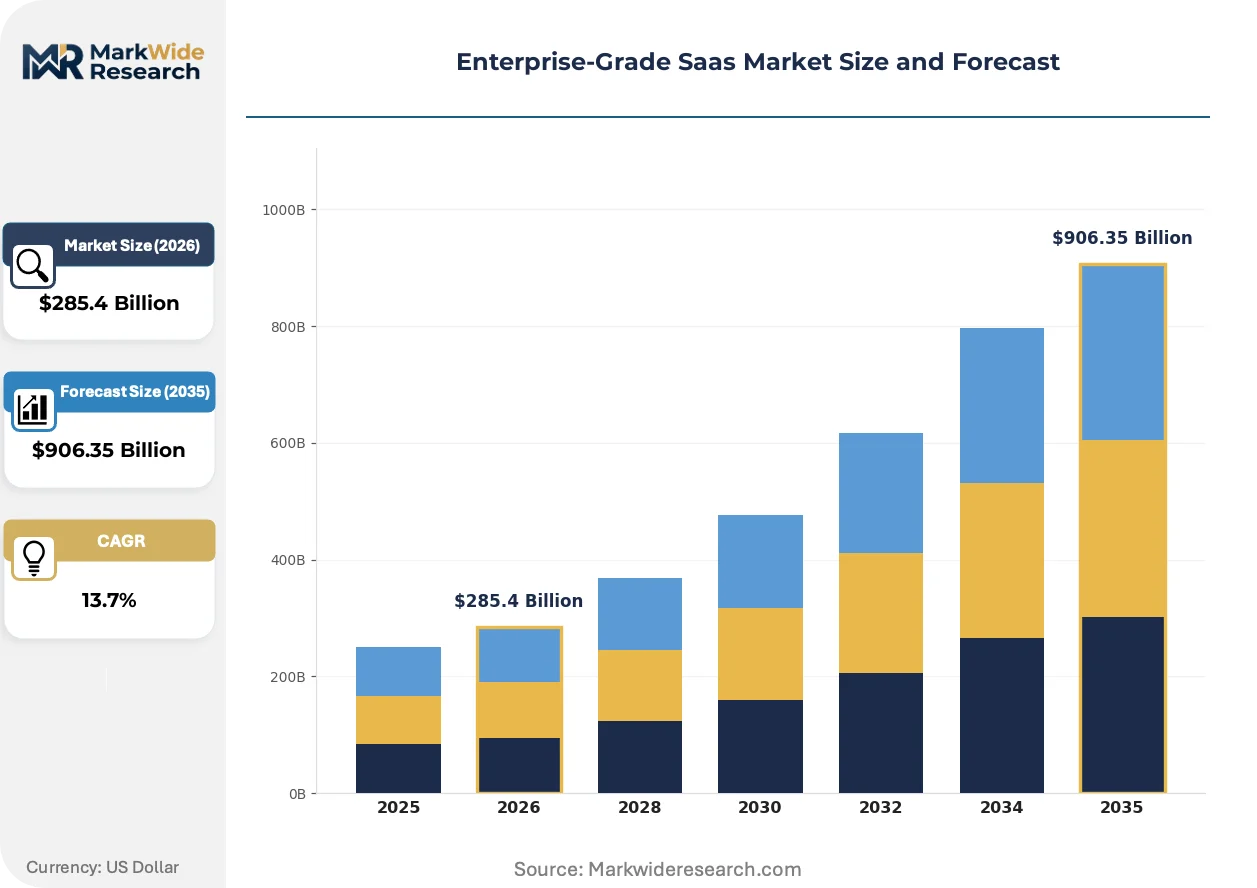
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $906.35 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Solution Type: CRM, ERP, HRM, Project Management End User: Small Businesses, Enterprises, Startups, Nonprofits Industry Vertical: Healthcare, Retail, Finance, Education |
| Companies Covered | Salesforce, Microsoft, Oracle, ServiceNow, IBM, Google Cloud, Shopify, Adobe, Okta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise-Grade Saas Market Trends and Innovations
Containerized microservices architectures are displacing monolithic application stacks, enabling granular compliance module deployment that satisfies sector-specific regulations without full-platform recertification cycles.
Serverless computing infrastructure is virtualizing the traditional data center boundary for financial services workloads. Tier-1 banks in London and Singapore now deploy customer-facing applications across ephemeral compute nodes that spin up within sovereign jurisdictions and terminate post-transaction. This architecture compresses permanent infrastructure footprint while maintaining audit trails required by SEC cybersecurity disclosure rules.
The EU AI Act's risk-classification framework is mandating algorithmic impact assessments before enterprise software procurement. Healthcare providers in France must document training data provenance and bias testing protocols for any AI-embedded CRM functionality. German automotive suppliers are responding by demanding vendor roadmaps that segregate high-risk automated decision-making from standard workflow automation.
Subscription fatigue among procurement departments is fragmenting buying authority away from centralized IT. Line-of-business executives in Australian mining firms now directly contract specialized compliance modules rather than purchasing full ERP suites. This decentralization compresses vendor sales cycles but increases integration complexity as shadow IT proliferates across business units without enterprise architecture oversight.
Enterprise-Grade Saas Market Segmentation
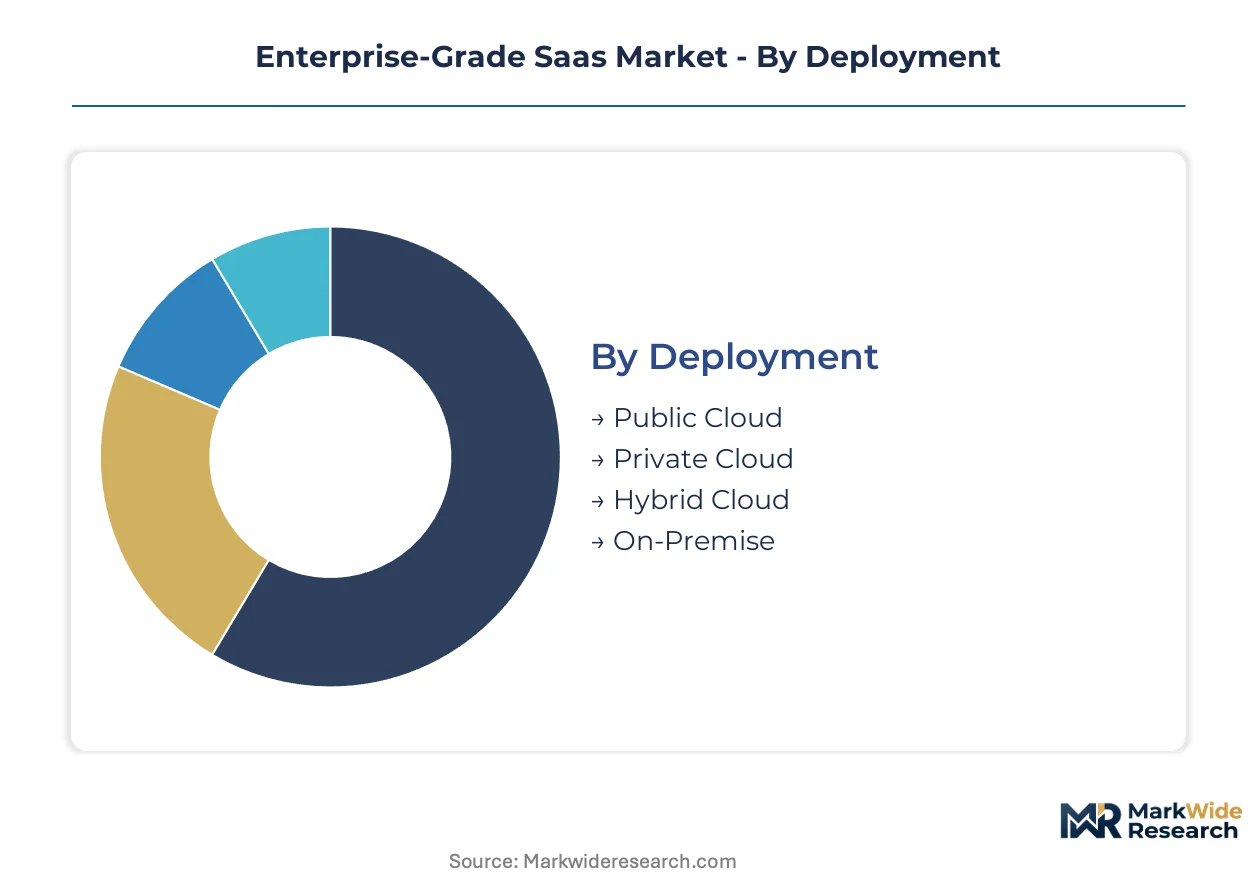
Enterprise-grade SaaS procurement patterns diverge sharply across deployment architectures and compliance requirements. Segmentation reveals how data sovereignty mandates reshape vendor selection criteria by vertical and organization scale.
Deployment:
After-sales engineering intensity peaks with hybrid configurations requiring ongoing residency compliance verification and cross-border orchestration support.
- Public Cloud:Multi-tenant infrastructure delivers elastic compute without dedicated hardware provisioning. German automotive suppliers leverage public instances for non-sensitive R&D workloads while maintaining ISO 27001 certification through vendor-managed controls.
- Private Cloud:Single-tenant environments provide isolated infrastructure stacks for regulated workloads. Swiss private banks mandate private deployments for core banking platforms to satisfy FINMA audit trail requirements without shared resource exposure.
- Hybrid Cloud:Split architecture preserves sensitive data on-premise while bursting transactional workloads to sovereign cloud zones. French healthcare networks deploy hybrid stacks to keep patient records local while utilizing public AI inference for diagnostic imaging.
- On-Premise:Legacy perpetual-license installations persist in Japanese automotive supply chains with proprietary data formats resisting API migration.
By volume, public cloud leads. By growth pace, hybrid cloud is ahead.
Solution Type:
Cost tier stratification separates compliance-heavy ERP suites from lightweight project management tools with minimal certification overhead.
- CRM:Customer data platforms embed AI-driven personalization engines with algorithmic transparency documentation. Australian mining firms contract specialized compliance modules directly rather than purchasing full suites.
- ERP:Financial and operational core systems require the most extensive jurisdictional certification. Mittelstand manufacturers in Bavaria replace legacy SAP installations with cloud-native ERP supporting real-time edge processing.
- HRM:Workforce management platforms integrate payroll, benefits, and talent analytics across distributed teams.
- Project Management:Collaboration tools with lighter compliance requirements serve line-of-business buyers outside centralized IT procurement.
CRM captures the largest revenue pool. ERP is climbing the fastest as replacement cycles accelerate.
End User:
Customer type determines contract structure complexity, with enterprise procurement teams negotiating federated identity architectures absent from startup buying patterns.
- Enterprises:Multi-divisional organizations demand API-first interoperability and SOC 2 Type II certification across 90+ jurisdictions. Tier-1 banks in London deploy serverless customer-facing applications across ephemeral compute nodes.
- Small Businesses:Mid-market buyers prioritize consumption-based pricing without dedicated legal-ops infrastructure for multi-jurisdiction compliance.
- Startups:Venture-backed firms favor seat-based subscriptions with rapid scaling clauses.
- Nonprofits:Grant-dependent organizations seek discounted licensing with simplified audit requirements.
Enterprises dominate contract value. Startups are gaining share fastest through decentralized procurement authority.
Industry Vertical:
Margin concentration aligns with sector-specific compliance module premiums over horizontal alternatives.
- Finance:Banking and insurance carriers require algorithmic impact assessments under SEC cybersecurity disclosure rules. Swiss insurers now contract against measurable retention metrics rather than seat-based pricing.
- Healthcare:Patient data platforms demand HIPAA-equivalent protections and training data provenance documentation. Saudi Arabia's SFDA and UAE's MOHAP establish localization frameworks lacking compliant multi-tenant vendors.
- Retail:Customer data monetization drives personalization platform investment with lighter regulatory burden.
- Education:Institutional procurement prioritizes cost efficiency over specialized compliance features.
Finance leads in pricing power. Healthcare shows the steepest expansion trajectory as sovereign cloud zones mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC cybersecurity disclosure rules anchor the United States as the primary demand geography, with algorithmic transparency mandates cascading through European banking regulators and fragmenting procurement criteria across multinational deployments.
United States
Financial services firms in New York and Chicago accelerate cloud-native ERP adoption to satisfy SEC incident response documentation requirements. Tier-1 banks deploy serverless customer-facing applications across ephemeral compute nodes that terminate post-transaction. The Silicon Valley-to-Seattle corridor concentrates Kubernetes security engineering expertise, creating recruitment competition for European vendors scaling sovereign operations.
Germany
Mittelstand manufacturers in Bavaria replace legacy SAP installations with hybrid ERP supporting real-time edge processing under ISO 27001 protocols. The EU AI Act forces algorithmic impact assessments before procurement, with KBA automotive suppliers demanding vendor roadmaps that segregate high-risk automated decision-making. Frankfurt's banking cluster drives federated identity architecture investment for cross-border operational continuity.
United Kingdom
London's insurance carriers pioneer outcome-based CRM contracts tied to measurable customer retention metrics rather than seat-based subscriptions. The Financial Conduct Authority's operational resilience requirements push Lloyd's syndicates toward SOC 2 Type II certified platforms with API-first interoperability. Edinburgh and Manchester health networks demand HIPAA-equivalent protections for patient data platforms.
India
Bangalore and Hyderabad host hyperscaler regions adding sovereign cloud capacity that narrows North America's infrastructure advantage. The Digital Personal Data Protection Act creates parallel compliance layers for multinational deployments, with RBI-regulated banks requiring data residency without sacrificing elasticity. Mumbai's financial services procurement teams prioritize consumption-based pricing models.
Brazil
São Paulo's banking sector faces LGPD mandates alongside GDPR extraterritorial application, forcing redundant infrastructure stacks. Hyperscaler concentration risk concentrates sovereign capacity expansion among three cloud providers, creating single-point-of-failure exposure for regulated deployments. ANVISA-regulated pharmaceutical distributors demand sector-specific compliance modules commanding pricing premiums.
Enterprise-Grade Saas Market Competitive Landscape
Capability concentration sits with specialized compliance architects; scale advantage sits with hyperscaler-backed platform vendors. The market structures around three tiers: database-to-application incumbents with perpetual license conversion pipelines, AI-embedded CRM specialists with algorithmic transparency documentation, and infrastructure-agnostic challengers federating identity across sovereign zones. Consolidation pressure favors M&A targeting mid-market vendors with multi-jurisdiction certification infrastructure, while organic expansion concentrates on edge computing nodes for sub-20ms latency manufacturing workloads.
Within the enterprise platform tier, Salesforce, Microsoft, and Oracle exemplify divergent competitive positioning. Salesforce occupies the AI-embedded CRM specialist archetype with Einstein layer integration across cloud suites. Microsoft anchors the hyperscaler-backed vector through Azure's multi-tenant architecture spanning 90 jurisdictions. Oracle represents the database-to-application incumbent with autonomous infrastructure sustaining legacy conversion momentum. Each archetype faces distinct pressure: Salesforce from algorithmic audit requirements, Microsoft from federated identity fragmentation, Oracle from API-first interoperability mandates.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft |
| Oracle |
| ServiceNow |
| IBM |
| Google Cloud |
| Shopify |
| Adobe |
| Okta |
| Others |
Pricing and Supply Chain Analysis
Bangalore's hyperscaler region expansion narrows North America's infrastructure advantage while compressing pricing premiums for multi-tenant SaaS deployments across Indian financial services procurement teams. Mumbai's banking sector demands consumption-based elasticity without sacrificing RBI-mandated data residency, forcing vendors to absorb compliance certification costs into base subscription tiers.
Pricing Analysis
Price spreads between Frankfurt and São Paulo exceed those between London and Singapore due to LGPD and GDPR extraterritorial overlap forcing redundant infrastructure stacks. Three-tier pricing structure across premium, standard, and economy levels segments by SOC 2 Type II certification scope and API interoperability depth. Cost compression in mid-market tiers is intensifying because Brazilian and Indian mid-market buyers lack dedicated legal-ops infrastructure for multi-jurisdiction audit overhead. Startups exhibit highest price sensitivity; Tier-1 banks in London and New York demonstrate lowest sensitivity due to outcome-based contracting tied to retention metrics.
Supply Chain Analysis
Export-control restrictions on advanced GPU clusters and encryption technologies limit sovereign cloud capacity flows into Saudi Arabia and UAE healthcare zones. Supply concentrates in the United States, Ireland, and Singapore for hyperscaler backbone infrastructure, with Germany and India adding federated identity node capacity. Raw material dependencies span specialized semiconductors for AI inference, undersea fiber capacity for cross-border latency, and certified data center real estate in financial districts. Single-source vulnerability concentrates in three cloud providers controlling Brazil and India sovereign expansion. Distribution runs through direct enterprise sales teams with embedded compliance architects rather than channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement authority creates niche positioning opportunities as line-of-business executives in Australian mining and German automotive supply chains bypass centralized IT to contract specialized compliance modules directly.
For Market Incumbents: Insulate against API-first interoperability mandates by embedding federated identity architectures that satisfy EU AI Act algorithmic transparency requirements without fragmenting user experience. Acquire mid-market vendors with pre-built multi-jurisdiction certification infrastructure to compress compliance timelines for Mittelstand manufacturers. Prioritize vertical integration into edge computing nodes for Bavarian manufacturing facilities demanding sub-20ms latency ERP processing. For New Entrants and Emerging Players: Saudi Arabia's SFDA and UAE's MOHAP healthcare data localization frameworks lack compliant multi-tenant vendors, creating first-mover positioning for certified entrants with HIPAA-equivalent module development. Target Swiss insurance carriers pioneering outcome-based CRM contracts against measurable retention metrics rather than seat-based subscriptions. Lead with serverless architecture go-to-market messaging that compresses permanent infrastructure footprint while maintaining SEC cybersecurity disclosure audit trails. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized compliance architects with pre-certified multi-jurisdiction infrastructure over horizontal platform vendors facing algorithmic audit fragmentation. Long-term viability rests on vendors demonstrating Kubernetes security engineering depth and federated identity roadmap execution across fragmented sovereignty requirements. Watch for Schrems II litigation resolution as inflection indicator for EU-US data flow architecture investments and redundant stack consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding Einstein AI layers across Sales Cloud and Service Cloud satisfies EU AI Act algorithmic documentation mandates for French healthcare providers. |
| Geographic Expansion | Establishing sovereign cloud nodes in Bangalore and Hyderabad captures RBI-regulated banking demand for data residency without elasticity sacrifice. |
| Acquisition of Specialist Firm | Buying mid-market vendors with LGPD and Digital Personal Data Protection Act certification infrastructure compresses compliance timelines for Brazilian deployments. |
| Strategic Partnership | Aligning with hyperscalers on federated identity architectures preserves cross-border operational continuity for Frankfurt banking clusters. |
| Product Launch | Introducing containerized microservices compliance modules enables granular deployment that satisfies sector-specific regulations without full-platform recertification. |
Research Methodology
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie enterprise mobility data, and EU regulatory filing databases anchors the qualitative findings. Bottom-up deployment modeling across public, private, and hybrid cloud configurations triangulates against top-down TAM sizing by vertical and organization scale.
Calibration against historical adoption curves in financial services and healthcare verticals shapes the projection framework across deployment architecture, solution type, end user scale, and industry vertical segmentation dimensions. CAGRs derive from elasticity-adjusted replacement cycle analysis incorporating EU AI Act compliance deadline impacts and Mittelstand manufacturer legacy SAP conversion momentum. Forecast inputs include RBI sovereign cloud capacity announcements and ANVISA pharmaceutical distributor module certification timelines.
Practitioners should monitor Schrems II litigation progression, hyperscaler region expansion announcements in Saudi Arabia and UAE, and EU AI Act risk-classification enforcement patterns for early signals of forecast deviation. Material shifts in cross-border data transfer legal frameworks or sovereign cloud capacity allocation policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Journal App Market
Software & Services
Software Testing Company Market
Software & Services
Russian IT Software and Services Market
Software & Services
Global Script Writing Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Global Recipe Apps Market
Software & Services
Board Portal Market
Software & Services
Global Data Entry Software Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Self-Storage Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Global OKR Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Construction and Design Software Market
Software & Services
Customs Declaration Software Market